
 Joint Reconstruction Devices Market | 2026-2036
Joint Reconstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Joint Reconstruction Devices Market Intelligence
Demand from Ambulatory Surgery Centers (ASCs) is bifurcating the market, shifting procedural volume away from traditional large-hospital settings. Stryker Corporation leverages its Mako robotic-arm assisted surgery platform to capture share within these high-volume ASCs. Zimmer Biomet sustains its market position through a broad portfolio of knee and hip implants catering to diverse patient anatomies. Smith+Nephew differentiates with its focus on sports medicine and less invasive joint repair technologies.
Joint reconstruction devices are medical implants designed to replace or resurface articulating joints damaged by disease or trauma. These devices are often fabricated from biocompatible materials like cobalt-chromium or titanium alloys, featuring porous coatings to encourage bone in-growth. Knee implants represent the largest product segment due to the high prevalence of osteoarthritis, while hip implants follow closely. Ceramic and advanced polyethylene materials are gaining traction for their superior wear resistance and longevity, especially in younger, more active patients.
Market access is governed by stringent regulatory approvals from bodies like the US FDA, the EU's EMA under the MDR, and China's NMPA. These agencies mandate extensive clinical data on device safety, biocompatibility, and long-term performance, creating high barriers to entry. Future competitive advantage will depend on navigating value-based healthcare models and demonstrating clear economic benefits alongside clinical efficacy.
Market Dynamics
The central structural force shaping the market is the procedural shift toward high-volume Ambulatory Surgery Centers. This migration away from inpatient hospital settings prioritizes devices and systems that support minimally invasive techniques, faster recovery times, and operational efficiency.
Growth Catalysts
- Robotic-Assisted Surgery:The integration of robotic platforms enhances surgical precision, reduces tissue damage, and improves implant alignment, leading to better long-term patient outcomes and wider surgeon adoption.
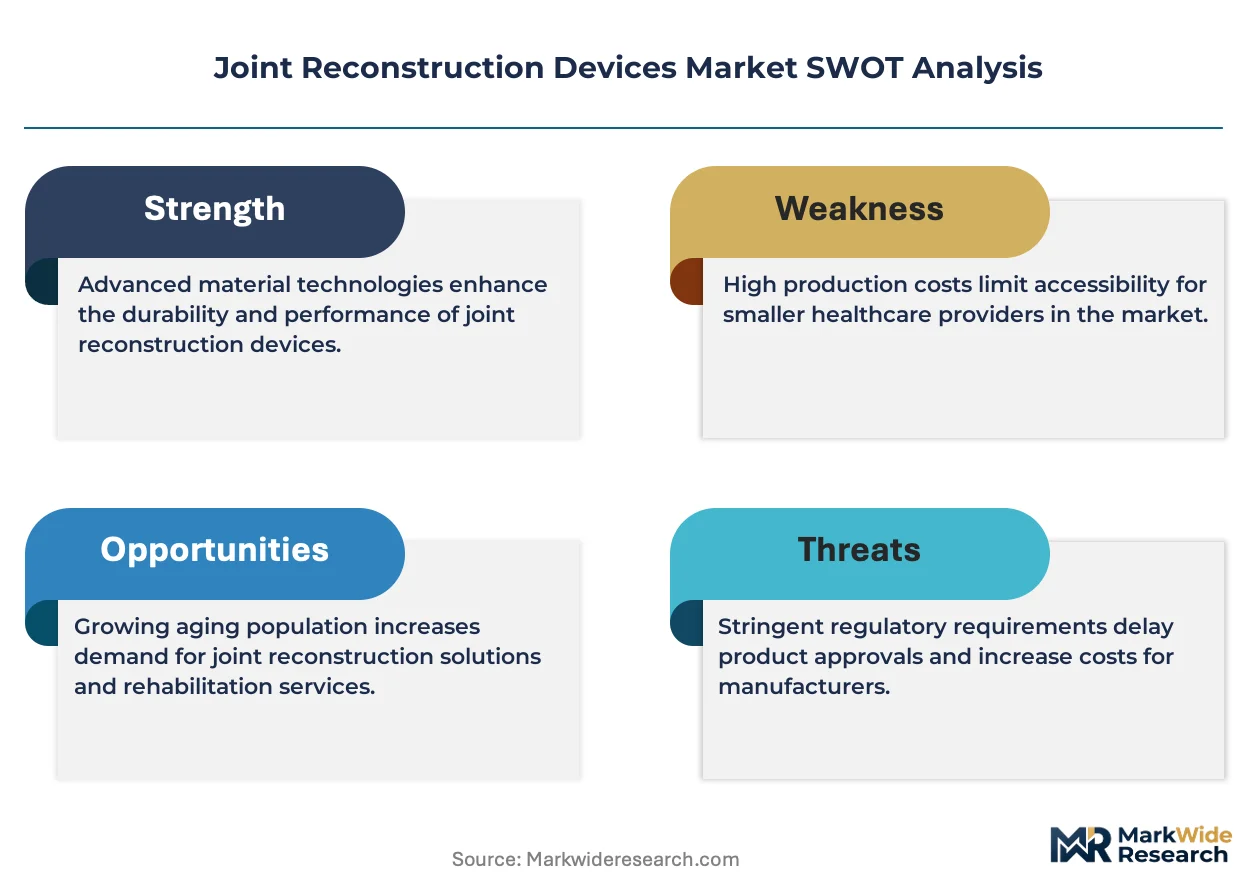
- Aging Demographics:Advanced economies, particularly Germany and Japan, have rapidly aging populations with a high prevalence of osteoarthritis, creating a consistent and expanding base of patients requiring joint replacement procedures.
- Value-Based Healthcare Models:Payment reforms that reward clinical efficacy and total cost-of-care efficiency incentivize the use of durable, technologically advanced implants that reduce the likelihood of costly revision surgeries.
Market Restraints
- Stringent Regulatory Hurdles:Extensive and costly clinical trials are mandated by bodies like the US FDA and the EU under its MDR, creating high barriers to entry and lengthening time-to-market for new devices.
- High Material Costs:The price volatility of medical-grade raw materials, such as cobalt-chromium and titanium alloys, directly impacts manufacturing costs and puts pressure on profit margins for device makers.
- Threat from Biologics:The advancement of regenerative medicine and non-surgical therapies, including stem cell treatments and viscosupplementation, presents a growing alternative for younger patients or those with early-stage joint degradation.
Strategic Opportunities
- Patient-Specific Implants:Leveraging 3D printing and advanced medical imaging allows for the creation of customized implants that match a patient's unique anatomy, offering superior fit and function over off-the-shelf devices.
- Expansion to Extremity Joints:A significant opportunity exists in developing and marketing devices for smaller, yet frequently afflicted, joints such as the ankle, shoulder, and wrist, which are currently underserved compared to hips and knees.
- Emerging Market Penetration:Increasing healthcare expenditure and infrastructure development in countries like Brazil and India create new growth frontiers for established device manufacturers as access to advanced surgical care expands.
Industry Challenges
- Surgical Skill Development:The adoption of complex robotic-assisted surgical systems requires substantial investment in surgeon training and certification, which can slow the diffusion of these technologies into mainstream clinical practice.
- Post-Market Surveillance Demands:Regulators are increasing requirements for long-term data collection on implant performance and patient outcomes, creating a significant data management and compliance burden for manufacturers.
- System Interoperability:Ensuring new surgical navigation and robotic platforms can seamlessly integrate with existing hospital information systems and operating room workflows remains a persistent technical and logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Joint Reconstruction Devices Market |
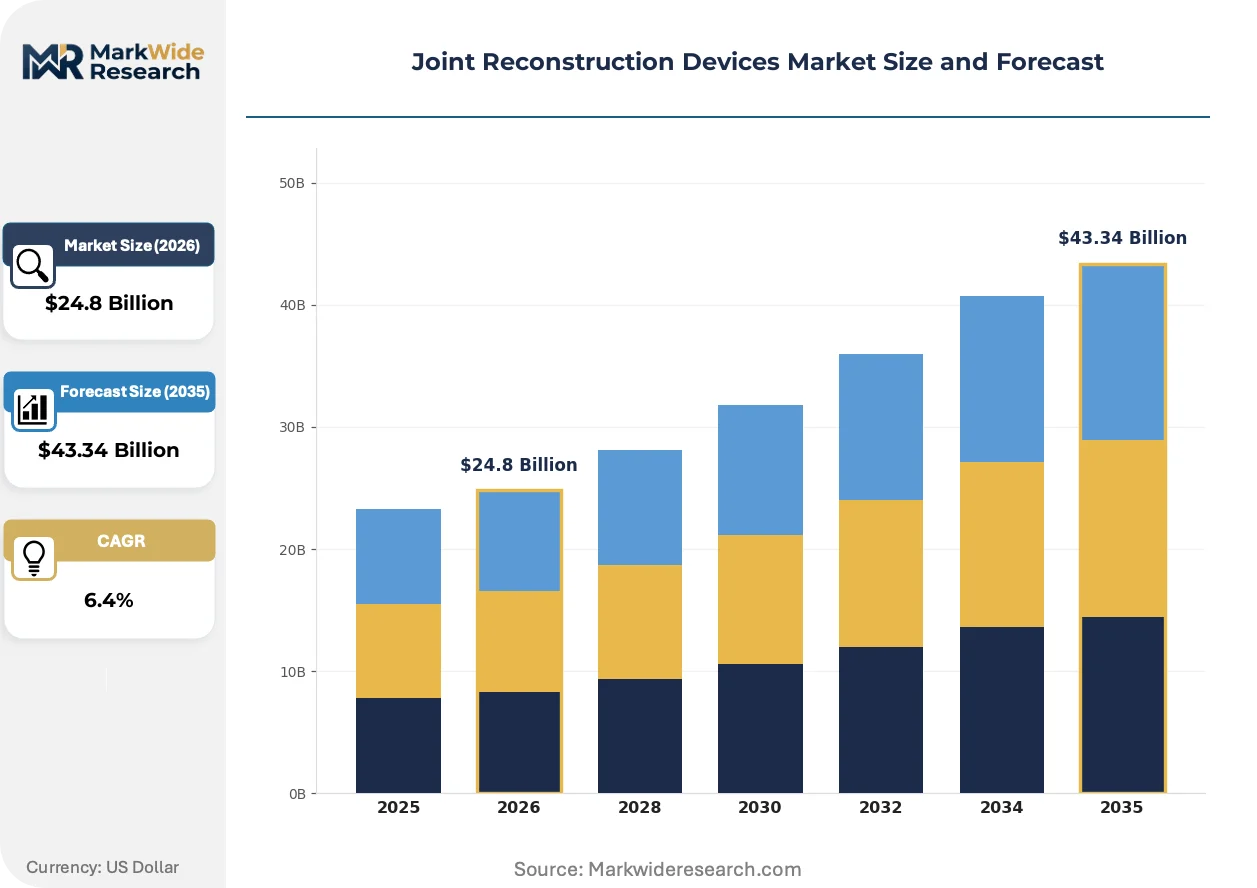
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
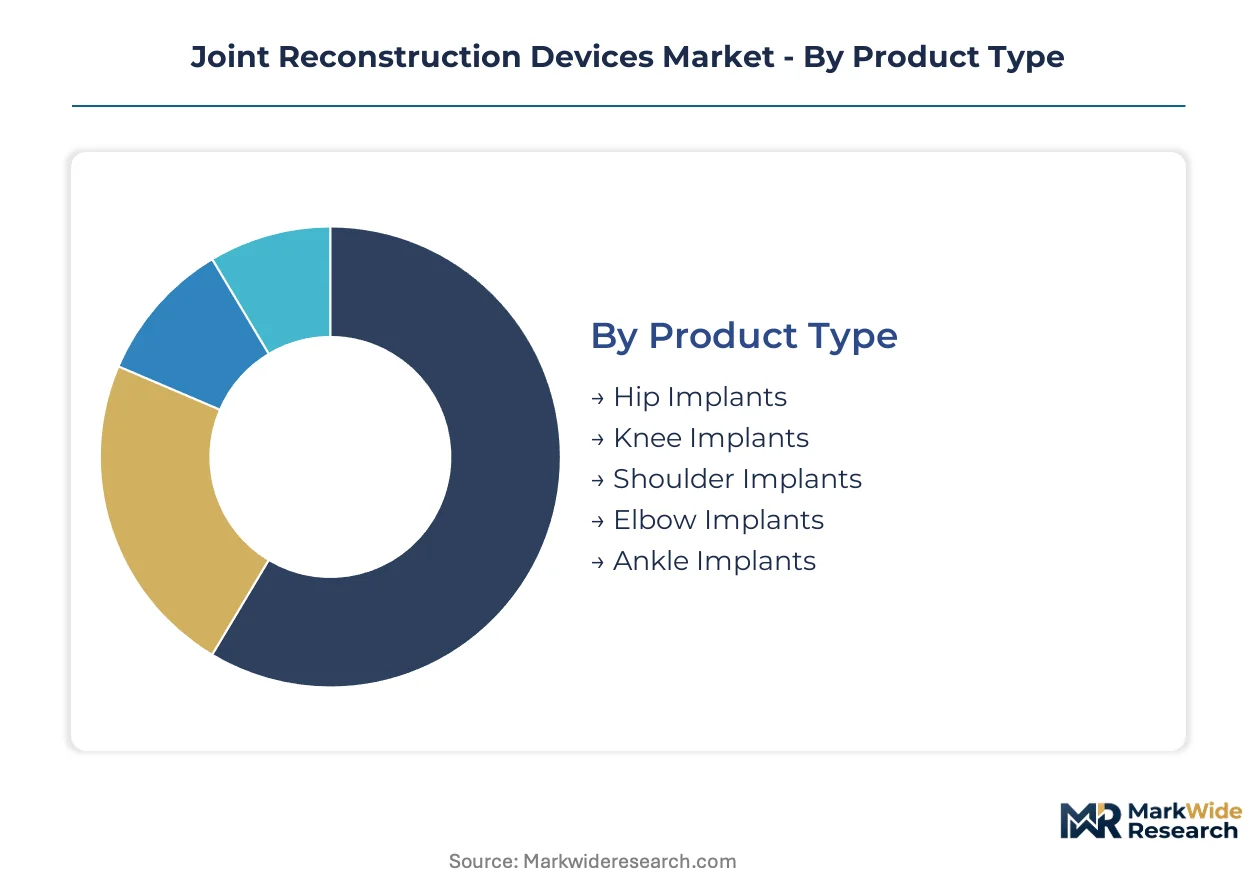
| Segmentation | Product Type: Hip Implants, Knee Implants, Shoulder Implants, Elbow Implants, Ankle Implants Material: Cobalt-Chromium, Titanium, Polyethylene, Ceramic, Stainless Steel Application: Osteoarthritis, Rheumatoid Arthritis, Post-Traumatic Arthritis, Avascular Necrosis, Juvenile Arthritis End User: Orthopedic Clinics, Ambulatory Surgery Centers, Rehabilitation Centers, Specialized Hospitals |
| Companies Covered | Zimmer Biomet, Stryker Corporation, DePuy Synthes, Smith+Nephew, Medtronic, Aesculap, CONMED Corporation, DJO, Arthrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Joint Reconstruction Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of advanced material science with data-driven personalization. This convergence aims to transform joint implants from passive mechanical devices into active components of a connected care ecosystem, improving both longevity and patient-specific outcomes.
Smart implants embedded with micro-sensors are a key technological evolution, designed to actively monitor factors like implant load, alignment, and patient activity post-surgery. Orthopedic centers and surgeons are adopting this technology for revision cases and high-performance athletes to gain objective performance data. This innovation is displacing traditional, subjective follow-up protocols that depend on patient reporting and infrequent radiographic imaging.
Regulatory frameworks are mandating greater device traceability, exemplified by the European Union's Medical Device Regulation (MDR). This rule requires a Unique Device Identification (UDI) on each implant, enabling tracking from manufacturing through to the patient. The primary impact is on manufacturers of high-volume knee and hip implants, who must overhaul their supply chain and data management systems to comply and retain access to the EU market.
A notable behavioral shift is occurring in how healthcare providers select devices, moving beyond unit price to a total cost of ownership model. This change disrupts the traditional sales process focused on surgeon preference, empowering hospital administrators who favor integrated device and technology bundles that promise lower revision rates. This trend is most visible in the United States and Germany, where bundled payment systems are increasingly common.
Joint Reconstruction Devices Market Segmentation
The Joint Reconstruction Devices Market is characterized by a diverse range of products, materials, applications, and end-users, each responding to specific clinical needs and market dynamics. Understanding these segments is crucial for manufacturers to tailor their product development and market penetration strategies effectively.
Product Type:
Regulatory bodies like the US FDA and EU's MDR impose distinct approval pathways for different joint reconstruction product types, reflecting varying risk profiles and performance requirements.
- Knee Implants:These devices replace damaged knee joints, often due to osteoarthritis, using components typically made from cobalt-chromium alloys and ultra-high molecular weight polyethylene. Demand concentrates in advanced economies like Germany and Japan, driven by aging populations and high osteoarthritis prevalence.
- Hip Implants:Designed to replace the hip joint, these implants consist of a femoral component, an acetabular cup, and a bearing surface, frequently employing titanium or ceramic materials. Demand is strong in the United States, where technological advancements in robotic-assisted surgery improve surgical precision and patient outcomes.
- Shoulder Implants:These devices address severe arthritis or fractures in the shoulder, offering both anatomical and reverse total shoulder arthroplasty options.
- Elbow Implants:Used for conditions like severe arthritis or complex fractures, elbow implants restore function and reduce pain in the elbow joint.
- Ankle Implants:Total ankle replacement devices are gaining traction as an alternative to fusion for end-stage ankle arthritis, preserving motion.
Knee implants handle the majority of throughput; ankle implants are the fastest mover on share.
Material:
The supply concentration for raw materials directly influences the cost and availability of various biocompatible options for joint reconstruction.
- Ceramic:These materials, such as alumina and zirconia, offer superior wear resistance and biocompatibility, making them ideal for younger, more active patients seeking long-term implant longevity. Demand is concentrated in regions prioritizing reduced revision rates, such as Western Europe.
- Titanium:Titanium alloys are valued for their excellent biocompatibility, strength-to-weight ratio, and ability to be porous-coated to promote bone in-growth, critical for stable fixation. Adoption is high in countries with advanced surgical techniques, including the United States.
- Cobalt-Chromium:Widely used for femoral components in knee and hip implants, this alloy provides high strength and wear resistance, though concerns about metal ion release persist.
- Polyethylene:Ultra-high molecular weight polyethylene (UHMWPE) serves as the bearing surface in many implants, offering low friction properties.
- Stainless Steel:Less common in primary load-bearing implants today, stainless steel offers good mechanical properties but inferior biocompatibility and corrosion resistance compared to other alloys.
Advanced materials like ceramics and specialized polyethylenes are gaining traction for their enhanced wear resistance and longevity.
Application:
Patient demographics and underlying disease progression define the demand patterns across various application segments for joint reconstruction devices.
- Osteoarthritis:This degenerative joint disease is the primary driver for joint replacement surgeries, particularly affecting knees and hips, due to cartilage breakdown. Demand is globally widespread, with high prevalence in aging populations across Europe and Asia.
- Post-Traumatic Arthritis:Arthritis developing after a joint injury, such as a fracture or ligament tear, often necessitates joint reconstruction to restore function and alleviate chronic pain. This application sees significant procedural volume in countries with high rates of sports injuries and accidents, like the United States.
- Rheumatoid Arthritis:This autoimmune disease causes chronic inflammation and destruction of joint cartilage, leading to severe pain and deformity requiring surgical intervention.
- Avascular Necrosis:This condition results from the loss of blood supply to bone, leading to bone death and joint collapse, frequently requiring hip replacement.
- Juvenile Arthritis:While less common, severe cases of arthritis in children can necessitate joint reconstruction to prevent long-term disability.
Osteoarthritis remains the predominant application, driving the largest volume of joint replacement procedures globally.
End User:
Procedural volume and facility capabilities drive the adoption of joint reconstruction devices across different end-user settings.
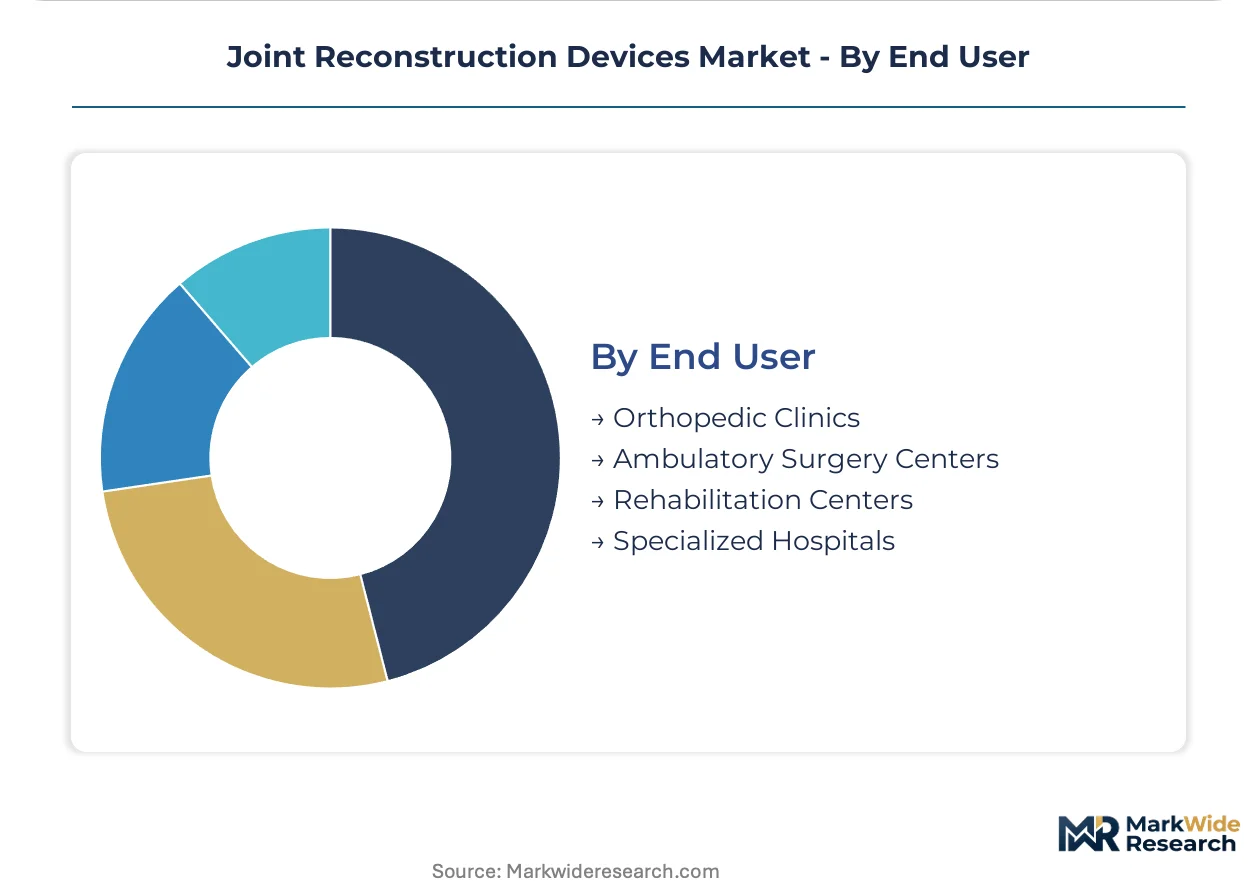
- Ambulatory Surgery Centers:These facilities are increasingly adopting joint reconstruction procedures, favoring minimally invasive techniques and devices that support faster patient recovery and operational efficiency. The United States is experiencing a significant shift of procedures to ASCs.
- Specialized Hospitals:These institutions handle complex cases, revision surgeries, and often serve as teaching hospitals, requiring a broad range of advanced joint reconstruction devices and technologies. Demand for high-end systems is consistent in major medical centers worldwide.
- Orthopedic Clinics:While primarily focused on diagnosis and non-surgical management, many clinics are affiliated with surgical centers and influence device selection.
- Rehabilitation Centers:These centers focus on post-operative recovery and physical therapy, requiring devices that support patient mobility and functional restoration.
The procedural shift toward Ambulatory Surgery Centers reflects a broader trend of optimizing surgical efficiency and patient recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers in the United States export advanced joint reconstruction devices to markets like Germany, driven by demand for innovative surgical solutions. This global trade flow highlights the interconnectedness of advanced healthcare systems. The market's regional dynamics are shaped by aging demographics and evolving regulatory landscapes.
United States
The United States leads in demand for joint reconstruction devices, fueled by high osteoarthritis prevalence and the adoption of robotic-assisted surgery. The US FDA mandates extensive clinical trials, ensuring device safety and performance for market access. Major medical device clusters in places like Boston and California drive innovation in implant design and surgical techniques.
Germany
Germany's aging population creates a consistent base of patients requiring knee and hip replacements. The EU MDR imposes stringent post-market surveillance requirements, influencing device development and market entry. Medical technology hubs in Tuttlingen and Bavaria foster research and manufacturing excellence in orthopedic implants.
Japan
Japan's advanced healthcare infrastructure supports a high volume of joint replacement procedures, particularly for its rapidly aging demographic. The PMDA oversees rigorous approval processes for new medical devices, emphasizing long-term efficacy. Biomedical clusters in Tokyo and Osaka contribute to the development of specialized materials and implant designs.
India
India exhibits significant growth in joint reconstruction, propelled by increasing healthcare expenditure and rising awareness of treatment options. The CDSCO regulates medical device registration, ensuring quality and safety standards for imported and domestic products. Cities like Bengaluru and Mumbai are emerging as centers for orthopedic care and device distribution.
Brazil
Brazil presents a dynamic market for joint reconstruction, with expanding access to advanced surgical care across its regions. ANVISA governs medical device market authorization, requiring comprehensive documentation for product entry. Major medical centers in São Paulo and Rio de Janeiro serve as key hubs for advanced orthopedic procedures and training.
Joint Reconstruction Devices Market Key Industry Players
Listed leaders compete with private specialists across technology integration and market reach. The market structure exhibits consolidation among a few global players alongside a fragmented base of niche innovators. Strategic archetypes include diversified medical technology conglomerates and focused orthopedic specialists. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand market access.
On the premium-tier vector, Zimmer Biomet and Stryker Corporation exemplify companies with broad portfolios and established global distribution networks. Smith+Nephew occupies a position as a specialist in sports medicine and less invasive joint repair technologies. These entities anchor distinct segments, from high-volume knee and hip implants to advanced extremity solutions. Their presence highlights the industry's stratification by product focus and technological sophistication.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| Smith+Nephew |
| Medtronic |
| Aesculap |
| CONMED Corporation |
| DJO |
| Arthrex |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) gates both supply qualification and price differentiation simultaneously, demanding robust clinical data for market access. This regulatory environment adds complexity to pricing models and influences material sourcing decisions across the industry.
Pricing Analysis
The pricing gap between next-generation robotic-assisted systems and established implant technologies reflects differing value propositions. Value-based healthcare models increasingly drive the dominant pricing structure, favoring bundled payments that reward clinical efficacy and reduced revision rates. Price differentiation stems from superior wear resistance of ceramic materials and the enhanced precision offered by robotic integration. Cost compression in the standard-tier implant market intensifies due to Ambulatory Surgery Centers' demand for efficiency, making these facilities the most price-sensitive buyers.
Supply Chain Analysis
Just-in-time inventory strategies often characterize high-volume, standardized implant components, while specialized patient-specific devices may necessitate strategic stockpiling of raw materials. Geographic supply concentrates for critical raw materials, with titanium alloys often sourced from countries like China and Russia, and advanced ceramic components from Germany and Japan. Commodity price volatility for medical-grade metals like cobalt-chromium presents a structural supply chain risk for device manufacturers. Distribution runs through a hybrid model combining direct sales forces to major hospital systems and regional distributor networks serving smaller clinics and ASCs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, primarily driven by the integration of robotic-assisted surgical systems. These technological advancements are fundamentally reshaping procedural approaches and patient outcomes.
For Market Incumbents: Secure market share by accelerating investment in advanced robotic platforms and smart implant technologies. Deepen integration with Ambulatory Surgery Centers to counter margin pressure from value-based care models and emerging biologic therapies. Invest in comprehensive surgeon training programs to ensure broad adoption of new surgical systems. Acquire niche innovators specializing in patient-specific implants or extremity joint solutions to expand portfolio reach.
For New Entrants and Emerging Players: Differentiate on advanced material science, focusing on superior wear resistance and biocompatibility for younger, more active patient populations. Target underserved extremity joints, such as the ankle and shoulder, which present significant white-space opportunities compared to hips and knees. Penetrate emerging markets like India and Brazil with cost-effective, high-quality implant solutions. Establish strong partnerships with specialized orthopedic clinics to build early market traction.
For Investors and Strategic Acquirers: The European Union's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust regulatory compliance and extensive clinical data. Focus on long-term viability by targeting firms innovating in smart implants or regenerative medicine, aligning with future value-based care trends. Acquisition target archetypes include specialized technology providers and regional players with strong ASC networks. A key signal to watch is the adoption rate of patient-specific implants in major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Robotic Platform Integration | Improves surgical precision and patient outcomes, driving wider adoption in ASCs. |
| Invest in Patient-Specific Implant R&D | Offers superior fit and longevity, catering to unique anatomical needs and reducing revision rates. |
| Expand Extremity Joint Portfolio | Addresses underserved market segments beyond hips and knees, capturing new growth opportunities. |
| Strengthen ASC Partnerships | Secures procedural volume and aligns with the shift towards efficient, outpatient surgical settings. |
| Develop Smart Implant Technology | Enables objective post-operative monitoring, enhancing data-driven patient care and long-term performance. |
Research Approach
Desk research of company annual reports, scientific journals, and regulatory filings preceded structured interviews with orthopedic surgeons, hospital procurement managers, device engineers, and regulatory affairs specialists. This primary data was validated against secondary sources including US FDA databases, EU MDR compliance documents, and clinical trial registries. The methodology employed both bottom-up and top-down triangulation to ensure comprehensive market sizing.
Variance decomposition underpinned the quantitative analysis, modeling market dynamics across the analysis window. Segmentation dimensions included product type, material, application, end-user, and regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical trends, competitive landscape analysis, and projected technological advancements. Key industry-specific forecast inputs included osteoarthritis prevalence rates and aging population demographics.
Decision-makers should treat outputs as directional under assumptions of stable regulatory frameworks, consistent healthcare funding, and predictable raw material supply; material deviation would warrant model refresh. Unforeseen shifts in reimbursement policies or rapid advancements in biologics represent key risk factors. Revision becomes warranted when new clinical evidence fundamentally alters treatment paradigms or major regulatory changes impact market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fracture Fixation Products Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Global Pessary Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Global Pupillometer Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market