
 North America Industrial Insulation Market | 2026-2036
North America Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Insulation Market Intelligence
Buyer concentration among downstream energy processors is rebalancing as midstream operators fragment procurement across specialized contractors. Owens Corning leverages its fiberglass manufacturing scale to dominate piping insulation contracts along the Gulf Coast. Johns Manville anchors its position through mineral wool specialization for power generation boiler applications. Rockwool International A/S competes on high-temperature stone wool formulations that sustain performance above 1,000 degrees Celsius in refinery settings.
North America industrial insulation encompasses thermally resistant materials engineered to reduce heat transfer, control surface temperatures, and conserve energy across process equipment, with typical fiberglass batts achieving thermal conductivity values near 0.04 W/m·K and mineral wool systems rated for continuous operation at 650 degrees Celsius. Mineral wool leads installation value in boiler and high-temperature piping applications where fire resistance and dimensional stability command premium positioning. Fiberglass occupies the largest volume share across HVAC and ductwork segments where lightweight handling and lower installed cost drive specification. Foam insulation represents the fastest-growing product category in pharmaceutical cleanroom and cold-process manufacturing where moisture resistance and precise thermal control justify higher material expenditure.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate boiler insulation upgrades to reduce fuel consumption and associated emissions, while OSHA's thermal burn protection standards dictate minimum surface temperature limits on exposed industrial equipment. The Department of Energy's industrial efficiency guidelines further shape product specification through documented thermal performance requirements. Stakeholders must monitor evolving state-level carbon intensity regulations and utility rebate programs that increasingly tie insulation upgrade incentives to verified energy savings metrics.
Market Dynamics
EPA's tightened emissions standards for industrial boilers are accelerating material upgrades across downstream energy processors. Petrochemical facility operators are expanding procurement of high-temperature insulation systems while midstream operators fragment procurement across specialized contractors.
Growth Catalysts
- EPA Emissions Mandates:The National Emission Standards for Hazardous Air Pollutants compel boiler insulation upgrades to reduce fuel consumption and associated emissions across power generation and refining facilities.
- Texas Gulf Coast Refining Clusters:Concentrated petrochemical capacity expansion drives sustained demand for high-temperature piping insulation systems rated for continuous operation above 650 degrees Celsius.
- Mineral Wool Formulations:Advanced stone wool compositions sustaining performance above 1,000 degrees Celsius displace legacy ceramic fiber in refinery furnace applications.
Market Restraints
- Silica Sand Supply Concentration:Fiberglass insulation production depends on high-purity silica sand deposits concentrated in limited Midwestern mining operations, creating input cost volatility.
- Basalt Fiber Technical Limitations:Stone wool manufacturing requires specific volcanic rock chemistries that constrain batch consistency and thermal performance repeatability at extreme temperatures.
- OSHA Compliance Friction:Thermal burn protection standards dictate minimum surface temperature limits that extend engineering timelines and certification costs for exposed industrial equipment.
Strategic Opportunities
- Alberta Oil Sands Processing Corridors:Bitumen upgrading facilities require specialized cryogenic and high-temperature insulation systems for steam-assisted gravity drainage operations.
- Department of Energy Efficiency Rebates:Utility incentive programs tying insulation upgrade subsidies to verified energy savings metrics create procurement pull through documented thermal performance requirements.
- Pharmaceutical Cleanroom Convergence:Moisture-resistant foam insulation systems combined with precision thermal control specifications penetrate sterile manufacturing environments previously served by HVAC-centric solutions.
Industry Challenges
- Certified Installer Scarcity:Proper application of high-temperature mineral wool systems demands specialized mechanical insulation journeymen with NCCER certification, constraining project velocity.
- Legacy Equipment Integration:Retrofitting asbestos-containing insulation in aging power generation boilers requires abatement protocols that compress installation windows and inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Insulation Market |
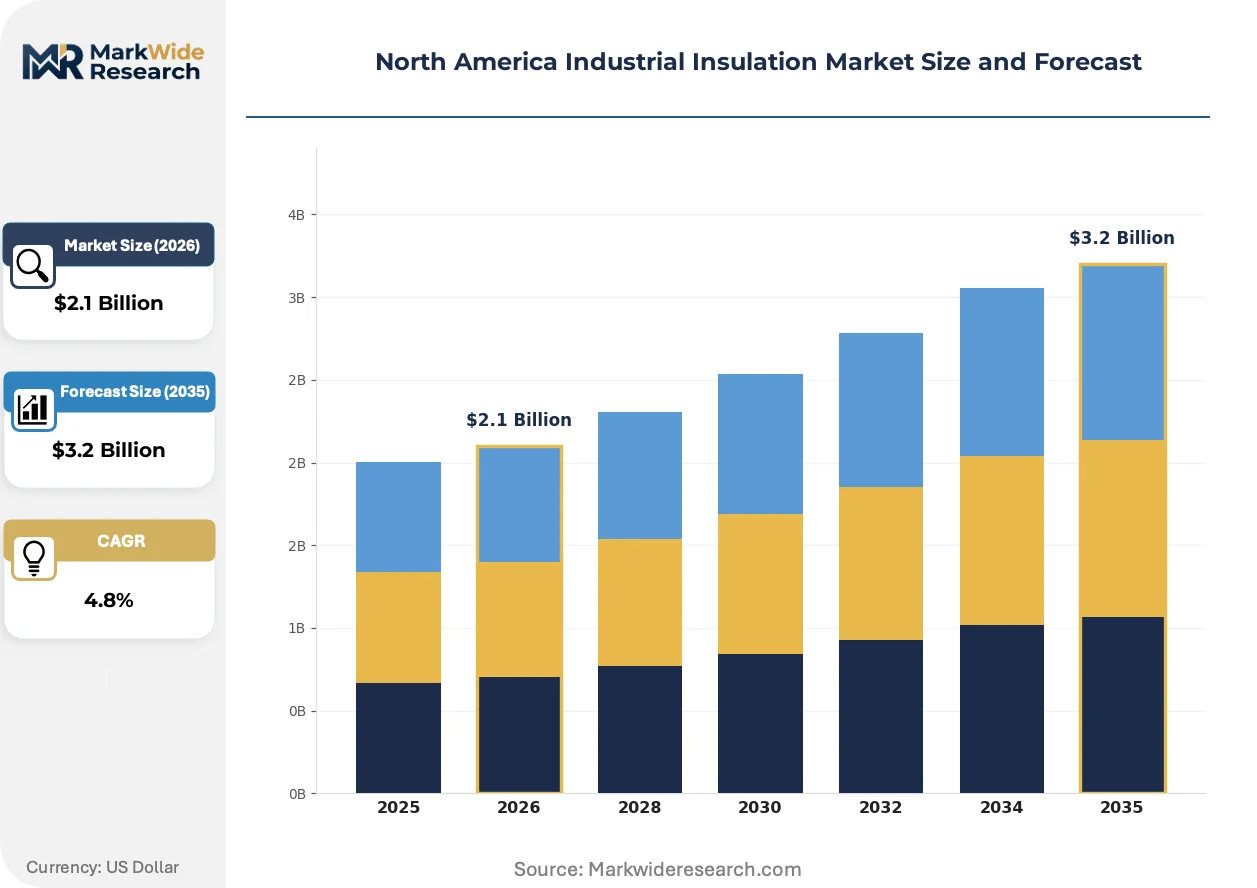
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Mineral Wool, Foam, Calcium Silicate Application: Piping, Boilers, HVAC, Ductwork End User: Oil & Gas, Power Generation, Manufacturing, Pharmaceutical Installation Type: New Construction, Retrofit, Maintenance, Upgrade |
| Companies Covered | Owens Corning, Johns Manville, Rockwool International A/S, Knauf Insulation, Saint-Gobain, Aspen Aerogels, Cabot Corporation, Morgan Advanced Materials, Unifrax, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Insulation Market Strategic Shifts & Innovations
Aerogel composite formulations and smart insulation monitoring systems are actively displacing conventional material specifications across critical process equipment. The convergence of advanced materials science with digital thermal management is compressing specification cycles and elevating performance benchmarks.
Silica aerogel blankets laminated with fiberglass scrim are rewriting thermal conductivity benchmarks for sub-ambient process lines. LNG export terminal operators along the Gulf Coast specify these composites for boil-off gas minimization. The technology is compressing insulation thickness requirements by half while maintaining equivalent thermal resistance, enabling pipe rack density improvements in congested process units.
The EPA's National Emission Standards for Hazardous Air Pollutants enforcement is mandating boiler MACT compliance upgrades across affected source categories. Industrial facility operators must document insulation thermal performance to demonstrate fuel efficiency gains that correlate with emissions reductions. Coal-fired power generators in the Ohio River Valley face compressed upgrade timelines as state implementation plans tighten.
Integrated service contracts bundling material supply with thermal performance guarantees are displacing traditional unit-price procurement. Downstream energy processors in the Houston Ship Channel corridor now specify outcome-based agreements where contractors assume energy savings risk. This model transfers performance verification burden to insulation contractors and compresses supplier qualification to firms with documented measurement and verification capabilities.
North America Industrial Insulation Market Segmentation
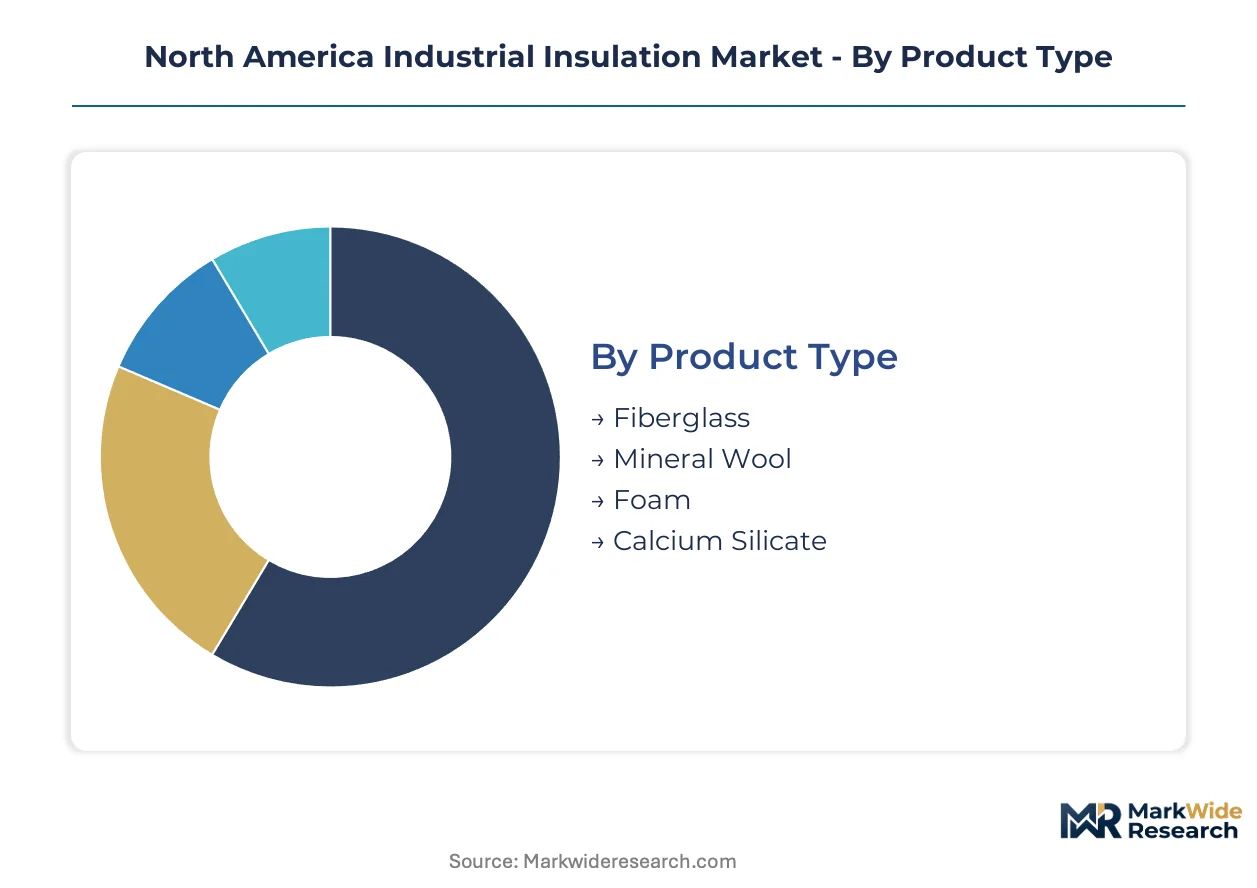
Industrial insulation procurement patterns diverge sharply between standalone material supply and integrated system contracts. Specification cycles compress where thermal performance guarantees bundle with installation labor, reshaping how segments interact across the value chain.
Product Type:
Fiberglass and mineral wool dominate standalone material procurement, while foam and calcium silicate systems increasingly embed within turnkey thermal management packages.
- Mineral Wool:Stone wool formulations engineered from basalt and slag deliver continuous operation ratings at 650 degrees Celsius and above. Demand concentrates across Texas Gulf Coast refinery furnace linings where EPA boiler MACT compliance mandates displace legacy ceramic fiber. Rockwool International A/S and Johns Manville anchor supply contracts through high-temperature specification expertise.
- Fiberglass:Lightweight glass fiber batts achieve thermal conductivity near 0.04 W/m·K and dominate HVAC ductwork and moderate-temperature piping. Owens Corning leverages manufacturing scale across Midwestern silica sand corridors to capture volume share in Gulf Coast petrochemical maintenance cycles.
- Foam:Closed-cell polymeric systems penetrate pharmaceutical cleanrooms and cryogenic LNG terminals where moisture resistance and precise thermal control justify premium positioning.
- Calcium Silicate:Pre-formed rigid sections serve high-temperature steam piping and industrial boiler applications requiring compressive strength and dimensional stability under thermal cycling.
Volume placements concentrate in fiberglass; the faster expansion belongs to foam.
Application:
Application selection tracks temperature regime and accessibility constraints, with high-heat environments commanding specialized contractor networks.
- Piping:Process line insulation spans cryogenic LNG transfer systems to superheated steam distribution, with thickness specifications driven by surface temperature limits under OSHA thermal burn standards. Alberta oil sands SAGD operations and Texas Gulf Coast refinery expansions sustain demand for multi-layer high-temperature systems.
- Boilers:Power generation and industrial steam generators require refractory-grade insulation rated for extreme thermal shock and chemical exposure. EPA emissions enforcement accelerates MACT-driven upgrade cycles across Ohio River Valley coal-fired plants.
- HVAC:Commercial and industrial climate control systems specify lightweight fiberglass duct lining and external wrap, with efficiency rebates from Department of Energy programs driving retrofit specification.
- Ductwork:Air handling distribution networks prioritize acoustic attenuation alongside thermal performance, with fabrication shop pre-insulation displacing field application in large commercial projects.
Revenue tilts toward piping; specification velocity peaks in boilers.
End User:
End-user procurement sophistication varies from commodity spot purchasing to outcome-based performance contracting with guaranteed energy savings.
- Oil & Gas:Integrated majors and midstream operators fragment procurement between material supply and specialized mechanical insulation contractors. Houston Ship Channel petrochemical clusters drive demand for high-temperature systems sustaining performance above 1,000 degrees Celsius in furnace applications.
- Power Generation:Coal, natural gas, and nuclear operators face compressed EPA compliance timelines that bundle insulation upgrades with emissions control investments. Legacy asbestos abatement constraints inflate project costs and extend engineering phases.
- Manufacturing:Process industries including steel, cement, and chemicals specify insulation through maintenance capital budgets with shorter approval cycles than greenfield projects.
- Pharmaceutical:Sterile manufacturing environments demand moisture-resistant foam systems with documented cleanroom compatibility, penetrating segments previously served by HVAC-centric solutions.
Contract value aggregates in oil and gas; the steepest expansion trajectory runs through pharmaceutical.
Installation Type:
Installation type determines contractor qualification requirements and project risk allocation between owner and service provider.
- New Construction:Greenfield petrochemical and power projects enable optimized insulation design integrated with process equipment specification, though capital cycle timing creates demand volatility.
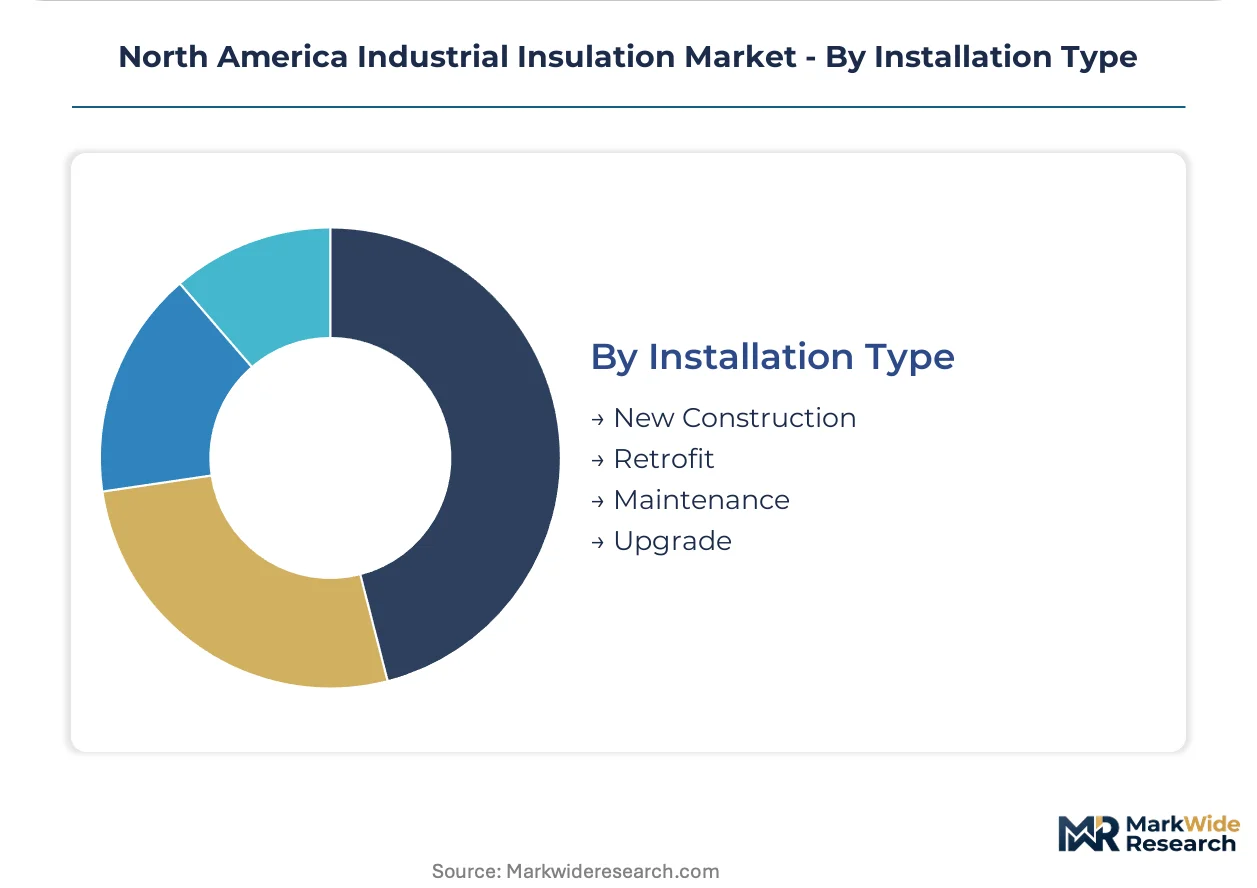
- Retrofit:Existing facility upgrades dominate current procurement as EPA mandates and efficiency incentives compress payback thresholds for thermal performance investments.
- Maintenance:Turnaround-driven replacement cycles sustain baseline demand across Gulf Coast refining corridors, with NCCER-certified journeyman scarcity constraining project velocity.
- Upgrade:Performance-enhancing replacements of legacy insulation systems bundle material supply with measurement and verification protocols that document energy savings for utility rebate capture.
Project flow concentrates in retrofit; upgrade contracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Downstream energy processors concentrate procurement across the Texas Gulf Coast and Alberta oil sands corridors, with EPA emissions mandates and provincial efficiency programs reshaping material specification patterns.
United States
Petrochemical facility operators along the Houston Ship Channel expand high-temperature insulation procurement for furnace applications above 1,000 degrees Celsius. EPA boiler MACT compliance deadlines compress upgrade timelines across Ohio River Valley coal-fired power plants. The Gulf Coast refining cluster sustains multi-layer piping insulation demand for continuous operation above 650 degrees Celsius.
Canada
Bitumen upgrading facilities in Alberta's oil sands processing corridors require specialized cryogenic and high-temperature systems for steam-assisted gravity drainage operations. Natural Resources Canada's energy efficiency programs tie insulation upgrade incentives to verified thermal performance metrics. Edmonton and Fort McMurray anchor procurement concentration for extreme-temperature process equipment.
Mexico
Pemex refining modernization drives specification of calcium silicate rigid sections for high-temperature steam distribution networks. Mexico's national energy efficiency standards mandate documented thermal performance for industrial boiler retrofits. Tula and Salina Cruz refining complexes concentrate demand for refractory-grade insulation systems.
North America Industrial Insulation Market Key Industry Players
United States producers anchor one tier; Danish and European specialists hold differentiated positions in high-temperature formulations. The market structures around three to five dominant material families with concentrated manufacturing scale in Midwestern silica corridors and specialized volcanic rock processing. Strategic archetypes include scale-driven fiberglass manufacturers, mineral wool specialists commanding premium thermal ratings, and aerogel innovators penetrating sub-ambient applications. Competitive moves center on integrated service contracts bundling material supply with performance guarantees, alongside selective capacity expansion in Gulf Coast logistics corridors.
Within the scale-driven tier, Owens Corning exemplifies manufacturing breadth anchored in domestic silica sand corridors. Johns Manville occupies a position exemplifying mineral wool specialization for power generation boiler applications. Rockwool International A/S represents the high-temperature stone wool archetype sustaining performance above 1,000 degrees Celsius in refinery furnace settings.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Rockwool International A/S |
| Knauf Insulation |
| Saint-Gobain |
| Aspen Aerogels |
| Cabot Corporation |
| Morgan Advanced Materials |
| Unifrax |
| Others |
Cost & Logistics Intelligence
EPA boiler MACT compliance mandates are compressing procurement timelines for high-temperature insulation systems, forcing suppliers to absorb certification costs while buyers demand bundled performance guarantees that compress material-only pricing power.
Pricing Analysis
Volume placements in fiberglass batts for HVAC and moderate-temperature piping run on thin margins anchored to Midwestern silica sand input costs, while premium mineral wool formulations for refinery furnace applications above 650 degrees Celsius command substantial markups tied to thermal performance certification. Price differentiation hinges on NCCER-certified installer availability and EPA emissions documentation capabilities. Cost compression in the fiberglass tier is intensifying because Owens Corning and Johns Manville leverage captive silica processing to undercut regional distributors. Midstream oil and gas operators exhibit the highest price sensitivity due to fragmented procurement across specialized contractors, whereas integrated petrochemical majors prioritize thermal performance guarantees over unit material costs.
Supply Chain Analysis
Reverse-logistics flows for asbestos-containing insulation abatement in aging power generation boilers compress installation windows and inflate project costs, creating specialized contractor scarcity that reshapes downstream distribution patterns. High-purity silica sand for fiberglass production concentrates in limited Midwestern United States mining operations, while basalt and slag feedstocks for stone wool draw from volcanic rock deposits in the United States and Canada. Single-source vulnerability in certified mechanical insulation journeymen with NCCER credentials constrains project velocity across Texas Gulf Coast refining clusters. Distribution runs through integrated service contracts bundling material supply with thermal performance guarantees, displacing traditional unit-price procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America industrial insulation market functions as a cost-of-compliance arena where EPA National Emission Standards for Hazardous Air Pollutants erect barrier-to-entry moats that favor incumbents with documented MACT compliance capabilities and certified installer networks.
For Market Incumbents: Anticipate margin compression in commodity fiberglass batts as Owens Corning leverages captive silica processing scale, and respond by deepening certification investment for high-temperature mineral wool formulations above 1,000 degrees Celsius where Rockwool International A/S and Johns Manville hold defensive positions. Backward integration into basalt fiber processing secures batch consistency for refinery furnace applications. For New Entrants and Emerging Players: Begin with pharmaceutical cleanroom foam insulation where moisture resistance specifications and cleanroom compatibility documentation create white-space penetration opportunities previously served by HVAC-centric solutions. Alberta oil sands SAGD operations offer a second penetrable frontier requiring specialized cryogenic and high-temperature systems. A go-to-market angle bundling material supply with measurement and verification protocols for utility rebate capture differentiates against commodity distributors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive raw material processing and certified installer training infrastructure. Over the long-term horizon, acquisition targets should demonstrate EPA compliance documentation capabilities and Gulf Coast logistics positioning. Monitor state-level carbon intensity regulation tightening and utility rebate program expansion as inflection indicators for upgrade contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Processing | Captive volcanic rock supply secures thermal performance repeatability for refinery furnace applications above 1,000 degrees Celsius. |
| NCCER Certification Program Expansion | Trained mechanical insulation journeymen alleviate installer scarcity constraining project velocity across Gulf Coast refining corridors. |
| Integrated Service Contract Bundling | Outcome-based agreements with thermal performance guarantees transfer energy savings risk and compress supplier qualification. |
| Aerogel Composite Formulation Development | Silica aerogel blankets laminated with fiberglass scrim enable LNG terminal boil-off gas minimization with half-thickness insulation. |
| Alberta Oil Sands Logistics Positioning | Edmonton and Fort McMurray distribution hubs capture SAGD bitumen upgrading facility demand for extreme-temperature systems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were cross-referenced with primary interviews conducted with petrochemical facility procurement managers, power generation maintenance directors, mechanical insulation contractors, EPA compliance officers, and utility rebate program administrators. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level estimates across the analysis window.
Granularity-level modeling tracked product type, application temperature regime, end-user industry, and installation type dimensions at the country level for the United States, Canada, and Mexico. CAGRs were derived from regression analysis of historical procurement patterns and forward-projected regulatory compliance deadlines. Forecast inputs incorporated EPA boiler MACT implementation timelines and Natural Resources Canada efficiency incentive program allocations.
EPA enforcement intensity variations, silica sand supply disruptions, and certified installer availability fluctuations are the dominant revision risks to the outlook. Forecasts reflect assumptions regarding sustained regulatory pressure and utility rebate continuity. Practitioners should monitor state implementation plan tightening and NCCER training program expansion for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Technical Foam Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Global Molded Foams Market