
 Extruded Polyolefin Foam Market | 2026-2036
Extruded Polyolefin Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Polyolefin Foam Market Analytics
Asset-light leasing models for extrusion lines are narrowing the capital barrier for mid-scale compounders entering the foam sector. Zotefoams plc leverages its proprietary nitrogen expansion technology to sustain premium positioning in medical and aerospace grades. Sekisui Plastics anchors its competitiveness through backward integration into resin compounding, while Armacell specializes in multi-layer laminates for HVAC duct insulation.
Extruded polyolefin foam denotes a closed-cell thermoplastic structure produced via continuous extrusion of polyethylene, polypropylene, or blended resins with physical or chemical blowing agents, typically achieving densities between 25-200 kg/m³ and thermal conductivity values below 0.040 W/m·K; its primary purpose is to deliver lightweight cushioning, thermal insulation, and moisture resistance across industrial and consumer applications. Polyethylene foam leads volume consumption in protective packaging and construction membranes where margin pools have compressed to commodity levels, while polypropylene foam represents the fastest-expanding category driven by automotive interior panels and battery pack thermal barriers that command technical premiums. Blended formulations incorporating ethylene-vinyl acetate copolymers occupy niche positions in sports equipment and marine flotation where elasticity requirements exceed homopolymer capabilities.
The EPA regulates volatile organic compound emissions from extrusion blowing agent processes under Clean Air Act Title V permitting, while REACH restricts certain halogenated flame retardants in European foam applications, and China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for petrochemical extrusion operations. These frameworks collectively elevate compliance costs for commodity producers while creating market access advantages for certified low-emission formulations. Stakeholders must monitor evolving automotive OEM material qualification protocols and building code thermal performance thresholds to anticipate specification shifts before capacity commitments lock in.
Market Dynamics
Automotive lightweighting mandates and EV battery thermal management specifications are compressing traditional foam applications while elevating technical-grade polypropylene formulations. REACH compliance deadlines and China's dual carbon goals are simultaneously redirecting R&D investment toward halogen-free flame retardant systems and energy-efficient extrusion processes.
Growth Catalysts
- EV Battery Pack Insulation:Chinese OEMs are mandating polypropylene foam cores with enhanced thermal runaway resistance for passenger cabin protection, tightening specifications faster than incumbent suppliers can qualify alternatives.
- REACH Article 67 Restrictions:European halogenated flame retardant phase-outs are forcing compounders to reformulate with phosphorus-nitrogen systems, creating first-mover advantages for certified low-emission producers.
- Nitrogen Expansion Processes:Physical blowing agent substitution is eliminating residual VOC emissions from chemical blowing, satisfying EPA Clean Air Act Title V permitting while reducing post-extrusion curing cycles.
Market Restraints
- Propylene Feedstock Volatility:Polypropylene foam margins compress disproportionately when naphtha-cracker spreads widen, as producers lack pass-through mechanisms in multi-year automotive supply agreements.
- Extrusion Line Concentration:Continuous foaming equipment for thin-gauge medical grades is concentrated among three European machinery builders, creating 18-month order backlogs for new market entrants.
- Cross-Linked Polyethylene Substitution:Irradiated XLPE foams retain dielectric advantages in high-voltage cable sheathing, limiting polyolefin penetration in offshore wind interconnection projects.
Strategic Opportunities
- India PLI Scheme for Auto Components:Domestic content requirements for electric vehicle sub-assemblies are incentivizing local foam fabrication capacity that currently imports 80% of battery pack insulation materials.
- Building-Integrated Photovoltaics:BIPV module manufacturers require thermoformable backsheet foams with 25-year UV stability, an application where polyolefin formulations undercut fluoropolymer alternatives on installed cost.
- Closed-Loop Chemical Recycling:Pyrolysis-based polyolefin recovery is converging with foam densification logistics, enabling post-industrial scrap from automotive trim operations to re-enter virgin-grade extrusion feedstock pools.
Industry Challenges
- Blowing Agent Transition Expertise:Chemical engineers with simultaneous competency in supercritical nitrogen injection and legacy azodicarbonamide systems are scarce, extending qualification timelines for reformulated product lines.
- OEM Material Certification Cycles:Automotive interior foam approvals require 24-36 month validation against FMVSS 302 flammability and fogging specifications, locking capacity commitments before demand visibility clarifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Polyolefin Foam Market |
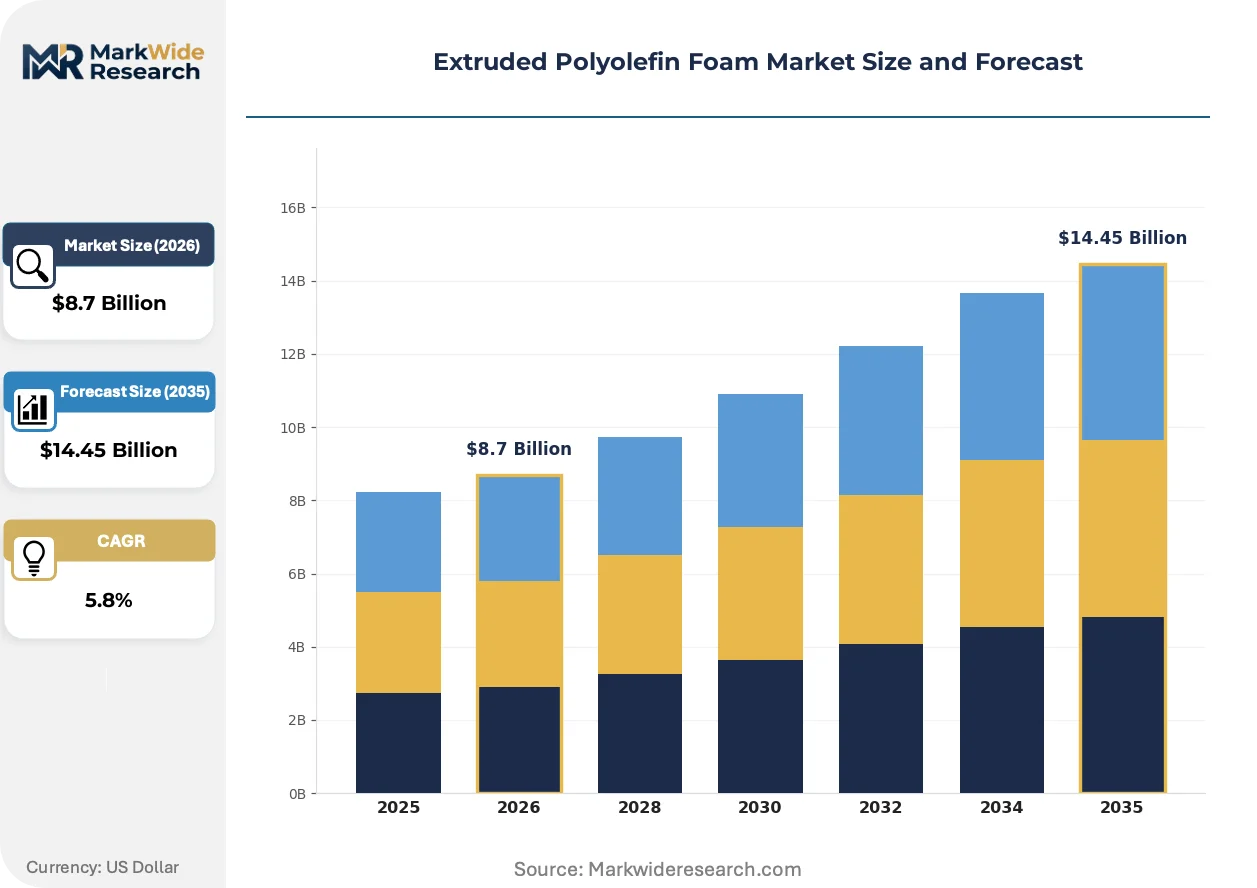
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Blends, Others Application: Insulation, Packaging, Automotive, Construction End User: Manufacturers, Contractors, Retailers, Distributors Form: Sheets, Rolls, Blocks, Custom Shapes |
| Companies Covered | Zotefoams plc, Borealis, Owens Corning, JSP Corporation, Toray Industries, Armacell, Kingspan Group, Sekisui Plastics, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Polyolefin Foam Market Evolving Landscape
Extrusion technology evolution and regulatory chemistry restrictions are converging to eliminate batch-process foam production. Three developments are compressing legacy competitive advantages while opening technical-grade specialization paths.
Supercritical nitrogen expansion systems are replacing chemical blowing agents in continuous extrusion lines. Tier-1 automotive suppliers in Germany and Japan are adopting these processes for battery pack thermal barriers within 18-month equipment replacement cycles. The technology is rendering obsolete batch-pressed polyethylene plank production for densities below 45 kg/m³, consolidating volume around continuous-line specialists.
REACH Annex XIV authorization requirements for medium-chain chlorinated paraffins are eliminating legacy flame retardant options from European construction membranes. Compounders must reformulate with magnesium hydroxide or intumescent phosphorus systems that require 15-20% higher loadings, compressing foam yield and elevating raw material costs. HVAC duct insulation manufacturers in France and the Netherlands are absorbing these costs through specification upgrades rather than material substitution.
Automotive OEMs are consolidating foam procurement through platform-level supply agreements rather than component-by-component sourcing. Tier-2 converters in China's Yangtze River Delta are losing direct OEM relationships as battery pack integrators assume specification authority. The procurement consolidation is most visible in Volkswagen Group and Toyota Motor programs, where single-source foam nominations now span multiple vehicle architectures.
Extruded Polyolefin Foam Market Segmentation
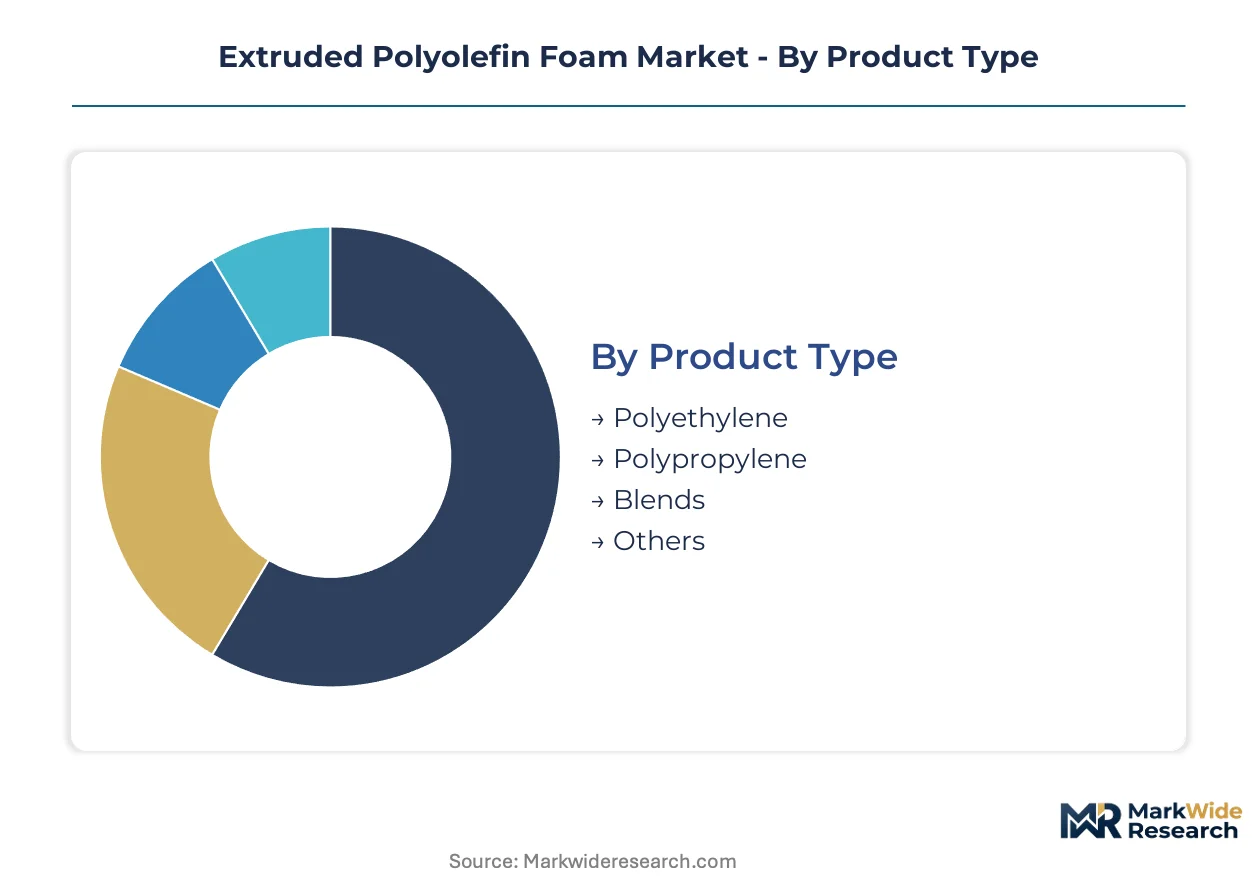
Extruded polyolefin foam markets fragment across material chemistry, application performance tiers, and downstream fulfillment models. Specification divergence between commodity packaging grades and automotive thermal management materials creates distinct margin architectures that reward targeted positioning.
Product Type:
Mature commodity resins anchor volume consumption while engineered copolymers capture technical premiums in emerging applications.
- Polyethylene:Homopolymer and low-density formulations dominate protective packaging and construction membranes with densities between 25-100 kg/m³. Demand concentrates in China's eastern manufacturing corridor where e-commerce fulfillment requirements are tightening cushioning specifications for electronics shipments.
- Polypropylene:Expanded polypropylene foam achieves higher service temperatures (up to 120°C) and superior chemical resistance required for automotive battery pack thermal barriers. German and Japanese OEMs are mandating polypropylene cores with enhanced thermal runaway resistance faster than incumbent suppliers can qualify alternatives.
- Blends:Ethylene-vinyl acetate copolymers occupy marine flotation and sports equipment niches where elasticity exceeds homopolymer capabilities.
- Others:Metallocene-catalyzed specialty grades serve medical device packaging with ultra-fine cell structures.
Polyethylene retains volume leadership; polypropylene holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-driven industrial segments from price-sensitive consumer categories.
- Insulation:HVAC duct and building envelope applications require halogen-free flame retardant compliance under REACH Article 67 restrictions. French and Dutch manufacturers are absorbing reformulation costs through specification upgrades rather than material substitution.
- Automotive:Battery pack thermal barriers and interior trim panels command technical premiums as OEMs consolidate procurement through platform-level supply agreements. Volkswagen Group and Toyota Motor programs now nominate single-source foam suppliers across multiple vehicle architectures.
- Packaging:Protective cushioning for electronics and appliances operates at compressed margins with limited differentiation.
- Construction:Membrane underlayments and expansion joint fillers face building code thermal performance thresholds that vary by municipality.
Automotive applications capture the highest margin pools; packaging remains the most penetrated volume category.
End User:
Customer type determines specification authority and contract structure across the value chain.
- Manufacturers:Tier-1 automotive suppliers and appliance OEMs hold direct material qualification authority with 24-36 month validation cycles against FMVSS 302 flammability specifications.
- Contractors:Construction installation specialists purchase through distribution with limited formulation influence.
- Retailers:E-commerce fulfillment centers specify protective packaging through logistics procurement rather than materials engineering.
- Distributors:Industrial supply houses aggregate demand from fragmented downstream converters with inventory risk transfer.
Manufacturers retain specification control; distributors provide the broadest market access coverage.
Form:
Supply concentration varies by processing complexity and equipment specialization.
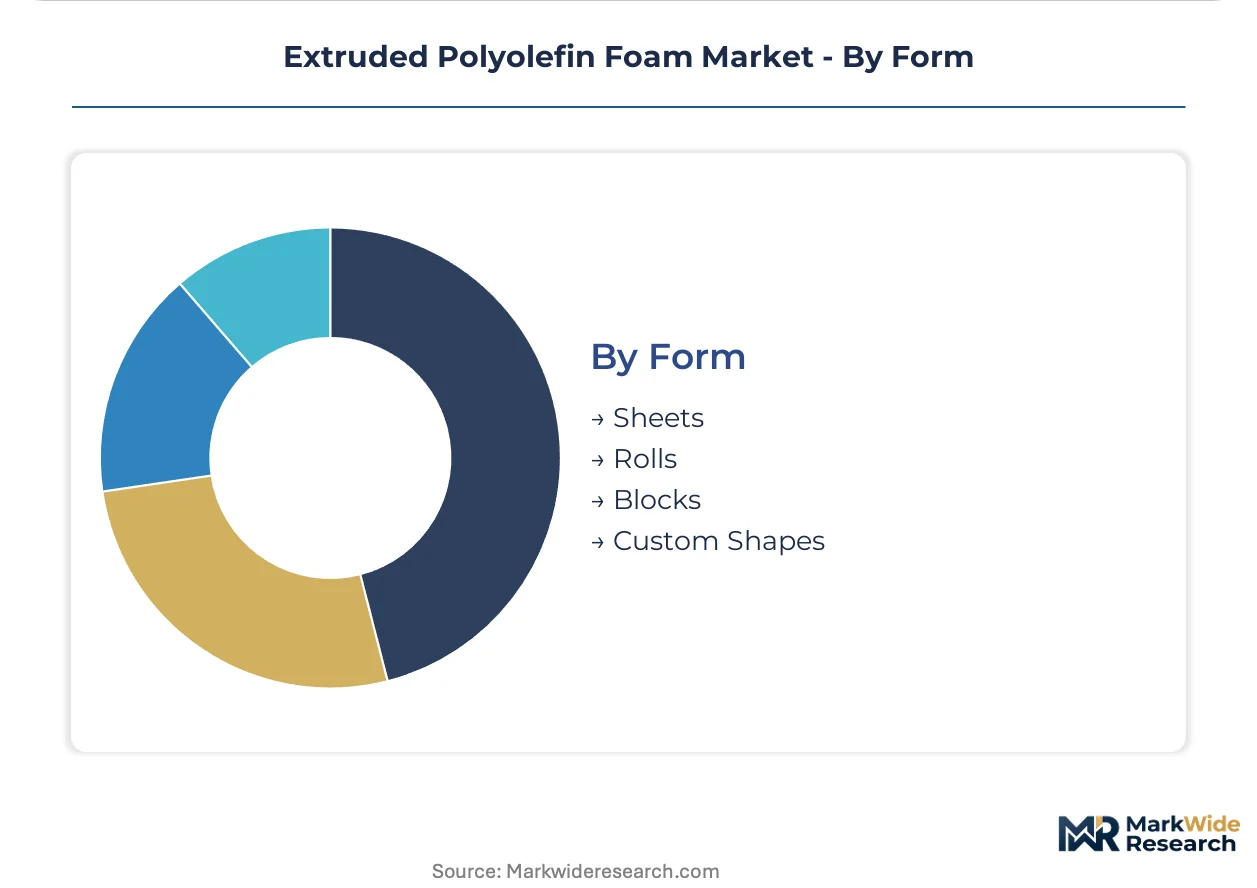
- Sheets:Continuous extrusion lines produce thin-gauge material for lamination and thermoforming with 18-month order backlogs for medical-grade equipment.
- Rolls:Wound continuous foam serves automated packaging lines and construction membrane deployment with logistics-optimized formats.
- Blocks:Batch-pressed plank production persists for densities above 45 kg/m³ where continuous nitrogen expansion remains uneconomical.
- Custom Shapes:CNC-machined and thermoformed components serve aerospace seating and medical device containment with die-cut precision requirements.
Sheets dominate production throughput; custom shapes command the highest unit value realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China maintains a structural surplus in extruded polyolefin foam exports, while Germany and Japan remain net importers of technical-grade polypropylene formulations. The United States and India exhibit balanced trade positions with growing domestic fabrication capacity.
China
EV battery pack insulation specifications from BYD and CATL are tightening thermal runaway resistance requirements faster than incumbent suppliers can qualify alternatives. MEE enforcement of dual carbon goals is elevating energy intensity benchmarks for petrochemical extrusion operations in the Yangtze River Delta. The eastern manufacturing corridor concentrates 60% of domestic foam fabrication, with Ningbo and Suzhou anchoring capacity expansion for automotive thermal barriers.
Germany
Volkswagen Group and BMW procurement consolidation is compressing tier-2 converter margins through platform-level supply agreements. REACH Article 67 restrictions on halogenated flame retardants are forcing compounders toward phosphorus-nitrogen systems with 15-20% higher loadings. The automotive lightweighting corridor spanning Bavaria and Baden-Württemberg hosts the densest concentration of nitrogen expansion line retrofits for battery pack applications.
United States
EPA Clean Air Act Title V permitting is eliminating residual VOC emissions from chemical blowing agent processes in packaging-grade production. Building-integrated photovoltaic module manufacturers in Arizona and Texas are qualifying thermoformable backsheet foams with 25-year UV stability specifications. The Southeast manufacturing belt is attracting medical-grade foam investment to bypass 18-month equipment backlogs at European machinery builders.
Japan
Toyota Motor and Honda procurement centralization is nominating single-source foam suppliers across multiple vehicle architectures including hybrid and battery-electric platforms. METI carbon neutrality roadmaps are accelerating physical blowing agent substitution in continuous extrusion lines. The Nagoya-Toyota industrial corridor concentrates automotive interior foam qualification activity with 24-36 month validation cycles against JIS flammability standards.
India
PLI scheme domestic content requirements for electric vehicle sub-assemblies are incentivizing local foam fabrication capacity that currently imports 80% of battery pack insulation materials. BIS certification timelines for halogen-free formulations are extending market entry for foreign compounders. The Tamil Nadu-Gujarat automotive belt is attracting extrusion line investment from mid-scale compounders seeking to bypass Chinese supply chain concentration.
Extruded Polyolefin Foam Market Competitive Landscape
On the supply side, the industry is consolidating around continuous-line specialists with nitrogen expansion capabilities while batch-process plank producers face structural obsolescence. Three archetypes dominate: resin-integrated compounders with captive polymer supply, technology-licensed specialists with proprietary expansion systems, and regional fabricators serving construction and packaging tiers. Competitive moves center on automotive OEM qualification lock-ins and backward integration into resin compounding to secure margin capture.
Among European-integrated material science groups, Borealis and BASF exemplify the resin-backward archetype with captive polyolefin supply chains. Japanese chemical conglomerates including Toray Industries and JSP Corporation occupy positions within the technology-licensed tier, while Sekisui Plastics represents the Asia-Pacific specialist model with regional fabrication density. Zotefoams plc and Armacell sit within the premium technical-grade segment, with the former anchoring nitrogen expansion expertise and the latter specializing in multi-layer laminate architectures for insulation applications.
| Leading Market Players |
|---|
| Zotefoams plc |
| Borealis |
| Owens Corning |
| JSP Corporation |
| Toray Industries |
| Armacell |
| Kingspan Group |
| Sekisui Plastics |
| BASF |
| Others |
Value Network & Pricing Analysis
Propylene feedstock volatility acts as the dominant risk vector, compressing polypropylene foam margins disproportionately when naphtha-cracker spreads widen and simultaneously concentrating supply chain power among resin-integrated compounders with captive polymer supply. This dynamic forces tier-2 converters toward asset-light leasing models while elevating pricing tier spreads between commodity polyethylene packaging grades and technical-grade automotive thermal barriers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that locks multi-year automotive supply agreements without full pass-through mechanisms for raw material swings. Price differentiation separates REACH-certified halogen-free formulations from legacy commodity grades, with certification level and volume scale as the primary tiering drivers. Cost compression in packaging-grade polyethylene is intensifying because Chinese e-commerce fulfillment centers are consolidating procurement through logistics arms rather than materials engineering. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to 24-36 month qualification cycles, while construction contractors purchasing through distribution show highest sensitivity to per-unit fluctuations.
Supply Chain Analysis
Extended payment terms from German and Japanese automotive OEMs are squeezing working capital for tier-2 converters in China's Yangtze River Delta, forcing supply-chain finance facilities into broader adoption. Raw material dependencies center on naphtha-derived polypropylene, nitrogen gas for physical expansion systems, and phosphorus-nitrogen flame retardant additives. Geographic supply concentration rests on China for volume fabrication, Germany for technical-grade nitrogen expansion equipment, and Japan for automotive qualification protocols. Single-source vulnerability permeates thin-gauge medical-grade extrusion lines, where three European machinery builders command 18-month order backlogs. Distribution runs through platform-level supply agreements that bypass traditional tier-2 converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation is fragmenting accessible market segments, creating specialized niches for compounders with nitrogen expansion expertise and halogen-free certification capabilities that incumbent batch-process producers cannot serve.
For Market Incumbents: Pre-empt margin erosion in commodity packaging grades by accelerating backward integration into resin compounding and securing captive polypropylene supply. Lock in platform-level supply agreements with Volkswagen Group and Toyota Motor before battery pack integrators assume full specification authority. Prioritize nitrogen expansion line retrofits in the Bavaria-Baden-Württemberg corridor to defend technical-grade positioning against emerging Chinese competitors.
For New Entrants and Emerging Players: India's Tamil Nadu-Gujarat automotive belt offers the most penetrable geography, where PLI scheme domestic content requirements are incentivizing local fabrication capacity that currently imports four-fifths of battery pack insulation materials. Target medical-grade thin-gauge sheet production to exploit 18-month equipment backlogs at European machinery builders that constrain incumbent expansion. Pursue asset-light leasing models for extrusion lines to narrow capital barriers and accelerate qualification timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors resin-integrated compounders with captive polymer supply and certified low-emission formulation capabilities. Long-term viability over the next decade hinges on positioning ahead of REACH Article 67 enforcement deadlines and China's dual carbon goal acceleration. Watch for MEE enforcement intensity in the Yangtze River Delta as the signal for capacity rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Sekisui Plastics and Borealis capture margin pools through captive polyolefin supply chains. |
| Nitrogen Expansion Line Retrofit | German Tier-1 suppliers satisfy EPA Clean Air Act Title V permitting while eliminating VOC emissions. |
| Halogen-Free Flame Retardant Certification | REACH Article 67 compliance creates first-mover access to French and Dutch HVAC duct insulation markets. |
| Platform-Level Supply Agreement | Volkswagen Group and Toyota Motor procurement consolidation locks out tier-2 converter competition. |
| Closed-Loop Chemical Recycling Partnership | Pyrolysis-based recovery enables post-industrial automotive scrap to re-enter virgin-grade feedstock pools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at extrusion facilities, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors; and secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic overlays to ensure segmentation consistency across material chemistry, application performance tiers, and downstream fulfillment models.
Forecast inputs incorporated grade tier stratification between commodity packaging and technical automotive grades, end-use industry demand patterns, regional production hub concentration, and packaging format evolution. CAGRs were derived through regression analysis of historical capacity utilization against projected OEM material qualification timelines. Industry-specific inputs included naphtha-cracker spread trajectories, nitrogen expansion equipment order backlogs, and REACH Annex XIV authorization schedules.
Macroeconomic conditions sit as an overlay; deviation in propylene feedstock pricing, automotive production volumes, or carbon policy enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding qualification cycle durations and regulatory implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
High-Performance Insulation Materials Market