
 Mexico Flat Glass Market | 2026-2036
Mexico Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Flat Glass Market Insights
Automotive glazing is repositioning as Mexico's highest-velocity flat glass demand vertical, driven by OEM assembly expansion and stricter windshield safety mandates. Vitro leverages its integrated float-to-fabrication footprint to dominate automotive supply contracts across central Mexico. Guardian Industries anchors its position through specialized tempered glass capacity serving Tier 1 automotive suppliers. Cardinal Glass Industries sustains architectural market share via low-emissivity coated product lines tailored to northern Mexico's solar load conditions.
Flat glass comprises silica-soda-lime sheets manufactured through the float process, yielding uniform thickness between 2 mm and 25 mm for architectural, transportation, and specialty applications. Tempered glass leads volume output due to mandatory safety codes for automotive side windows and commercial facades, while laminated glass captures expanding margin pools from hurricane-resistant and acoustic insulation specifications. Coated glass, particularly solar control and low-emissivity variants, represents the fastest-growing product category as NOM-020-ENER energy standards tighten across Mexican states.
Secretaría de Energía (SENER) enforces building envelope efficiency mandates that directly specify coated glass performance coefficients, while SEMARNAT regulates emissions from float furnace operations. PROFECO's consumer protection standards govern glass product labeling and warranty claims, shaping market access requirements for imported and domestic suppliers. Stakeholders must monitor proposed updates to NOM construction codes and furnace emission thresholds to anticipate capacity investment timing and product certification priorities.
Market Dynamics
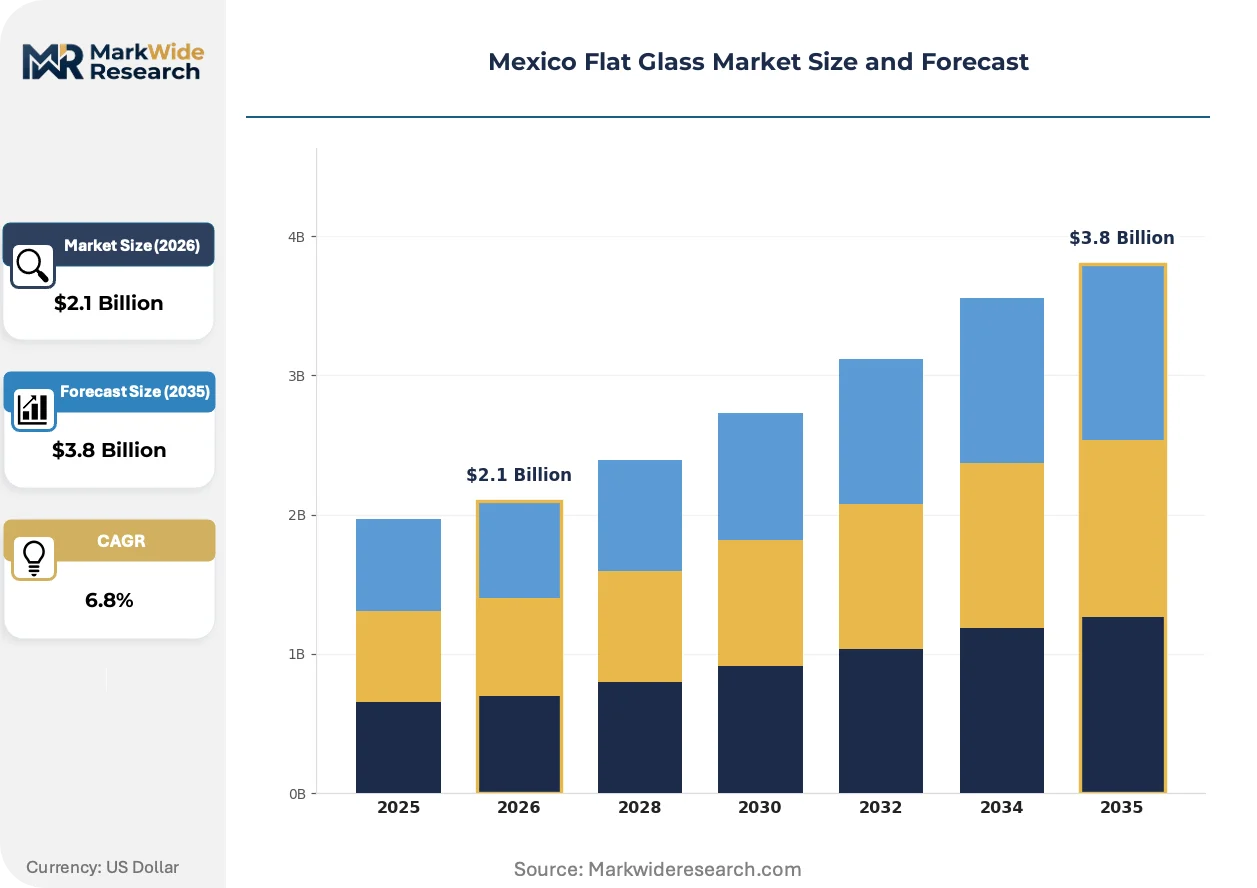
The Mexico flat glass market is undergoing structural reconfiguration as NOM-020-ENER energy efficiency mandates force rapid specification upgrades across building envelopes, compressing product lifecycles and rewarding coated glass capabilities.
Growth Catalysts
- Automotive OEM expansion:Electric vehicle assembly lines across Guanajuato and Querétaro are sourcing laminated windshields in volumes that outpace traditional sedan glazing requirements.
- NOM-020-ENER enforcement:The Secretariat of Energy's updated thermal performance coefficients are mandating low-emissivity glass in new commercial construction across multiple states.
- Float furnace technology:Advanced tin bath process controls are yielding thinner, stronger substrates that reduce transportation costs for Bajío corridor fabricators.
Market Restraints
- Soda ash import dependency:Mexico lacks domestic sodium carbonate mining capacity, exposing flat glass producers to US and Turkish supply price volatility.
- Natural gas cost exposure:Float furnace operations consume methane-intensive energy inputs that track international LNG benchmark fluctuations without hedge mechanisms.
- Monterrey-Saltillo supply concentration:Over half of national float capacity sits within a 200-kilometer radius, creating geographic vulnerability to localized infrastructure disruptions.
Strategic Opportunities
- Yucatán Peninsula underpenetration:Mérida and Cancún construction markets show coated glass specification gaps that northern suppliers have not systematically targeted.
- Photovoltaic glass integration:Solar module assembly plants in Sonora and Baja California are creating captive demand for tempered solar glass that local float lines can pivot to serve.
- SEMARNAT emissions trading:Proposed carbon credit frameworks for float furnace operations would reward early methane capture investments with tradable offset revenues.
Industry Challenges
- Coating technician scarcity:Chemical vapor deposition and magnetron sputtering operations require specialized labor pools that Mexican technical institutes have not scaled to produce.
- PROFECO certification timelines:Product labeling and warranty claim approvals for imported coated glass can extend six to nine months, delaying market entry for new suppliers.
- Legacy furnace reconfiguration:Converting 1980s-era float lines to handle thin-glass or solar substrates demands capital outlays that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Flat Glass Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Annealed Glass, Tempered Glass, Laminated Glass, Coated Glass End User: Construction, Automotive, Electronics, Furniture Application: Windows, Facades, Interior Partitions, Shower Doors Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Vitro, Cardinal Glass Industries, AGC Inc., Fuyao Glass Industry Group Co. Ltd, Corning Incorporated, Saint-Gobain, Nippon Sheet Glass Co. Ltd, Sisecam, Guardian Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Flat Glass Market Trends and Innovations
Active specification rewriting across Mexican construction and automotive end-uses is compressing traditional product categories and elevating performance-certified glass variants. Three intersecting developments are reshaping competitive requirements.
Thin-glass float technology is expanding into automotive sunroof and panoramic roof applications previously dominated by thicker tempered substrates. Audi and BMW assembly plants in San Luis Potosí are qualifying 2.1-millimeter laminated constructions for weight reduction targets. This capability compression is forcing domestic fabricators to retool edge-deletion and bending furnaces.
SENER's proposed NOM-008-ENER-2024 update would tighten U-value requirements for fenestration in climate zones encompassing Mexico City, Guadalajara, and Monterrey. The regulation's draft language specifies maximum thermal transmittance coefficients that only double-silver low-emissivity coatings currently achieve. Architectural specifiers in these metropolitan zones are pre-qualifying suppliers against the anticipated standard.
Consolidated buying desks at major residential developers are replacing fragmented project-by-project glass procurement with multi-year framework agreements tied to volume commitments and performance guarantees. This channel compression is most visible in Mexico City's high-rise residential construction, where four developers now control glazing specifications for over half of new vertical square footage.
Mexico Flat Glass Market Segmentation
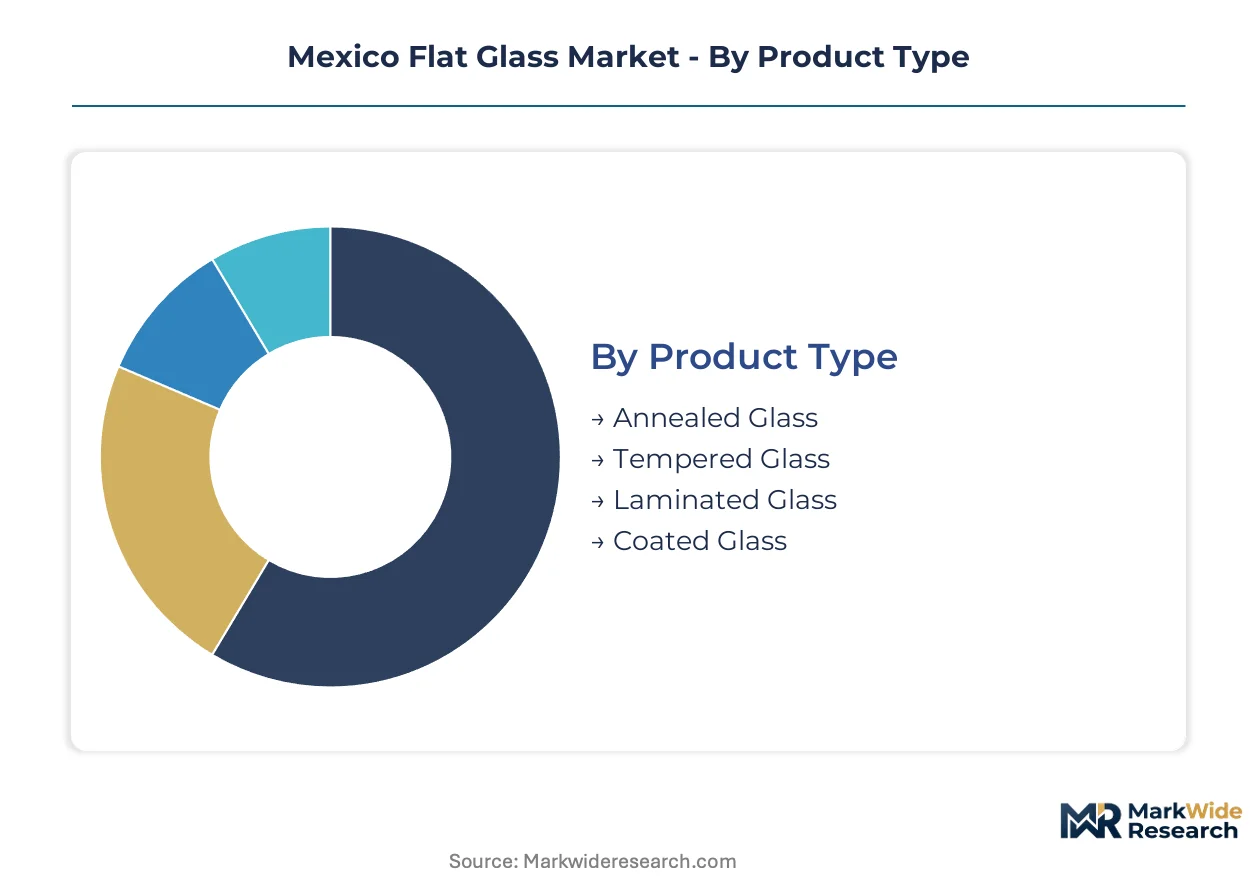
Mexico's flat glass market fragments across four distinct segmentation axes that shape procurement patterns and margin structures. Each category reflects how buyers prioritize performance specifications, regulatory compliance, or supply chain efficiency differently across the Bajío corridor and northern industrial zones.
Product Type:
Buyers in this category differentiate primarily by safety code requirements and energy performance mandates rather than base material cost.
- Tempered Glass:Produced through controlled thermal treatment that creates compressive surface stress, yielding 4-5x mechanical strength versus annealed substrates. Automotive side windows and commercial facade codes across Guanajuato and Querétaro mandate this specification, with OEM assembly plants sourcing through dedicated tempering furnaces near San Luis Potosí.
- Coated Glass:Low-emissivity and solar control variants manufactured via magnetron sputtering or chemical vapor deposition, delivering thermal transmittance coefficients below NOM-020-ENER thresholds. SENER enforcement across Mexico City, Guadalajara, and Monterrey climate zones is accelerating specification shifts from uncoated alternatives.
- Annealed Glass:Standard float-processed substrates serving interior applications and secondary fabrication feedstock, with limited structural load-bearing use due to brittle fracture patterns.
- Laminated Glass:Polyvinyl butyral interlayer constructions for windshield safety and acoustic dampening, capturing expanding share from electric vehicle panoramic roof specifications.
Tempered glass leads volumes today; coated glass is gaining share fastest.
End User:
Volume concentration varies sharply by end user, with construction commanding batch scale and automotive demanding just-in-time precision.
- Construction:Commercial and residential building envelopes drive bulk float offtake, with developers in Mexico City's high-rise residential segment consolidating procurement through multi-year framework agreements tied to NOM energy compliance.
- Automotive:OEM assembly plants across the Bajío corridor specify laminated windshields and tempered side lites, with Audi and BMW facilities in San Luis Potosí qualifying thinner 2.1-millimeter laminated constructions for weight reduction targets.
- Electronics:Display and touch panel substrates requiring ultra-thin float capabilities, with limited domestic fabrication capacity forcing import dependency.
- Furniture:Tabletops, shelving, and decorative applications utilizing tempered and annealed variants, with fragmented demand spread across small-scale fabricators.
Construction absorbs the highest tonnage; automotive commands the steepest price premiums.
Application:
Application segmentation tracks how performance requirements intensify from interior to exterior exposure conditions.
- Facades:Curtain wall and storefront systems requiring combined wind load, thermal, and optical performance, with Monterrey and Mexico City commercial towers specifying double-silver low-emissivity coatings to meet draft NOM-008-ENER-2024 U-value thresholds.
- Windows:Fenestration spanning residential vinyl frames to commercial aluminum systems, with northern Mexico solar load conditions driving solar control coating adoption.
- Interior Partitions:Tempered glass office dividers and decorative panels, with lower performance barriers to entry than exterior applications.
- Shower Doors:Safety-tempered specifications governed by PROFECO consumer protection standards for impact resistance and edge quality.
Windows dominate unit volumes; facades generate the highest value per square meter.
Distribution Channel:
Channel selection correlates with buyer scale and technical specification complexity, fragmenting between relationship-driven and transaction-based procurement.
- Direct Sales:Long-term supply contracts between float producers and major automotive OEMs or national construction developers, with volume commitments and technical service integration.
- Wholesale:Regional distributors serving mid-scale fabricators and contractors across the Bajío corridor, consolidating fragmented demand for standard thicknesses.
- Retail:Big-box home improvement channels for residential replacement and small contractor spot buying, with limited coated glass availability.
- Online:Emerging digital procurement for standard cut-to-size tempered panels, constrained by freight fragility and specification verification challenges.
Direct sales capture the largest revenue concentration; wholesale maintains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío industrial corridor anchors Mexico's flat glass demand concentration, with Guanajuato, Querétaro, and Aguascalientes generating the bulk of automotive and construction offtake. Regional production clusters align with OEM assembly expansion and NOM energy code enforcement patterns.
Mexico City Metro
Commercial high-rise construction drives coated glass specifications as SENER enforces NOM-020-ENER thermal performance thresholds across the capital's climate zone. The Secretariat of Energy's draft NOM-008-ENER-2024 update tightens U-value requirements for fenestration. Consolidated buying desks at four major residential developers now control glazing specifications for over half of new vertical square footage in the metropolitan area.
Nuevo León
Monterrey-Saltillo concentration hosts over half of national float capacity within a 200-kilometer radius, creating geographic vulnerability to localized infrastructure disruptions. PROFECO consumer protection standards govern glass product labeling and warranty claims for regional fabricators. The industrial cluster serves northern Mexico's solar load conditions through specialized solar control coating adoption.
Jalisco
Guadalajara's commercial construction market accelerates low-emissivity glass procurement ahead of anticipated NOM-008-ENER-2024 enforcement. SENER's building envelope efficiency mandates directly specify coated glass performance coefficients for new developments. Regional distributors consolidate fragmented demand from mid-scale fabricators across the metropolitan construction zone.
Bajío Region
Automotive OEM expansion across Guanajuato and Querétaro sources laminated windshields in volumes outpacing traditional sedan glazing requirements. Audi and BMW assembly plants in San Luis Potosí qualify thinner 2.1-millimeter laminated constructions for weight reduction targets. Float-to-fabrication footprints dominate automotive supply contracts through integrated tempering and laminating capacity.
Northern Border States
Sonora and Baja California solar module assembly plants create captive demand for tempered solar glass that local float lines can pivot to serve. SEMARNAT regulates emissions from float furnace operations across the border industrial zone. Proposed carbon credit frameworks for furnace operations would reward early methane capture investments with tradable offset revenues.
Mexico Flat Glass Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit float lines for thin-glass and solar substrates. The vendor base stratifies between integrated float-to-fabrication operators, specialized coating specialists, and regional tempering-focused fabricators. Three archetypes define competitive positioning: scale-driven integrated producers, technology-licensed coating specialists, and automotive-dedicated tempering operators. M&A activity and furnace technology licensing represent the primary competitive vectors reshaping market share.
Within the integrated producer tier, Vitro anchors Mexican market presence through captive float and downstream fabrication assets. Guardian Industries occupies a position among automotive-dedicated suppliers serving Tier 1 relationships across the Bajío corridor. Cardinal Glass Industries exemplifies the coating-specialist archetype, with low-emissivity product lines tailored to northern Mexico solar conditions. These three entities represent distinct strategic postures without implying specific market share figures or operational claims.
| Leading Market Players |
|---|
| Vitro |
| Cardinal Glass Industries |
| AGC Inc. |
| Fuyao Glass Industry Group Co. Ltd |
| Corning Incorporated |
| Saint-Gobain |
| Nippon Sheet Glass Co. Ltd |
| Sisecam |
| Guardian Industries |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between NOM-020-ENER certified low-emissivity glass and standard annealed substrates manifests in both margin structures and procurement channel configurations across Mexico. Premium coated products command dedicated direct-sales relationships with Bajío automotive OEMs and Mexico City commercial developers, while commodity tempered glass flows through wholesale distributors serving fragmented regional fabricators.
Pricing Analysis
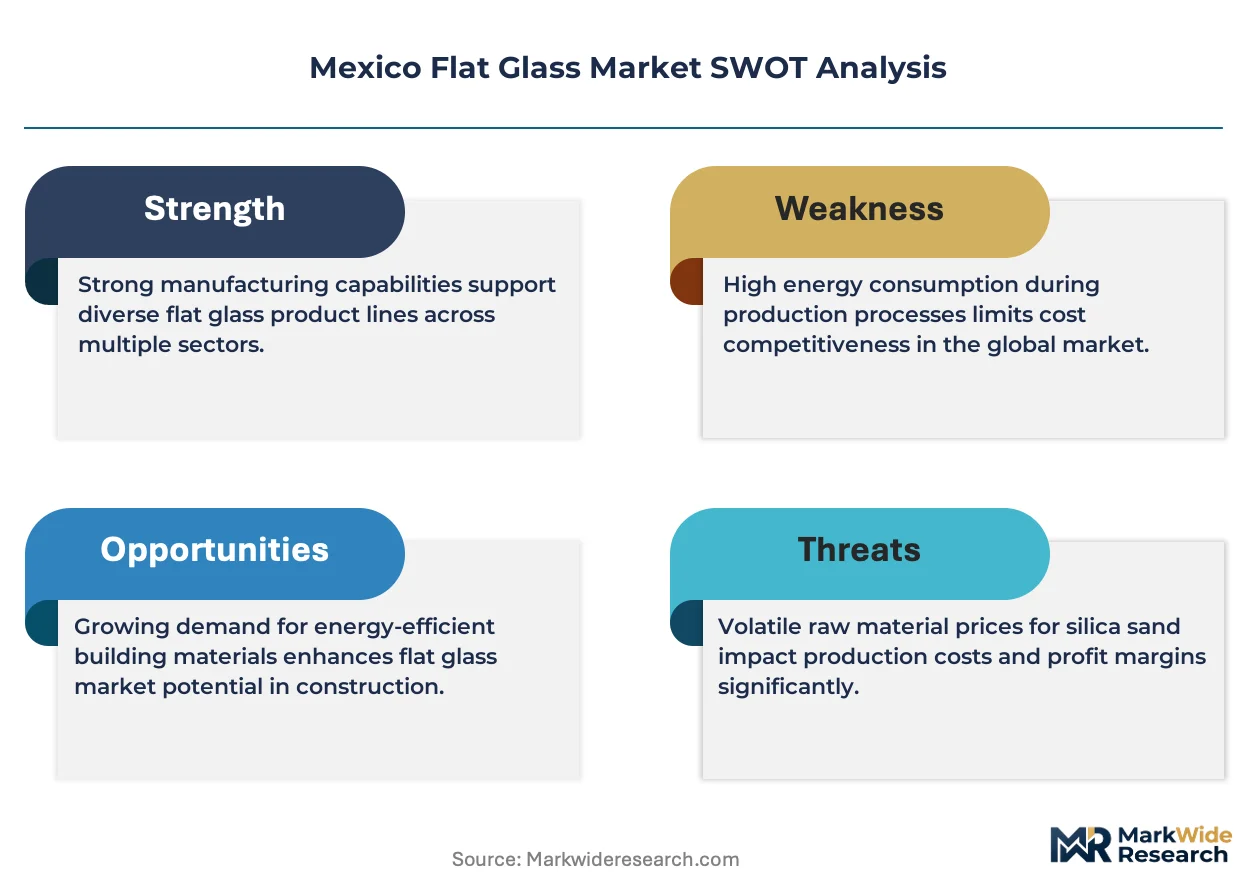
Natural gas and soda ash cost pass-through mechanisms dominate pricing formation for Mexican float producers, with methane-intensive furnace operations exposing margins to international LNG benchmark fluctuations. Three-tier pricing structure across premium low-emissivity, standard tempered, and economy annealed levels reflects certification grade and volume scale differentiation. Pricing pressure stems from Turkish and US soda ash import volatility, with mid-scale fabricators most price-sensitive due to limited hedge mechanisms against raw material spikes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand from Guanajuato and Querétaro assembly plants, while wholesale distributors consolidate fragmented construction offtake across the Bajío corridor. Geographic supply concentration centers on Monterrey-Saltillo for float capacity and northern Mexico for coating operations, drawing from US and Turkish soda ash, domestic silica sand, and imported natural gas. Single-source vulnerability to Monterrey-Saltillo infrastructure disruptions represents the dominant structural risk, with distribution running through integrated float-to-fabrication operators and regional tempering specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's flat glass market offers margin expansion through thin-glass qualification for automotive weight-reduction targets and premium low-emissivity specification shifts ahead of NOM-008-ENER-2024 enforcement. Coating capability scarcity and consolidated buyer desk formation create pricing power for certified suppliers.
For Market Incumbents: Anticipate coating technician scarcity by investing in captive training partnerships with Guanajuato technical institutes before NOM-008-ENER-2024 tightens U-value requirements. Retrofit legacy float lines for 2.1-millimeter laminated automotive substrates to defend against thin-glass import competition from specialized Asian suppliers. Backward integration into natural gas storage or long-term pipeline contracts reduces cost volatility exposure.
For New Entrants and Emerging Players: Regional distributors serving Mérida and Cancún construction markets represent the most penetrable channel gap, with coated glass specification lags creating white-space opportunity ahead of SENER enforcement expansion. Target photovoltaic glass integration with Sonora solar module assembly plants through tempered solar substrate qualification. A go-to-market angle anchored in PROFECO certification acceleration—compressing six-to-nine-month labeling timelines—differentiates against established import suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale tempering operators lack capital to convert 1980s-era float lines for thin-glass or solar substrates. Long-term viability favors integrated float-to-fabrication footprints with captive coating capability and Bajío automotive supply contracts. The signal to watch is SEMARNAT emissions trading framework finalization, which would revalue early methane capture investments across the Monterrey-Saltillo cluster.
| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Glass Float Line Retrofit | Enables 2.1-millimeter laminated qualification for Audi and BMW weight targets. |
| Coating Technician Training Partnership | Addresses magnetron sputtering labor scarcity before NOM-008-ENER-2024 enforcement. |
| Yucatán Distribution Channel Buildout | Captures underpenetrated Mérida and Cancún construction specification gaps. |
| Photovoltaic Glass Pivot | Serves captive Sonora and Baja California solar module assembly demand. |
| Methane Capture Investment | Positions for SEMARNAT carbon credit revenues across Monterrey-Saltillo operations. |
Research Methodology
Bottom-up automotive and construction demand modeling reconciled against top-down float capacity and coating output tracking forms the analytical core of this study. Primary interviews with float plant managers, automotive Tier 1 procurement leads, commercial construction developers, SENER regulatory officials, and regional wholesale distributors combined with secondary validation from SEC filings of multinational glass producers, Mexican customs trade data, NOM regulatory gazettes, and automotive production databases. Triangulation across stakeholder perspectives and data sources ensures cross-verified market sizing.
Input-output matrix framing connects raw material flows—soda ash, natural gas, silica sand—to finished glass output across product categories and end-use applications over the projection horizon. Segmentation dimensions modeled include product type, end user, application, and distribution channel, with CAGRs derived from elasticity analysis against automotive production forecasts and commercial construction permitting data. Forecast inputs incorporate NOM-020-ENER enforcement timelines and thin-glass automotive qualification trajectories.
Revisions become necessary when SEMARNAT emissions regulations, NOM energy code updates, or natural gas price shocks materialize outside modeled scenarios. Forecasts reflect assumptions about coating technology adoption rates and automotive OEM sourcing consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Coated Glass Market
Glass
North America Glass Insulators Market
Glass
Glass Lens Market
Glass
Glass Balustrade Lamination Market
Glass
Glass Like Carbon Market
Glass
Shatterproof Glass Market
Glass
Global Flat Glass Market
Glass
Global Scratch Resistant Glass Market
Glass
Latin America Flat Glass Market
Glass
North America Flat Glass Market
Glass
India Flat Glass Market
Glass
Foam Glass Market
Glass
Glass Mat Market
Glass
Silica Sand for Glass Making Market
Glass
Asia Pacific Flexible Glass Market
Glass
Glass Substrate Market