
 Australia Engineering Plastics Market | 2026-2036
Australia Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Engineering Plastics Market Insights
Technical service subscriptions for material qualification and regulatory filing support is rebalancing how engineering plastics are sold in Australia. BASF Australia Limited leverages its Ludwigshafen technical backbone to sustain high-touch polymer specification services for automotive OEMs. Covestro Australia Pty Ltd anchors its position through direct sales teams that specialize in optical-grade polycarbonate for medical device manufacturers. DuPont Australia Pty Ltd competes by controlling access to Zytel nylon compounds with localized inventory buffers in Sydney and Melbourne.
Engineering plastics encompass thermoplastic polymers formulated to withstand mechanical load, thermal stress, and chemical exposure beyond commodity-grade capabilities, with melt temperatures typically ranging from 200°C to 350°C and tensile strengths exceeding 60 MPa. These materials serve as metal substitutes in precision components where weight reduction, corrosion resistance, or design freedom justify premium unit economics. ABS and polycarbonate dominate volume flows into automotive components and consumer goods, where cost-performance thresholds favor established injection molding infrastructure. Nylon and PBT capture higher-margin positions in electrical insulation and under-hood automotive applications, where thermal aging resistance and dimensional stability command specification premiums from Tier-1 suppliers and OEMs.
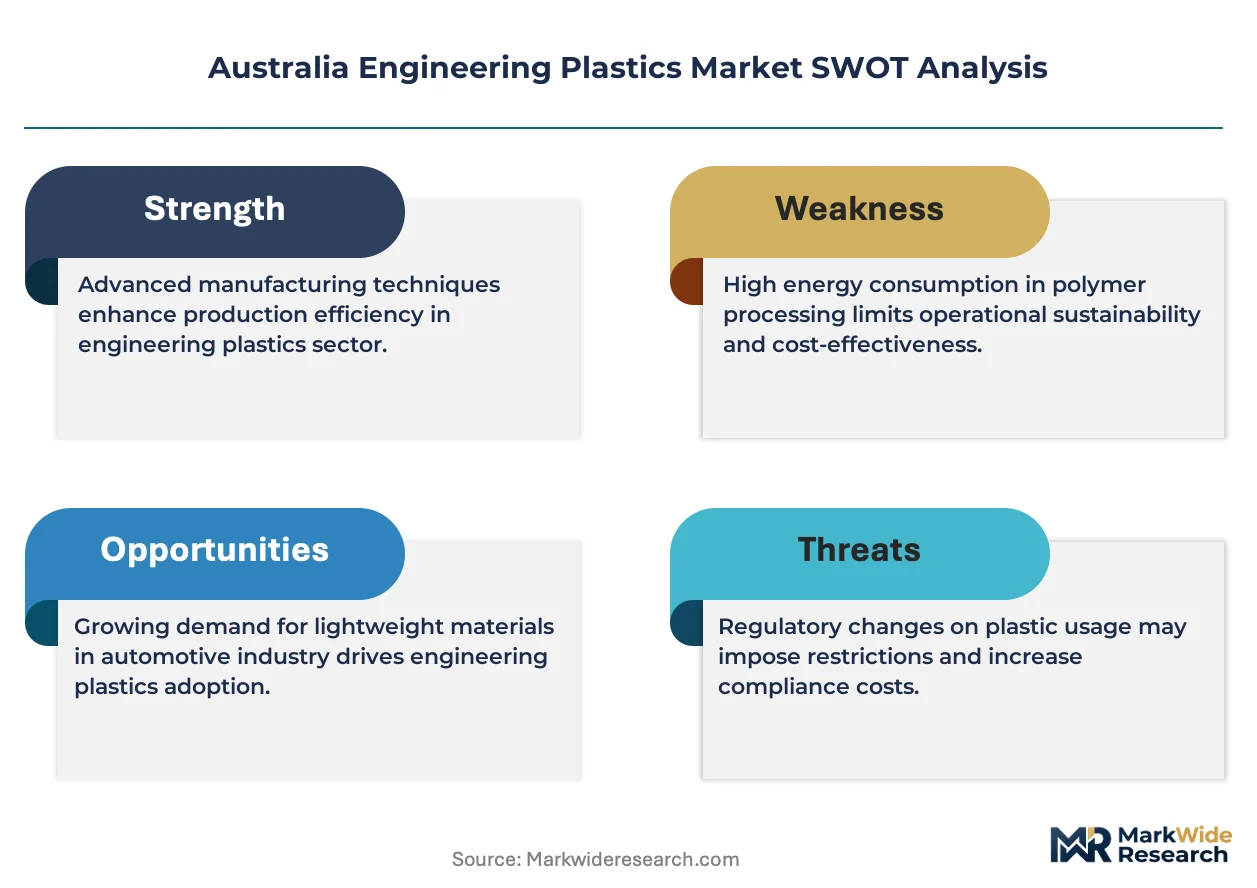
TGA standards for implantable device polymers intersect with AS/NZS electrical safety codes and state-level EPA regulations on industrial emissions from compounding operations, creating a multi-layer compliance burden that favors suppliers with in-house testing laboratories. The Australian Competition and Consumer Commission (ACCC) monitors polymer supply chain representations, particularly around recycled content claims in engineering-grade formulations. Stakeholders must track how TGA's evolving biocompatibility frameworks and Victoria's plastics recycling targets will reshape material qualification timelines and compounder certification requirements.
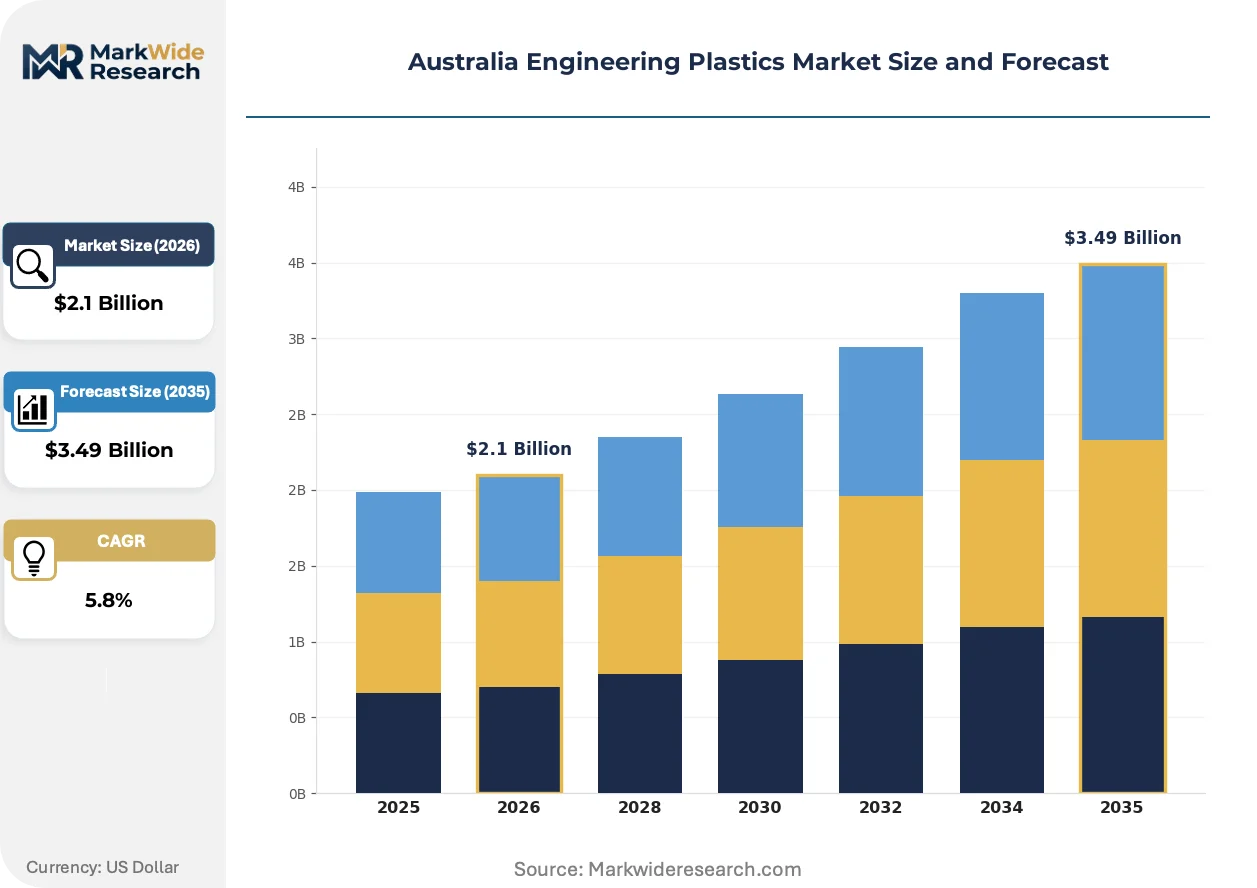
Market Dynamics
TGA's tightening biocompatibility frameworks for implant-grade polymers is concentrating R&D investment toward medical-grade PEEK and PSU formulations, while automotive material substitution programs across Victoria and New South Wales pull compounder technical resources toward under-hood metal replacement applications.
Growth Catalysts
- Medical device regulation:TGA's evolving biocompatibility requirements for implantable polymers redirect compounder development toward high-margin medical-grade formulations, creating specification premiums for qualified suppliers.
- Automotive lightweighting:Victoria and New South Wales automotive Tier-1 suppliers are accelerating nylon and PBT substitution for metal under-hood components to meet OEM weight reduction targets.
- Advanced manufacturing clustering:Melbourne's corridor concentration of medical device OEMs and technical service laboratories shortens material qualification cycles and deepens compounder-customer collaboration.
Market Restraints
- Petrochemical feedstock volatility:Engineering plastics production depends on benzene and caprolactam derivatives whose price swings compress compounder margins and destabilize long-term supply agreements.
- Asia-Pacific supply concentration:Specialty polymer resin production concentrates in China and South Korea, exposing Australian compounders to shipping cost spikes and extended lead times.
- Recycled content technical ceiling:Post-consumer recycled feedstocks degrade melt flow and mechanical properties, limiting their penetration beyond non-structural automotive and consumer goods applications.
Strategic Opportunities
- Queensland medical device expansion:Brisbane's emerging health technology precinct offers underpenetrated demand for implant-grade polymer compounding and localized regulatory filing support.
- Victoria circular economy mandates:State-level plastics recycling targets create regulatory tailwinds for compounders developing chemically recycled and bio-based engineering polymer formulations.
- Technical service digitization:Virtual material qualification platforms and remote rheological testing are compressing specification timelines for resource-sector OEMs in Western Australia.
Industry Challenges
- Polymer characterization expertise shortage:Melbourne and Sydney laboratories face acute competition for analytical chemists skilled in differential scanning calorimetry and dynamic mechanical analysis for medical-grade certification.
- Multi-jurisdiction compliance stacking:AS/NZS electrical safety codes, TGA biocompatibility frameworks, and state EPA emissions regulations create overlapping certification timelines that strain compounder quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Engineering Plastics Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, PC, Nylon, PBT Application: Automotive Components, Electrical Insulation, Consumer Goods, Medical Devices End User: OEMs, Tier-1 Suppliers, Retailers, Distributors Distribution Channel: Online Retail, Direct Sales, Wholesalers, Others |
| Companies Covered | Solvay Australia Pty Ltd, Covestro Australia Pty Ltd, Dow Chemical Australia Pty Ltd, BASF Australia Limited, Huntsman Corporation Australia, DuPont Australia Pty Ltd, Asahi Kasei Plastics Australia Pty Ltd, Victrex Australia Pty Ltd, Celanese Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Engineering Plastics Market Trends and Innovations
Material science convergence with digital manufacturing tools is compressing product development cycles across Australia's engineering plastics value chain, while regulatory complexity elevates the strategic value of in-house testing and technical service capabilities.
High-performance polyaryletherketones are absorbing specification share from traditional implant metals in spinal and orthopedic applications. Melbourne medical device OEMs are qualifying PEEK compounds for load-bearing implants at accelerated pace. This absorption is compressing the addressable market for cobalt-chrome and titanium suppliers in Australia's orthopedic supply chain.
TGA's alignment with ISO 10993 biocompatibility testing protocols is elevating documentation burdens for compounders serving implantable device manufacturers. The industrial consequence is extended material qualification timelines and elevated barriers to entry for non-specialized suppliers. Medical-grade PEEK and PSU formulations face the most intensive scrutiny, with compounders investing in captive toxicology testing to maintain specification access.
Subscription-based technical service contracts are displacing transactional resin sales in automotive and medical segments. Tier-1 suppliers in Victoria now procure material qualification, regulatory filing support, and inventory management as bundled services rather than discrete purchases. This behavioral shift concentrates procurement leverage with compounders maintaining Sydney and Melbourne technical laboratories and localized inventory buffers.
Australia Engineering Plastics Market Segmentation
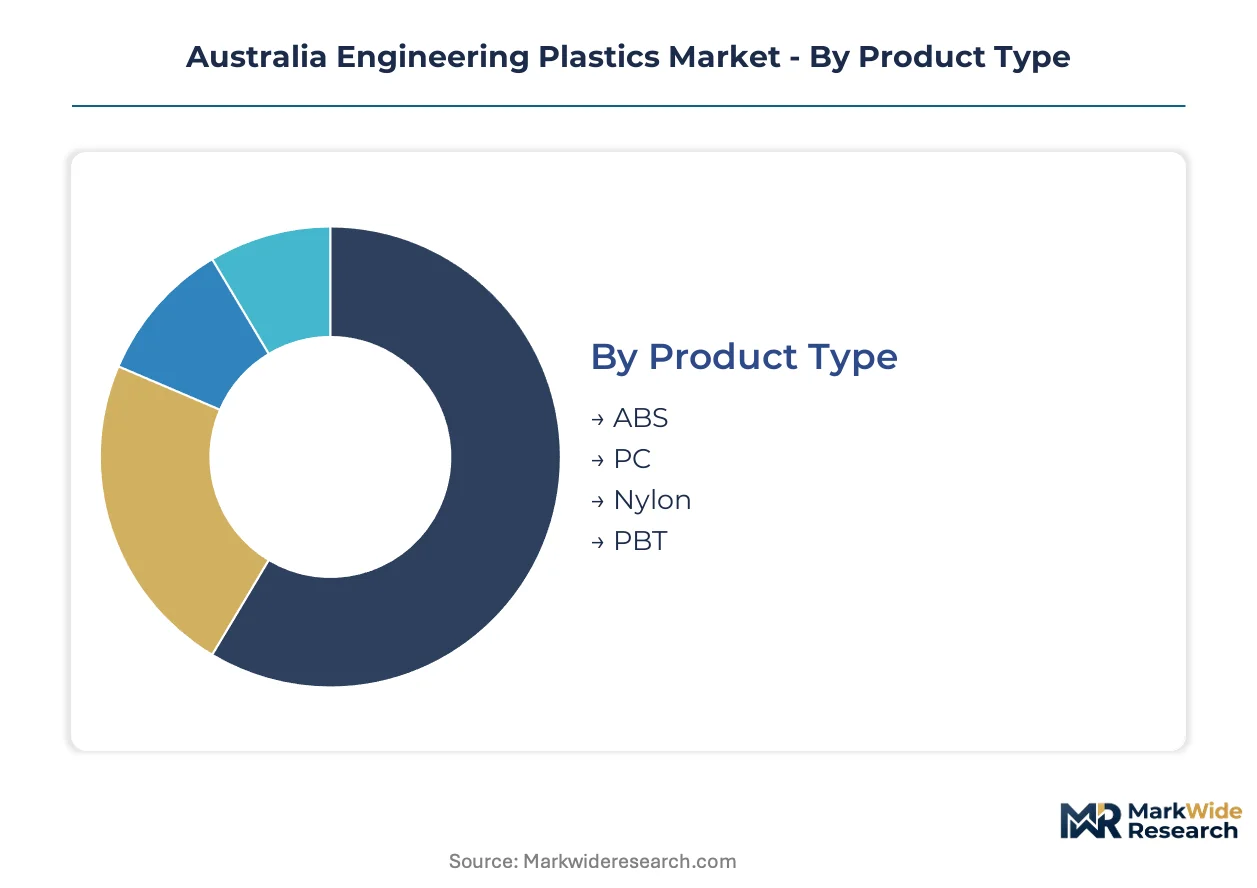
Engineering plastics procurement in Australia follows distinct specification logics across product chemistry, application stress requirements, and channel service intensity. Each segmentation dimension carries different margin structures and regulatory compliance burdens that reshape supplier competitive positioning.
Product Type:
Cost-performance thresholds dominate material selection, with thermal and mechanical load requirements filtering options before regulatory considerations enter the qualification process.
- Nylon:Polyamide formulations deliver thermal aging resistance and dimensional stability under sustained mechanical load. Demand concentrates in Victoria and New South Wales automotive under-hood applications where OEM weight reduction targets accelerate metal substitution programs.
- PC:Polycarbonate offers optical clarity paired with impact resistance and heat deflection temperatures exceeding 140°C. Melbourne medical device OEMs specify optical-grade grades for surgical instrument housings, with TGA biocompatibility frameworks extending qualification timelines for implant-adjacent applications.
- ABS:Acrylonitrile-butadiene-styrene copolymers balance processability with surface aesthetics for consumer-facing components.
- PBT:Polybutylene terephthalate provides electrical insulation performance with low moisture absorption for connector and switchgear applications.
Nylon leads on scale through automotive volume; PC leads on momentum through medical device specification premiums.
Application:
Application segmentation maps directly to regulatory jurisdiction intensity, with medical and automotive segments carrying the heaviest compliance documentation requirements.
- Medical Devices:Implant-grade polymer applications demand ISO 10993-aligned toxicology testing and TGA biocompatibility certification. Melbourne's advanced manufacturing corridor concentrates demand for PEEK and PSU formulations in spinal and orthopedic load-bearing components.
- Automotive Components:Under-hood metal replacement drives specification of heat-stabilized nylon and PBT compounds across Victoria and New South Wales Tier-1 supplier networks. OEM weight targets pull compounder technical resources toward thermal management and vibration resistance validation.
- Electrical Insulation:AS/NZS electrical safety codes govern material selection for switchgear, connectors, and housing applications in industrial and residential electrical systems.
- Consumer Goods:Cost-driven applications favor ABS and PC blends where established injection molding infrastructure and shorter qualification cycles support rapid product turnover.
Automotive Components leads on scale; Medical Devices leads on margin expansion through regulatory barriers.
End User:
Procurement sophistication varies sharply across end user categories, with technical service requirements scaling from transactional resin sales to embedded material qualification partnerships.
- Tier-1 Suppliers:Victoria and New South Wales automotive component manufacturers now procure bundled technical services including material qualification, regulatory filing support, and inventory management rather than discrete resin purchases.
- OEMs:Medical device and automotive original equipment manufacturers specify polymer grades directly, requiring compounders to maintain captive testing laboratories for accelerated qualification cycles.
- Distributors:Channel partners aggregate demand from smaller processors and compounders, carrying inventory risk in exchange for volume aggregation.
- Retailers:Consumer goods supply chains source through distribution networks with minimal technical service attachment.
Tier-1 Suppliers leads on technical service contract value; OEMs leads on direct specification control.
Distribution Channel:
Channel selection reflects customer scale and service intensity requirements, with direct engagement dominating high-specification medical and automotive segments.
- Direct Sales:Specialized sales teams deliver optical-grade polycarbonate and medical-grade PEEK formulations to Melbourne medical device OEMs, with localized inventory buffers in Sydney and Melbourne supporting just-in-time delivery commitments.
- Online Retail:Digital platforms serve small-to-mid processors with standard grades, compressing procurement timelines for non-critical applications.
- Wholesalers:Volume aggregation channels support consumer goods and industrial applications with established logistics networks.
- Others:Agent and broker networks fill geographic coverage gaps in Western Australia and Queensland.
Direct Sales leads on margin capture; Online Retail leads on geographic expansion velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping engineering plastics production geography as compounders migrate toward jurisdictions offering streamlined biocompatibility certification and lower emissions compliance costs. Australia captures investment flows from medical-grade specialists seeking proximity to TGA-aligned testing protocols without European REACH overhead.
New South Wales
Automotive Tier-1 suppliers in Western Sydney and Newcastle accelerate nylon substitution for metal under-hood components. The state's Protection of the Environment Operations Act governs industrial emissions from compounding facilities. Parramatta's technical service corridor concentrates BASF and DuPont inventory buffers serving just-in-time automotive contracts.
Victoria
Melbourne's advanced manufacturing precinct drives specification demand for medical-grade PEEK and PSU in spinal implant applications. The state's circular economy plastics recycling targets redirect compounder R&D toward chemically recycled formulations. Clayton and Dandenong host captive toxicology laboratories serving TGA biocompatibility documentation requirements.
Queensland
Brisbane's emerging health technology precinct offers underpenetrated demand for implant-grade polymer compounding. Queensland's waste levy framework incentivizes bio-based feedstock development. Herston's medical research cluster attracts compounders establishing localized regulatory filing support capabilities.
Western Australia
Resource-sector OEMs in Perth specify engineering plastics for mining equipment corrosion resistance. The state's environmental protection regulations govern industrial chemical handling at compounding operations. Kwinana's industrial zone supports remote rheological testing platforms compressing material qualification timelines.
South Australia
Adelaide's defense manufacturing base specifies high-performance polymers for aerospace component applications. The state's EPA mandates emissions monitoring at polymer processing facilities. Edinburgh Parks defense precinct concentrates demand for heat-stabilized compounds meeting AS/NZS electrical safety codes.
Australia Engineering Plastics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational compounders controlling premium medical-grade formulations while regional distributors aggregate volume in automotive and consumer applications. Market structure concentrates around three archetypes: integrated petrochemical majors with captive resin supply, specialized medical-grade compounders with TGA-certified laboratories, and technical service distributors bundling inventory management with regulatory filing support. Competitive dynamics center on M&A activity consolidating regional distribution networks and strategic partnerships linking compounders to Melbourne medical device OEMs for accelerated qualification cycles.
Among European-headquartered majors, Solvay Australia Pty Ltd and Covestro Australia Pty Ltd anchor the premium-tier medical and optical-grade segments, while BASF Australia Limited represents the integrated petrochemical archetype with Ludwigshafen-backed technical service infrastructure. Victrex Australia Pty Ltd exemplifies the specialized high-performance polymer compounder model, occupying a position defined by PEEK formulation expertise and implant-grade certification depth. These three entities collectively illustrate how competitive positioning in Australia's engineering plastics market depends on regulatory filing bandwidth and captive testing laboratory access rather than resin production scale alone.
| Leading Market Players |
|---|
| Solvay Australia Pty Ltd |
| Covestro Australia Pty Ltd |
| Dow Chemical Australia Pty Ltd |
| BASF Australia Limited |
| Huntsman Corporation Australia |
| DuPont Australia Pty Ltd |
| Asahi Kasei Plastics Australia Pty Ltd |
| Victrex Australia Pty Ltd |
| Celanese Australia Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive suppliers in Victoria and New South Wales procurement concentration is compressing pricing power toward contract-based technical service bundles rather than transactional resin sales. TGA biocompatibility certification premiums for medical-grade PEEK and PSU formulations sustain margin separation from commodity-grade compounds.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for specialty polymer resins entering Australian compounder operations. Three-tier pricing structure across implant-grade certified, automotive-specified, and standard industrial levels differentiates compounder offerings. Pricing pressure stems from benzene and caprolactam derivative volatility compressing compounder margins. Consumer goods processors exhibit highest price sensitivity due to established injection molding infrastructure and rapid product turnover cycles.
Supply Chain Analysis
Engineering plastics feedstock supply rests on Chinese and South Korean petrochemical complexes for specialty resin production. Australian compounders draw from benzene derivatives, caprolactam monomers, and bisphenol-A intermediates as critical inputs. Single-source vulnerability concentrates in Asia-Pacific shipping lanes exposing Melbourne and Sydney inventory buffers to extended lead time spikes. Distribution runs through direct sales teams for medical device OEMs and technical service distributors for automotive Tier-1 networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's engineering plastics market functions as a geographic-arbitrage destination for medical-grade compounders escaping European REACH compliance overhead while maintaining TGA-aligned certification pathways. State-level circular economy mandates in Victoria create regulatory differentiation against Asian supply bases lacking equivalent bio-based feedstock incentives.
For Market Incumbents: Anchor technical service capabilities through captive toxicology laboratories in Melbourne's advanced manufacturing corridor to defend against emerging specialized compounders targeting TGA certification gaps. Deepen inventory buffers in Sydney and Parramatta to secure just-in-time automotive contracts against shipping volatility from Asian resin suppliers. Certification investment in ISO 10993-aligned testing protocols represents the critical defensive lever against margin compression.
For New Entrants and Emerging Players: Virtual material qualification platforms offer technology-first wedge into Western Australia resource-sector OEM procurement where remote rheological testing compresses specification timelines. Queensland's underpenetrated Brisbane health technology precinct presents the most penetrable geography for implant-grade polymer compounding with localized regulatory filing support. Direct technical service partnerships with Herston medical research clusters provide the essential go-to-market angle.
For Investors and Strategic Acquirers: Specialized medical-grade compounders with TGA-certified laboratories are the most active acquirer targets in this space as multinational petrochemical majors seek specification access without organic certification buildout. Long-term viability centers on compounders controlling captive testing infrastructure rather than resin production scale alone. Watch TGA biocompatibility framework alignment with ISO 10993 protocols as the inflection indicator for qualification timeline extension and barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Toxicology Laboratory Investment | TGA biocompatibility certification accelerates qualification cycles for Melbourne medical device OEMs. |
| Technical Service Subscription Bundling | Victoria Tier-1 suppliers now procure material qualification and inventory management as integrated services. |
| Chemically Recycled Feedstock Development | Victoria circular economy mandates redirect R&D toward bio-based engineering polymer formulations. |
| Queensland Regulatory Filing Support Expansion | Brisbane health technology precinct offers underpenetrated demand for implant-grade compounding localization. |
| Remote Rheological Testing Platform Deployment | Western Australia resource-sector OEMs compress material qualification timelines through virtual platforms. |
Research Methodology
Direct dialogue with compounder technical directors, automotive Tier-1 procurement managers, medical device OEM material scientists, and TGA regulatory consultants grounded qualitative insights across the value chain. Secondary validation drew from Australian Bureau of Statistics trade data, TGA regulatory filings, ACCC consumer protection reports, and state EPA emissions disclosures. Bottom-up segmentation modeling triangulated against top-down petrochemical feedstock flow analysis.
Segmented outputs across product chemistry tiers, application stress requirements, end-user procurement sophistication levels, and state-level regulatory clusters structured the analytical framework throughout the projection horizon. CAGRs derived from historical resin import trajectories and medical device production indices. Forecast inputs incorporated TGA biocompatibility timeline evolution and Victoria circular economy mandate implementation pacing.
The model holds under stable Asia-Pacific shipping lane conditions and consistent TGA-ISO alignment; deviation in petrochemical feedstock volatility or state recycling target acceleration would shift compounder margin assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market