
 UK Industrial Insulation Market | 2026-2036
UK Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Industrial Insulation Market Insights
Scotland's Grangemouth petrochemical complex is reshaping procurement patterns for high-temperature insulation across the UK. Rockwool International A/S leverages its stone wool manufacturing base in Bridgend to sustain supply security for power generation clients. Saint-Gobain S.A. dominates specification-driven segments through its ISOVER brand's technical specification depth. Knauf Insulation Limited anchors residential-adjacent industrial retrofits with its Glass Mineral Wool product lines.
UK industrial insulation encompasses engineered thermal barrier systems—typically mineral wool batts rated to 750°C, cellular glass blocks with closed-cell structures, or aerogel blankets at 10-20 mm equivalent thickness—deployed to reduce energy loss, prevent corrosion under insulation, and protect personnel from hot surfaces. Mineral wool retains the largest installed base across power plants and chemical processing, while aerogel commands premium positioning in space-constrained retrofit projects where thermal performance per unit thickness determines feasibility. Cellular glass leads in cryogenic and below-ambient applications across petrochemical facilities due to its zero water absorption and dimensional stability under thermal cycling.
The Health and Safety Executive enforces COMAH regulations that mandate surface temperature limits and energy efficiency benchmarks at major hazard sites, directly specifying insulation performance tiers. Building Regulations Part L and the UK's Net Zero Strategy impose escalating thermal efficiency standards that filter into industrial building envelopes and process equipment. Stakeholders must monitor the trajectory of PAS 2038 retrofit standards and the Carbon Border Adjustment Mechanism's indirect pressure on energy-intensive installations to anticipate specification shifts before they harden into procurement mandates.
Market Dynamics
The UK's Net Zero Strategy and Building Regulations Part L are forcing simultaneous upgrades across process equipment and building envelopes, compressing replacement cycles that previously ran 15-20 years.
Growth Catalysts
- COMAH surface temperature mandates:The Health and Safety Executive enforces strict thermal limits at major hazard sites, mandating insulation performance tiers that accelerate material replacement schedules.
- Humber industrial cluster expansion:England's largest refining and chemical concentration is driving concentrated demand for high-temperature mineral wool systems in continuous process applications.
- Aerogel blanket adoption:Space-constrained retrofit projects in aging power infrastructure are specifying 10-20mm equivalent thickness aerogel where conventional materials cannot fit.
Market Restraints
- Basalt and slag input volatility:Stone wool manufacturers face raw material cost swings tied to steel production cycles, compressing margin buffers on fixed-price contracts.
- Cellular glass supply concentration:Cryogenic-grade cellular glass production centers on a limited number of specialized European facilities, creating lead time vulnerability for UK petrochemical clients.
- Silica aerogel handling complexity:Supercritical drying requirements and dust containment protocols limit in-house installation capabilities, constraining uptake outside specialist contractor networks.
Strategic Opportunities
- Scotland's Grangemouth transition:The petrochemical hub's decarbonization roadmap creates demand for cryogenic and high-temperature insulation in hydrogen and carbon capture retrofit applications.
- PAS 2038 retrofit standards:The emerging framework for non-domestic building upgrades will mandate thermal performance documentation, expanding specification services and measurement-verification contracts.
- Digital twin integration:Combining thermal imaging with building information modeling enables predictive maintenance contracts that bundle insulation condition monitoring with replacement scheduling.
Industry Challenges
- Specialized installer certification gaps:Complex aerogel and cellular glass applications require trained crews that remain scarce outside major industrial centers, extending project timelines.
- Legacy asbestos identification:Pre-2000 industrial sites demand costly survey and removal protocols before insulation replacement, adding 15-25% to retrofit project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Industrial Insulation Market |
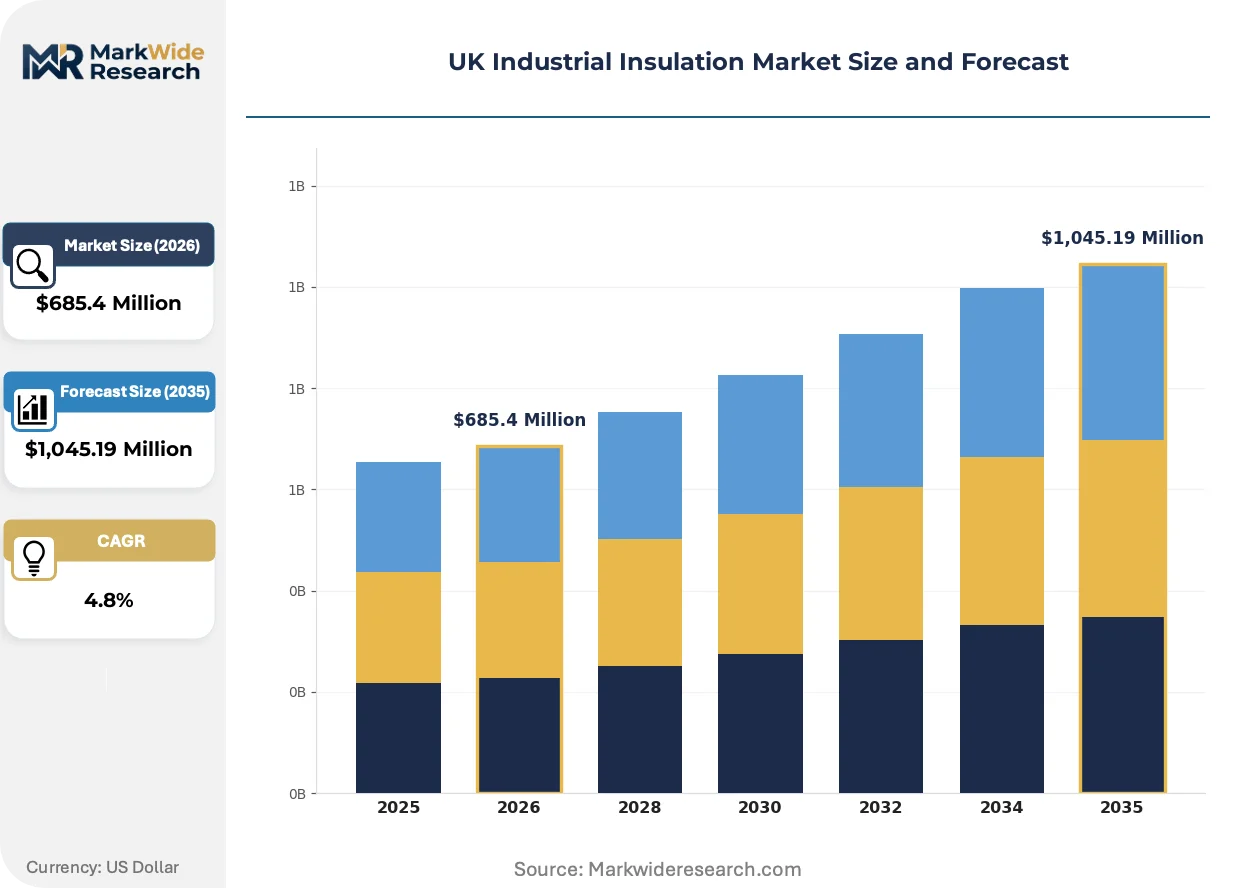
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Wool, Cellular Glass, Foamed Polymers, Calcium Silicate, Aerogel Application: Power Plants, Chemical Processing, Petrochemical Facilities, Food Manufacturing, Pulp & Paper Installation Type: New Construction, Retrofit Projects, Maintenance, Turnaround Shutdowns End User: Manufacturing Plants, Energy Providers, Water Treatment Facilities, HVAC Contractors |
| Companies Covered | Rockwool International A/S, Saint-Gobain S.A., Knauf Insulation Limited, Owens Corning Insulating Systems LLC, Johns Manville Corporation, Kingspan Group plc, Aspen Aerogels Incorporated, Armacell International S.A., Promat International N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Industrial Insulation Market Trends and Innovations
Material science advances and regulatory tightening are compressing the viable lifecycle of conventional insulation systems while opening premium positioning for performance-optimized alternatives.
Multilayer aerogel composite blankets rated to 650°C are rendering obsolete thick mineral wool installations in turbine and exhaust ducting where space constraints previously dictated compromise on thermal performance. Power generation operators in Scotland and northern England are specifying these systems for 2030 compliance deadlines. The shift is compressing contractor pricing power on conventional high-temperature materials.
The UK's Carbon Border Adjustment Mechanism implementation timeline is pressuring energy-intensive installations to document embodied carbon in insulation procurement. Industrial buyers in chemicals and refining are now requiring Environmental Product Declarations for mineral wool and cellular glass systems. This is elevating suppliers with verified lifecycle data while marginalizing commodity producers.
Engineering-procurement-construction firms are consolidating insulation specification authority under centralized technical teams, displacing site-level contractor autonomy on material selection. Tier-one EPCs operating in the Humber and Teesside clusters are mandating approved vendor lists with pre-negotiated pricing. This concentration is compressing regional distributor margins while favoring manufacturers with direct specification relationships.
UK Industrial Insulation Market Segmentation
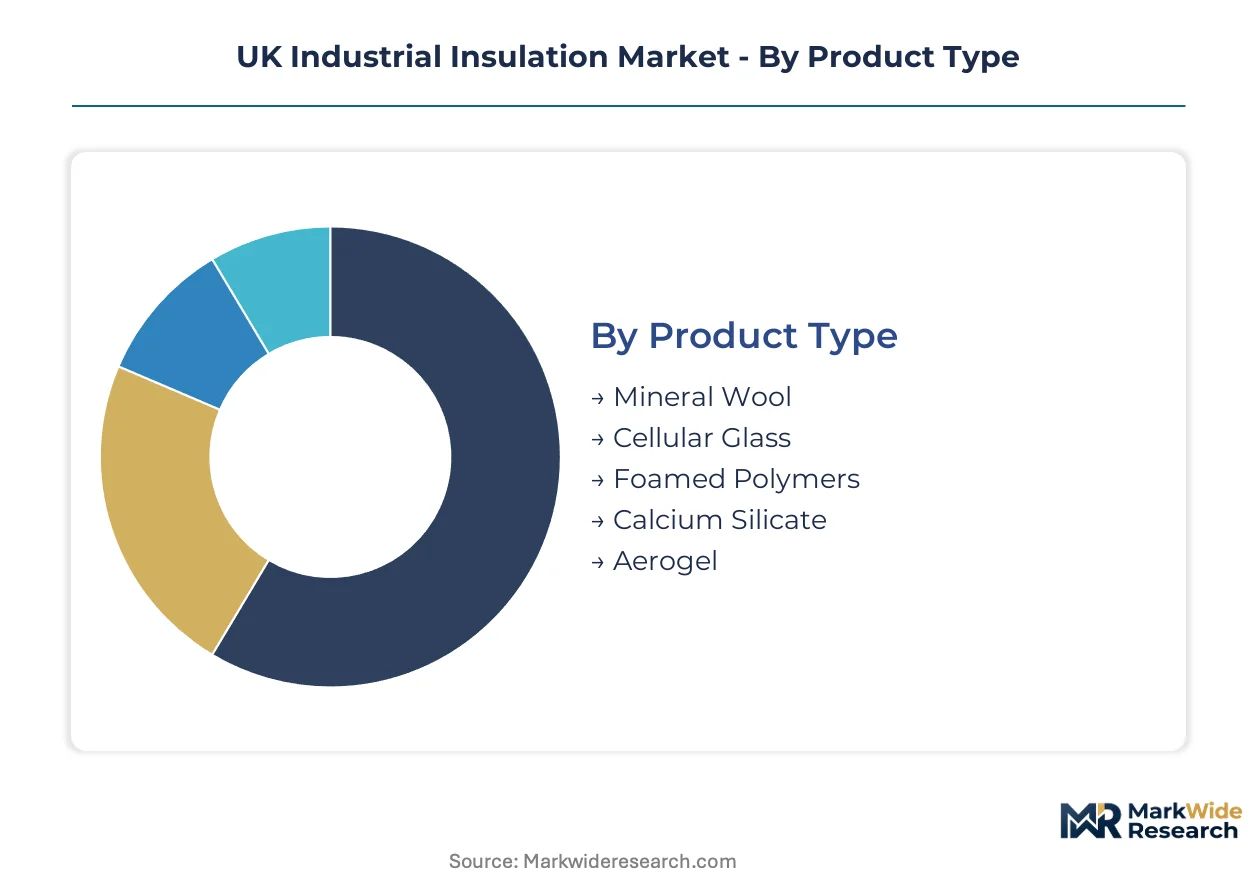
Material selection and installation method determine lifecycle cost and regulatory compliance trajectories across UK industrial sites. Specification authority increasingly concentrates with EPC firms and asset owners who bundle insulation procurement into broader maintenance contracts.
Product Type:
After-sales service intensity varies sharply by material chemistry, with aerogel and cellular glass demanding specialist contractor networks for proper handling and warranty validation.
- Mineral Wool:Stone wool and glass wool batts rated to 750°C dominate power plant boiler insulation and chemical processing vessel lagging. Demand concentrates in England's Humber cluster where continuous process operations require thermal cycling resistance. The Health and Safety Executive's COMAH surface temperature mandates sustain replacement schedules.
- Cellular Glass:Closed-cell rigid blocks with zero water absorption lead cryogenic and below-ambient applications across Grangemouth petrochemical facilities. Supply concentrates in specialized European production centers, creating lead time vulnerability for UK clients.
- Foamed Polymers:Phenolic and PIR foams serve HVAC ductwork and secondary containment in water treatment facilities.
- Calcium Silicate:Pre-formed pipe sections rated to 650°C protect high-temperature steam lines in manufacturing plants.
- Aerogel:Silica-based blankets at 10-20mm equivalent thickness command premium positioning in space-constrained turbine retrofits. Supercritical drying requirements and dust containment protocols limit installation to specialist contractor networks.
Mineral wool holds the largest share; momentum sits with aerogel.
Application:
Project scale and technical risk profile separate high-value specification-driven segments from commodity maintenance work.
- Power Plants:Combined cycle gas turbine exhaust ducting and steam pipe networks drive demand for multilayer high-temperature systems. Scottish and northern English operators specify aerogel composites for 2030 compliance deadlines.
- Chemical Processing:Continuous reactors and distillation columns require corrosion-resistant insulation with documented thermal performance. The Carbon Border Adjustment Mechanism pressures operators to procure systems with verified Environmental Product Declarations.
- Petrochemical Facilities:Grangemouth's decarbonization roadmap creates demand for cryogenic insulation in hydrogen and carbon capture retrofit applications.
- Food Manufacturing:Process steam and refrigeration systems need hygienic surface finishes and moisture-resistant barriers.
- Pulp & Paper:Recovery boiler insulation and lime kiln applications favor calcium silicate for chemical resistance.
Chemical processing generates the highest specification intensity; hydrogen transition projects at petrochemical facilities are expanding most quickly.
Installation Type:
Margin structure and customer relationship durability diverge between capital-project spikes and recurring maintenance revenue.
- New Construction:Greenfield power and chemical facilities in the Humber and Teesside clusters bundle insulation into EPC contracts with centralized technical teams. Tier-one contractors mandate approved vendor lists with pre-negotiated pricing.
- Retrofit Projects:Aging infrastructure replacement demands asbestos survey protocols that add 15-25% to project costs before insulation installation begins. PAS 2038 standards will mandate thermal performance documentation.
- Maintenance:Routine inspection and patch repair contracts offer recurring revenue with lower technical barriers to entry.
- Turnaround Shutdowns:Time-critical replacement during planned outages commands premium labor rates and requires pre-staged material inventories.
New construction captures the largest project value; digital twin integration is reshaping maintenance contract structures.
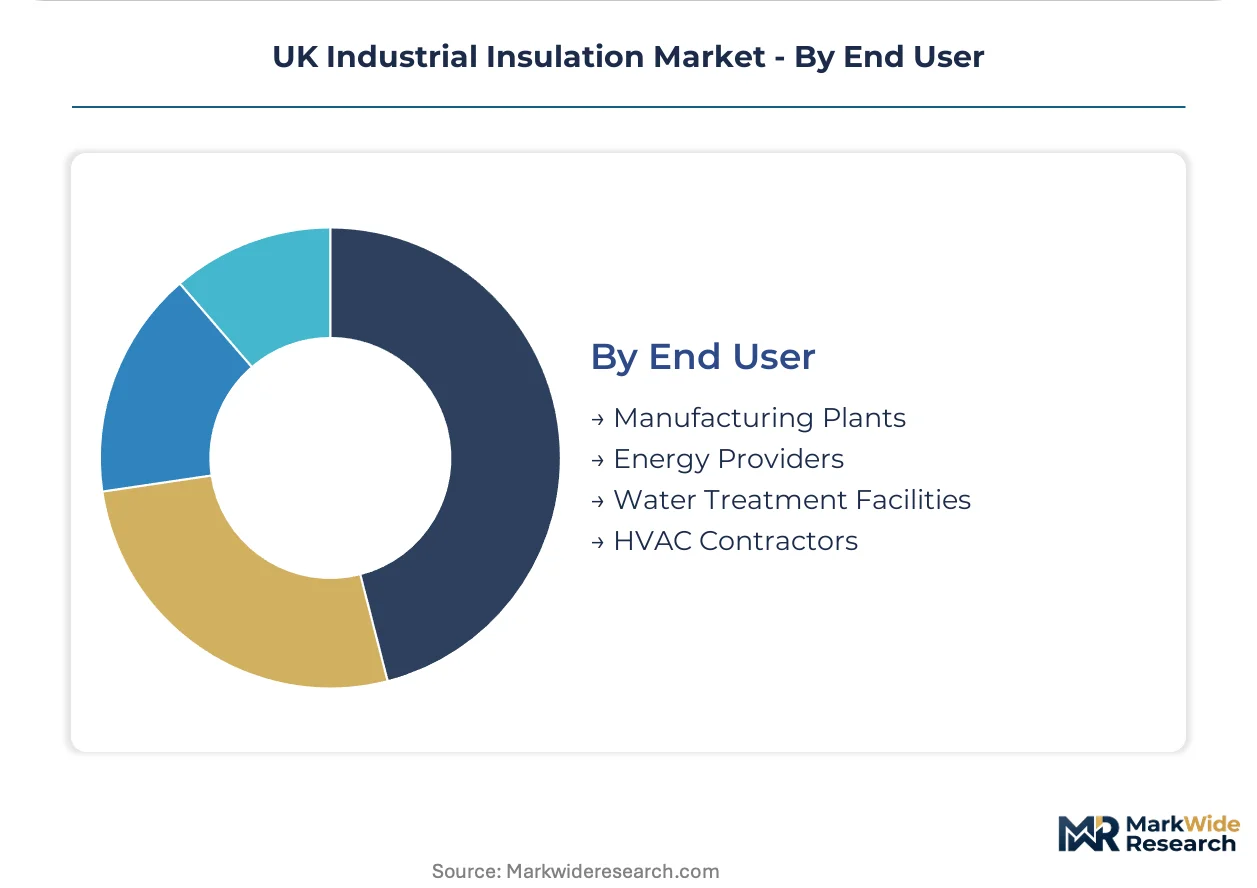
End User:
Procurement sophistication and specification autonomy vary by asset ownership structure and in-house engineering capability.
- Manufacturing Plants:Chemical, food, and paper producers with captive maintenance teams source materials directly from distributors for routine work while outsourcing complex retrofits.
- Energy Providers:National Grid and thermal generator operators maintain centralized technical specifications that pre-qualify insulation systems for safety-critical applications.
- Water Treatment Facilities:Regional utilities prioritize moisture-resistant cellular glass and foamed polymers for below-grade pipe networks.
- HVAC Contractors:Building envelope specialists serving industrial facilities anchor residential-adjacent retrofit volumes with glass mineral wool product lines.
Energy providers command the most stringent specification regimes; water treatment facilities are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stone wool manufacturing concentrates in South Wales, while specification authority for high-performance systems clusters around England's industrial corridors. The Health and Safety Executive's COMAH enforcement and the UK's Net Zero Strategy create divergent compliance pressures across sub-regions.
England
The Humber industrial cluster drives concentrated demand for high-temperature mineral wool in continuous chemical processing operations. Building Regulations Part L upgrades accelerate envelope retrofits across manufacturing facilities in the Midlands and northern counties. EPC contractors in Teesside mandate approved vendor lists that compress regional distributor margins.
Scotland
Grangemouth's petrochemical decarbonization roadmap generates procurement for cryogenic insulation in hydrogen and carbon capture retrofit applications. Scottish Power and thermal generator operators specify multilayer aerogel composites for 2030 compliance deadlines on combined cycle gas turbine exhaust ducting. The Scottish Government's energy transition funding accelerates project timelines beyond English counterparts.
Wales
Bridgend anchors domestic stone wool production capacity, supplying power generation clients across the UK with thermal cycling-resistant systems. The Welsh Government's industrial decarbonization plan targets process efficiency upgrades at Port Talbot steel adjacent facilities. Local manufacturers face raw material cost volatility tied to UK steel production cycles.
Northern Ireland
Belfast's manufacturing base sources insulation through distributors serving cross-border chemical and food processing operations. The Northern Ireland Environment Agency enforces COMAH-aligned surface temperature mandates at major hazard sites. Lagging infrastructure investment constrains uptake of advanced aerogel systems relative to Great Britain.
UK Industrial Insulation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material chemistry. The UK industrial insulation market structures around three tiers: multinational manufacturers with direct specification relationships, regional distributors serving maintenance contractors, and specialist applicators handling complex aerogel and cellular glass installations. Two strategic archetypes dominate: vertically integrated stone wool producers leveraging captive raw material streams, and technology licensors positioning on thermal performance per unit thickness. Competitive moves concentrate on EPC partnership consolidation and PAS 2038 certification pre-positioning.
Within the mineral wool tier, Rockwool International A/S and Knauf Insulation Limited exemplify scale-driven positioning anchored to domestic manufacturing infrastructure. Saint-Gobain S.A. occupies a specification-led position through technical documentation depth. These three entities represent divergent strategic postures: production proximity, residential-adjacent retrofit penetration, and engineered systems specification authority respectively.
| Leading Market Players |
|---|
| Rockwool International A/S |
| Saint-Gobain S.A. |
| Knauf Insulation Limited |
| Owens Corning Insulating Systems LLC |
| Johns Manville Corporation |
| Kingspan Group plc |
| Aspen Aerogels Incorporated |
| Armacell International S.A. |
| Promat International N.V. |
| Others |
Pricing and Supply Chain Analysis
Port of Rotterdam freight corridors feed basalt and slag feedstock into South Wales manufacturing, where steel production cycle volatility translates directly into stone wool pricing spreads and downstream tier differentiation across UK industrial buyers.
Pricing Analysis
COMAH surface temperature mandates dictate the pricing tier structure across UK industrial insulation procurement. Three-tier pricing structure across premium, standard, and economy levels separates aerogel composites with installation warranties from certified mineral wool systems and uncertified commodity batts. Price differentiation hinges on certification grade under Health and Safety Executive compliance tiers and volume scale in EPC-contracted new construction. Cost compression in standard-grade mineral wool is intensifying because basalt input volatility erodes fixed-price contract margins. Maintenance contractors serving manufacturing plants exhibit highest price sensitivity; energy providers with centralized technical specifications show least.
Supply Chain Analysis
Basalt and blast furnace slag feedstock draws from UK steel production centers, Belgian recycling facilities, and German metallurgical operations. Raw material dependencies span mineral wool binders sourced from phenolic resin suppliers, cellular glass production concentrated in specialized European facilities, and aerogel silica precursors. Single-source vulnerability concentrates in cryogenic-grade cellular glass where limited continental manufacturing creates lead time exposure. Distribution runs through EPC-contractor approved vendor lists in England's Humber cluster, regional distributor networks for maintenance contractors, and direct manufacturer relationships with energy providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAS 2038 thermal performance documentation services are expanding faster than hardware sales, creating recurring-revenue attach opportunities that outpace material shipment growth across UK industrial retrofit markets.
For Market Incumbents: Insulate core EPC relationships against specification authority consolidation by embedding digital twin integration capabilities into maintenance contracts. Deepen backward integration into Bridgend-adjacent basalt processing to buffer margin compression from steel cycle volatility. Counter aerogel specialist contractors by pre-qualifying installation crews for complex multilayer applications. For New Entrants and Emerging Players: Establish a beachhead in Scotland's Grangemouth hydrogen transition projects where cryogenic insulation demand outpaces established supply relationships. Target water treatment facilities gaining procurement sophistication for below-grade cellular glass specifications. Lead with measurement-verification contracting bundled into PAS 2038 compliance services rather than commodity material supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist applicators with certified aerogel installation networks over pure-play manufacturers facing input cost volatility. Five-to-ten year viability hinges on service-attach revenue durability rather than hardware margin sustainability. Watch Carbon Border Adjustment Mechanism implementation timing as inflection indicator for Environmental Product Declaration premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| PAS 2038 Certification Pre-Positioning | Captures measurement-verification contracts ahead of mandatory thermal performance documentation requirements. |
| Backward Integration into Basalt Processing | Buffers Rockwool's Bridgend operations against UK steel production cycle volatility. |
| Digital Twin Integration Development | Enables predictive maintenance bundling that reshapes contract structures for Scottish Power operators. |
| Cryogenic Installation Capability Buildout | Addresses Grangemouth hydrogen retrofit demand where specialist contractor scarcity extends project timelines. |
| Environmental Product Declaration Investment | Elevates specification positioning as Carbon Border Adjustment Mechanism pressures chemicals and refining procurement. |
Research Methodology
Cross-validation between plant manager interviews and customs trade data anchors the qualitative findings on procurement pattern shifts. Primary fieldwork engaged EPC technical directors, maintenance contractors in the Humber cluster, mineral wool manufacturing procurement leads, and Health and Safety Executive compliance officers. Secondary validation drew from UK Building Regulations Part L amendments, COMAH enforcement records, SEC filings of listed insulation manufacturers, and UK steel production statistics. Bottom-up project pipeline assessment triangulates against top-down market sizing across material chemistry tiers.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shapes the analytical framework. Segmentation dimensions span material chemistry, application temperature regime, installation type, and end-user procurement sophistication. CAGRs derive from installed base depreciation curves and regulatory mandate acceleration effects. Forecast inputs include EPC contract award visibility in Teesside and Grangemouth, and steel production outlook correlations with stone wool input costs.
Macroeconomic conditions sit as an overlay; deviation in UK industrial construction investment and EU carbon border implementation timing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and EPC vendor list consolidation pace. Material shifts in hydrogen infrastructure deployment scale or PAS 2038 standard finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Flexible Insulation Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Refrigeration Insulation Materials Market