
 Technical Foam Market | 2026-2036
Technical Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Foam Market Intelligence
The shift from general furniture production towards specialized applications in medical devices is hardening the requirement for high-purity, biocompatible foam materials. BASF SE leverages its extensive chemical portfolio to develop advanced polyurethane and melamine foams for these demanding sectors. Meanwhile, Rogers Corporation specializes in high-performance elastomeric materials for electronics, while Armacell International Holding dominates the market for flexible insulation foams in construction and HVAC systems.
Technical foam is a class of cellular polymer engineered for specific performance, such as controlled cell structures for superior thermal insulation or acoustic absorption. These materials are distinct from commodity cushioning foams due to their precise functional properties. Polyurethane foams maintain a dominant position, though cross-linked polyethylene is expanding rapidly in high-value applications. Within end-uses, construction insulation provides volume, while acoustic control for aerospace and automotive offers higher margin opportunities.
Regulatory frameworks like Europe's REACH and the US EPA's rules on blowing agents significantly influence material composition and manufacturing processes. Additionally, GB standards in China and specific building codes in countries like Germany and Japan set stringent performance criteria for flammability and thermal efficiency. Navigating this complex regulatory landscape while investing in sustainable, recyclable foam solutions will be critical for maintaining market access and competitive advantage.
Market Dynamics
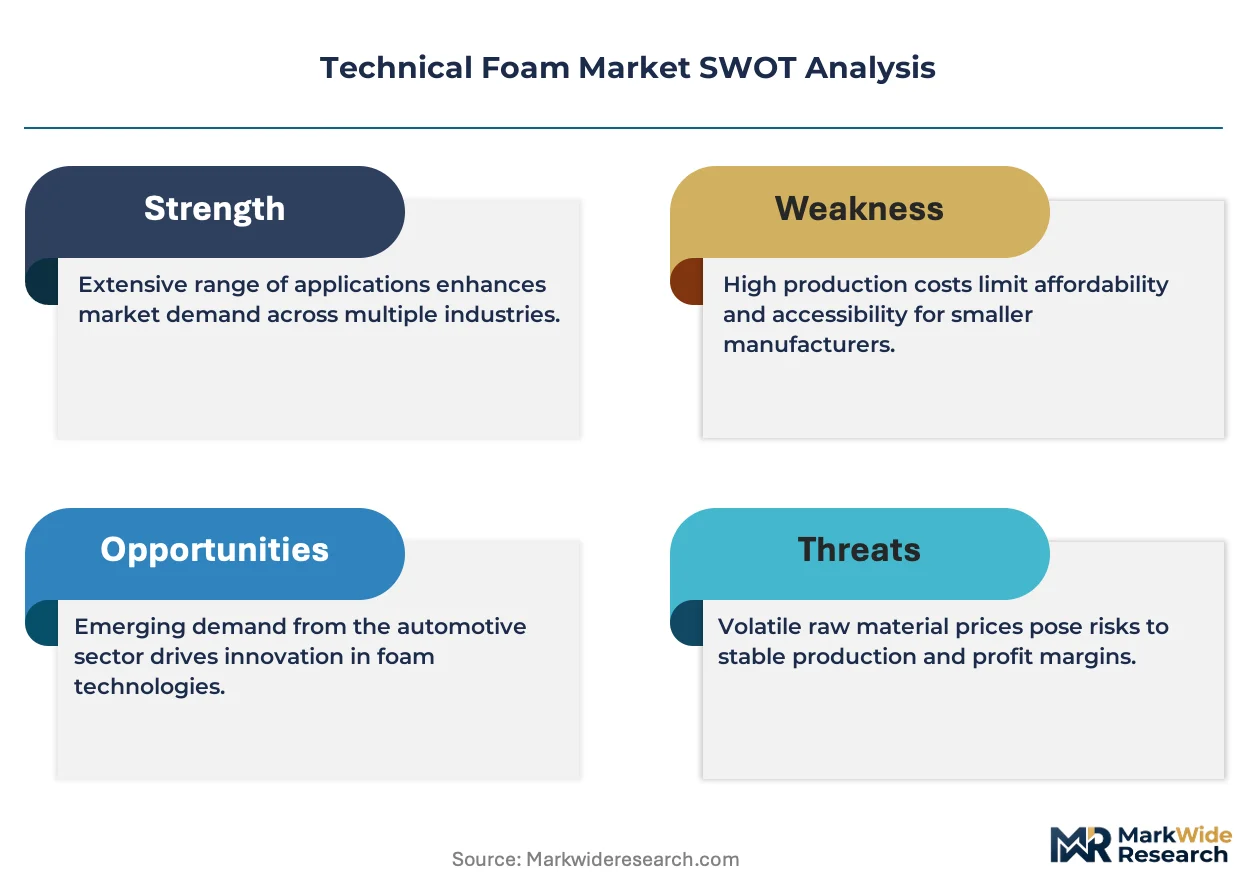
Intensifying regulatory pressure on thermal efficiency and material circularity is the central force shaping the technical foam market. Mandates like the EU Green Deal and stricter GB standards in China are compelling a fundamental shift in material science and production processes.
Growth Catalysts
- Aerospace Fabrication Demand:The requirement for lightweight, high-performance insulation and acoustic absorption materials in aerospace manufacturing provides a high-margin growth vector. These applications demand foams with superior thermal stability and low outgassing properties.
- Stricter Building Codes:Energy efficiency mandates, such as those aligned with the EU Green Deal, are expanding the use of advanced insulation foams. These regulations create new requirements for thermal resistance in both new construction and retrofitting projects.
- Cross-Linked Polyethylene (XLPE) Adoption:The expansion of XLPE foam in high-value applications, including medical device packaging and automotive components, is creating new market segments. Its superior chemical resistance and durability offer advantages over traditional materials.
Market Restraints
- Polyurethane Feedstock Volatility:The market is exposed to price fluctuations in key polyurethane precursors like polyols and isocyanates. This volatility complicates cost management and can compress margins for foam converters, especially for commodity-adjacent grades.
- Blowing Agent Regulations:Phasing out of hydrofluorocarbons under frameworks like the US EPA rules and the EU F-Gas Regulation requires significant R&D investment. Finding alternative blowing agents with low global warming potential that do not compromise performance is a major hurdle.
- Competition from Traditional Insulators:In the high-volume construction sector, technical foams face persistent competition from established materials like mineral wool and fiberglass. These alternatives often present a lower initial cost, posing a barrier in price-sensitive projects.
Strategic Opportunities
- Biocompatible Medical Foams:The need for high-purity, biocompatible materials in single-use medical devices and orthopedic supports presents a significant opportunity. These applications demand strict adherence to standards like ISO 10993 for patient-contact materials.
- Circular Economy Initiatives:Developing and commercializing recyclable or bio-based foam solutions creates a competitive advantage. Policies promoting material circularity will favor producers who can offer foams that fit into closed-loop recycling systems, particularly in Europe.
- Smart Foam Systems:Integrating sensors and conductive materials within foam structures opens new possibilities for smart components in automotive seating or industrial monitoring. This convergence creates higher-value products with diagnostic or responsive capabilities.
Industry Challenges
- Navigating Global Standards:Manufacturers face complexity in meeting divergent performance criteria across geographies, such as Germany's DIN standards for flammability and Japan's JIS standards for thermal testing. Harmonizing products for multiple markets is an operational burden.
- Recycling Infrastructure Costs:Establishing effective collection and chemical recycling processes for post-consumer foam waste requires substantial capital expenditure. The lack of scaled infrastructure remains a primary barrier to achieving true circularity for materials like polyurethane.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Foam Market |
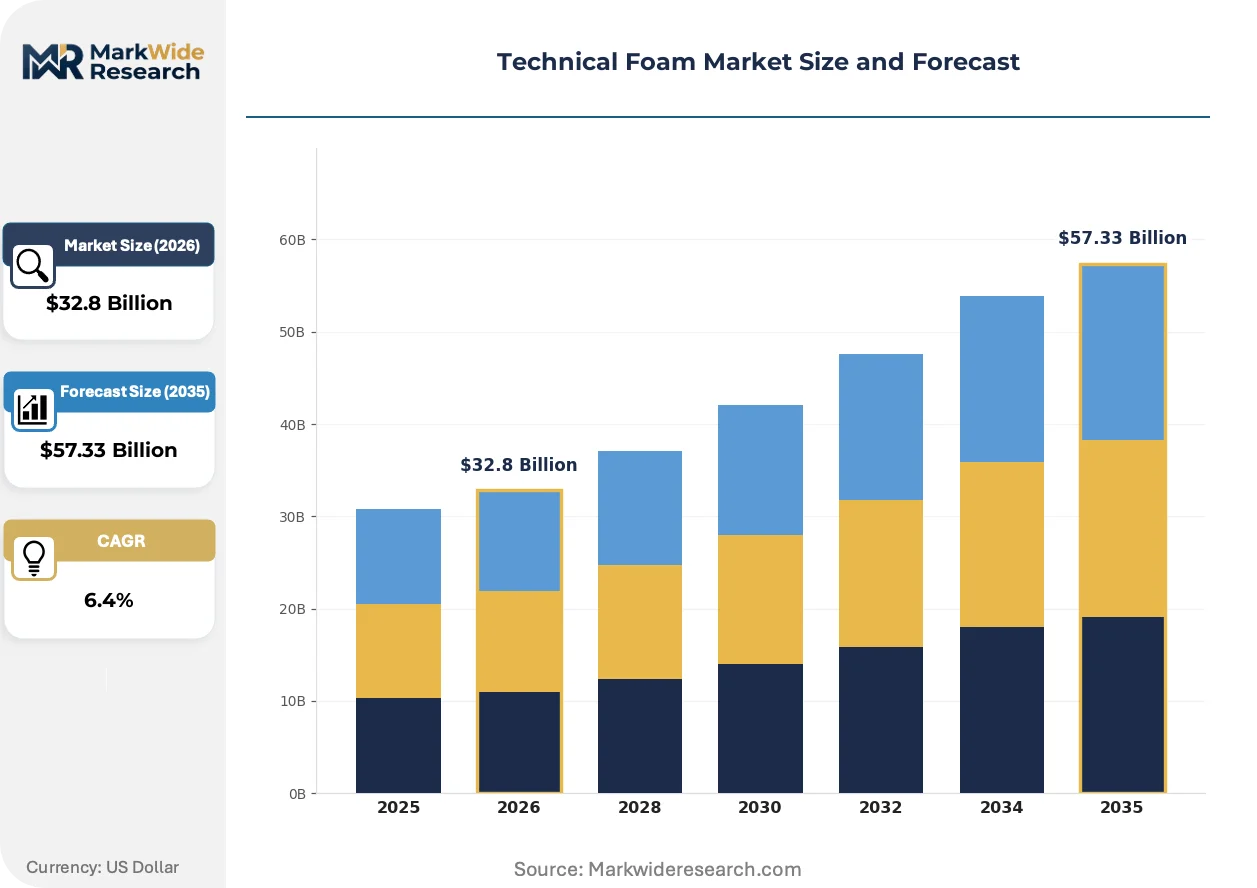
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Polyethylene, PVC, Phenolic, Melamine Technology: Open Cell, Closed Cell, Reticulated, Cross-linked, Elastomeric Application: Construction Insulation, Packaging Protection, Sports Equipment, Acoustic Control, Thermal Containment End User Industry: Electronics Manufacturing, Furniture Production, Aerospace Fabrication, Marine Assembly, Medical Devices |
| Companies Covered | BASF SE, Dow Inc., Armacell International Holding, Recticel NV, Huntsman Corporation, Sekisui Chemical Co. Ltd., Woodbridge Company Ltd., INOAC Corporation, Rogers Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Foam Market Strategic Shifts & Innovations
Material science advancements are redefining the performance limits and lifecycle of technical foams. Innovations focus on creating specialized properties for demanding end-uses while simultaneously addressing regulatory pressures for improved sustainability and reduced environmental impact.
Melamine foam, known for its inherent flame retardancy and excellent acoustic properties, is a key innovation in safety-critical applications. The aerospace and rail transport sectors are steadily adopting this material for cabin interiors and acoustic insulation. Its lightweight nature and thermal stability mean it is absorbing roles previously held by heavier, multi-component insulation systems.
Europe's REACH regulation continues to exert significant influence on chemical compositions used in foam production. The framework restricts or requires authorization for certain substances of very high concern (SVHCs), including specific catalysts, flame retardants, and blowing agents. Polyurethane and polystyrene foam manufacturers are most affected, forcing reformulation efforts to ensure market access within the European Union.
A notable demand-side shift involves the procurement of certified, pre-tested insulation systems rather than just raw foam components. This trend is displacing the traditional component-supplier model, favoring manufacturers who can provide integrated solutions with documented performance. The construction and HVAC sectors in North America and Europe are leading this transition, driven by building code compliance and liability reduction.
Technical Foam Market Segmentation
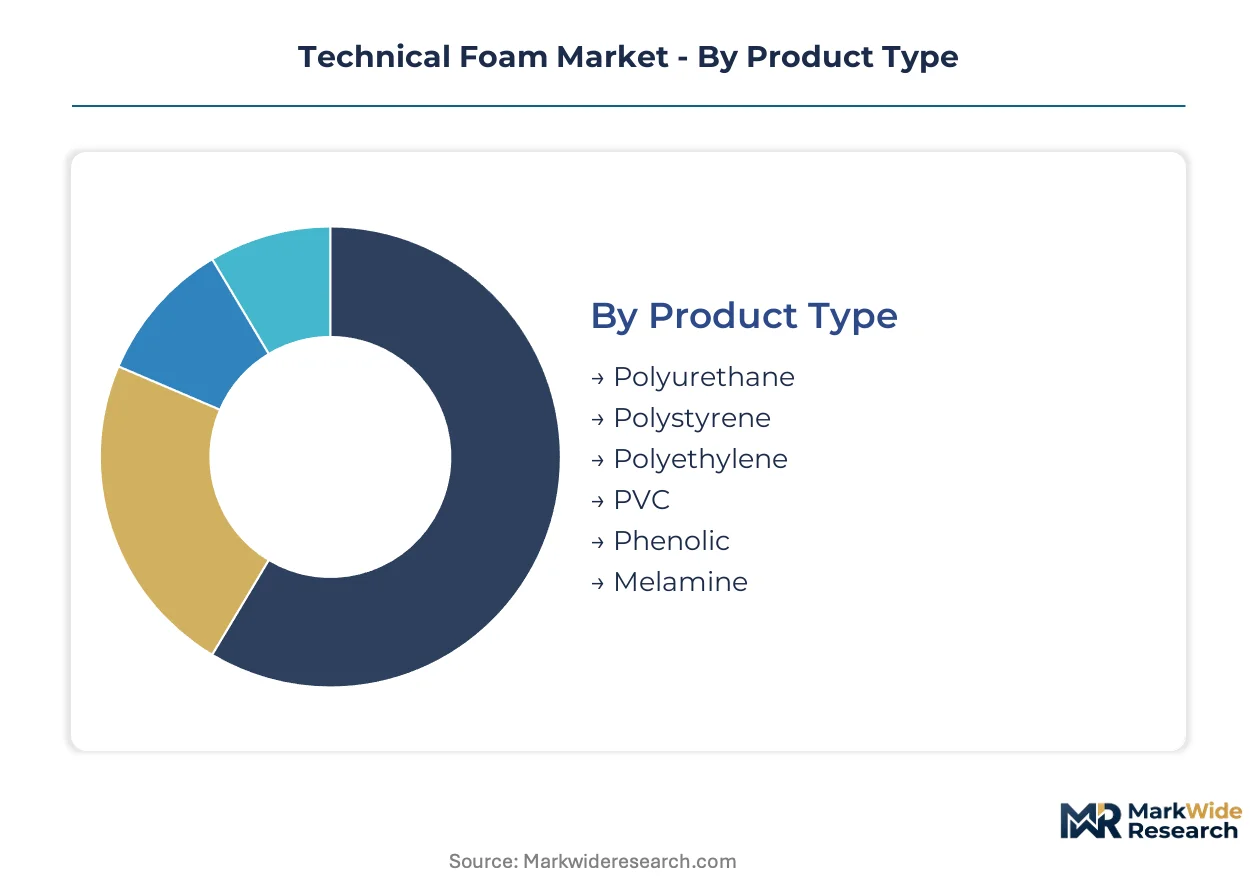
Technical foam market segmentation reveals distinct material preferences and performance requirements across diverse end-use sectors. Manufacturers strategically tailor foam properties, such as cell structure and chemical composition, to meet specific functional demands. This granular analysis provides clarity on where value creation and innovation are concentrated within the industry.
Product Type:
Polyurethane and polystyrene production capacity largely dictates the volume and cost structures across the foam market.
- Polyurethane:This dominant polymer leverages versatile chemistry, allowing for a wide range of densities and rigidities. Demand for polyurethane is strong in construction insulation and automotive seating, driven by energy efficiency and comfort requirements.
- Melamine:Known for inherent flame retardancy and excellent acoustic absorption properties, melamine foam is often used in safety-critical environments. Melamine demand is high in aerospace and rail transport for cabin interiors, driven by stringent fire safety standards.
- Polystyrene:Lightweight and cost-effective, polystyrene is primarily used for insulation boards and protective packaging.
- Polyethylene:This product type offers good chemical resistance and shock absorption, expanding in medical packaging and sports equipment.
- PVC:Flexible and durable, PVC foam finds applications in sealing and gasketing.
- Phenolic:Phenolic foam provides superior fire resistance and thermal insulation, critical for industrial applications.
Today's leader: Polyurethane. Tomorrow's challenger: Melamine.
Technology:
Foam technology differentiation directly impacts performance characteristics, enabling specialized solutions for demanding applications.
- Open Cell:This technology features interconnected pores, allowing air and liquids to pass through, ideal for acoustic absorption and filtration. Open cell foam finds extensive use in soundproofing panels and air filters, driven by noise reduction and air quality mandates.
- Cross-linked:Polymers are chemically bonded in cross-linked foams, enhancing durability, chemical resistance, and thermal stability. Cross-linked foam applications are expanding in medical device packaging and automotive components, driven by performance and longevity requirements.
- Closed Cell:Closed cell foams contain discrete, sealed cells, providing superior thermal insulation and buoyancy properties.
- Reticulated:This technology offers a highly porous, open-cell structure with excellent filtration and fluid management capabilities.
- Elastomeric:Flexible and resilient, elastomeric foams are commonly used for sealing, gasketing, and vibration dampening.
Open Cell technology currently holds significant volume, while Cross-linked technology exhibits the steepest expansion trajectory.
Application:
The volume dynamics of technical foam are largely shaped by the scale and regulatory requirements of specific end-use applications.
- Construction Insulation:This application utilizes foams for thermal and acoustic barriers in buildings, crucial for energy efficiency. Construction insulation demand is significant in Europe and North America, driven by stringent building codes and green building initiatives.
- Acoustic Control:This segment employs foams to absorb sound and reduce noise levels in various environments. Acoustic control foam is highly sought after in aerospace and automotive sectors, driven by passenger comfort and regulatory noise limits.
- Packaging Protection:Foam in this application safeguards sensitive goods during transit, providing shock absorption and vibration dampening.
- Thermal Containment:This application maintains temperature stability for products like pharmaceuticals and food during storage and transport.
- Sports Equipment:Foams enhance safety and performance in gear such as helmets, pads, and footwear.
Construction Insulation represents the largest application segment by volume, with Acoustic Control offering higher margin opportunities.
End User Industry:
Specific end-user industries drive demand for technical foams based on their unique product lifecycle and performance specifications.
- Medical Devices:This industry requires high-purity, biocompatible foams for applications like wound care, prosthetics, and diagnostic equipment. Medical device foam demand is prevalent in developed economies, driven by aging populations and strict regulatory approvals like ISO 10993.
- Aerospace Fabrication:This sector utilizes lightweight, high-performance foams for insulation, acoustic dampening, and structural components. Aerospace fabrication requires foam extensively in major aircraft manufacturing hubs, driven by fuel efficiency and safety standards.
- Electronics Manufacturing:This industry employs foams for packaging, gasketing, and thermal management in electronic devices.
- Furniture Production:This sector uses foams for cushioning, support, and ergonomic design in various furniture types.
- Marine Assembly:Marine assembly incorporates foams for buoyancy, insulation, and vibration control in marine vessels.
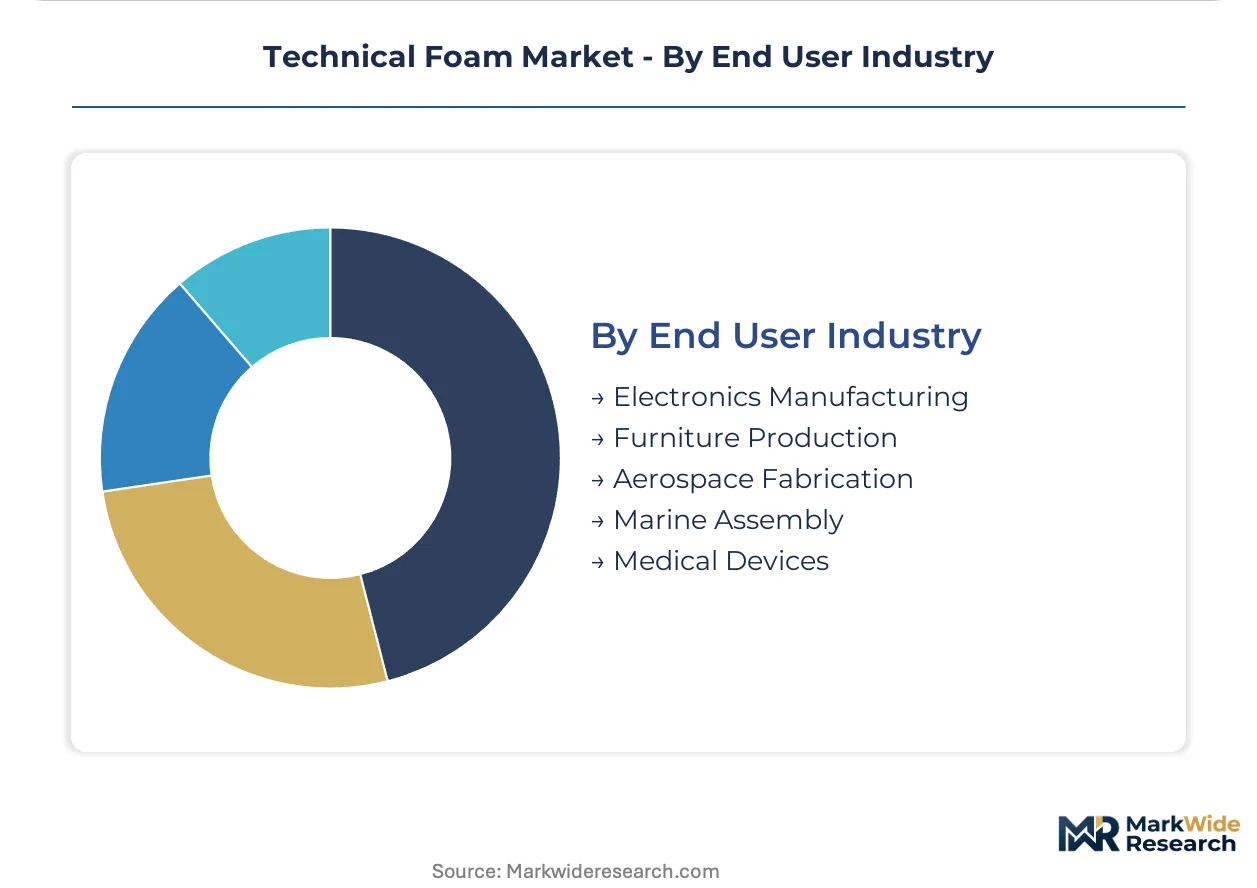
Medical Devices and Aerospace Fabrication are high-value segments, while Electronics Manufacturing offers significant volume potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage significantly influences technical foam production, as manufacturers seek locations with more favorable environmental compliance costs or incentives. This dynamic drives investment and capacity shifts, especially for materials facing stringent chemical restrictions in established markets. Global demand for technical foams remains robust across diverse applications.
China
Demand for technical foams in China stems from its expansive electronics manufacturing sector and ambitious infrastructure projects. Stricter GB standards for building insulation and fire safety are compelling domestic producers to upgrade material performance. Manufacturing hubs in the Yangtze River Delta are seeing concentrated procurement for advanced packaging and construction foams.
Germany
Germany's technical foam market is driven by stringent energy efficiency mandates under the EU Green Deal and a strong automotive industry. Regulations like REACH compel continuous innovation in foam formulations and blowing agents to ensure market access. The Rhine-Ruhr region, with its chemical industry clusters, remains a focal point for polyurethane and specialty foam research.
United States
The United States market for technical foam benefits from significant aerospace fabrication and a growing medical device industry. US EPA rules on blowing agents and flammability standards for construction materials shape product development. Silicon Valley and other tech hubs drive demand for high-performance electronics packaging foams.
Japan
Japan exhibits consistent demand for high-performance technical foams, particularly in construction and automotive sectors, driven by rigorous JIS standards for thermal efficiency and acoustic performance. The country's focus on disaster resilience also boosts demand for fire-resistant insulation materials. Manufacturing facilities in the Kanto region are active in developing advanced cross-linked polyethylene foams.
Technical Foam Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry barriers and customer requirements. The market features a tiered structure, with a few large integrated chemical companies at the top and numerous regional converters below. Strategic archetypes include material innovators, application-specific solution providers, and high-volume commodity producers. Dominant competitive moves involve portfolio diversification and strategic partnerships to navigate complex regulatory landscapes.
Specialists in advanced material solutions include BASF SE, which leverages its extensive chemical portfolio to serve demanding sectors like medical devices and aerospace. Rogers Corporation represents a focused approach, anchoring its position in high-performance elastomeric materials for electronics applications. Armacell International Holding sits within the application-specific solution provider archetype, dominating flexible insulation foams for construction and HVAC systems.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Armacell International Holding |
| Recticel NV |
| Huntsman Corporation |
| Sekisui Chemical Co. Ltd. |
| Woodbridge Company Ltd. |
| INOAC Corporation |
| Rogers Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into key chemical precursors anchors both supply position and pricing power for large technical foam manufacturers. This strategic control mitigates the impact of raw material price fluctuations on downstream product costs.
Pricing Analysis
Direct-to-OEM discounts significantly influence pricing in the technical foam market, particularly for high-volume automotive and construction applications. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade, ISO 10993 certification level for medical use, and customization requirements. Pricing pressure stems from intense competition in commodity construction insulation, pushing margins down. Buyers in aerospace fabrication exhibit lower price sensitivity compared to highly cost-conscious construction insulation procurers.
Supply Chain Analysis
Domestic-content mandates under initiatives like the EU Green Deal are reshaping sourcing patterns for technical foams. Geographic supply concentration for raw materials centers on chemical production hubs in Germany and China. Polyols and isocyanates for polyurethane foams represent critical raw material dependencies. Commodity price volatility for these precursors poses a structural supply chain risk. Distribution runs through a mix of specialized distributors for high-performance products and direct sales channels for large-volume industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The technical foam market operates as a stable compounder, with consistent growth driven by intensifying global regulatory pressures for thermal efficiency and material circularity.
For Market Incumbents:
Lock in long-term supply agreements for specialized precursors to hedge against feedstock volatility, a persistent threat to margins. Incumbents should also expand R&D into bio-based and recyclable foam solutions to meet evolving EU Green Deal mandates and avoid market access restrictions. Diversify product portfolios to capture high-margin opportunities in medical devices, mitigating the impact of competition from traditional insulators in construction.
For New Entrants and Emerging Players:
Begin with a focus on niche, high-value applications like biocompatible medical foams, leveraging strict ISO 10993 standards as a barrier to entry. Target specialized medical device manufacturing clusters in the United States by offering pre-certified, integrated foam solutions. Develop smart foam systems with integrated sensors to differentiate from established players and capture premium pricing in automotive seating.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized technical foam manufacturers because of the fragmented nature of application-specific solution providers. Focus on acquiring mid-sized companies with proprietary technology in cross-linked polyethylene for medical devices, or strong regional positions in Germany's automotive sector. The long-term viability remains strong due to sustained demand from critical infrastructure. A signal to watch is the commercialization of scalable chemical recycling processes for polyurethane waste.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Melamine Foam | Addresses growing demand in aerospace and rail transport for inherent flame retardancy. |
| Investment in Bio-based Polyurethane R&D | Aligns with EU Green Deal objectives and reduces reliance on petrochemical feedstocks. |
| Development of Integrated Insulation Systems | Captures market share from component suppliers by offering certified solutions for construction in North America. |
| Strategic Partnership for Chemical Recycling | Establishes a circular economy pathway for post-consumer foam waste, reducing environmental impact. |
| Acquisition of Cross-Linked Polyethylene Specialist | Expands portfolio into high-value medical device packaging and automotive components. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Discussions with R&D directors, procurement leads from aerospace fabrication, and building code officials in Germany informed market dynamics. Secondary data sources included EU Green Deal policy documents, US EPA regulations, and ISO standards for medical devices.
The forecast window was anchored to historical reference periods, establishing baseline market performance and growth trajectories. Segmentation dimensions included product type, technology, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from projected shifts in material science and increasing demand from aerospace fabrication. Regulatory compliance costs for blowing agents served as a key forecast input.
Caveats apply where geopolitical instability impacting feedstock prices or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement and industry adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Active Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Thin Insulation Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Insulation Products Market