
 Industrial Insulation Market | 2026-2036
Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Insulation Market Analysis
A shortage of certified industrial insulation installers is reorganizing contractor networks and project timelines across energy and chemical corridors. Owens Corning leverages its fiberglass manufacturing scale to secure long-term supply agreements with refinery operators. ROCKWOOL Insulation A/S anchors its position through stone wool formulations that withstand continuous operating temperatures above 1,000 degrees Celsius. Knauf Insulation competes by extending its distribution footprint into emerging industrial zones with prefabricated blanket systems.
Industrial insulation comprises engineered materials designed to reduce heat transfer, control surface temperatures, and protect equipment from thermal loss or fire exposure in demanding operating environments; calcium silicate and mineral wool formulations typically achieve thermal conductivity ratings below 0.05 W/m·K at elevated temperatures, serving the essential purpose of energy conservation and personnel safety in process industries. Mineral wool dominates installed base volumes across power generation and chemical processing due to its fire resistance and acoustic dampening properties, while aerogel-based systems represent the fastest-growing product class as operators retrofit legacy steam lines where space constraints prevent thicker conventional wraps. Pipe insulation generates the largest application-specific revenue pool given the extensive network of steam and process piping in oil refineries and combined-cycle plants.
The EPA enforces emissions and energy efficiency standards that mandate insulation upgrades in US industrial facilities, while REACH and the EU Green Deal restrict hazardous substances in insulation binders and set carbon intensity benchmarks for imported materials. India's BIS certification requirements and the Bureau of Energy Efficiency's consumption norms are tightening product compliance for domestic and imported insulation systems. Stakeholders must monitor evolving fire safety codes and embodied carbon accounting rules as procurement criteria shift from first-cost optimization to lifecycle thermal performance.
Market Dynamics
The EU Green Deal and tightened F-Gas Regulation are compressing allowable emission profiles for insulation chemistries, forcing European manufacturers to reformulate binders and accelerating retrofit cycles across energy-intensive process industries.
Growth Catalysts
- Power generation retrofits:Combined-cycle and thermal plant operators are expanding insulation replacement programs to cut heat loss and improve cycle efficiency. Steam turbine housings and boiler casings dominate retrofit volumes.
- India's PLI scheme:Production-linked incentives for domestic manufacturing are drawing insulation producers into industrial park clusters near petrochemical and steel complexes. Bureau of Energy Efficiency consumption norms tighten compliance thresholds for imported systems.
- Aerogel maturation:Silica-based blanket systems achieve thermal conductivity below 0.020 W/m·K in sub-10mm profiles. Space-constrained legacy steam lines in refineries and chemical plants are converting where conventional wraps cannot fit.
Market Restraints
- Binder cost volatility:Phenolic and acrylic resin prices fluctuate with petrochemical feedstock cycles. Formulation cost exposure concentrates in mineral wool and calcium silicate producers dependent on synthetic binders.
- Installer certification scarcity:Certified industrial insulation contractors cluster in established energy corridors. Project timelines extend where qualified labor pools thin across emerging industrial zones.
- Technical thickness constraints:Conventional mineral wool and fiberglass systems require 50-150mm profiles for high-temperature service. Retrofit applications with clearance limitations face substitution pressure from thinner advanced materials.
Strategic Opportunities
- Carbon accounting integration:Embodied carbon reporting under CSRD and evolving ISO standards is elevating lifecycle thermal performance in procurement criteria. Insulation suppliers embedding verified carbon data capture premium positioning.
- Prefabrication channels:Modular blanket and removable cover systems are bypassing traditional field-cut installation. Distribution partnerships with MRO suppliers and direct OEM supply agreements are opening.
- Hydrogen infrastructure:Cryogenic and high-temperature insulation demand is emerging at electrolyzer and ammonia synthesis facilities. Dual-temperature service specifications are creating specification openings for multi-layer systems.
Industry Challenges
- Fire safety code harmonization:Divergent ASTM, EN, and BIS testing protocols for reaction-to-fire performance force parallel certification tracks. Product validation timelines extend where jurisdictions lack mutual recognition.
- Legacy system integration:Asbestos-containing insulation in aging industrial assets requires abatement sequencing before retrofit. Project complexity multiplies where historical material surveys are incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Insulation Market |
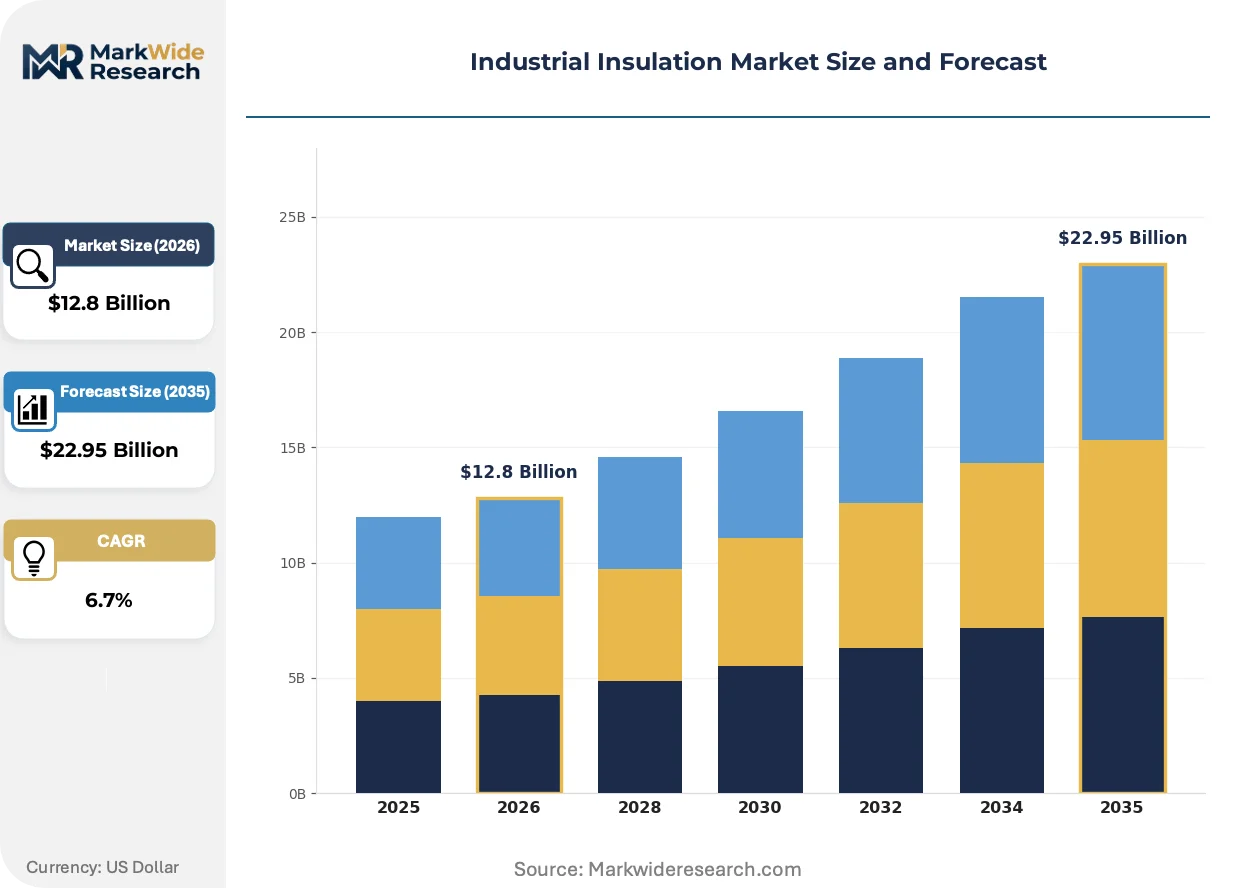
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Mineral Wool, Foam, Calcium Silicate Application: Pipe Insulation, HVAC, Equipment Insulation, Fire Protection End User: Oil & Gas, Power Generation, Manufacturing, Chemical Processing Installation Method: Pre-Insulated, Custom-Fabricated, Spray-Applied, Blanket |
| Companies Covered | Owens Corning, ROCKWOOL Insulation A/S, Knauf Insulation, Morgan Advanced Materials plc, 3M, Saint-Gobain ISOVER, Johns Manville, Aspen Aerogels, Inc., Unifrax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Insulation Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to compress conventional product lifecycles. Formulation priorities are pivoting from first-cost optimization to verified thermal performance over extended service intervals.
Silica aerogel composites are displacing multi-layer mineral wool wraps in high-temperature steam service. Refinery operators facing space constraints in congested pipe racks are specifying 6-10mm aerogel blankets where 75mm conventional systems cannot fit. Equipment density in legacy facilities is compressing acceptable insulation footprints and accelerating specification migration toward thinner advanced materials.
REACH authorization restrictions on boron compounds and formaldehyde-based binders are forcing reformulation of mineral wool and calcium silicate products. European manufacturers face 2025-2027 sunset dates for legacy chemistries, requiring validation of alternative binder systems under shortened transition timelines. Export-oriented producers in India and Turkey are adapting formulations to maintain EU market access, spreading compliance costs across global supply chains.
Lifecycle service contracts are displacing discrete material procurement in large industrial accounts. Refinery and chemical plant operators are unbundling insulation supply from installation and predictive maintenance, consolidating vendor relationships under multi-year thermal performance guarantees. This contracting evolution concentrates in the US Gulf Coast and North Sea industrial clusters where asset integrity programs emphasize total cost of ownership over unit material pricing.
Industrial Insulation Market Segmentation
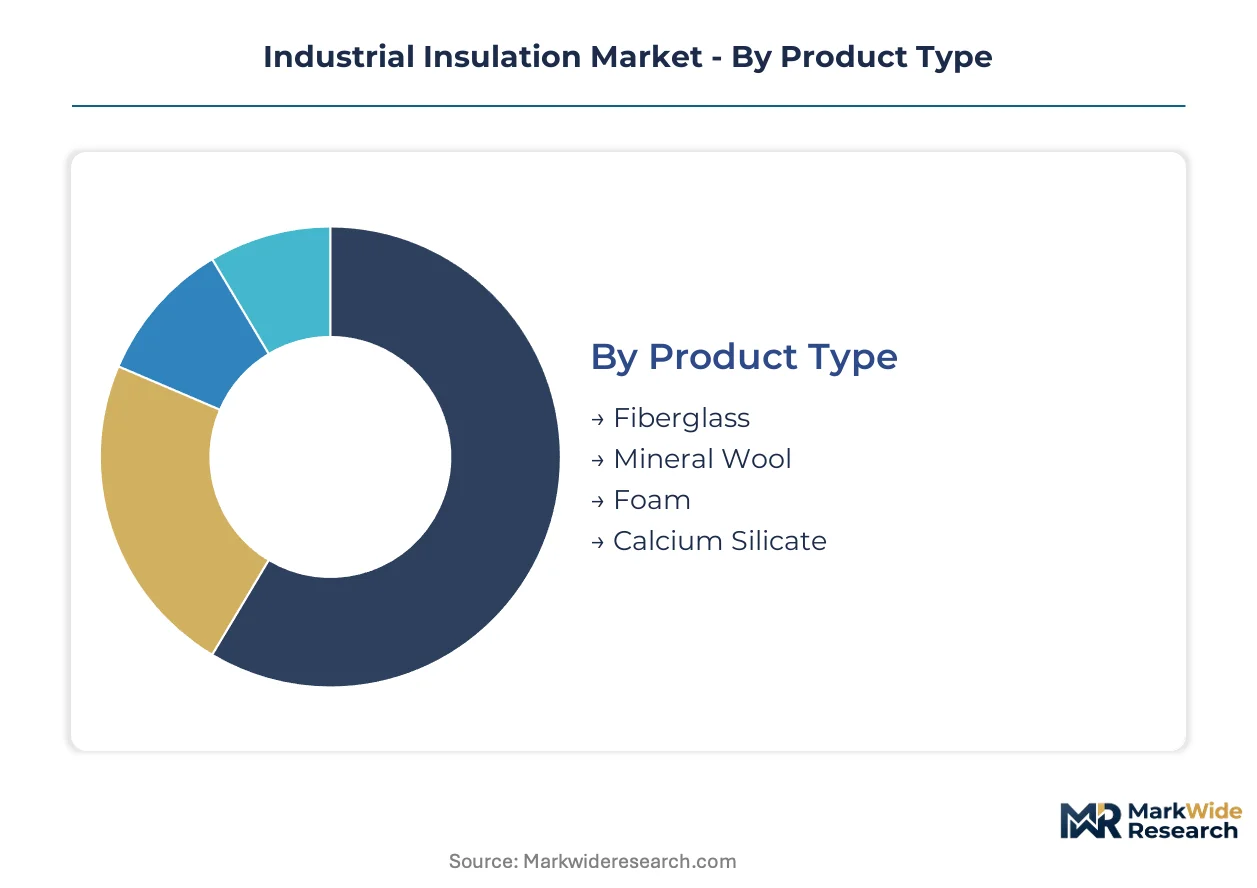
Industrial insulation procurement patterns diverge sharply between domestic maintenance cycles and export-driven newbuild projects. Material specifications and installation methods vary by end-use thermal requirements, creating distinct margin structures across segment combinations.
Product Type:
Domestic consumption concentrates in mineral wool and fiberglass for power plant retrofits across India and the United States, while calcium silicate and advanced foam systems flow primarily to export markets serving Middle Eastern petrochemical complexes.
- Mineral Wool:Stone wool and slag wool formulations achieve continuous service temperatures above 750°C with inherent fire resistance. Indian steel complexes under the PLI scheme are absorbing record volumes for furnace linings and ductwork as domestic production scales. Mineral wool holds the largest share; momentum sits with aerogel-enhanced variants.
- Fiberglass:Glass fiber batts and boards deliver thermal conductivity near 0.04 W/m·K at moderate temperatures up to 540°C. Owens Corning's long-term refinery supply agreements anchor North American demand for boiler and turbine housing applications. Demand concentrates in combined-cycle plant retrofits where acoustic dampening requirements coexist with thermal control.
- Foam:Polyisocyanurate and phenolic foam systems provide sub-0.025 W/m·K conductivity in sub-50mm profiles. Cold storage and LNG infrastructure projects specify rigid foam for cryogenic pipe support and vessel bases.
- Calcium Silicate:Hydrous calcium silicate boards withstand 650°C service with compressive strength exceeding 1 MPa. Petrochemical operators in Saudi Arabia and the UAE specify pre-formed pipe covers for high-temperature steam distribution.
Mineral wool dominates installed base volumes; fiberglass gains share fastest in aerogel-composite configurations.
Application:
Cost tier stratification separates commodity pipe wraps from engineered fire protection systems, with specification authority residing in EPC contractors for newbuilds versus facility engineers for retrofits.
- Pipe Insulation:Steam and process piping networks in oil refineries and chemical plants generate the largest revenue pool. Removable blanket systems for maintenance access points command premium pricing over permanent wraps. Pipe insulation captures the greatest volume; fire protection climbs fastest on regulatory tightening.
- Fire Protection:Intumescent coatings and fire-rated board systems protect structural steel and critical equipment. EU Green Deal chemistry restrictions are forcing binder reformulations that extend product validation timelines.
- HVAC:Ductwork and air handling insulation emphasizes acoustic performance alongside thermal efficiency. Commercial and institutional building codes drive specification in developed markets.
- Equipment Insulation:Turbine housings, heat exchangers, and vessel skirts require custom-fabricated removable covers. Lifecycle service contracts are consolidating vendor relationships under thermal performance guarantees.
Pipe insulation commands the largest revenue base; fire protection specifications are expanding most quickly on code harmonization pressures.
End User:
Customer type segmentation separates owner-operated assets with total cost of ownership procurement from EPC-driven projects with first-cost optimization, particularly across hydrogen infrastructure emerging at electrolyzer facilities.
- Oil & Gas:Refinery and upstream operators prioritize thermal efficiency retrofits to cut operational losses. US Gulf Coast facilities face EPA emissions standards mandating insulation upgrades. Oil & gas anchors the largest installed base; chemical processing shows steepest expansion trajectory on capacity additions.
- Chemical Processing:Petrochemical and specialty chemical complexes specify multi-layer systems for dual-temperature service. Indian industrial park expansion under PLI incentives is accelerating adoption across polymer and fertilizer plants.
- Power Generation:Combined-cycle and thermal plant operators replace aging insulation during scheduled outages. Steam turbine housings and boiler casings dominate replacement volumes.
- Manufacturing:Cement, steel, and food processing facilities balance thermal performance with personnel safety requirements. BIS certification requirements tighten compliance for imported systems serving this fragmented segment.
Oil & gas retains the largest share; chemical processing gains fastest on hydrogen infrastructure buildout.
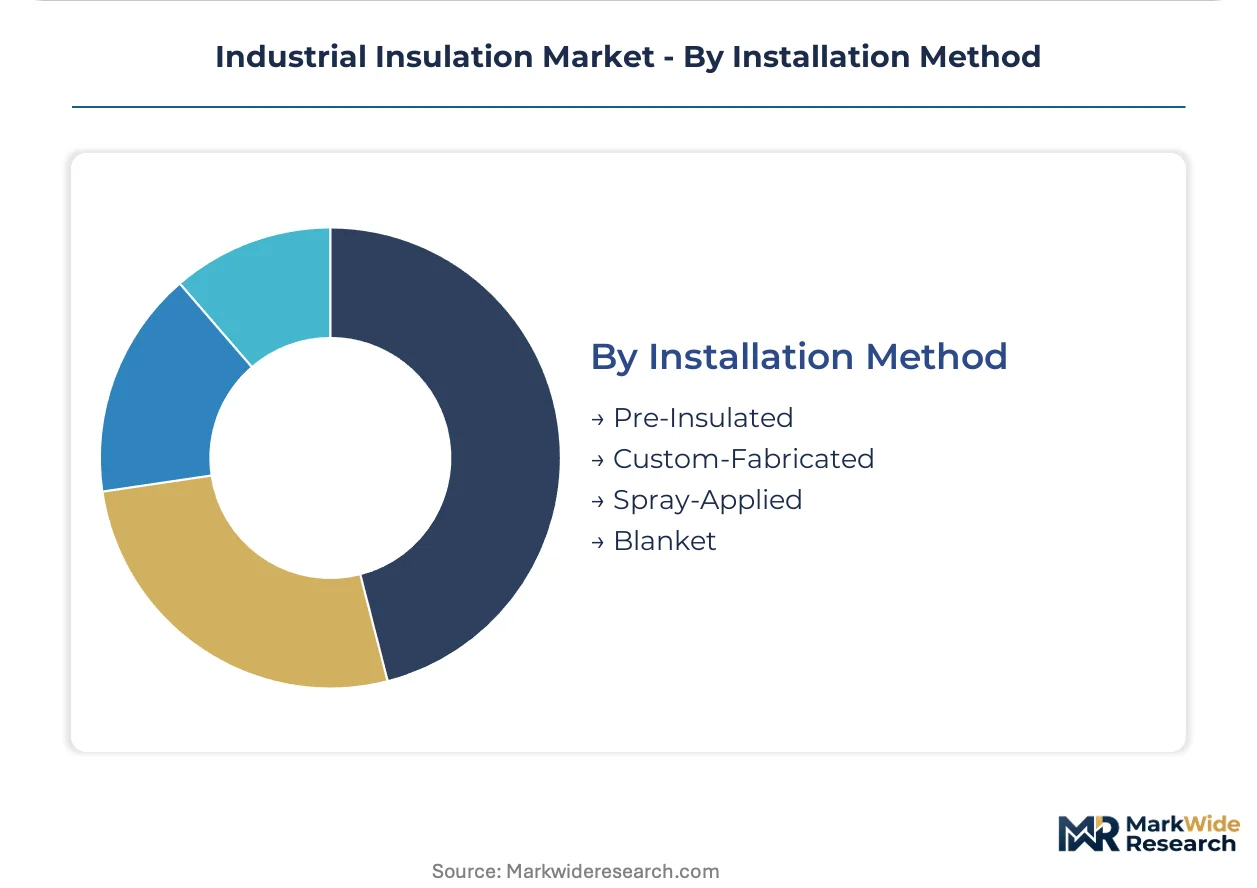
Installation Method:
Volume concentration favors field-applied blanket systems in maintenance environments, while prefabrication channels expand through MRO distribution partnerships and direct OEM supply agreements.
- Blanket:Flexible mineral wool and fiberglass wraps conform to complex geometries in field conditions. Knauf Insulation's distribution push into emerging industrial zones targets this installation category.
- Pre-Insulated:Factory-applied insulation on pipe spools and equipment modules reduces site labor requirements. Modular construction trends in Middle Eastern petrochemical projects favor this method.
- Custom-Fabricated:Removable covers and shaped segments fit specific equipment dimensions. Lifecycle service contracts increasingly bundle custom fabrication with predictive maintenance.
- Spray-Applied:Polyurethane and ceramic coatings access confined spaces where board or blanket systems cannot fit. Application requires certified contractor networks that cluster in established energy corridors.
Blanket installation dominates maintenance volumes; pre-insulated systems expand fastest on modular construction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial insulation consumption patterns diverge sharply by geography: mature markets emphasize retrofit-driven thermal efficiency upgrades, while emerging economies prioritize newbuild capacity in expanding industrial corridors.
United States
Combined-cycle power plant retrofits and refinery insulation replacements dominate demand volumes. EPA emissions standards mandate thermal efficiency upgrades across Gulf Coast petrochemical clusters. Houston and Corpus Christi anchor contractor networks where certified installer scarcity extends project timelines.
Germany
Chemical processing complexes drive specification for high-temperature stone wool systems. REACH authorization deadlines for boron compounds and formaldehyde binders force 2025-2027 formulation transitions. Ludwigshafen and Leverkusen industrial zones concentrate reformulation validation activity.
India
Steel and petrochemical capacity expansion under PLI incentives accelerates mineral wool absorption. BIS certification requirements and Bureau of Energy Efficiency consumption norms tighten compliance for imported systems. Gujarat and Maharashtra industrial parks concentrate domestic manufacturing investment.
Saudi Arabia
Petrochemical newbuild projects specify pre-formed calcium silicate pipe covers for high-temperature steam distribution. Domestic content requirements in Vision 2030 frameworks localize supply chain development. Jubail and Yanbu industrial cities anchor Middle Eastern demand concentration.
China
Dual carbon goals and MIIT energy efficiency standards compress allowable heat loss rates across process industries. Yangtze River Delta chemical complexes retrofit legacy steam lines where space constraints favor advanced thin-profile materials. Shanghai and Ningbo clusters dominate specification authority.
Industrial Insulation Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial insulation supply. Owens Corning and ROCKWOOL Insulation A/S occupy the upper tier through manufacturing scale and formulation breadth, while regional fabricators and application specialists fill mid-market and niche segments. Three archetypes define competitive positioning: integrated material-scaling leaders, high-temperature formulation specialists, and prefabrication-focused distributors. Capacity expansion and lifecycle service contracting represent the dominant competitive vectors as procurement criteria shift from unit pricing to thermal performance guarantees.
Among North American and European material-scaling leaders, Owens Corning, ROCKWOOL Insulation A/S, and Knauf Insulation exemplify divergent strategic postures. Owens Corning represents the fiberglass-centric archetype with refinery supply agreement anchoring. ROCKWOOL Insulation A/S occupies the high-temperature stone wool specialist position. Knauf Insulation sits within the distribution-expansion archetype targeting emerging industrial zones with prefabricated systems. These three collectively illustrate how scale, temperature capability, and channel strategy segment competitive terrain.
| Leading Market Players |
|---|
| Owens Corning |
| ROCKWOOL Insulation A/S |
| Knauf Insulation |
| Morgan Advanced Materials plc |
| 3M |
| Saint-Gobain ISOVER |
| Johns Manville |
| Aspen Aerogels, Inc. |
| Unifrax |
| Others |
Supply Flow & Price Mechanics
Ninety-day binder resin inventories at European mineral wool producers amplify pricing power asymmetries between integrated manufacturers and formulation-dependent specialists. Long-term supply agreements with Gulf Coast refineries insulate Owens Corning from phenolic resin volatility that compresses margins at smaller competitors.
Pricing Analysis
Long-term offtake contracts anchor pricing stability for power generation retrofits, while spot-market exposure concentrates in project-based chemical plant procurement. Three-tier pricing structure across premium, standard, and economy levels separates aerogel-enhanced systems from conventional mineral wool wraps and commodity fiberglass batts. Cost compression in standard-grade mineral wool intensifies as Indian PLI-supported domestic capacity scales. EPC contractors driving newbuild petrochemical projects exhibit highest price sensitivity; owner-operators with lifecycle service contracts prioritize thermal performance guarantees over unit material costs.
Supply Chain Analysis
Sixty-day shipping windows from Chinese boron compound suppliers extend formulation validation timelines for REACH-compliant European manufacturers. Supply concentrates in China for processed silica aerogel precursors, the United States for fiberglass manufacturing, and India for expanding stone wool capacity under PLI incentives. Synthetic binder formulations rest on petrochemical feedstock cycles from South Korean and Saudi Arabian resin producers. Single-source vulnerability sits with Chinese processed mineral additives. Distribution runs through MRO channel partnerships for maintenance volumes and direct OEM supply agreements for newbuild modular construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer scarcity across emerging industrial corridors constrains project execution velocity and consolidates contracting power with established energy corridor networks. Material suppliers must secure installation capacity before specification authority shifts to integrated service providers.
For Market Incumbents: Fortify installation capacity through captive certification programs or exclusive contractor partnerships before aerogel specialists capture lifecycle service contracts. Backward integration into synthetic resin production hedges petrochemical feedstock volatility threatening mineral wool margins. Prioritize REACH-compliant binder validation ahead of 2025-2027 sunset deadlines to defend EU market positioning.
For New Entrants and Emerging Players: Lead with thin-profile aerogel systems targeting space-constrained refinery retrofits where conventional wraps cannot fit. India's industrial park expansion under PLI incentives offers the most penetrable geography for new manufacturing footprint. Pursue direct OEM supply agreements with electrolyzer fabricators specifying dual-temperature insulation for hydrogen infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction-material parents with underoptimized industrial insulation divisions lacking lifecycle service contracting capabilities. Five-to-ten year viability hinges on carbon accounting integration under CSRD and evolving ISO standards. Watch for BIS certification enforcement accelerating import substitution in Indian industrial corridors as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Resins | Captive binder supply insulates Owens Corning and ROCKWOOL from petrochemical feedstock cycles compressing competitor margins. |
| Lifecycle Service Contracting | Multi-year thermal performance guarantees consolidate vendor relationships with US Gulf Coast refinery operators prioritizing total cost of ownership. |
| Carbon Accounting Data Integration | Verified embodied carbon reporting under CSRD elevates procurement criteria beyond first-cost optimization for EU Green Deal compliance. |
| Prefabricated Modular Systems | Factory-applied insulation on pipe spools reduces site labor requirements for Middle Eastern petrochemical newbuild projects. |
| Dual-Temperature Formulation Development | Multi-layer systems addressing cryogenic and high-temperature service capture specification openings at electrolyzer and ammonia synthesis facilities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Bureau of Energy Efficiency consumption norm disclosures. Primary interviews with plant engineers at US Gulf Coast refineries, procurement leads at Indian steel complexes under PLI schemes, EPC contractors specifying Middle Eastern petrochemical projects, and technical R&D directors at European formulation labs inform demand-side validation. Bottom-up triangulation across product-type shipment volumes and top-down reconciliation against end-use capital expenditure cycles ensure cross-verified outputs.
Segmentation dimensions modeled include material chemistry, thermal service temperature tier, installation method, and end-use industry vertical across the projection horizon. CAGRs derive from regression analysis of historical retrofit cycles against regulatory compliance deadlines and capacity expansion announcements. Forecast inputs incorporate REACH authorization sunset timelines for boron compound binders and MIIT energy efficiency standard enforcement trajectories in Chinese chemical processing clusters.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding or accelerated EU Green Deal implementation would require recalibration. Forecasts reflect documented assumptions regarding certified labor pool expansion and raw material price normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market