
 Roofing Underlying Materials Market | 2026-2036
Roofing Underlying Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Underlying Materials Market Outlook
Multi-family housing developers and institutional property managers are redrawing procurement priorities for roofing underlying materials, shifting volume toward higher-performance synthetic systems. GAF leverages its integrated shingle-underlayment bundling to capture contractor loyalty across the residential channel. Owens Corning sustains manufacturing scale advantages in fiberglass-reinforced mats that feed both its own underlayment lines and third-party converters. Soprema Group specializes in self-adhered membrane technology for commercial flat-roof applications where labor scarcity drives demand for faster installation.
Roofing underlying materials constitute water-resistant or waterproof barriers installed between the roof deck and the primary roofing cover, typically manufactured from organic felts saturated with asphalt, polymer-modified synthetics, or rubberized asphalt composites ranging from 15 to 50 mils in thickness. Their primary purpose is to provide temporary weather protection during construction and permanent secondary drainage plane defense against wind-driven rain and ice dam infiltration. Synthetic underlayment leads product type value generation due to lighter roll weights and extended UV exposure tolerance that reduce contractor callback liability. Self-adhered technology commands premium positioning in coastal and northern climate zones where peel-and-stick installation eliminates torch or hot-mop safety protocols. Residential end use anchors volume throughput, though commercial specifications are migrating toward multi-ply membrane systems with longer warranty terms.
FEMA building codes in U.S. coastal counties, IECC energy efficiency standards, and OSHA fall-protection regulations collectively elevate product performance minimums and installation training burdens for contractors. The EPA's National Pollutant Discharge Elimination System influences membrane specification in commercial projects where stormwater retention integrates with roof assembly design. Stakeholders must monitor evolving state-level amendments to the International Building Code that accelerate synthetic underlayment mandates in high-velocity wind zones.
Market Dynamics
Synthetic underlayment is displacing organic felt across North American residential re-roofing as contractors prioritize lighter roll weights and extended UV tolerance during extended construction timelines.
Growth Catalysts
- FEMA High-Velocity Wind Zones:Coastal county building codes now mandate enhanced secondary water barriers, accelerating synthetic underlayment specifications in hurricane-prone Florida and Gulf Coast states.
- IECC Energy Efficiency Standards:Tightening moisture-barrier requirements in climate zones 4 through 8 are forcing specification upgrades across multi-family housing developments.
- Sun Belt Metro Corridors:Residential construction volume in Texas, Arizona, and Nevada is concentrating demand for self-adhered membrane systems with faster installation profiles.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil markets, compressing margins for synthetic underlayment manufacturers.
- Specialized Labor Scarcity:Self-adhered and multi-ply membrane installation requires certified contractors, creating bottlenecks in markets with limited training infrastructure.
- OSHA Fall-Protection Compliance:Elevated installation training burdens and equipment requirements add cost layers that slow residential retrofit adoption.
Strategic Opportunities
- Commercial Flat-Roof Convergence:Labor scarcity is driving demand for peel-and-stick self-adhered membranes that eliminate torch-application safety protocols.
- Stormwater Integration Mandates:EPA National Pollutant Discharge Elimination System guidelines are creating specification pathways for membrane systems in commercial projects with retention requirements.
- Institutional Property Management:Extended warranty terms and lifecycle cost modeling are opening multi-ply system adoption in healthcare and education verticals.
Industry Challenges
- State-Level Code Fragmentation:Amendments to the International Building Code vary by jurisdiction, forcing manufacturers to maintain multiple product SKUs for compliance.
- Contractor Certification Timelines:Extended training programs for self-adhered and synthetic systems delay workforce scaling in high-demand markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Underlying Materials Market |
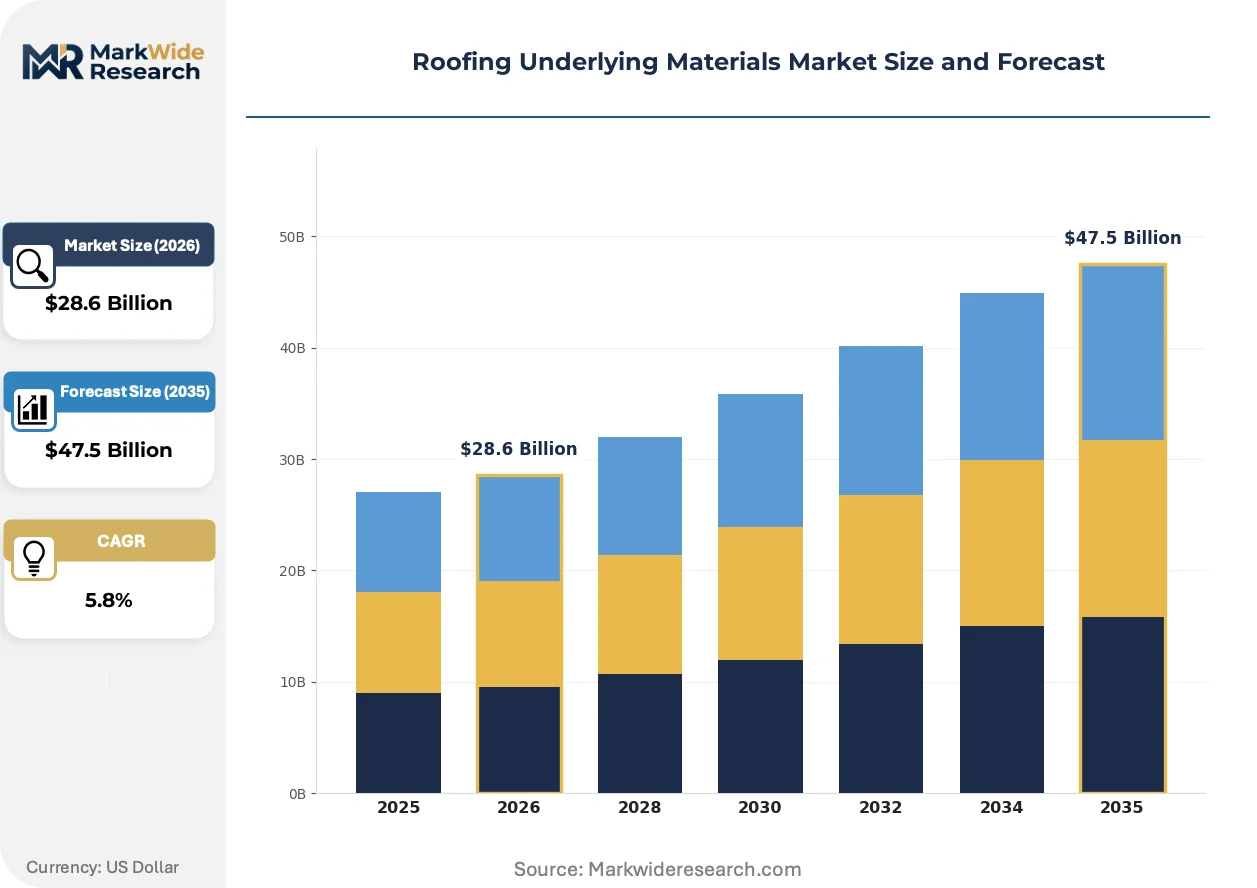
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Felt, Synthetic Underlayment, Ice & Water Shield, Roof Membrane Technology: Standard, Self-Adhered, Hot-Mopped, Cold-Process End Use: Residential, Commercial, Industrial, Agricultural Installation Method: Sheet Installation, Roll Installation, Panel Installation, Tile Installation |
| Companies Covered | GAF, DuPont, Carlisle, Soprema Group, Renolit, Sika, CertainTeed, Owens Corning, TAMKO Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Underlying Materials Market Strategic Shifts
Material science advances and installation-method evolution are compressing project timelines while elevating performance minimums across residential and commercial segments.
Polymer-modified synthetic underlayment is bifurcating the residential market between premium extended-UV products and economy-grade alternatives. Large-scale homebuilders in Texas and Arizona are specifying 180-day UV-rated synthetics for phased construction schedules. This technology split is compressing organic felt to price-sensitive repair segments while capturing margin in new construction.
EPA stormwater management guidelines are reshaping commercial membrane specification. The National Pollutant Discharge Elimination System now influences roof assembly design where stormwater retention integrates with underlying barrier selection. Multi-ply membrane systems with enhanced drainage planes are capturing specification share in California and Northeastern commercial retrofits.
Contractor purchasing behavior is consolidating around bundled shingle-underlayment offerings. National distributors are responding with private-label synthetic lines that bypass traditional brand premiums. This channel compression is most visible in Florida and coastal Georgia, where hurricane-season demand spikes reward inventory availability over manufacturer loyalty.
Roofing Underlying Materials Market Segmentation
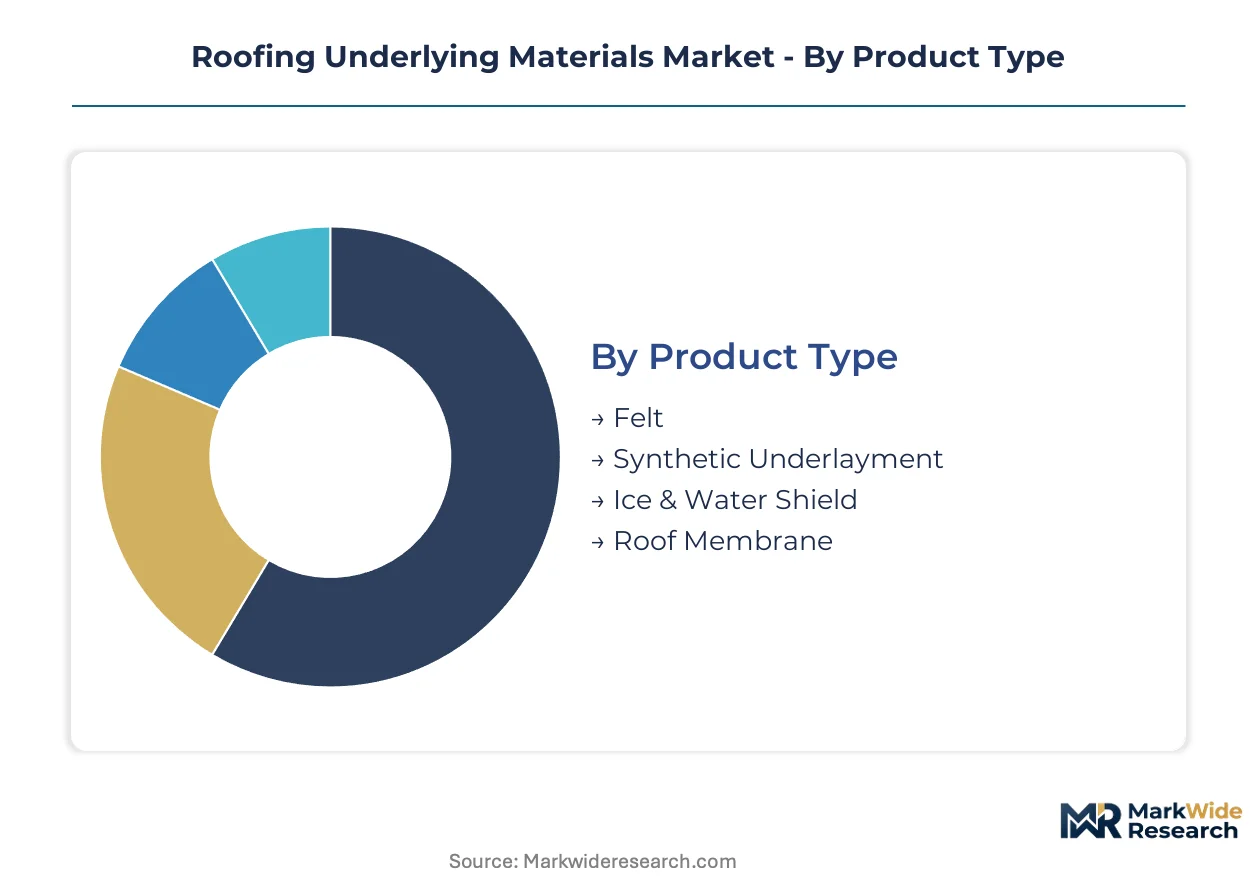
Roofing underlying materials fragment across four distinct axes that shape procurement patterns and margin structures. Product type and technology choices determine performance tiers and regulatory compliance, while end-use and installation method dictate channel access and labor requirements. Understanding these intersections reveals where specification power concentrates and where substitution risks emerge.
Product Type:
Domestic production dominates felt and synthetic underlayment, while ice and water shield and specialized roof membranes draw heavier import dependence from European and Asian manufacturers.
- Felt:Organic mats saturated with asphalt remain the legacy standard for economy residential repairs and temporary weather protection. Demand concentrates in price-sensitive Midwest and rural markets where contractors prioritize material cost over extended UV tolerance. IECC code upgrades in climate zones 4 through 8 are accelerating displacement toward synthetic alternatives.
- Synthetic Underlayment:Polypropylene and polyethylene woven laminates deliver lighter roll weights and 180-day UV exposure ratings that reduce callback liability for phased construction timelines. Sun Belt metro corridors in Texas, Arizona, and Nevada specify these systems for multi-family developments where labor efficiency outweighs material premiums.
- Ice & Water Shield:Rubberized asphalt composites with self-adhered backing target northern climate zones and coastal counties where ice dam infiltration and wind-driven rain demand redundant drainage planes.
- Roof Membrane:Multi-ply modified bitumen and TPO systems serve commercial flat-roof applications requiring 20-year warranty terms and integrated stormwater management.
Felt commands the established base. The steepest expansion runs through synthetic underlayment.
Technology:
Cost tier stratification separates premium self-adhered systems from economy standard applications, with hot-mopped and cold-process technologies occupying mid-market commercial positioning.
- Standard:Mechanically fastened felts and synthetics rely on cap nails and staples, demanding lower-skilled labor but sacrificing wind uplift resistance. Residential re-roofing in inland markets maintains volume here.
- Self-Adhered:Peel-and-stick membranes eliminate torch-application hazards and accelerate installation in labor-scarce markets. FEMA high-velocity wind zone mandates in Florida and Gulf Coast counties are concentrating demand for this technology.
- Hot-Mopped:Asphalt kettle application persists in commercial built-up roofing where substrate conditions demand fluid-applied adhesion.
- Cold-Process:Solvent-based adhesives serve repair and retrofit segments where open-flame restrictions prohibit torch or hot-mop methods.
Standard technology anchors volume throughput. Self-adhered systems are climbing the fastest as coastal code mandates tighten.
End Use:
Application context determines performance specifications, with residential segmenting into single-family versus multi-family procurement patterns and commercial dividing between new construction and retrofit warranty requirements.
- Residential:Single-family re-roofing drives felt-to-synthetic substitution in North American markets, while multi-family developers specify extended-UV synthetics for phased construction schedules. FEMA secondary water barrier mandates in coastal counties are reshaping material selection.
- Commercial:Flat-roof membrane systems with 15-30 year warranty terms dominate healthcare, education, and institutional verticals where lifecycle cost modeling overrides first-cost considerations.
- Industrial:Chemical-resistant membranes and high-temperature underlayment serve manufacturing facilities with process exhaust and ventilation integration requirements.
- Agricultural:Economy-grade felts and standard synthetics protect barns, storage facilities, and processing buildings where functional coverage outweighs aesthetic or warranty priorities.
Residential end use holds the volume base. Commercial applications are gaining share fastest on extended warranty adoption.
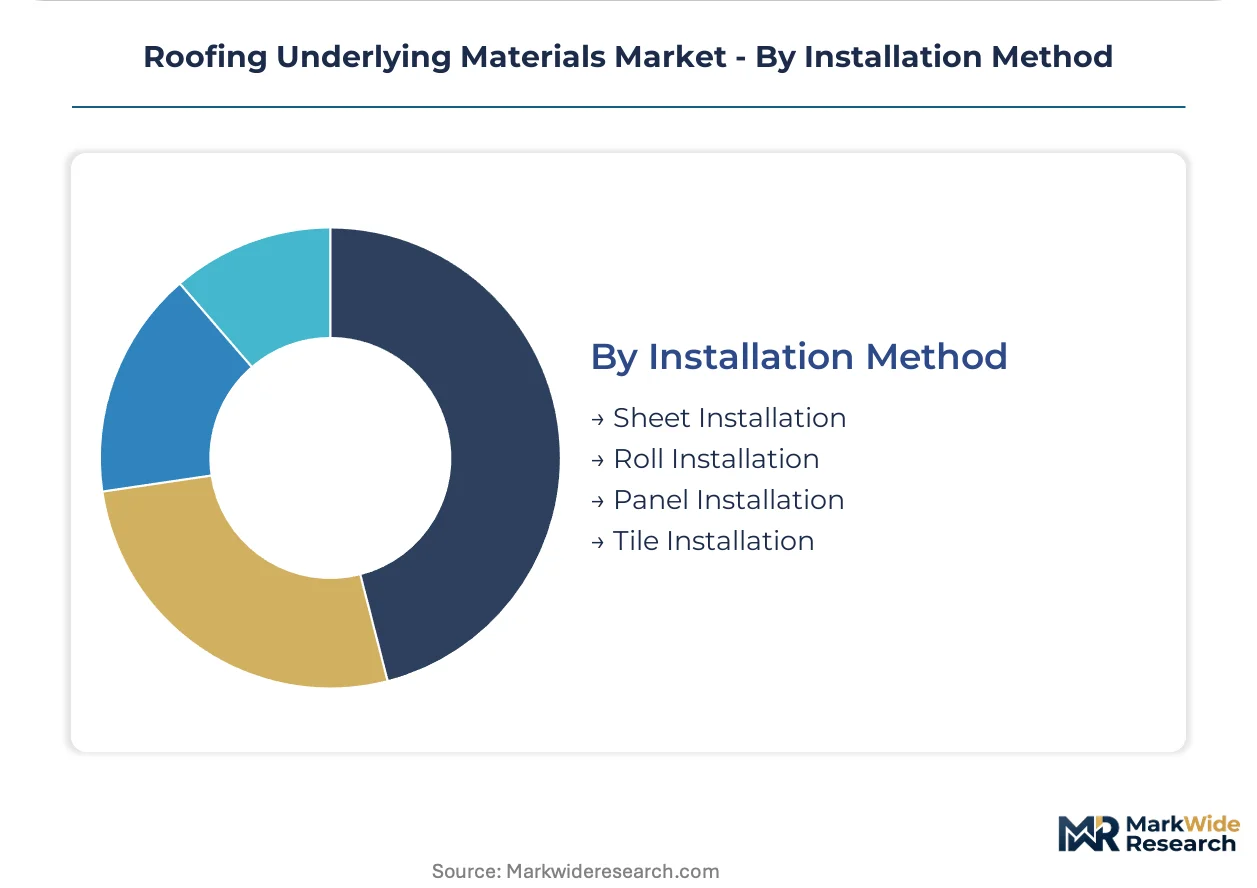
Installation Method:
Customer type fragmentation separates contractor-preferred roll formats from OEM-integrated panel systems and specialized tile applications.
- Sheet Installation:Cut-to-fit membrane sheets serve commercial flat-roof applications where field welding and seaming create monolithic drainage planes.
- Roll Installation:Continuous synthetic and felt rolls dominate residential steep-slope roofing, with 10-square and 20-square formats optimizing contractor handling efficiency.
- Panel Installation:Pre-cut underlayment panels integrate with modular roofing systems and prefabricated construction methods, gaining traction in multi-family and hospitality verticals.
- Tile Installation:Specialized underlayment for clay, concrete, and slate tile roofs requires enhanced puncture resistance and batten spacing compatibility.
Roll installation commands the established base. Panel installation shows the steepest expansion trajectory on prefabrication trends in multi-family construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane manufacturers export modified bitumen systems to Gulf Coast contractors facing FEMA secondary water barrier mandates. This trade corridor channels European self-adhered technology into hurricane-prone U.S. markets where installation speed outweighs material premiums.
United States
Florida and Texas metro corridors concentrate residential re-roofing volume as Sun Belt migration accelerates housing starts. EPA stormwater management guidelines tighten commercial membrane specifications in California and Northeastern states. Houston and Phoenix contractors specify extended-UV synthetic underlayment for phased multi-family construction timelines.
Germany
Industrial flat-roof retrofit demand drives specification of multi-ply membrane systems with integrated drainage planes. REACH chemical regulations constrain solvent-based adhesive formulations, pushing cold-process technology toward waterborne alternatives. The Rhine-Ruhr industrial corridor anchors manufacturing scale for exports to Nordic and Eastern European markets.
China
Urban renewal programs in tier-one cities generate commercial roofing replacement volume for TPO and modified bitumen systems. GB standards for building energy efficiency tighten moisture-barrier requirements in climate zones with high summer humidity. The Yangtze River Delta manufacturing cluster supplies synthetic underlayment for domestic residential construction and Southeast Asian export markets.
India
Commercial real estate development in Mumbai and Bangalore concentrates demand for single-ply membrane systems with 15-year warranty terms. BIS certification requirements for construction materials elevate import substitution pressures on European and Chinese suppliers. Gujarat's petrochemical corridor feeds domestic polypropylene resin production for emerging synthetic underlayment manufacturing.
Brazil
São Paulo's industrial warehouse construction anchors membrane demand for self-adhered systems that eliminate torch-application hazards. ANVISA building material regulations align with international fire-safety standards, accelerating specification of peel-and-stick technologies. The São Paulo-Minas Gerais corridor concentrates distributor networks serving commercial retrofit and new construction segments.
Roofing Underlying Materials Market Competitive Environment
Player mix skews toward integrated building materials conglomerates with captive shingle-underlayment bundling capabilities. The competitive structure tiers across three strata: national distributors with private-label synthetic lines, specialized membrane manufacturers with self-adhered technology focus, and petrochemical-integrated producers controlling resin feedstock costs. Dominant competitive moves include backward integration into polypropylene resin production and strategic partnerships with multi-family housing developers for specification lock-in.
Among North American building materials specialists, GAF and Owens Corning exemplify the integrated conglomerate archetype with bundled product offerings. Soprema Group represents the specialized membrane manufacturer positioning. These three anchors illustrate how competitive advantage concentrates in contractor channel relationships and specification influence with institutional property managers.
| Leading Market Players |
|---|
| GAF |
| DuPont |
| Carlisle |
| Soprema Group |
| Renolit |
| Sika |
| CertainTeed |
| Owens Corning |
| TAMKO Building Products |
| Others |
Value Chain & Pricing Dynamics
Polymer-modified synthetic underlayment displacing organic felt simultaneously redraws supply geography toward Gulf Coast petrochemical corridors and compresses pricing economics across three performance tiers. This substitution dynamic concentrates resin sourcing leverage with integrated producers while fragmenting margin capture between premium UV-rated systems and economy-grade alternatives.
Pricing Analysis
Current-generation synthetic underlayment commands a material premium over prior-generation organic felt, while next-generation self-adhered membranes with extended UV ratings extract further value in coastal markets. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UV exposure rating, FEMA wind-zone certification, and contractor bundling arrangements. Price erosion runs through economy-grade felt as IECC code upgrades accelerate displacement, though margins are tightening for mid-tier synthetics facing private-label competition. Single-family residential contractors exhibit highest price sensitivity, while institutional property managers prioritize lifecycle cost over first-cost considerations.
Supply Chain Analysis
Just-in-time inventory strategies dominate residential distribution, while strategic stockpiling of synthetic underlayment concentrates in Florida and Texas ahead of hurricane season demand spikes. Manufacturing draws from polypropylene resin production in the United States, Germany, and China, with woven laminate fabrication anchored in domestic facilities serving regional construction corridors. Supply chain risk centers on petrochemical feedstock volatility tied to crude oil price swings, creating margin compression exposure for non-integrated manufacturers. Distribution runs through national building materials distributors with private-label bypass capabilities, supplemented by direct contractor relationships from integrated shingle-underlayment bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level building code amendments creates niche specification opportunities as contractors navigate varying FEMA wind-zone mandates and IECC climate zone requirements. This demand-side code heterogeneity rewards agile product portfolio management over scale-driven standardization.
For Market Incumbents: Compound channel loyalty through integrated shingle-underlayment bundling that locks contractor specification habits before private-label alternatives capture shelf space. Prioritize backward integration into polypropylene resin production to defend margin position against petrochemical volatility. Invest in certified installer training infrastructure to create switching costs around self-adhered membrane specifications in FEMA-mandated coastal counties.
For New Entrants and Emerging Players: Extended-UV synthetic underlayment for phased multi-family construction in Sun Belt metro corridors represents an underserved service layer where national distributors lack technical sales support. Target Texas and Arizona homebuilders with direct specification relationships, bypassing traditional roofing contractor channels. Lead with 180-day UV rating certification and rapid sample fulfillment to differentiate from inventory-constrained incumbents during seasonal demand spikes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional membrane manufacturers possessing FEMA-certified product lines but lacking national distribution scale. Five-to-ten-year viability hinges on consolidation capture of code-driven specification upgrades rather than commodity volume growth. Monitor state-level International Building Code amendment calendars as inflection indicators for synthetic underlayment mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captures margin compression defense against crude oil price volatility for synthetic underlayment producers. |
| Certified Installer Training Program Expansion | Creates specification lock-in with contractors facing OSHA fall-protection compliance burdens and self-adhered certification requirements. |
| Private-Label Synthetic Underlayment Launch | Bypasses brand premiums through national distributor relationships in hurricane-prone Florida and Georgia markets. |
| Multi-Ply Membrane System Development | Captures commercial flat-roof specifications where EPA stormwater integration mandates elevate warranty requirements. |
| Geographic Manufacturing Footprint Expansion | Reduces delivery cost differentials in Texas and Arizona Sun Belt corridors with concentrated multi-family construction volume. |
Study Parameters
A spread of perspectives from roofing contractors, multi-family housing developers, institutional property managers, and building materials distributors converged on the working assumptions underlying this analysis. Primary field engagement with certified installers in Florida, Texas, and California informed specification behavior and code compliance burden assessment. Secondary validation drew from EPA stormwater management guidelines, FEMA building code documentation, IECC climate zone standards, and SEC filings from publicly traded building materials conglomerates. Bottom-up volume estimates by product type and installation method triangulated against top-down construction spending data across residential and commercial end uses.
Segmentation dimensions modeled include product type hierarchy, technology generation, end-use application context, and geographic regulatory cluster across the analysis window. Analytical framework projected value expansion by mapping specification upgrade trajectories from felt to synthetic underlayment against housing start concentrations in hurricane-prone and Sun Belt markets. CAGRs were derived from elasticity-adjusted demand curves incorporating contractor purchasing behavior shifts and distributor inventory cycle patterns. Forecast inputs integrated petrochemical feedstock cost trajectories and state-level code amendment pipelines.
Underlying assumptions cover sustained IECC energy code tightening and FEMA wind-zone mandate expansion, with deviation risk concentrated in petrochemical price volatility and contractor certification bottleneck severity. Forecasts reflect these documented assumptions with explicit scenario weighting. Revision becomes warranted when state-level code adoption rates or resin cost trajectories cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market