
 Global Electrical Insulation Materials Market | 2026-2036
Global Electrical Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Insulation Materials Market Intelligence
A divergence in capital allocation for developing high-temperature, high-voltage materials is rotating competitive advantage toward specialized producers. DuPont de Nemours, Inc. leverages its polymer science leadership to offer advanced films and laminates. Elantas GmbH specializes in liquid insulating resins and varnishes for motors and transformers. Weidmann Electrical Technology AG dominates the cellulose-based insulation segment for power transformers.
Electrical insulation materials are dielectrics engineered to resist the flow of electric current, characterized by critical properties like high dielectric strength and thermal stability. Their primary industrial function is to prevent short circuits, ensuring the operational safety and longevity of electrical components. Epoxy resins and polyimide films lead the material segments due to superior performance in demanding conditions. The transformers and electric motors application segments drive significant volume, requiring robust insulation for high-voltage reliability.
International Electrotechnical Commission (IEC) standards define global performance and testing protocols. Concurrently, regulations like the European Union’s RoHS directive and rules from the US EPA restrict hazardous substances, directly influencing material formulation. Supplier success depends on aligning product portfolios with stricter thermal management needs in new applications and evolving regional chemical compliance mandates.
Market Dynamics
The electrification of transportation and the expansion of renewable energy grids represent the central structural force shaping the market. This creates a dual demand for materials that can simultaneously manage higher voltages and withstand elevated operating temperatures, pulling innovation toward specialized, high-performance polymers and composites.
Growth Catalysts
- Grid Modernization Programs:Government initiatives in the United States and Europe, such as the US Inflation Reduction Act (IRA), are channeling investment into upgrading electrical grids and EV charging infrastructure, directly increasing consumption of insulation for transformers and switchgear.
- Advanced Power Electronics:The adoption of wide-bandgap semiconductors like silicon carbide (SiC) in solar inverters and EV powertrains necessitates insulation materials with superior thermal conductivity and dielectric strength to handle higher switching frequencies and temperatures.
- UHV Transmission Expansion:China's continued build-out of ultra-high-voltage (UHV) power transmission networks to connect remote renewable energy sources creates sustained, large-scale demand for specialized transformer board and high-voltage bushings.
Market Restraints
- Raw Material Volatility:The pricing of essential precursors for epoxy resins and polyimide films, which are derived from crude oil, is subject to significant volatility, creating margin uncertainty and complicating cost management for material converters.
- Performance Limits of Traditional Materials:Cellulose-based insulation, a mainstay in oil-filled transformers, exhibits thermal degradation at temperatures required for next-generation compact and high-efficiency designs, limiting its use in advanced applications.
- Divergent Chemical Regulations:Navigating conflicting substance restrictions between frameworks like the EU's REACH and the US EPA's Toxic Substances Control Act (TSCA) increases compliance overhead and can delay the introduction of new material formulations to the market.
Strategic Opportunities
- Electrification of Aerospace:The development of more-electric and hybrid-electric aircraft creates a high-value niche for lightweight, flame-retardant insulation materials capable of performing reliably at high altitudes and across extreme temperature ranges.
- Bio-Based Dielectric Fluids:Growing OEM and utility focus on sustainability presents an opportunity for ester-based, biodegradable insulating liquids as environmentally superior alternatives to traditional mineral oil in transformers, particularly in sensitive locations.
- Insulation for Energy Storage:The rapid expansion of battery energy storage systems (BESS) opens a new application segment for materials providing thermal management and electrical insulation between battery cells and modules to ensure safety and prevent thermal runaway.
Industry Challenges
- Lengthy Qualification Cycles:The process for certifying new insulation materials under IEC and other international standards for high-voltage applications is extensive and costly, creating a significant time lag between innovation and commercial deployment.
- High Capital Investment:Manufacturing advanced polymer films and high-purity resins requires substantial capital expenditure for cleanroom facilities and precision processing equipment, posing a significant barrier to entry for new competitors.
- Specialized Talent Scarcity:A shortage of material scientists and chemical engineers with expertise in high-voltage dielectric phenomena and polymer formulation constrains the research and development capacity of manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Insulation Materials Market |
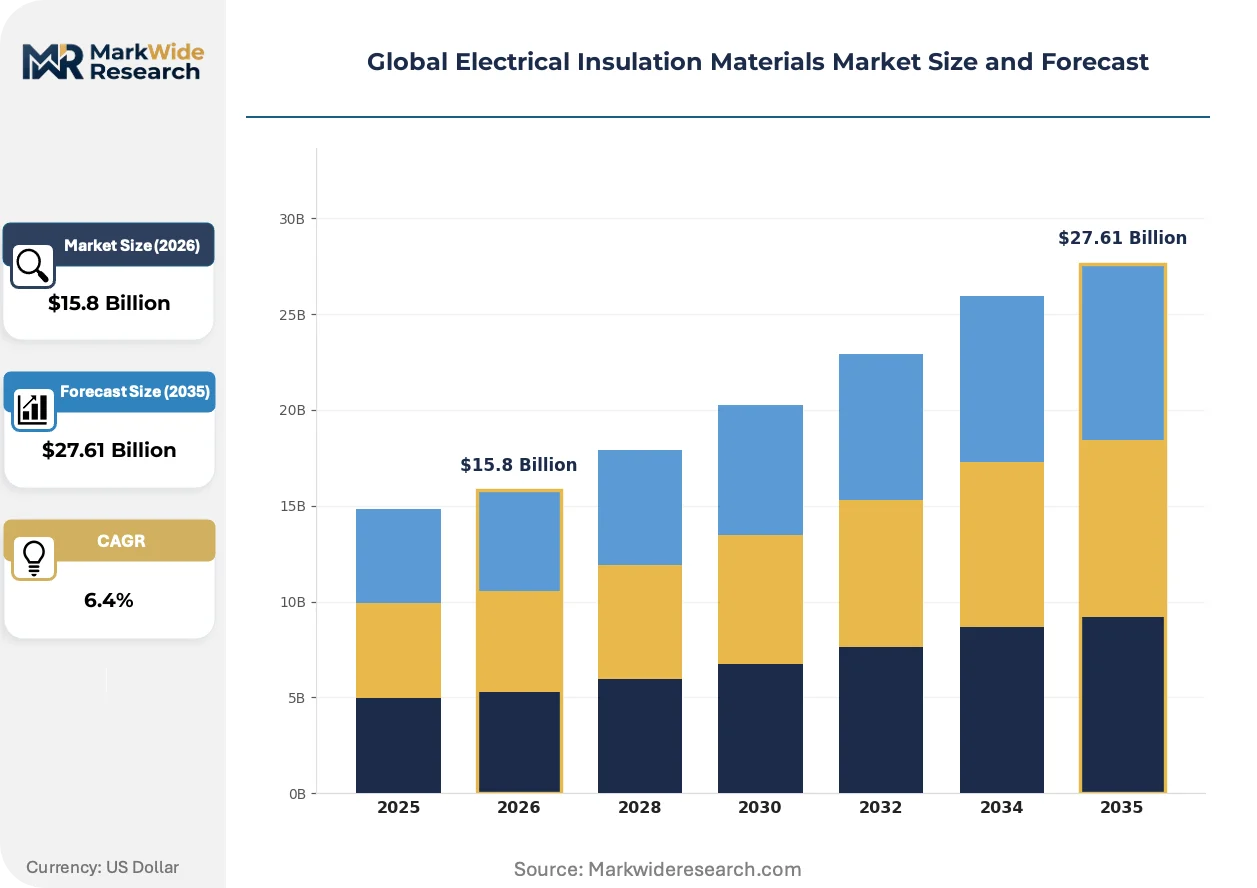
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyimide, Fiberglass, Ceramic, Mica, Epoxy Resin, Polytetrafluoroethylene Application: Transformers, Generators, Switchgear, Circuit Breakers, Motors, Capacitors End User: Renewable Energy Facilities, Telecommunications Providers, Aerospace Manufacturers, Power Distribution Companies, Electronics Assemblers Form: Films, Tapes, Coatings, Laminates, Boards, Sleeves |
| Companies Covered | Elantas GmbH, Toray Industries, Inc., DuPont de Nemours, Inc., Siemens AG, ABB, 3M Company, Hitachi, General Electric, Weidmann Electrical Technology AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Insulation Materials Market Strategic Shifts & Innovations
Concurrent pressures from regulatory compliance and performance escalation are accelerating material science innovation. The market is shifting from commoditized insulators toward engineered dielectric systems tailored for specific, demanding applications in power electronics and electrical infrastructure.
Advanced insulation materials with superior thermal management properties are a primary focus of product development. The power electronics sector, particularly for data centers and electric vehicles, is a key adopter of these new formulations. This technological push is miniaturizing components like DC-DC converters and on-board chargers, enabling greater power density within confined spaces.
The European Union's RoHS directive continues to influence material formulation globally. This regulation restricts the use of specific hazardous substances in electrical and electronic equipment, forcing suppliers to invest in R&D for compliant alternatives without compromising performance. The consumer electronics and automotive electronics segments are most affected, driving the phase-out of lead- and halogen-containing materials in solders and wire insulation.
A notable shift in purchasing criteria toward evaluating total cost of ownership is changing specification patterns. Equipment manufacturers in high-reliability sectors are moving beyond initial price, prioritizing insulation materials that enhance operational longevity and minimize the risk of costly failures. This trend is most pronounced in the renewable energy sector for wind turbine generators and in critical data center power distribution units.
Global Electrical Insulation Materials Market Segmentation
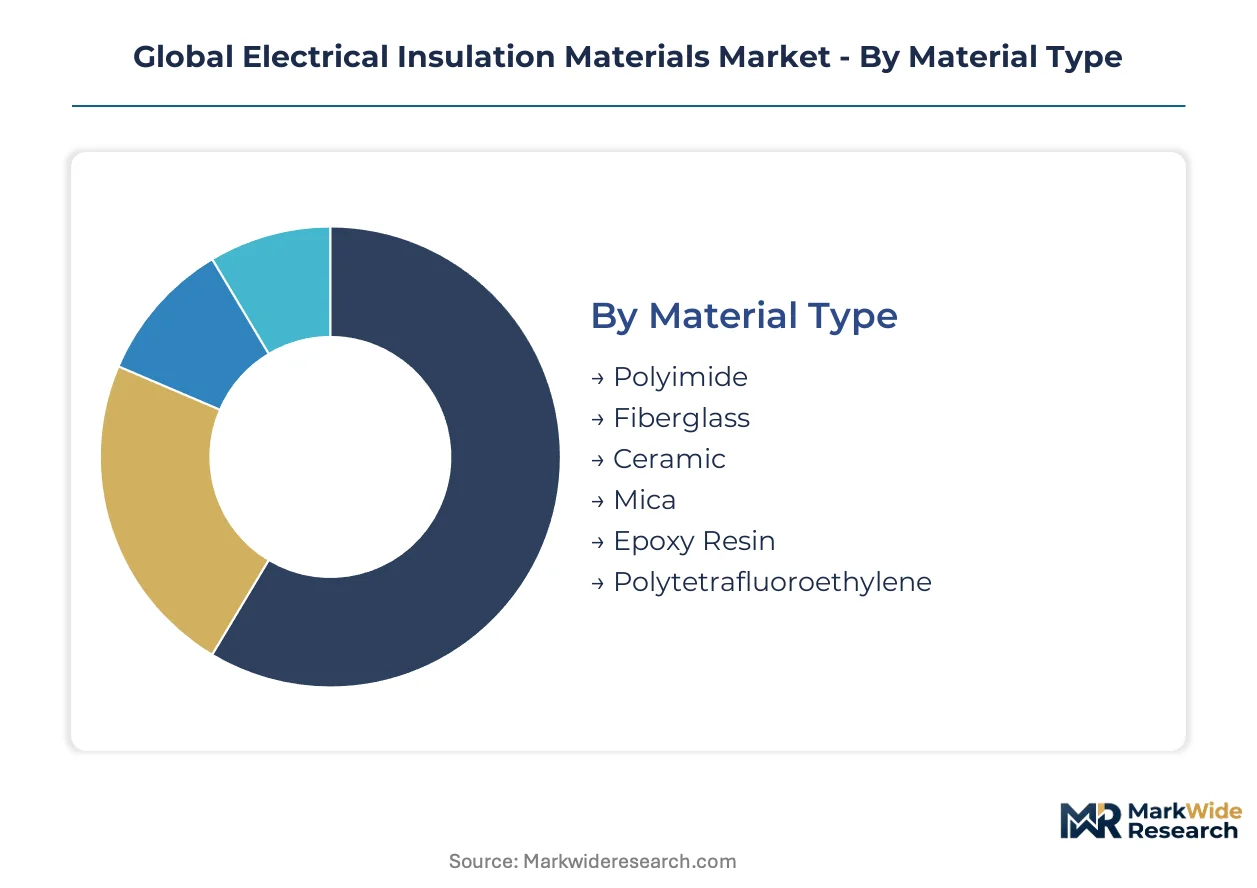
The segmentation of the global electrical insulation materials market delineates key product characteristics and application areas. This granular view helps identify concentrated demand and emerging technological needs across various industries, informing strategic product development.
Material Type:
Material type segmentation reveals how different compositions are distributed across various manufacturing channels. Suppliers channel specific materials to meet distinct performance criteria for electrical components.
- Epoxy Resin:These thermosetting polymers offer superior mechanical strength, dielectric properties, and high thermal stability. Demand concentrates in transformers and electric motors due to robust performance in high-voltage applications.
- Polyimide:Known for exceptional thermal resistance and dielectric strength, polyimide films maintain integrity across extreme temperatures. Aerospace electrification and advanced power electronics for EVs require these films.
- Fiberglass:Fine glass fibers provide good mechanical strength and thermal stability, often reinforcing composite insulation systems.
- Ceramic:Ceramic materials offer very high temperature resistance and excellent dielectric properties for specialized high-frequency applications.
- Mica:This natural mineral provides outstanding thermal and electrical insulation, processed into sheets for high-voltage motor and generator insulation.
- Polytetrafluoroethylene:PTFE exhibits excellent chemical resistance, low dielectric loss, and high temperature stability, valuable for wire and cable insulation.
Cellulose-based insulation dominates the installed base for traditional oil-filled transformers. Polyimide films are where expansion concentrates for next-generation power electronics.
Application:
Application segments are differentiated by the volume of insulation material consumed and specific performance demands of each apparatus. Each requires tailored properties for operational safety.
- Transformers:These devices require robust insulation to manage high voltages and prevent dielectric breakdown in UHV transmission networks. China's UHV build-out drives demand for transformer board.
- Electric Motors:Motors demand insulation with high thermal stability and dielectric strength to withstand operating temperatures. Electrification of transportation drives material consumption in EV powertrains.
- Generators:Large-scale power generators utilize high-performance insulation to protect windings.
- Switchgear:Insulation in switchgear prevents arcing and short circuits, critical for grid modernization programs.
- Circuit Breakers:These protective devices rely on insulation to isolate electrical faults and ensure rapid current interruption.
- Capacitors:Insulation films and coatings are essential in capacitors to store electrical energy efficiently.
The transformers application segment commands substantial material volume. Electric motors for electric vehicles represent the fastest-growing trajectory for insulation material consumption.
End User:
End-user segmentation reflects the distinct application environments and regulatory compliance needs of different industries. Each sector presents unique challenges for suppliers.
- Renewable Energy Facilities:Wind turbines and solar inverters require insulation managing higher voltages and elevated operating temperatures. The US Inflation Reduction Act (IRA) stimulates demand here.
- Power Distribution Companies:These utilities invest in insulation for grid modernization and ultra-high-voltage transmission networks. Upgrading electrical grids in Europe increases insulation consumption.
- Telecommunications Providers:Insulation materials protect sensitive electronic components in communication infrastructure.
- Aerospace Manufacturers:Electrification of aircraft creates a high-value niche for lightweight, flame-retardant insulation.
- Electronics Assemblers:This segment requires compliant insulation for consumer and automotive electronics, driven by the EU's RoHS directive.
Power distribution companies maintain foundational demand. Renewable energy facilities are climbing the fastest in adopting advanced dielectric solutions.
Form:
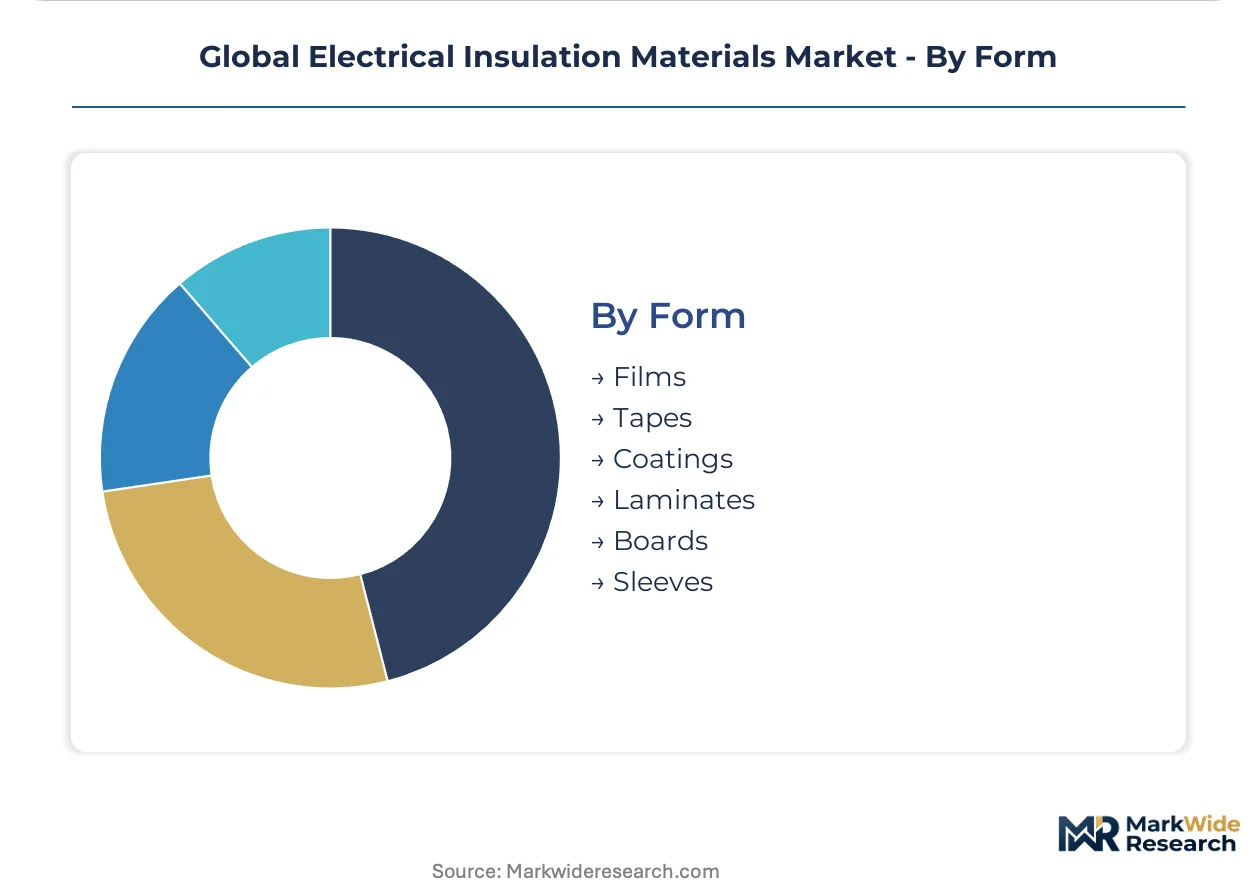
Form segmentation categorizes electrical insulation materials by their physical configuration and how they are applied. Each form serves specific functional requirements.
- Films:Thin, flexible sheets like polyimide films offer high dielectric strength and thermal stability. These are crucial for miniaturized components in advanced power electronics.
- Laminates:Multiple layers of insulating materials bonded together provide enhanced mechanical strength and dielectric performance. They are used in printed circuit boards.
- Tapes:Adhesive or non-adhesive tapes, often fiberglass or mica, provide flexible insulation for wrapping coils.
- Coatings:Liquid insulating resins and varnishes are applied to components, providing a protective dielectric layer. These improve thermal management and moisture resistance.
- Boards:Rigid insulating boards, often cellulose-based, are vital for structural support and electrical separation in large power transformers.
- Sleeves:Flexible tubular insulation, typically fiberglass or silicone, protects wire harnesses from abrasion.
Insulating boards represent a mature product form with long-standing applications. Films and coatings are gaining share fastest due to adaptability for high-density power electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Some applications exhibit high demand elasticity, where material cost significantly influences purchasing decisions. Other segments prioritize performance and reliability, demonstrating lower price sensitivity for specialized insulation materials. This divergence shapes regional investment and technology adoption patterns across the global market.
China
China's ultra-high-voltage (UHV) transmission expansion and massive electronics manufacturing drive significant demand for electrical insulation materials. The country's dual carbon goals push for energy-efficient solutions and advanced material development. The Yangtze River Delta region, with its dense concentration of electronics and power equipment manufacturers, is a focal point for material consumption.
United States
The United States sees substantial demand from grid modernization programs and the build-out of EV charging infrastructure. The US Inflation Reduction Act (IRA) channels investment into renewable energy and related electrical infrastructure, directly boosting insulation material consumption. California, a leader in renewable energy and electric vehicle adoption, drives innovation in advanced dielectric solutions.
Germany
Germany's advanced power electronics sector and robust automotive electrification initiatives generate strong demand for high-performance insulation. Compliance with the EU's RoHS directive influences material formulation, emphasizing compliant alternatives. Bavaria, a hub for industrial machinery and automotive research and development, features a high concentration of specialized material usage.
Japan
Japanese manufacturers require insulation for miniaturized electronics and high-precision industrial robotics, demanding materials with superior thermal and dielectric properties. Initiatives from METI promote energy efficiency and advanced material science research. The Kanto region, encompassing Tokyo, remains a critical center for high-tech manufacturing and component integration.
India
India's ongoing power distribution network upgrades and ambitious renewable energy projects create a substantial market for electrical insulation. The government's PLI scheme for electronics manufacturing stimulates domestic production and material demand. Maharashtra, a key industrial and automotive component production state, exhibits a growing need for robust insulation solutions.
Global Electrical Insulation Materials Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market's competitive structure. Integrated material science companies, specialized chemical producers, and focused component manufacturers represent distinct strategic archetypes. Capacity expansion and strategic partnerships are dominant competitive moves, alongside portfolio diversification to address emerging application needs.
Within the specialized producer tier, Elantas GmbH excels in liquid insulating resins and varnishes for electric motors and transformers. DuPont de Nemours, Inc., leveraging its polymer science leadership, offers advanced films and laminates for demanding applications. Weidmann Electrical Technology AG occupies a strong position in cellulose-based insulation for large power transformers.
| Leading Market Players |
|---|
| Elantas GmbH |
| Toray Industries, Inc. |
| DuPont de Nemours, Inc. |
| Siemens AG |
| ABB |
| 3M Company |
| Hitachi |
| General Electric |
| Weidmann Electrical Technology AG |
| Others |
Cost & Logistics Intelligence
Scale economies in manufacturing advanced polymer films and high-purity resins shape both supply concentration and price floors in the electrical insulation materials market. This dynamic favors specialized producers with established production capabilities, influencing overall market pricing.
Pricing Analysis
After-sales service and extended contracts drive lifetime value for specialized electrical insulation materials. The dominant pricing model is contract-based long-term offtake for high-reliability sectors, complemented by per-unit transactional pricing for commoditized products. Price differentiation stems from performance specifications, such as dielectric strength and thermal stability, and adherence to IEC certification levels. Pricing softness affects traditional cellulose-based materials due to performance limits in next-generation applications. Renewable energy facilities and aerospace manufacturers exhibit lower price sensitivity, prioritizing long-term operational reliability over initial cost.
Supply Chain Analysis
Port congestion and container availability impact inbound logistics costs for essential precursors. Geographic supply concentration for advanced materials centers on China for electronics manufacturing, Germany for specialized chemicals, and Japan for advanced films. The market draws from raw material dependencies including crude oil for epoxy resins and polyimide films, cellulose pulp, and mica. Raw material volatility, particularly crude oil prices, presents a significant structural supply chain risk. Distribution runs through direct sales channels to large original equipment manufacturers and specialized distributors for smaller-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical insulation materials market is at a platform-economics inflection, driven by the interoperability shift in integrated power electronics systems for EVs and renewable energy.
For Market Incumbents:Consolidate specialized production capabilities to reinforce market leadership in high-performance segments. Focus R&D on advanced polymers and composites that meet the stricter thermal management needs of UHV transmission and aerospace electrification. Invest in certification processes under IEC standards to navigate the threat of performance limits in traditional materials. Control key intellectual property for next-generation dielectric solutions to maintain competitive advantage against emerging entrants.
For New Entrants and Emerging Players:Differentiate on sustainability by developing bio-based dielectric fluids or specialized thermal management solutions for battery energy storage systems. Target the electrification of aerospace and energy storage as high-value, under-penetrated white spaces. Partner with OEMs in these emerging sectors for early material qualification and design-in opportunities. Focus on niche applications where existing materials struggle with extreme temperature ranges or weight constraints.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized material science firms with proprietary formulations. Long-term viability is driven by grid modernization and the electrification of transportation, ensuring sustained demand for advanced insulation. Identify niche players with strong R&D in wide-bandgap semiconductor insulation or bio-based dielectric fluids as prime acquisition targets. The accelerated qualification of new materials under IEC standards for UHV or EV applications serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports growing demand from EV and renewable energy sectors. |
| Green Manufacturing Transition | Addresses evolving EU RoHS and EPA chemical compliance mandates. |
| Long-term Supply Agreement | Secures critical raw materials amidst price volatility for epoxy resins. |
| Joint Venture | Accelerates R&D for high-temperature, high-voltage materials in China. |
| Technology Licensing | Expands reach of advanced film formulations into new application segments. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from published sources. Primary insights were gathered from R&D directors, procurement leads, application engineers, and regulatory compliance officers across the value chain. Secondary data included IEC standards documents, EU RoHS directives, US EPA reports, and company annual filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
The forecasting boundary extends across the analysis window, modeling market dynamics over the projection horizon. Segmentation dimensions included material type, application, end-user, form, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market forces, integrating inputs like grid modernization investment and EV production forecasts. This comprehensive framework enables robust market projections.
The analysis sits within stated boundaries; outcomes outside unforeseen raw material price spikes or rapid shifts in chemical compliance mandates would require recalibration. Forecasts reflect assumptions regarding current regulatory trajectories and technological development speeds. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Global Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Recyclable Thermal Insulation Packs Market