
 Moistureproof Glass Wool Market | 2026-2036
Moistureproof Glass Wool Market Size, Share, and Industry Trends Forecast 2026-2036
Moistureproof Glass Wool Market Insights
Aftermarket service revenue from insulation system audits and moisture-damage remediation is reshaping margin pools across the value chain. Owens Corning leverages its building science expertise to anchor premium positioning in building envelope solutions. Saint-Gobain Isover dominates European specification channels through controlled distribution networks. Johns Manville specializes in industrial-grade formulations that compete aggressively in power generation and petrochemical applications.
Moistureproof glass wool consists of fine glass fibers bonded with thermosetting resins and treated with hydrophobic silicone agents to achieve water repellency, typically manufactured via centrifugal spinning or flame attenuation processes to control fiber diameter between 3-7 microns and bulk density from 10 to 100 kg/m³. Its primary purpose is to deliver thermal resistance and acoustic absorption in environments where humidity, condensation, or direct water exposure would degrade standard glass wool performance. Blanket Rolls capture the largest volume share due to flexibility in retrofit wall and roof cavity installations, while Rigid Boards command superior margins in commercial facade systems where dimensional stability under load matters. Pipe Insulation represents the fastest-growing product category as district heating networks and industrial process lines expand across climate-sensitive geographies.
REACH compliance in Europe, EPA emissions guidelines in the United States, and China's GB standards for building materials collectively elevate barrier-to-entry for uncertified producers while steering procurement toward validated hydrophobic formulations. The EU F-Gas Regulation indirectly reinforces moistureproof glass wool demand by restricting synthetic foam alternatives in certain HVAC applications. Stakeholders must monitor evolving national building codes that increasingly mandate whole-life carbon assessments for insulation materials, as this shifts specification criteria beyond thermal performance toward embodied energy and recyclability credentials.
Market Dynamics
The EU Green Deal's tightening energy efficiency mandates for retrofit projects are accelerating specification shifts toward hydrophobic insulation solutions, compressing demand cycles for conventional glass wool in commercial building envelopes.
Growth Catalysts
- EU F-Gas Regulation:Synthetic foam restrictions in HVAC applications redirect procurement toward moistureproof glass wool for duct and equipment insulation across German and French commercial construction.
- District heating networks:Pipe insulation demand accelerates as climate-sensitive geographies expand district energy infrastructure requiring hydrophobic thermal protection.
- Deep renovation targets:Germany's stringent building codes and national retrofit mandates sustain volume for hydrophobic formulations in wall and roof cavity applications.
Market Restraints
- Binder resin volatility:Thermosetting phenolic and formaldehyde-based resin prices fluctuate with petrochemical feedstock costs, compressing margin stability for mid-tier producers.
- Centrifugal spinning equipment concentration:Specialized fiber formation machinery suppliers cluster in Western Europe, creating capex bottlenecks for capacity expansion outside established manufacturing zones.
- Mineral wool substitution:Stone wool alternatives with comparable hydrophobic treatments compete on fire resistance ratings in high-rise facade specifications.
Strategic Opportunities
- Industrial process lines:Petrochemical and power generation facilities in the Gulf region present underpenetrated demand for rigid board formulations rated for extreme humidity exposure.
- Whole-life carbon assessments:National building codes in France and the Netherlands increasingly mandate embodied energy credentials, favoring suppliers with verified recyclability and low-carbon production processes.
- Digital specification platforms:Building information modeling integration enables direct-to-architect channels that bypass traditional distributor markups in commercial project bidding.
Industry Challenges
- Silicone treatment certification:REACH compliance documentation for hydrophobic agents requires extended testing timelines, delaying product launches by 8-14 months.
- Building science expertise scarcity:Moisture-risk assessment capabilities for envelope system design remain concentrated among specialized engineering consultancies, limiting installer training scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moistureproof Glass Wool Market |
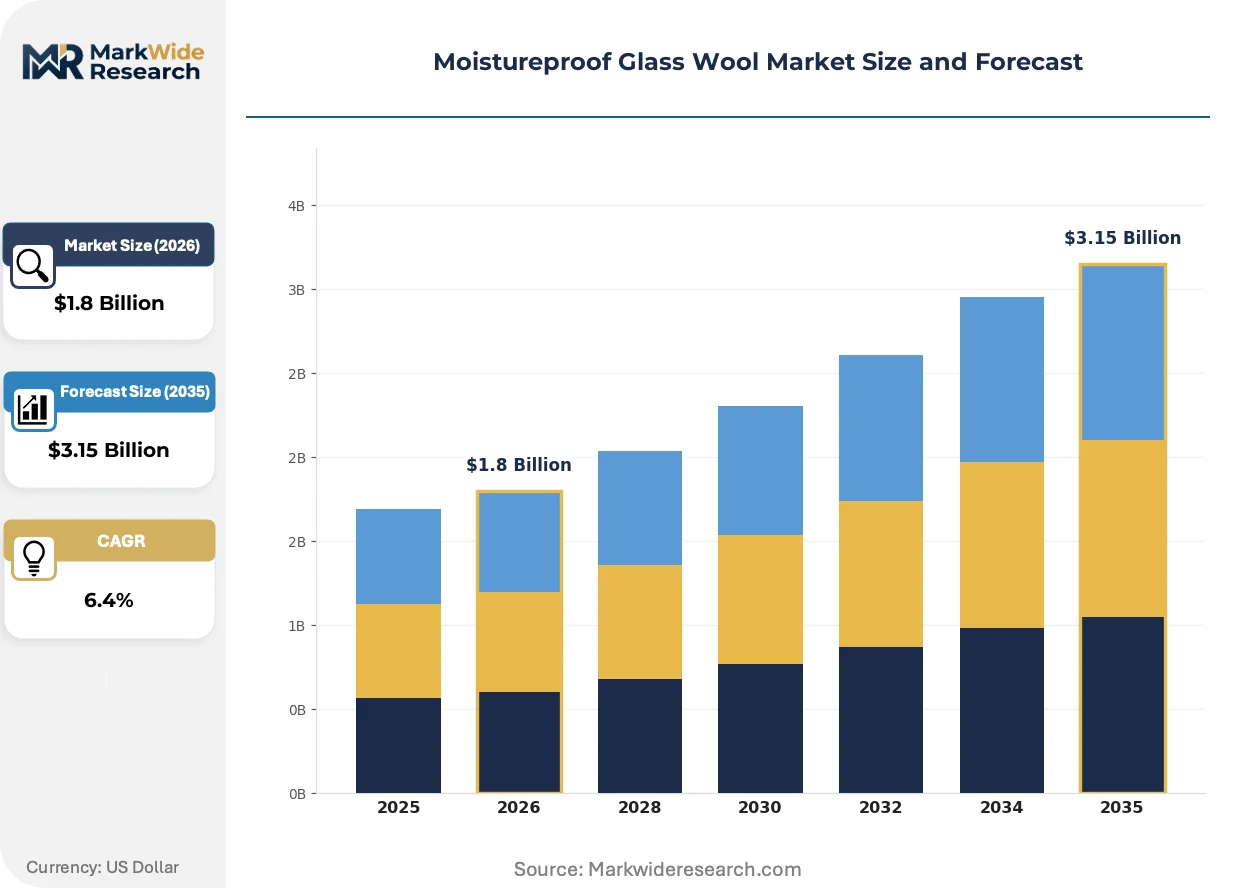
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanket Rolls, Loose Fill, Rigid Boards, Pipe Insulation Grade: Standard, High Density, Low Density, Fire Resistant, Acoustic Application: Thermal Insulation, Acoustic Insulation, Fireproofing, HVAC Systems End User: Construction Contractors, Insulation Specialists, Industrial Manufacturers, Commercial Facility Managers, Residential Builders |
| Companies Covered | Owens Corning, Saint-Gobain Isover, Johns Manville, Knauf Insulation, Rockwool International, Kingspan Group, Armacell, Funas Insulations, URSA Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moistureproof Glass Wool Market Trends and Innovations
Digital building science tools and advanced fiber treatment chemistries are compressing specification cycles while elevating performance verification standards across commercial and industrial segments.
Centrifugal spinning process control systems equipped with real-time fiber diameter monitoring are virtualizing quality assurance protocols that previously required batch sampling. German manufacturers deploy these systems to maintain 3-7 micron consistency for premium facade specifications. The technology is virtualizing traditional laboratory-based certification workflows, compressing validation timelines from weeks to hours.
REACH authorization requirements for formaldehyde-based binders are forcing reformulation investments across European production bases. Manufacturers accelerate phenol-alternative resin development to maintain specification eligibility in commercial building channels. Germany's Federal Institute for Risk Assessment evaluations drive the tightest compliance timelines, with producers front-loading R&D spend to secure 2025-2026 authorization windows.
Performance-based procurement contracts now dominate commercial envelope projects above 10,000 square meters, replacing unit-price purchasing with thermal outcome guarantees. General contractors in France and the Netherlands absorb moisture-risk liability, shifting specification authority toward specialized insulation subcontractors. This behavior concentrates demand among suppliers offering system-level warranties rather than component-only sales.
Moistureproof Glass Wool Market Segmentation
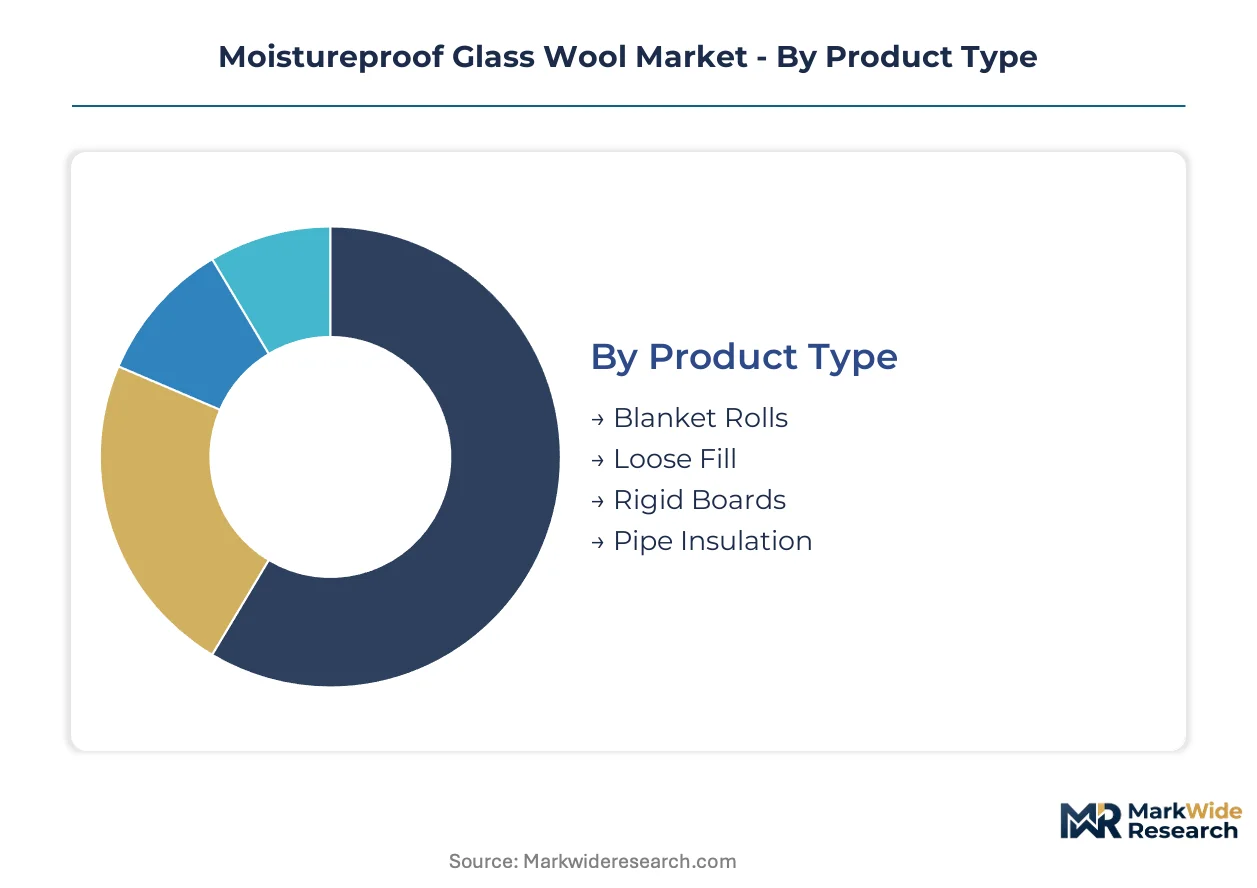
Segmentation in moistureproof glass wool tracks how hydrophobic treatment chemistries and physical formats align with distinct installation environments and regulatory pressure points across commercial, industrial, and residential build-outs.
Product Type:
Mature formats dominate retrofit workflows while emerging configurations target infrastructure-scale thermal networks.
- Blanket Rolls:Flexible continuous sheets with thermoset resin bonding and silicone hydrophobic coating enable rapid cavity wall and roof deck installation. German commercial retrofit contractors specify blanket rolls for deep renovation projects under national building code mandates. The format absorbs the highest volume across EU Green Deal-funded envelope upgrades.
- Pipe Insulation:Pre-formed cylindrical segments with closed-cell edge sealing and vapor-barrier jacketing protect district heating distribution lines from condensation degradation. Demand concentrates in Scandinavian and Baltic district energy expansions where below-grade humidity exposure is severe. This category is gaining share fastest as municipal heating utilities modernize distribution infrastructure.
- Loose Fill:Blown-in fiber clusters with surface-applied hydrophobic agents fill irregular attic and wall cavities where batt installation is impractical.
- Rigid Boards:Compressed high-density panels with laminated facers deliver dimensional stability for commercial facade rainscreen systems.
Blanket Rolls handle the majority of throughput; Pipe Insulation is the fastest mover on share.
Grade:
Cost tiers separate commodity specifications from performance-engineered formulations serving fire-rated and acoustic-critical assemblies.
- Standard:General-purpose hydrophobic glass wool with 10-24 kg/m³ density and basic silicone treatment satisfies residential and light commercial thermal requirements. Procurement concentrates among residential builders in cost-sensitive Central European markets where minimum code compliance suffices. Price volatility in phenolic binder feedstocks squeezes margin stability for this tier.
- Fire Resistant:Reformulated binder systems and fiber matrix engineering achieve Euroclass A1 or A2-s1,d0 ratings for high-rise facade and escape route specifications. French and Dutch commercial envelope contractors specify this grade for projects above 50 meters where stone wool substitution pressure is intense. Regulatory tightening on combustible materials in tall buildings is accelerating specification migration from Standard to Fire Resistant grades.
- High Density:Compressed matrices at 48-100 kg/m³ deliver load-bearing thermal resistance for flat roof and industrial floor applications.
- Low Density:10-14 kg/m³ open matrices optimize acoustic absorption in suspended ceiling and partition wall systems.
- Acoustic:Tuned fiber diameter distributions and facing laminates target specific frequency absorption in concert halls, cinemas, and open-plan offices.
Standard grade still moves the highest volume tonnage; Fire Resistant is expanding most quickly as facade safety codes tighten.
Application:
Functional use cases map directly to building system performance guarantees and contractor liability structures.
- Thermal Insulation:The core application leverages hydrophobic glass wool's stable R-value in condensation-prone envelope cavities and mechanical rooms. German and French commercial contractors absorb moisture-risk liability under performance-based procurement contracts, concentrating demand on validated hydrophobic formulations. Whole-life carbon assessment mandates in the Netherlands and France now filter thermal insulation selection beyond R-value to embodied energy credentials.
- HVAC Systems:Duct lining and equipment insulation applications exploit moistureproof glass wool's resilience in supply air streams where temperature differentials generate condensation. EU F-Gas Regulation restrictions on synthetic foam alternatives redirect specification toward hydrophobic glass wool in German and French commercial mechanical installations. This segment is climbing the fastest as heat pump deployment accelerates across climate-sensitive geographies.
- Acoustic Insulation:Fiber matrix tuning for sound absorption targets commercial interior fit-outs and industrial noise control.
- Fireproofing:Passive fire protection applications in steel column and duct encasement compete directly with mineral wool and intumescent coatings.
Thermal Insulation commands the dominant share of specification volume; HVAC Systems is the fastest-expanding application as electrification reshapes mechanical infrastructure.
End User:
Customer type segmentation reveals how specification authority and procurement risk allocation vary across project scales.
- Construction Contractors:General contracting firms on commercial envelope projects above 10,000 square meters increasingly absorb moisture-risk liability, shifting specification authority toward insulation subcontractors with system-level warranty capabilities. French and Dutch performance-based contracts concentrate demand among contractors partnered with validated hydrophobic glass wool suppliers.
- Insulation Specialists:Dedicated envelope subcontractors with building science expertise and moisture-risk assessment capabilities capture specification authority on complex commercial retrofits. German deep renovation workflows depend on these specialists for cavity wall and roof deck hydrophobic system design. This channel is gaining influence fastest as envelope performance guarantees replace unit-price purchasing.
- Industrial Manufacturers:Petrochemical and power generation facility operators specify rigid board formulations for process line and vessel insulation in extreme humidity exposure conditions.
- Commercial Facility Managers:Building owners and operators procure for maintenance, repair, and operations cycles with emphasis on lifecycle cost and remediation risk.
- Residential Builders:Single-family and multi-family developers prioritize cost-efficient code compliance with limited technical specification involvement.
Construction Contractors remain the largest procurement channel by project value; Insulation Specialists are ascending fastest as performance liability concentrates expertise-driven selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and French buyers absorb premium pricing for certified hydrophobic systems, while Central European residential markets prioritize cost-efficient code compliance over performance tiers.
Germany
Deep renovation mandates under the Buildings Energy Act (GEG) sustain volume for hydrophobic blanket rolls in cavity wall retrofits. The Federal Institute for Risk Assessment drives the tightest REACH compliance timelines for formaldehyde-based binder alternatives. Manufacturing clusters in North Rhine-Westphalia and Bavaria deploy centrifugal spinning systems with real-time fiber diameter monitoring for premium facade specifications.
France
Commercial envelope contractors above 10,000 square meters absorb moisture-risk liability under performance-based procurement contracts. RE2020 environmental regulations mandate whole-life carbon assessments that filter insulation selection toward low-embodied-energy formulations. Industrial concentration in Île-de-France and Auvergne-Rhône-Alpes anchors specification channels for fire-resistant grades in high-rise projects.
Netherlands
National building codes require embodied energy credentials for insulation materials in public procurement, shifting selection criteria beyond thermal performance. The EU F-Gas Regulation redirects HVAC specification toward hydrophobic glass wool as synthetic foam alternatives face restriction. The Randstad corridor concentrates district heating network expansions that accelerate pipe insulation demand.
United States
EPA emissions guidelines elevate barrier-to-entry for uncertified producers while steering commercial procurement toward validated hydrophobic formulations. Deep energy retrofit programs in the Northeast and Pacific Northwest drive specification of moisture-resistant envelope systems. Regional manufacturing bases in the Southeast and Midwest compete on scale for standard-grade residential applications.
China
GB standards for building materials enforce hydrophobic performance testing that compresses demand cycles for untreated glass wool. Dual carbon goals accelerate specification of low-carbon insulation in state-funded commercial construction. Yangtze River Delta and Pearl River Delta manufacturing hubs concentrate centrifugal spinning capacity for domestic and export markets.
Moistureproof Glass Wool Market Competitive Landscape
Capability concentration sits with building-science specialists; scale advantage sits with diversified materials conglomerates. The vendor base stratifies across three tiers: integrated building envelope solution providers, standalone insulation manufacturers with controlled distribution networks, and regional fabricators competing on unit economics. Dominant competitive moves include vertical integration into binder resin production to hedge petrochemical feedstock volatility, and strategic partnerships with district heating utilities to anchor pipe insulation specifications.
Within the integrated solution-provider tier, Owens Corning anchors premium positioning through building science expertise, while Saint-Gobain Isover exemplifies European specification-channel dominance through controlled distribution networks. Johns Manville occupies a position on the industrial-grade formulation vector, competing aggressively in power generation and petrochemical applications where extreme humidity exposure demands validated hydrophobic performance.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain Isover |
| Johns Manville |
| Knauf Insulation |
| Rockwool International |
| Kingspan Group |
| Armacell |
| Funas Insulations |
| URSA Insulation |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's volatile container rates compress margin pools for hydrophobic glass wool moving from German manufacturing clusters to French commercial construction sites, concentrating pricing power among producers with captive logistics networks while forcing mid-tier competitors toward regional fabricator partnerships.
Pricing Analysis
Aftermarket service revenue from insulation system audits and moisture-damage remediation anchors lifetime value capture. Three-tier pricing structure across premium certified, standard compliant, and economy grade levels stratifies procurement in German deep renovation markets. Cost compression in standard-grade formulations intensifies as phenolic binder feedstock volatility squeezes mid-tier producers. Residential builders in Central Europe exhibit highest price sensitivity, while French commercial envelope contractors absorbing moisture-risk liability under performance-based contracts demonstrate lowest sensitivity to unit pricing.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate procurement contracts for centrifugal spinning equipment, stretching working capital for capacity expansion outside established manufacturing zones. Supply concentrates in Germany, France, and China, with fiber formation machinery clustering in North Rhine-Westphalia and Bavaria. Raw material dependencies center on borosilicate glass cullet, phenolic resin precursors, and silicone hydrophobic agents. Single-source vulnerability for specialized spinning equipment creates capex bottlenecks. Distribution runs through controlled specification channels anchored by building science expertise rather than commodity wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Moistureproof glass wool functions as a platform where building information modeling integration enables direct-to-architect specification channels, compressing traditional distributor markups and rewiring competitive positioning around digital interoperability rather than physical inventory control.
For Market Incumbents: Insulate specification authority by deepening captive supply of hydrophobic silicone agents and accelerating REACH pre-registration for formaldehyde-free binder alternatives. Stone wool substitution pressure in French high-rise facades demands fire-resistant grade portfolio expansion. Controlled distribution networks in German commercial channels remain the priority defensive lever.
For New Entrants and Emerging Players: Industrial process lines in Gulf region petrochemical facilities represent the most penetrable entry point, where extreme humidity exposure and limited local hydrophobic formulation expertise create specification gaps. District heating utility partnerships in Baltic states offer second-mover anchoring through pipe insulation pre-qualification. Digital specification platform integration provides the lowest-friction go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underutilized centrifugal spinning capacity and dormant REACH compliance documentation. Long-term viability hinges on whole-life carbon assessment credentialing as Dutch and French building codes harden embodied energy requirements. The signal to watch is authorization timeline compression for phenol-alternative binders under Germany's Federal Institute for Risk Assessment evaluations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Resin Production | Captive phenolic resin supply hedges petrochemical feedstock volatility for German manufacturers. |
| Digital Specification Platform Integration | Building information modeling channels bypass traditional distributor markups in French commercial bidding. |
| District Heating Utility Partnership | Long-term pipe insulation pre-qualification secures volume in Scandinavian municipal energy expansions. |
| REACH Pre-Registration Acceleration | Formaldehyde-free binder authorization windows under German Federal Institute timelines protect specification eligibility. |
| Fire-Resistant Grade Portfolio Expansion | Euroclass A1 certification counters stone wool substitution in Dutch high-rise facade specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant managers at centrifugal spinning facilities, procurement leads at French commercial envelope contractors, technical R&D directors at hydrophobic agent suppliers, and specification channel partners; alongside secondary validation through customs and trade data, ECHA REACH registration databases, SEC filings from listed building materials conglomerates, and national building code repositories. Bottom-up volume modeling triangulated against top-down construction spending allocation produced convergent estimates.
Forecast inputs considered product format segmentation across blanket rolls, pipe insulation, and rigid boards; grade tiering from standard to fire-resistant; application splits between thermal envelope and HVAC systems; and end-user channel dynamics shifting toward insulation specialists. CAGRs were derived from elasticity-adjusted demand curves mapped against EU Green Deal retrofit funding trajectories and district heating infrastructure deployment schedules across climate-sensitive geographies.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, petrochemical feedstock pricing, or REACH authorization timelines would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Insulation Products Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market