
 Fiberglass Resin Market | 2026-2036
Fiberglass Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Resin Market Analytics
Closed-mold infusion and vacuum-assisted resin transfer molding is fragmenting traditional open-mold fabrication across marine and wind energy supply chains. Owens Corning dominates upstream glass fiber supply, leveraging captive mineral resources and furnace scale across North American and European production nodes. China Jushi Co., Ltd. anchors Asia-Pacific supply security, sustaining cost-competitive E-glass output through integrated boron-free formulations and state-supported capacity expansions.
Fiberglass resin comprises thermoset polymer matrices—primarily unsaturated polyester, vinyl ester, or epoxy—chemically bonded with glass fiber reinforcement to produce lightweight, corrosion-resistant composite structures with specific tensile strengths exceeding 300 MPa. These formulations serve critical load-bearing and environmental protection roles in transportation, infrastructure, and renewable energy hardware. Polyester resin occupies the largest volume share across construction and marine applications, though epoxy resin captures premium margin pools in aerospace and wind turbine blade manufacturing where fatigue resistance and fiber adhesion properties command specification-driven pricing. Vinyl ester resin differentiates in chemical processing and infrastructure segments, bridging cost-performance gaps between commodity polyester and high-performance epoxy systems.
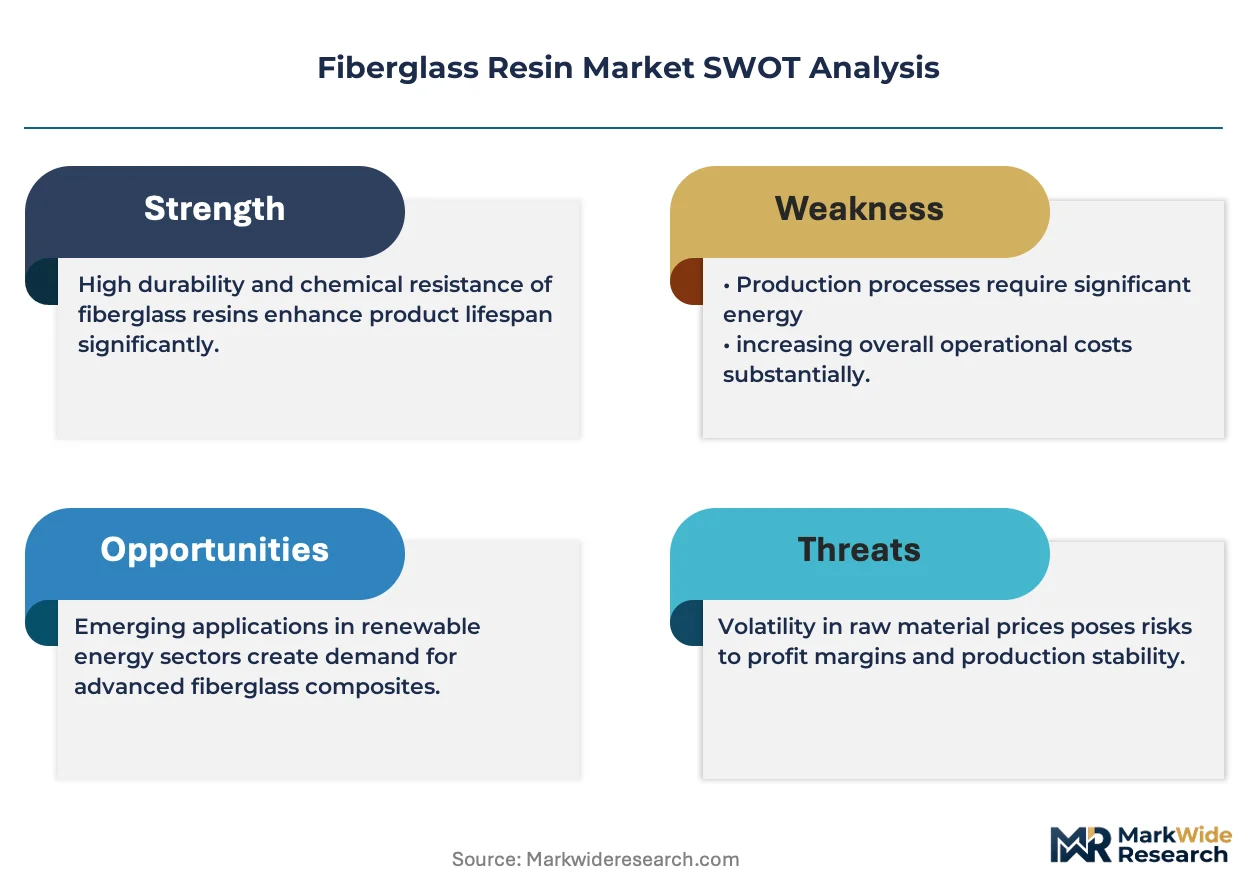
EPA air toxics standards and OSHA permissible exposure limits constrain styrene emissions from polyester resin operations across US fabrication facilities, while REACH registration requirements and the EU Green Deal carbon border adjustments reshape import competitiveness for Asian resin producers. China's MEE environmental enforcement and GB standards on volatile organic compound discharge intensify compliance capital requirements for domestic manufacturers. Stakeholders must monitor evolving chemical hazard classifications under ECHA and state-level California Air Resources Board protocols, as reclassification risks would force formulation redesigns across established product lines.
Market Dynamics
Closed-mold infusion processes are systematically displacing open-mold fabrication across marine and wind energy supply chains, compressing styrene emissions and labor intensity while demanding capital-heavy equipment upgrades from mid-tier fabricators.
Growth Catalysts
- Wind blade manufacturing scale-up:Vinyl ester and epoxy formulations penetrate turbine blade production as blade lengths exceed 80 meters, demanding fatigue-resistant matrix systems.
- EU Green Deal carbon border mechanisms:REACH chemical compliance frameworks tighten volatile organic compound limits on polyester resin imports, advantaging low-emission domestic European producers.
- China state infrastructure buildouts:State-backed renewable energy and transportation infrastructure sustain large-volume consumption of fiberglass composites through centralized procurement.
Market Restraints
- Styrene price volatility:Unsaturated polyester resin production remains exposed to benzene-ethylene derivative feedstock swings, compressing margin predictability for commodity-grade suppliers.
- Glass fiber supply concentration:Upstream E-glass roving production clusters among three dominant furnace operators, creating bottleneck risk during energy price spikes.
- Epoxy curing energy intensity:Heat-cured epoxy systems require sustained thermal input that conflicts with industrial decarbonization targets in EU and Chinese manufacturing zones.
Strategic Opportunities
- India infrastructure buildout:National highway and railway corridor expansion creates unserved demand for corrosion-resistant bridge decking and tunnel lining composites.
- Bio-based resin formulation:Epoxidized vegetable oil precursors converge with conventional hardener chemistry to serve EU Green Deal procurement preferences.
- Direct blade manufacturer supply contracts:Wind OEMs bypass distributor tiers to secure multi-year vinyl ester volume commitments with price-indexed adjustments.
Industry Challenges
- Vacuum infusion technician scarcity:Closed-mold fabrication requires specialized laminate technicians trained in bagging, leak detection, and resin flow modeling.
- REACH reclassification exposure:ECHA hazard classification reviews threaten styrene and cobalt accelerator redesigns across established polyester product lines.
- Legacy open-mold asset strandedness:Fabricators face write-down pressure on gelcoat spray booths and hand-layup tables incompatible with emission compliance trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Resin Market |
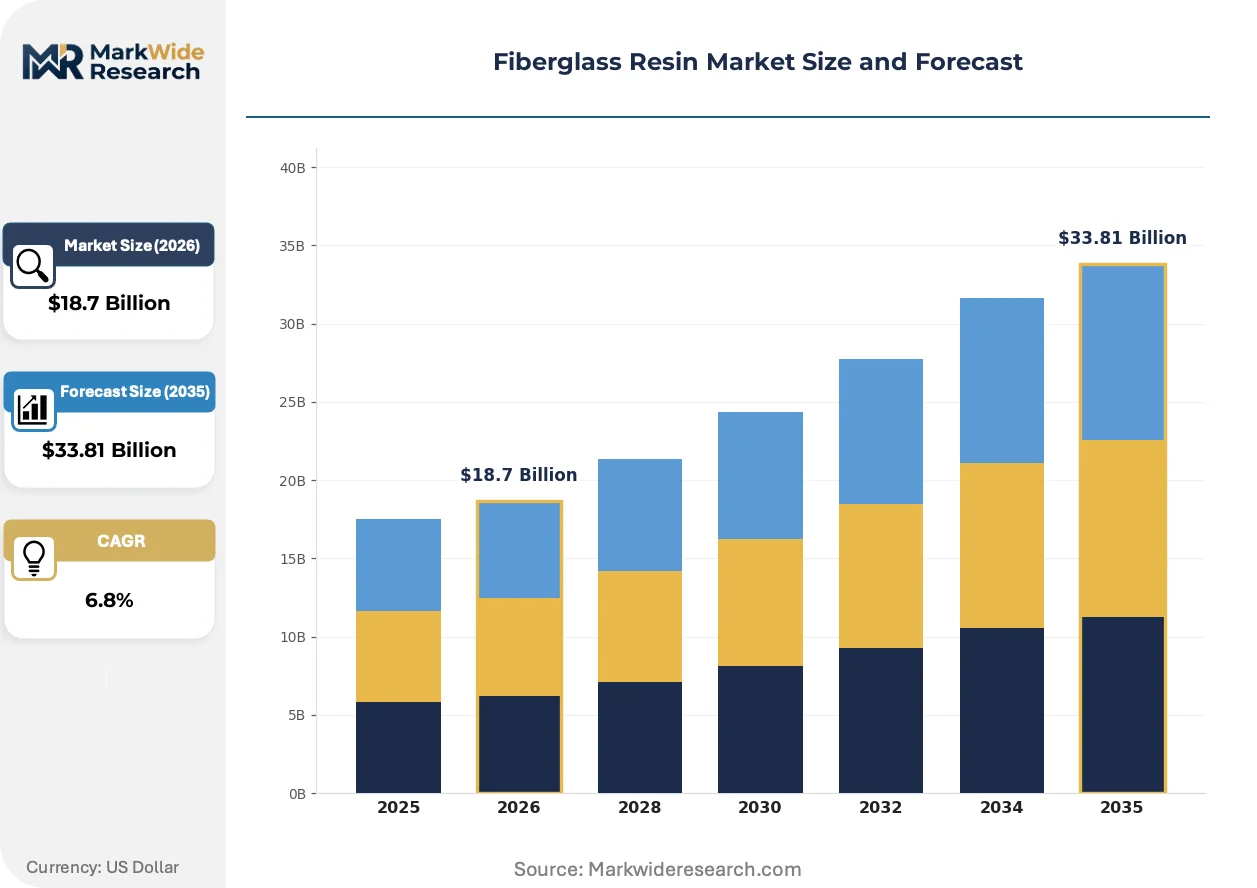
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Resin, Vinyl Ester Resin, Epoxy Resin, Phenolic Resin Application: Aerospace, Automotive, Marine, Construction End User: OEMs, Tier-1 Suppliers, Manufacturers, Contractors Form: Liquid, Solid, Gel Coat, Prepreg |
| Companies Covered | PPG Industries, Owens Corning, China Jushi Co., Ltd., Saint-Gobain, 3M, Evercoat, Hi-Bond, West System, Chongqing Polycomp International Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Resin Market Evolving Landscape
Resin transfer molding automation and bio-based feedstock substitution are compressing traditional manufacturing economics while regulatory chemistry restrictions force formulation redesign cycles.
Out-of-autoclave epoxy prepregs are collapsing thermal processing requirements for aerospace and wind blade secondary structures. Tier-one blade manufacturers adopt ambient-cure formulations for root inserts and shear webs, eliminating autoclave bottlenecks. This diffusion is collapsing capital barriers between aerospace-grade and industrial-grade composite fabrication.
REACH authorization requirements for cobalt-based accelerators are forcing polyester resin formulators to evaluate manganese and iron-based alternatives. The substitution timeline compresses product development cycles as downstream fabricators face supply continuity risks. Marine hull builders in Mediterranean shipyards are accelerating qualification trials for cobalt-free gelcoat systems ahead of 2026 sunset dates.
Direct long-term contracting between wind turbine OEMs and resin compounders is displacing distributor-mediated spot purchasing. Vestas and Siemens Gamesa negotiate three-to-five-year vinyl ester supply agreements with fixed-volume, price-adjusted terms. This concentration is most visible in Denmark and northern Germany, where blade manufacturing clusters align with North Sea offshore installation pipelines.
Fiberglass Resin Market Segmentation
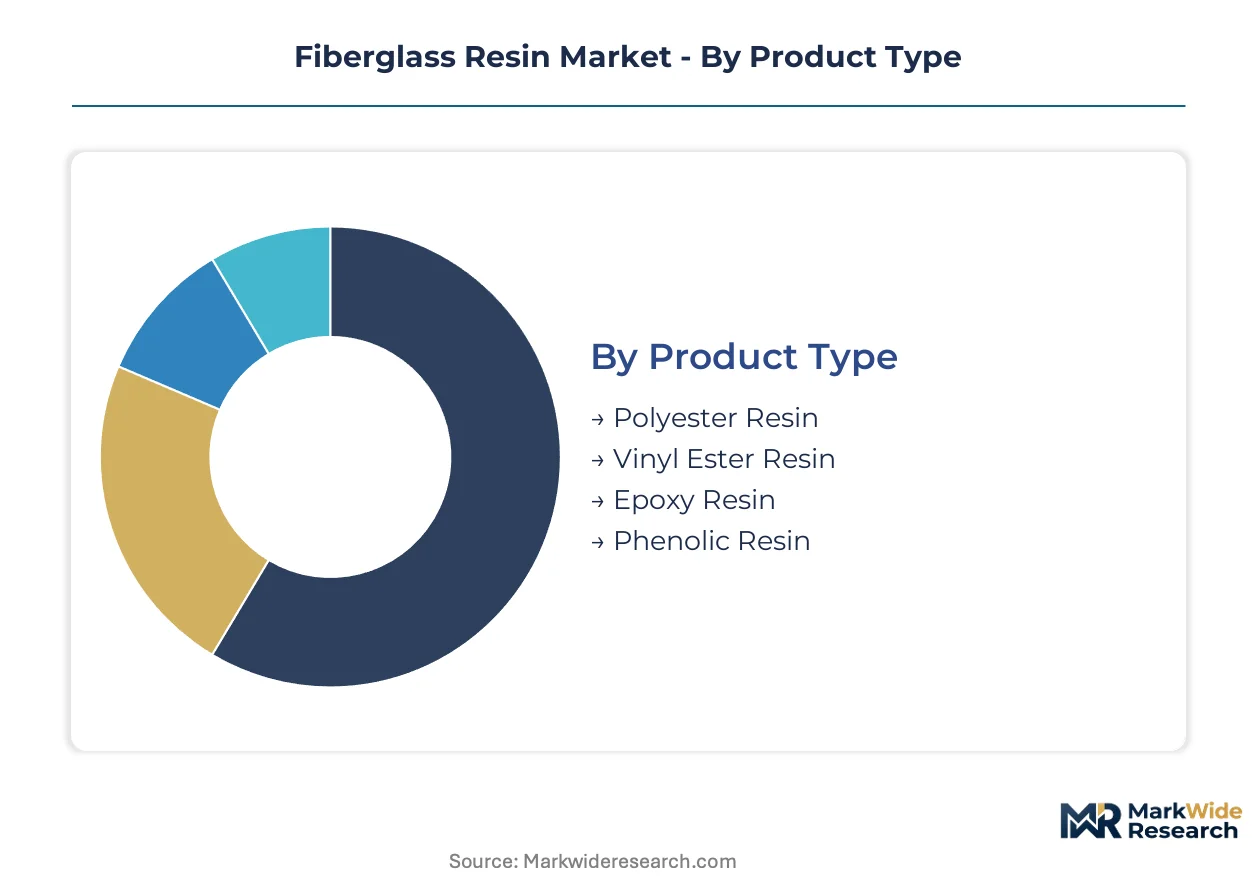
Resin selection dictates fabrication economics and regulatory compliance across fiberglass composite supply chains. Specification-driven procurement separates premium formulations from commodity grades. End-use performance requirements and emission standards reshape segment priorities continuously.
Product Type:
After-sales service intensity varies sharply by resin chemistry, with epoxy demanding technical support for cure cycle optimization while polyester relies on distributor logistics.
- Polyester Resin:Unsaturated thermoset matrices bond with styrene monomers to achieve rapid cure cycles at ambient temperatures. Construction and marine fabricators across China and India specify this chemistry for cost-sensitive corrosion barriers and panel laminates, though EPA and REACH styrene exposure limits force ventilation capital expenditure.
- Epoxy Resin:Bisphenol-A or novolac-based systems deliver superior fiber adhesion and fatigue resistance through cross-linked amine curing. Wind turbine blade manufacturers in Denmark and Germany mandate epoxy for root sections exceeding 80 meters, where delamination risks command specification-driven pricing and on-site technical service contracts.
- Vinyl Ester Resin:Hybrid methacrylate-epoxy backbones bridge cost-performance gaps for chemical processing infrastructure.
- Phenolic Resin:Formaldehyde-based thermosets serve fire-resistant aerospace and rail interior applications.
Polyester resin holds the largest share; momentum sits with epoxy formulations.
Application:
Cost tier stratification separates aerospace qualification expenses from construction commodity purchasing.
- Construction:Bridge decking, rebar, and architectural panels exploit corrosion resistance and electromagnetic transparency. Infrastructure buildouts in India and China's provincial highway programs sustain volume demand for pultruded profiles and spray-up laminates.
- Marine:Hull laminates and superstructures demand gelcoat surface finishes and blister-resistant osmotic barriers. Mediterranean and Southeast Asian shipyards transition from open-mold to infusion processing, compressing styrene emissions while raising capital requirements.
- Automotive:Underbody shields and structural reinforcements substitute metal stampings in electric vehicle platforms.
- Aerospace:Secondary structures and interior components require flame-smoke-toxicity certification and autoclave processing.
Construction commands the dominant volume position; marine applications are expanding most quickly.
End User:
Customer type determines contract structure, with OEMs negotiating multi-year supply agreements while contractors purchase through distribution.
- OEMs:Wind turbine and automotive original equipment manufacturers specify resin systems directly, bypassing compounder-distributor channels. Vestas and Siemens Gamesa negotiate three-to-five-year vinyl ester commitments with price-indexed adjustments and dedicated technical support.
- Tier-1 Suppliers:Subsystem integrators qualify resin formulations for blade spar caps and automotive body panels, managing supplier audit programs and batch certification documentation.
- Manufacturers:Independent fabricators purchase through distribution networks with spot pricing exposure.
- Contractors:Field installation crews rely on packaged kits with pre-measured catalyst ratios.
OEMs concentrate procurement leverage; Tier-1 suppliers are gaining negotiation sophistication fastest.
Form:
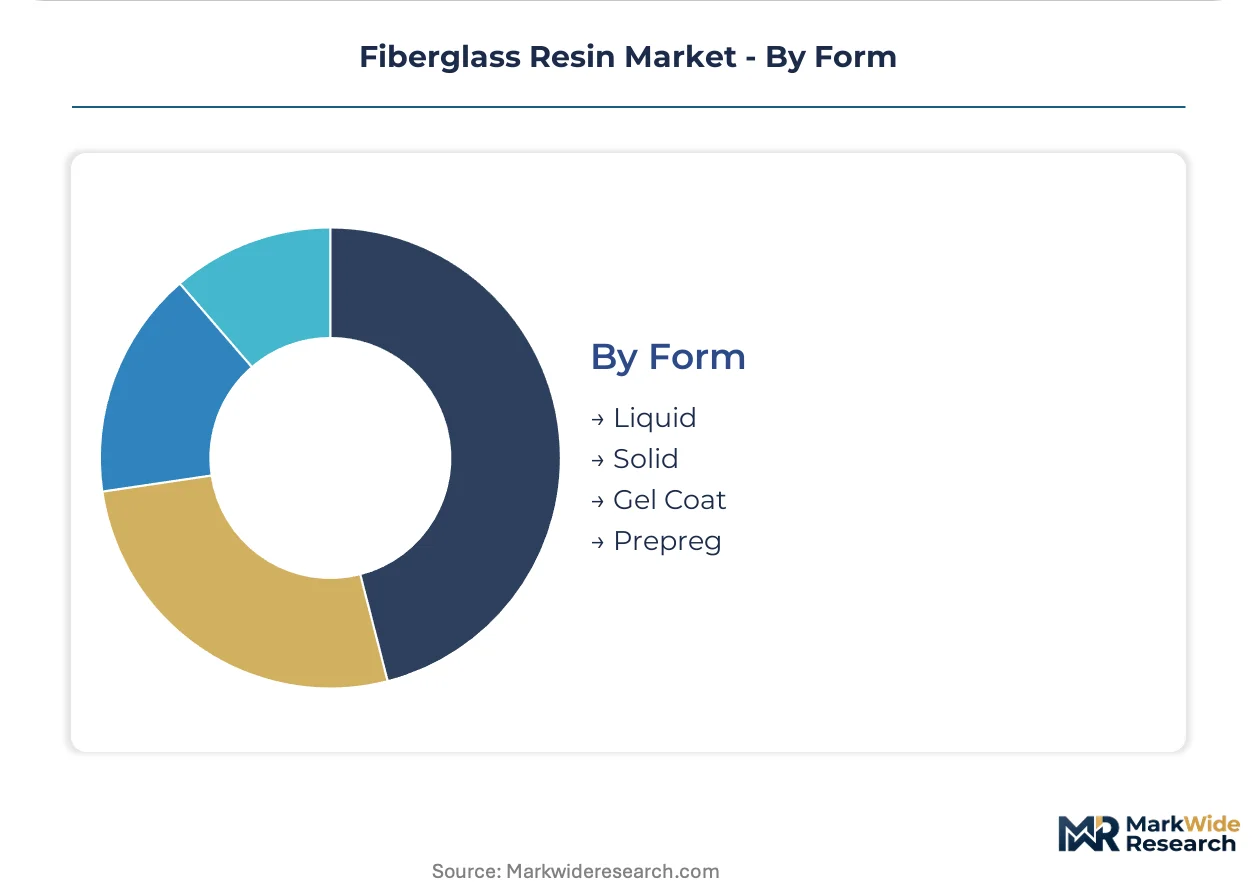
Supply concentration shapes availability, with liquid resins dominating volume and prepregs capturing premium margins.
- Liquid:Bulk isocyanate and amine formulations ship in heated tankers for wind blade and boat hull infusion. Chinese and US Gulf Coast production clusters serve regional fabrication networks with just-in-time delivery contracts.
- Prepreg:Reinforcement fabrics pre-impregnated with partially cured resin demand frozen storage and out-time tracking. Aerospace tier suppliers in France and Germany manage cold-chain logistics for autoclave-grade materials.
- Gel Coat:Pigmented surface finishes provide UV and abrasion protection for marine and sanitary applications.
- Solid:Powder and flake forms serve compression molding and adhesive compounding.
Liquid formulations absorb the majority of volume; prepreg systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine OEMs and marine fabricators dominate procurement across four concentrated manufacturing zones. State-backed infrastructure programs and REACH chemical compliance are reshaping supplier qualification requirements in each geography.
China
State-directed renewable energy buildouts and provincial highway expansion sustain E-glass roving consumption at scale. MEE environmental enforcement and GB standards on volatile organic compound discharge intensify compliance capital requirements for domestic polyester resin manufacturers. Yangtze River Delta fabrication clusters around Shanghai and Nantong anchor vinyl ester supply for offshore wind blade production.
United States
EPA air toxics standards and OSHA permissible exposure limits constrain styrene emissions from open-mold fabrication across Gulf Coast boatbuilding corridors. Owens Corning leverages captive mineral resources and furnace scale across North American production nodes serving automotive underbody shield programs. Texas and Louisiana chemical processing infrastructure supports bisphenol-A feedstock integration for epoxy formulation.
Germany
REACH registration requirements and EU Green Deal carbon border adjustments reshape import competitiveness for Asian resin producers. Siemens Gamesa and Vestas negotiate multi-year vinyl ester supply agreements with fixed-volume, price-indexed terms across northern blade manufacturing clusters. Bavarian and Lower Saxon fabrication facilities transition from autoclave to out-of-autoclave epoxy processing for wind turbine root sections.
India
National highway and railway corridor expansion creates unserved demand for corrosion-resistant bridge decking and tunnel lining composites. BIS standards on construction material certification and DGFT import tariff structures influence resin formulation sourcing decisions. Gujarat and Maharashtra industrial corridors concentrate pultruded profile manufacturing for infrastructure applications.
Denmark
Offshore wind installation pipelines across the North Sea drive specification-driven procurement of fatigue-resistant matrix systems. ECHA hazard classification reviews threaten cobalt accelerator redesigns across established polyester gelcoat product lines. Copenhagen and Aarhus technical service hubs support blade OEM direct contracting with resin compounders.
Fiberglass Resin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Upstream glass fiber supply concentrates among furnace operators with captive mineral access, while downstream formulation segments fragment across regional compounders serving marine and construction fabricators. Strategic archetypes include integrated glass-to-resin operators, specialty epoxy formulators, and commodity polyester distributors. Capacity expansion and direct OEM contracting represent the dominant competitive moves.
Within the integrated operator tier, Owens Corning and China Jushi Co., Ltd. exemplify scale-driven positioning through captive E-glass production. Saint-Gobain occupies a position bridging European specialty formulation with multi-regional distribution infrastructure. Among channel-focused players, PPG Industries represents the diversified coatings and materials archetype with fiberglass resin exposure through adjacent product lines.
| Leading Market Players |
|---|
| PPG Industries |
| Owens Corning |
| China Jushi Co., Ltd. |
| Saint-Gobain |
| 3M |
| Evercoat |
| Hi-Bond |
| West System |
| Chongqing Polycomp International Corp. |
| Others |
Value Network & Pricing Analysis
Captive E-glass furnace operations in China and the United States anchor upstream supply concentration, directing margin capture toward resin formulators with backward integration into glass fiber production and long-term wind OEM contracting power.
Pricing Analysis
Cost-plus contracts with styrene and benzene indexation dominate polyester resin procurement, separating spot-exposed commodity distributors from formula-protected integrated suppliers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and technical service bundling. Cost compression in commodity polyester intensifies as Chinese state-backed capacity expansions flood regional spot markets. Tier-1 wind blade manufacturers exhibit lowest price sensitivity due to specification-locked formulations, while independent marine fabricators drive hardest bargain pressure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for epoxy hardener and specialty chemical flows. Upstream E-glass roving production concentrates in China, the United States, and Germany, while bisphenol-A and ethylene feedstocks draw from Gulf Coast and Northeast Asian petrochemical complexes. Single-source vulnerability concentrates around cobalt-based accelerator supply ahead of REACH authorization deadlines. Distribution runs through regional compounder networks serving marine and construction fabricators with just-in-time heated tanker delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where REACH registration timelines and wind blade qualification protocols create switching costs that lock out unqualified competitors.
For Market Incumbents: Harden formulation portfolios against REACH reclassification exposure by accelerating cobalt-free accelerator qualification and securing multi-year vinyl ester supply agreements with Vestas and Siemens Gamesa. Backward integration into glass fiber roving production in Nantong or Texas defends margin position against feedstock volatility and Chinese import competition.
For New Entrants and Emerging Players: Establish a beachhead in India's infrastructure composite segment, where national highway expansion and BIS certification gaps create unserved demand for corrosion-resistant bridge decking. Bio-based epoxy formulations targeting EU Green Deal procurement preferences offer the most penetrable wedge, with direct contracting to state-backed contractors bypassing entrenched distributor networks.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated glass-to-resin operators with captive mineral access and wind OEM direct relationships, as these assets compound defensive positioning across the analysis window. Monitor ECHA hazard classification reviews as the critical inflection signal; material styrene or cobalt redesign mandates would force consolidation among unqualified regional compounders and reward pre-positioned integrated players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Production | Captive mineral resources and furnace scale insulate margin from feedstock volatility and supply interruption. |
| REACH-Compliant Accelerator Substitution | Manganese and iron-based alternatives preempt 2026 cobalt sunset dates and secure marine gelcoat continuity. |
| Direct OEM Supply Contracting | Three-to-five-year vinyl ester agreements with Vestas and Siemens Gamesa displace distributor-mediated spot purchasing. |
| Out-of-Autoclave Process Adoption | Ambient-cure epoxy formulations collapse capital barriers between aerospace-grade and industrial-grade fabrication. |
| Bio-Based Resin Formulation Development | Epoxidized vegetable oil precursors align with EU Green Deal procurement preferences and carbon border adjustments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including wind blade manufacturing engineers, marine hull fabricators, resin formulation chemists, and procurement leads at Tier-1 automotive suppliers. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA registration databases, and American Chemistry Council industry reports. Bottom-up volume modeling triangulated against top-down market sizing across resin chemistry, application, and regional production hub dimensions.
Calibration anchored on historical shipment data and forward contract disclosures from integrated glass fiber and resin producers. Segmentation modeling spanned product type, end-use industry, customer tier, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of capacity expansion announcements, OEM procurement pipelines, and substitution elasticity parameters for metal-to-composite conversion in transportation and infrastructure.
Sensitivities concentrate around REACH reclassification timelines, Chinese environmental enforcement intensity, and wind turbine blade length evolution beyond 80 meters. Forecasts reflect assumptions on regulatory continuity and feedstock cost trajectories. Material shifts in ECHA hazard classifications or EU carbon border adjustment mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Ceramic Fiber Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
E-Glass Fiber Market
Fibers
Fiber Intermediates Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Carbon Fiber Tapes Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Thermoformed Fiber Market
Fibers
Bioglass Fiber Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Viscose Staple Fiber Market
Fibers
Carbon Fiber Filament Market