
 Low-Frequency Sound-Absorbing Insulation Materials Market | 2026-2036
Low-Frequency Sound-Absorbing Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Frequency Sound-Absorbing Insulation Materials Market Outlook
Performance-based acoustic consulting and installation certification is shifting how low-frequency insulation gets specified and sold. Saint-Gobain leverages its building-science service arm to bundle material supply with acoustic modeling, locking in multi-year project relationships. Autoneum anchors its position through captive R&D centers in acoustic vehicle development, sustaining technology leadership in powertrain noise reduction. BASF differentiates via polymer chemistry expertise, controlling formulation pipelines that feed both automotive and construction channels.
Low-frequency sound-absorbing insulation materials are engineered composites—typically fiberglass, mineral wool, or open-cell foam with densities of 32–96 kg/m³ and flow resistances calibrated to target 50–500 Hz absorption coefficients above 0.85—designed to dissipate acoustic energy through viscous and thermal losses in porous structures. These materials serve critical noise-control functions in automotive passenger compartments, building mechanical rooms, and wind-turbine nacelles where tonal low-frequency sources dominate the acoustic environment. Fiberglass and mineral wool categories occupy mature volume positions in construction and industrial applications, though margin pools are migrating toward foam formulations that address weight-sensitive automotive and renewable-energy installations. Polyester fiber segments are gaining fastest in sustainable building projects, where recycled-content specifications from facility managers and green contractors reshape procurement criteria.
EMA's Medical Device Regulation and REACH chemical restrictions in Europe govern binder chemistries and emissions testing, while OSHA noise-exposure limits in the US mandate industrial acoustic treatments that specify certified absorption performance. The EU F-Gas Regulation and evolving CE marking requirements for construction products are forcing reformulation of blowing agents and adhesive systems. Stakeholders must monitor how acoustic-performance standards diverge between automotive OEM specifications and building-code harmonization efforts, as this tension determines which material platforms scale across end-use boundaries.
Market Dynamics
The EU Green Deal's embodied-carbon rules are forcing binder reformulation across construction-grade insulation, compressing margins for conventional fiberglass while opening procurement pathways for bio-based alternatives certified under tightening CE marking protocols.
Growth Catalysts
- Electric vehicle cabin quieting:Automotive OEMs are expanding acoustic insulation specifications for powertrain noise reduction as internal combustion engine masking disappears.
- REACH chemical restrictions:European reformulation mandates are accelerating substitution of formaldehyde-based binders with bio-alternatives in building products.
- Stuttgart-Wolfsburg engineering clusters:Germany's automotive acoustics concentration drives premium material sourcing for NVH engineering programs.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate price swings compress foam formulation margins and destabilize open-cell insulation pricing.
- Supplier concentration in blowing agents:EU F-Gas Regulation limits hydrofluorocarbon availability, constraining foam expansion chemistry options.
- Mineral wool density limitations:Structural weight constraints in automotive applications restrict mineral fiber deployment despite cost advantages.
Strategic Opportunities
- Wind turbine nacelle acoustics:Renewable energy installations create demand for lightweight, weather-resistant low-frequency absorption in rotating machinery enclosures.
- Building mechanical room retrofit mandates:OSHA noise-exposure limits in industrial facilities specify certified absorption performance for compliance-driven replacement cycles.
- Recycled-content polyester fiber:Green contractor procurement criteria reshape sustainable building material specifications toward post-consumer feedstocks.
Industry Challenges
- Acoustic-performance certification timelines:Divergence between automotive OEM specifications and building-code harmonization efforts creates testing backlog and specification uncertainty.
- Multi-physics modeling talent scarcity:Viscous-thermal loss simulation expertise for porous material design concentrates in specialized acoustics engineering programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Frequency Sound-Absorbing Insulation Materials Market |
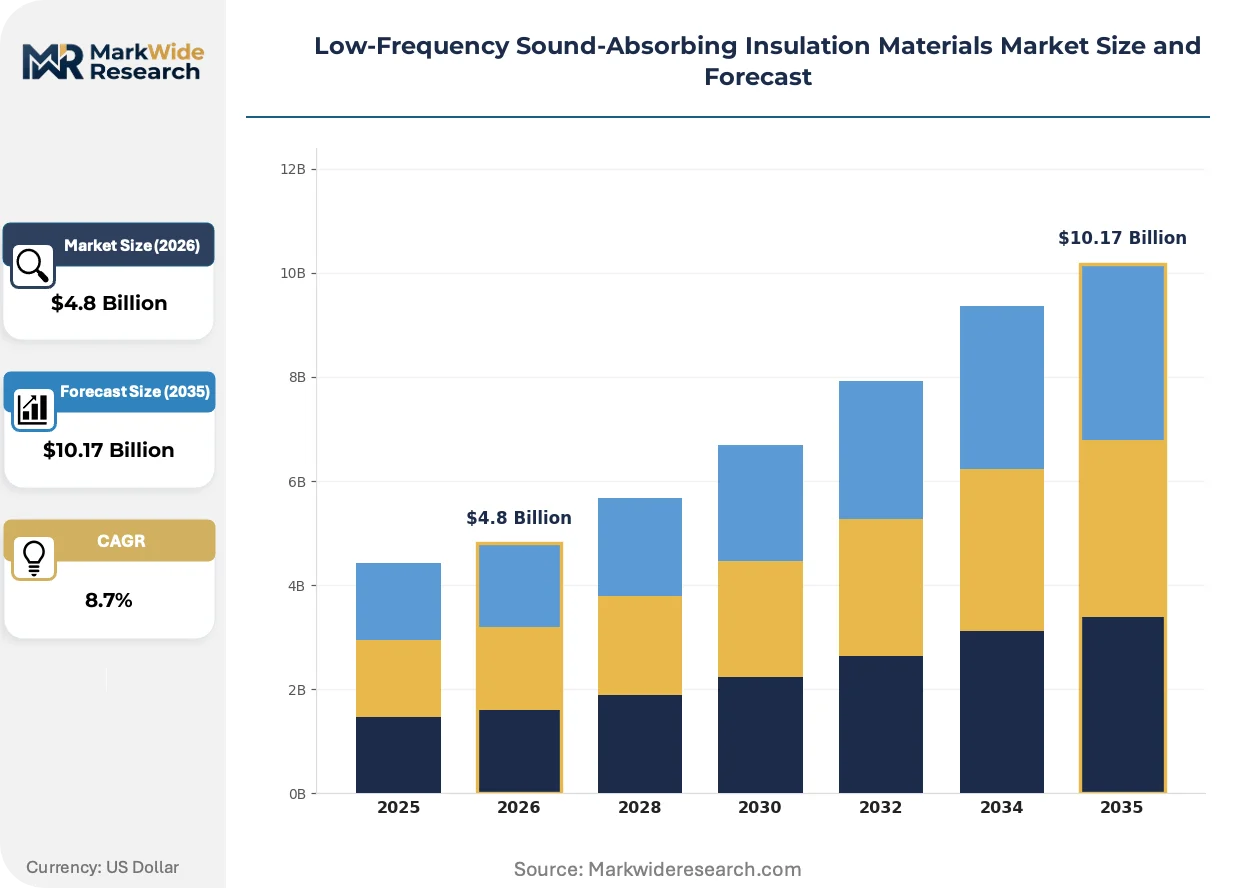
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Mineral Wool, Foam, Polyester Application: Automotive, Construction, Electronics, Renewable Energy Installation Method: Wall Panels, Ceiling Tiles, Floor Underlayment, Duct Liners End User: Manufacturers, Contractors, OEMs, Facility Managers |
| Companies Covered | Saint-Gobain, Autoneum, 3M, DuPont, BASF, Mitsubishi Chemical Holdings, Stevens Insulation LLC, Wan Rui Chemical, Yuan Yuan Sponge Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Frequency Sound-Absorbing Insulation Materials Market Strategic Shifts
Bio-based binder chemistry is converging with performance-grade acoustic engineering, compressing the traditional trade-off between sustainability credentials and low-frequency absorption coefficients in specification-driven markets.
Metamaterial-structured absorbers are converging with conventional porous insulation manufacturing, enabling sub-wavelength resonance targeting in the 50–200 Hz range. Wind turbine OEMs are piloting these hybrid structures for nacelle tonal noise control. The technology is converging with roll-to-roll production methods, collapsing cost premiums against conventional foam formulations.
EU F-Gas Regulation phase-down schedules are forcing blowing agent transitions in polyurethane foam insulation. Reformulation with hydrofluoroolefin alternatives raises material costs while reducing global warming potential ratings. Construction product manufacturers serving German and French building markets are prioritizing CE-marked low-GWP formulations to maintain specification eligibility.
Facility managers are consolidating acoustic material procurement under performance-based service contracts that bundle installation, monitoring, and replacement. This displaces transactional spot purchasing in commercial building mechanical rooms. The model is most visible in US industrial facilities subject to OSHA noise-exposure auditing and remediation mandates.
Low-Frequency Sound-Absorbing Insulation Materials Market Segmentation
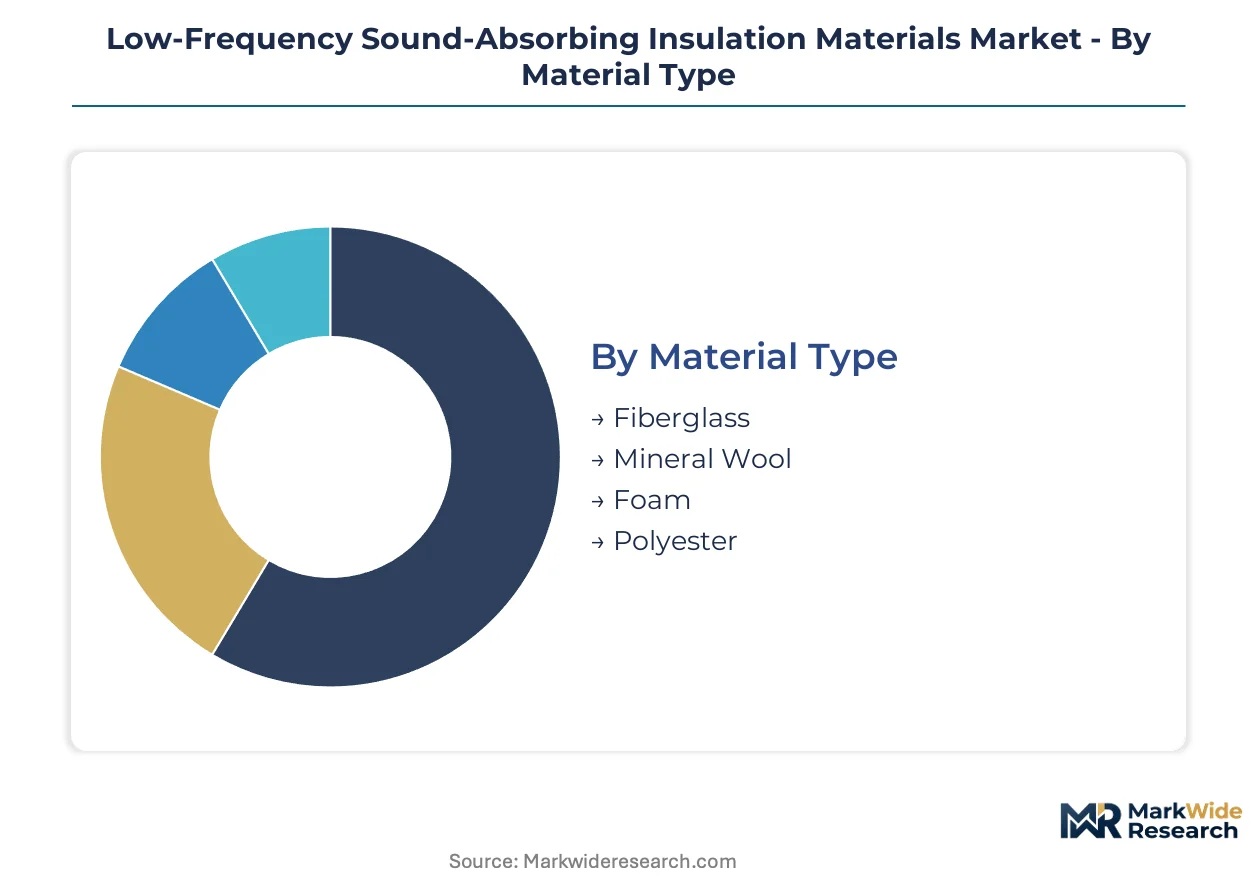
Segmentation in low-frequency insulation materials tracks how technical specifications, installation constraints, and procurement authority reshape margin pools across automotive, construction, and industrial channels. Material chemistry, application environment, and buyer type collectively determine which formulations capture specification-driven premiums versus commodity volume.
Material Type:
Flow resistance and density calibrations separate specification-grade formulations from commodity supply in porous acoustic engineering.
- Fiberglass:Bonded glass fiber matrices with calibrated fiber diameters deliver absorption coefficients above 0.85 in the 100–500 Hz range. Construction contractors in Germany specify these for mechanical room retrofits under OSHA-mandated noise remediation programs, though embodied-carbon scrutiny from the EU Green Deal compresses margins on conventional binder chemistries.
- Mineral Wool:Slag or rock wool formulations achieve higher operating temperatures and fire ratings than organic alternatives. Density limitations above 96 kg/m³ restrict deployment in Stuttgart-area automotive NVH programs where weight-driven specifications favor lighter substrates, confining mineral wool to building envelope and industrial applications.
- Foam:Open-cell polyurethane structures with tunable cell geometries address weight-sensitive installations across electric vehicle cabins and wind turbine nacelles.
- Polyester:Recycled-content fiber batts certified under green procurement criteria reshape sustainable building specifications in France and the Netherlands.
Mature deployment sits with fiberglass. Newer deployment is concentrated in polyester fiber as post-consumer feedstock specifications harden.
Application:
End-use acoustic environments dictate absorption coefficient targets, weathering requirements, and regulatory compliance burdens.
- Automotive:Electric vehicle OEMs specify multi-layer foam composites for cabin quieting as internal combustion engine masking disappears. Stuttgart and Wolfsburg engineering clusters drive premium material sourcing for powertrain NVH reduction, with acoustic performance validation against OEM-specific test protocols.
- Construction:Building mechanical rooms and building envelopes absorb the largest material volumes. EU F-Gas Regulation phase-downs and REACH chemical restrictions force simultaneous reformulation of blowing agents and binders, raising qualification costs for CE-marked products.
- Electronics:Server rack and data center acoustic management requires thin-profile absorption with thermal management integration.
- Renewable Energy:Wind turbine nacelles generate concentrated low-frequency tonal noise from gearbox and generator operation. Metamaterial-structured absorbers piloted by Danish and Spanish turbine OEMs target sub-wavelength resonance in the 50–200 Hz range.
Volume concentrates in construction. Specification premiums are climbing fastest in automotive as cabin quieting requirements intensify.
Installation Method:
Mounting geometry and accessibility determine whether absorption targets are achieved through surface-applied panels or integrated building system components.
- Wall Panels:Removable acoustic panels with fabric-wrapped faces dominate retrofit applications in US industrial facilities subject to OSHA noise-exposure auditing. Performance-based service contracts bundle panel supply with installation certification and periodic replacement, displacing transactional procurement.
- Ceiling Tiles:Suspended ceiling systems integrate absorption with HVAC distribution and lighting infrastructure. Facility managers in German commercial buildings prioritize CE-marked products with documented absorption coefficients across octave bands.
- Floor Underlayment:Resilient mats and composite assemblies address structure-borne transmission in multi-occupancy buildings.
- Duct Liners:Internal duct insulation combines acoustic attenuation with thermal performance in HVAC distribution systems.
Retrofit activity centers on wall panels. New construction specifications favor ceiling tile integration with mechanical and electrical systems.
End User:
Procurement authority and technical capability separate specification-driven buyers from price-sensitive volume purchasers.
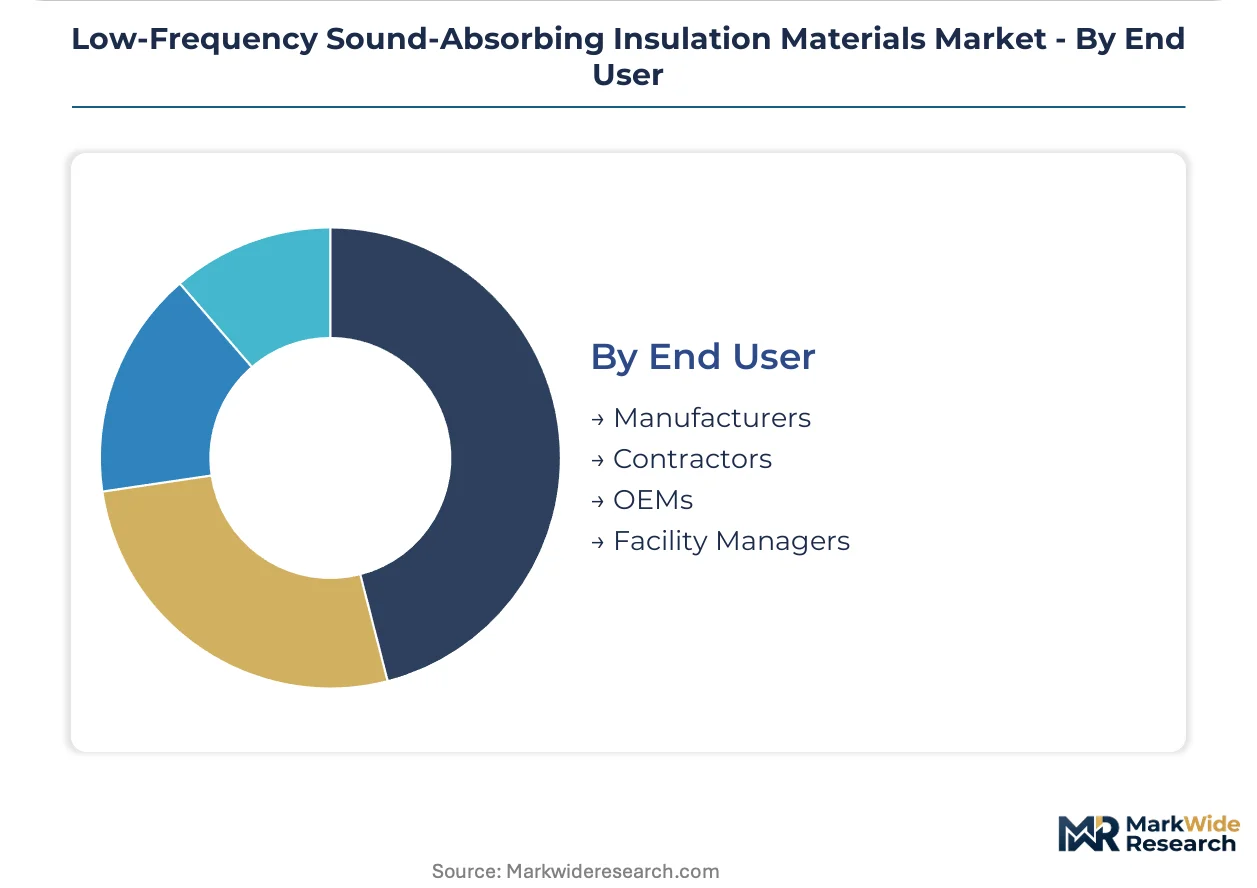
- Manufacturers:Tier-1 automotive suppliers and construction product fabricators control formulation pipelines and acoustic testing infrastructure. These buyers source raw fiber, foam chemicals, and binder systems for captive conversion into finished insulation products.
- Contractors:Installation firms serving commercial and industrial building markets consolidate procurement under performance-based contracts. Green contractor certification programs in France and Germany reshape material selection toward recycled-content and bio-based alternatives.
- OEMs:Automotive and wind turbine original equipment manufacturers specify absorption performance against proprietary test protocols.
- Facility Managers:Building owners and operators responsible for OSHA compliance and tenant acoustic comfort drive replacement cycles in existing building stock.
Specification authority concentrates with OEMs and manufacturers. Compliance-driven replacement volume flows through contractors and facility managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors acoustic materials engineering for electric vehicle cabin quieting, with Wolfsburg and Ingolstadt forming a southern German cluster that drives premium insulation sourcing across European automotive programs.
Germany
Automotive OEMs in Baden-Württemberg and Lower Saxony specify multi-layer foam composites for powertrain NVH reduction as internal combustion engine masking disappears. REACH chemical restrictions from ECHA accelerate substitution of formaldehyde-based binders with bio-alternatives in building products. The Stuttgart-Wolfsburg corridor concentrates acoustic R&D centers from Tier-1 suppliers and material formulators serving premium vehicle programs.
United States
OSHA noise-exposure limits mandate industrial acoustic treatments in manufacturing facilities and data center mechanical rooms. The EPA oversees emissions testing protocols for binder chemistries used in construction-grade insulation products. Industrial clusters in Michigan and Ohio drive specification of certified absorption performance for compliance-driven replacement cycles in automotive and heavy manufacturing plants.
China
Electric vehicle production in Shanghai and Shenzhen creates demand for lightweight cabin insulation as domestic OEMs expand premium EV lineups. MIIT oversees national standards for automotive interior materials including acoustic performance requirements. The Yangtze River Delta concentrates manufacturing of open-cell polyurethane foams serving both automotive seating and NVH applications.
France
Green contractor certification programs reshape procurement toward recycled-content polyester fiber certified under tightening embodied-carbon rules. ANSM and ECHA jointly govern chemical emissions testing for construction products entering French building markets. The Île-de-France region anchors facility management service contracts that bundle acoustic installation with performance monitoring for commercial building mechanical rooms.
Japan
METI promotes advanced materials development including metamaterial-structured absorbers for sub-wavelength resonance targeting in industrial applications. JIS standards govern acoustic performance testing for building and transportation insulation products. The Nagoya-Toyota corridor concentrates automotive acoustics engineering for hybrid and electric powertrain noise control programs.
Low-Frequency Sound-Absorbing Insulation Materials Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct technology vectors in acoustic materials. The market structure consolidates around integrated chemical conglomerates controlling polymer formulation pipelines, while specialized fabricators capture specification premiums in automotive and renewable energy niches. Three archetypes dominate: diversified material science conglomerates with captive R&D infrastructure, regional foam converters serving construction distribution channels, and acoustic engineering specialists bundling material supply with performance certification. Competitive dynamics center on backward integration into bio-based binder chemistry and strategic partnerships with wind turbine OEMs piloting metamaterial hybrid structures.
Among diversified material science conglomerates, Saint-Gobain exemplifies the integrated service model through its building-science arm bundling acoustic modeling with material supply. Autoneum occupies a position within the automotive-specialist tier, anchoring technology leadership through captive R&D centers in acoustic vehicle development. BASF represents the chemical-formulation archetype, controlling polymer chemistry pipelines that feed both automotive NVH and construction insulation channels across European and Asian markets.
| Leading Market Players |
|---|
| Saint-Gobain |
| Autoneum |
| 3M |
| DuPont |
| BASF |
| Mitsubishi Chemical Holdings |
| Stevens Insulation LLC |
| Wan Rui Chemical |
| Yuan Yuan Sponge Products |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal embodied-carbon mandates for building products are forcing binder reformulation across construction-grade insulation, compelling suppliers to absorb qualification costs or cede specification eligibility to bio-based competitors. This procurement pivot compresses margins on conventional fiberglass while opening premium pricing corridors for CE-marked low-GWP foam formulations.
Pricing Analysis
Margin tightening in specification-grade foam reflects simultaneous petrochemical input volatility and REACH-driven reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated automotive NVH materials from commodity construction batts, with certification grade and volume scale as primary differentiation drivers. Pricing pressure intensifies in mineral wool segments as weight-driven automotive specifications favor lighter substrates. Tier-1 automotive suppliers exhibit lowest price sensitivity due to performance validation requirements, while construction contractors face acute cost pressure under fixed-bid retrofit contracts.
Supply Chain Analysis
Domestic-content requirements under France's green contractor certification programs and Germany's CE marking protocols are reshaping sourcing toward regional bio-based binder production. Manufacturing concentrates in Germany, China, and the United States, with polyurethane foam chemical feedstocks drawing from petrochemical complexes in the Yangtze River Delta and the US Gulf Coast. Supply chain risk centers on EU F-Gas Regulation phase-downs constraining hydrofluorocarbon availability for foam expansion. Distribution runs through captive Tier-1 automotive supply chains and construction product distribution networks serving facility management service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constrained blowing agent supply under EU F-Gas phase-down schedules props pricing for qualified foam formulations, creating durable margin pools for incumbent producers with validated low-GWP chemistries.
For Market Incumbents: Extend backward integration into bio-based binder production to defend formulation pipelines against REACH chemical restrictions. Lock in multi-year offtake agreements with Stuttgart-area automotive OEMs before second-tier foam converters achieve NVH validation certification. Capacity addition in France and Germany secures CE marking eligibility as green procurement criteria harden. For New Entrants and Emerging Players: Direct-to-facility-manager digital platforms bypass consolidated construction distribution channels to capture OSHA-mandated industrial retrofit volume. Wind turbine nacelle acoustics in Spain and Denmark represents the most penetrable application, with metamaterial-structured absorber pilots creating specification entry points. Partner with renewable energy EPC contractors for bundled acoustic-performance contracting. For Investors and Strategic Acquirers: Re-rating potential sits with acoustic engineering specialists given convergence of metamaterial manufacturing with roll-to-roll production methods collapsing cost premiums. Long-term viability favors asset-light designers with captive R&D infrastructure serving automotive and renewable energy niches. Watch for CE marking backlog resolution as inflection signal for bio-based formulation scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | REACH compliance secures CE marking eligibility for German and French construction markets. |
| Metamaterial Manufacturing Scale-Up | Danish wind turbine OEM pilot programs validate sub-wavelength absorption for nacelle tonal control. |
| Performance-Based Service Contracting | OSHA audit mandates in US industrial facilities displace transactional spot purchasing for wall panel retrofits. |
| Automotive NVH Validation Certification | Stuttgart-Wolfsburg engineering clusters lock in multi-year supply relationships with Tier-1 suppliers. |
| Low-GWP Foam Formulation Qualification | EU F-Gas Regulation phase-down preserves specification access as hydrofluorocarbon supply constricts. |
Study Parameters
Trade association filings from Cefic, customs data from Eurostat, and automotive production databases formed the secondary backbone, cross-referenced with primary interviews involving acoustic materials R&D directors, Tier-1 supplier procurement managers, facility management executives, and construction product distribution heads. Bottom-up and top-down triangulation reconciled formulation-level cost structures with end-use demand aggregation across automotive, construction, and renewable energy channels.
Bottom-up modeling anchored volume projections to electric vehicle platform ramp schedules and wind turbine installation forecasts, while top-down validation tested segment totals against chemical feedstock demand indicators. Segmentation across material type, application environment, installation method, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating REACH regulatory phase-in timelines and EU Green Deal embodied-carbon trajectory assumptions.
The model holds under stable petrochemical input pricing and gradual F-Gas Regulation phase-down schedules; deviation in polyol-isocyanate volatility or accelerated blowing agent restrictions would shift volume toward mineral wool and polyester fiber alternatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Thin Insulation Market