
 Protective Building Materials Market | 2026-2036
Protective Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Building Materials Market Outlook
CE marking under the Construction Products Regulation is collapsing the competitive field for protective building materials sold across European Union member states. Owens Corning leverages its mineral wool manufacturing scale to dominate industrial insulation specifications in North America. Sika AG anchors its position through waterproofing system integration and direct contractor channel control. BASF SE differentiates via polyurethane chemistry leadership in spray-applied thermal barriers.
Protective building materials encompass engineered substances and assemblies designed to shield structures from thermal loss, flame propagation, ballistic impact, moisture ingress, and chemical degradation, typically measured by fire-resistance ratings in minutes and U-values in thermal conductivity. These materials serve primarily to extend building lifespan, reduce operational energy, and preserve occupant safety under extreme loading events. Fire-resistant coatings command premium margin pools in commercial building specifications due to phased-in mandates for passive fire protection. Waterproof membranes represent the fastest-growing product category as climate-adaptive retrofitting accelerates across coastal infrastructure projects. Insulation maintains volume leadership but faces margin compression from commodity mineral fiber competition.
EPA regulations on formaldehyde emissions from composite wood products and REACH restrictions on flame-retardant chemistries are forcing reformulation across polyurethane and intumescent coating lines. OSHA workplace exposure limits during spray foam installation shape contractor training requirements and product substitution patterns in the United States. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules that will determine which material chemistries retain specification access in high-value construction markets.
Market Dynamics
EU Green Deal implementation is compressing specification windows for protective building materials across European construction markets, forcing rapid chemistry transitions in thermal and fire-rated systems.
Growth Catalysts
- Retrofit mandates in Germany:National building energy efficiency regulations are accelerating mineral wool and intumescent coating specifications in existing commercial stock.
- REACH restrictions on halogenated flame retardants:ECHA-driven reformulation deadlines are pulling phosphorus-based alternatives into specification dominance across polyurethane foam lines.
- Coastal infrastructure resilience programs:Climate-adaptive waterproofing demand is concentrating specification pull from port authorities and flood-defense contractors in the Netherlands and Belgium.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs for spray polyurethane foam remain structurally exposed to crude oil and natural gas price swings.
- Mineral wool supply concentration:High-temperature industrial insulation capacity clusters in a limited set of European production sites, creating geographic vulnerability to energy cost spikes.
- Intumescent coating cure-time limitations:Extended application windows in high-humidity environments restrict year-round deployment in Northern European climates.
Strategic Opportunities
- Carbon-border adjustment preparation:Early certification of embodied-carbon disclosures under developing EU CBAM rules will secure specification access for low-chemistry insulation systems.
- Building-integrated photovoltaics convergence:Fire-rated backsheet and mounting insulation combinations represent unpenetrated specification space in commercial rooftop solar deployments.
- Direct contractor digital platforms:Bypassing traditional distribution through specification-software integration creates channel control for system suppliers in French and Italian markets.
Industry Challenges
- Spray foam installer certification gaps:OSHA respiratory protection compliance and equipment training requirements are constraining qualified contractor availability in US commercial markets.
- CE marking documentation complexity:Multi-country notified body coordination for Construction Products Regulation compliance extends product launch timelines by 12-18 months for novel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Building Materials Market |
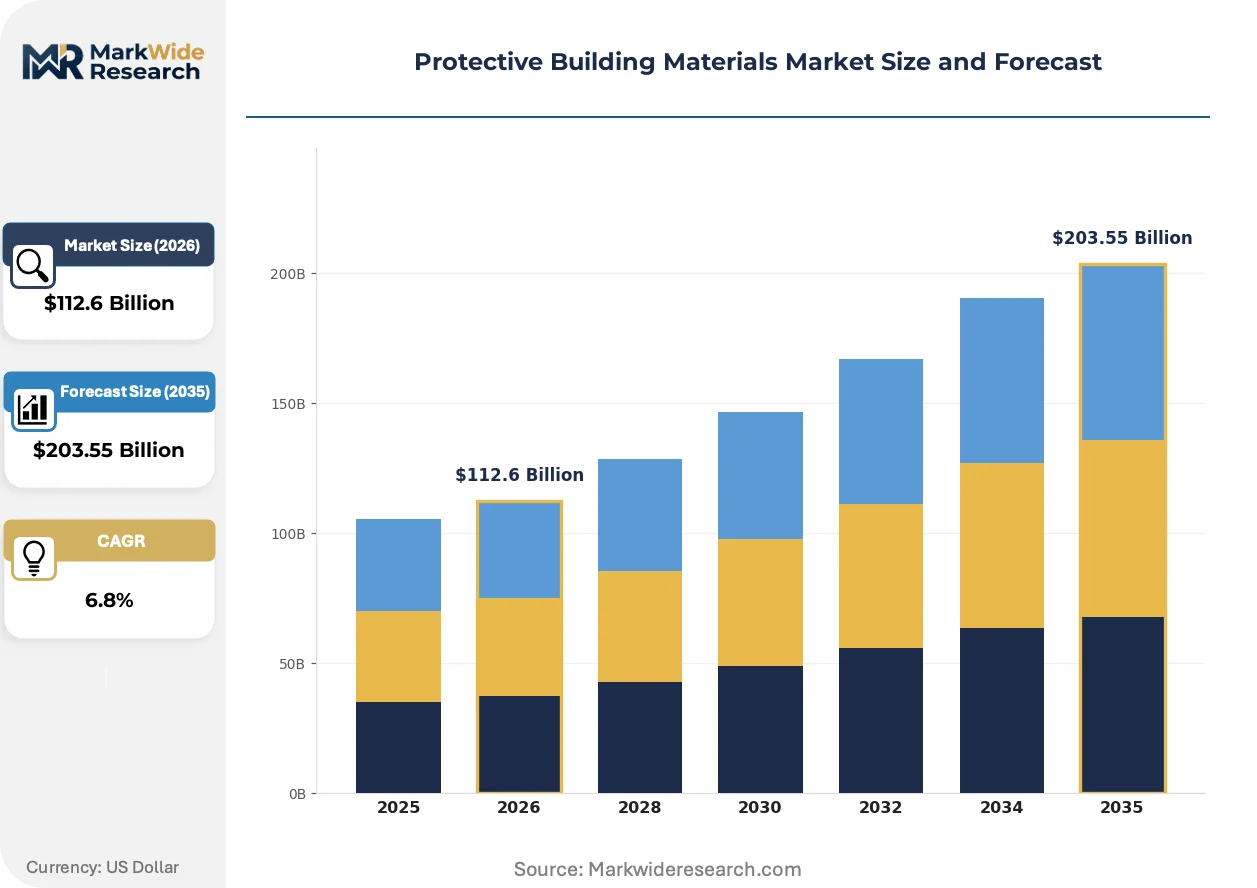
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Fire-Resistant Coatings, Impact-Resistant Glass, Waterproof Membranes Application: Commercial Buildings, Residential Structures, Industrial Facilities, Infrastructure Projects Installation: New Construction, Renovation, Retrofitting, Modular Installation End User: Contractors, Architects, Builders, Property Developers |
| Companies Covered | BASF SE, 3M, Owens Corning, Sika AG, DuPont, Knauf Insulation, Trelleborg AB, Cymat Building Materials, CBC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Building Materials Market Strategic Shifts
Aerogel insulation composites are compressing thermal conductivity thresholds previously held by vacuum panels, while bio-based binder chemistries displace formaldehyde-releasing systems in mineral fiber production.
Aerogel-blanket systems are fragmenting the high-performance thermal insulation segment by delivering sub-20 mW/m·K conductivity without vacuum maintenance requirements. Data center and cold-chain logistics operators are specifying silica-aerogel composites for space-constrained envelope retrofits. This performance tier is fragmenting the traditional premium insulation market into conductivity-specific specification bands.
The EU F-Gas Regulation phase-down is compressing availability of hydrofluorocarbon blowing agents used in closed-cell spray foam formulations. Polyurethane system houses are accelerating hydro-olefin and water-blown chemistry transitions to maintain specification compliance. Nordic and Alpine markets are experiencing the fastest formulation switches due to earlier national HFC bans.
Performance-guarantee contracting is displacing unit-price procurement for integrated waterproofing and insulation systems in UK social housing retrofit programs. Contractors assume lifecycle liability in exchange for multi-year maintenance contracts. This model is concentrating specification authority with national-tier installation groups capable of balance-sheet backing.
Protective Building Materials Market Segmentation
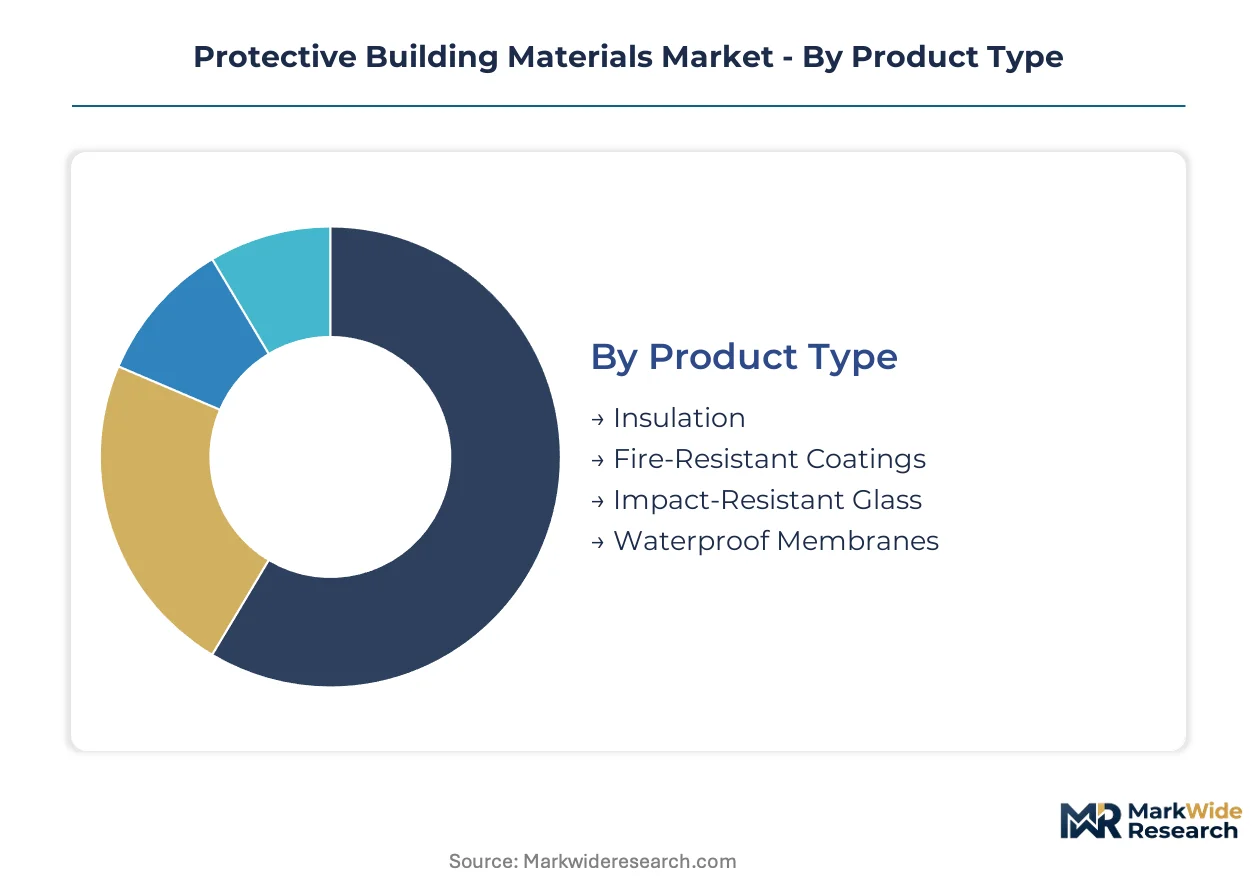
Protective building materials fragment sharply across performance tiers and procurement channels. Specification authority varies dramatically between new construction and retrofit contexts, reshaping how suppliers configure product portfolios and pricing architectures.
Product Type:
Mineral wool and spray polyurethane foam dominate domestic production clusters in Germany and the United States, while aerogel composites and advanced intumescent systems travel through specialized export channels serving data center and aerospace contractors.
- Insulation:Mineral wool, fiberglass batts, and spray polyurethane foam assemblies deliver thermal resistance measured in R-values and U-values. German industrial retrofit mandates are compressing specification windows for mineral wool in existing commercial envelopes, though polyol feedstock volatility constrains spray foam margin stability.
- Fire-Resistant Coatings:Intumescent and cementitious formulations expand under heat exposure to form insulating char layers. Dutch port authorities and Belgian flood-defense contractors are pulling specification volume for cementitious systems in coastal infrastructure resilience programs, where extended cure times in high-humidity Northern European climates restrict year-round deployment.
- Impact-Resistant Glass:Laminated and tempered assemblies with interlayer reinforcement against ballistic and blast loading. Security-sensitive federal and institutional specifications in France and Italy concentrate demand.
- Waterproof Membranes:Bituminous, thermoplastic, and liquid-applied barriers against moisture ingress. Climate-adaptive retrofitting across Netherlands coastal zones is accelerating specification velocity for liquid-applied systems.
Insulation holds the largest share; momentum sits with waterproof membranes.
Application:
Cost-tier stratification separates commodity mineral fiber specifications in residential construction from premium aerogel and intumescent deployments in mission-critical commercial and industrial envelopes.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures drive fire-rated assembly specifications. CE marking under the Construction Products Regulation compresses competitive fields for passive fire protection systems across EU member states.
- Residential Structures:Single-family and multi-family housing stock favors batt and loose-fill insulation for cost-sensitive thermal code compliance. German Energieeinsparverordnung mandates are accelerating mineral wool retrofit specifications in existing residential envelopes.
- Industrial Facilities:Manufacturing plants, warehouses, and energy infrastructure demand high-temperature insulation and fire-resistant coatings. REACH restrictions on halogenated flame retardants are pulling phosphorus-based alternatives into specification dominance across polyurethane foam lines serving petrochemical and power generation sites.
- Infrastructure Projects:Transportation, water treatment, and coastal defense installations require waterproofing and impact-resistant systems. UK social housing retrofit programs are displacing unit-price procurement with performance-guarantee contracting for integrated waterproofing and insulation systems.
Commercial buildings anchor volume; infrastructure projects are climbing the fastest.
Installation:
Customer-type concentration separates specification authority between developer-driven new construction and contractor-controlled renovation channels.
- New Construction:Ground-up building projects allow integrated system design from structural framing through envelope completion. Direct contractor digital platforms in French and Italian markets are bypassing traditional distribution through specification-software integration.
- Renovation:Partial system replacement in occupied structures demands phased installation protocols. OSHA respiratory protection compliance and equipment training requirements constrain qualified spray foam contractor availability in US commercial renovation markets.
- Retrofitting:Deep energy retrofits of existing building envelopes dominate EU Green Deal implementation. National building energy efficiency regulations in Germany are accelerating mineral wool and intumescent coating specifications in existing commercial stock.
- Modular Installation:Factory-assembled panel systems with pre-installed protective layers. Offsite construction growth in Nordic markets favors standardized fire-rated and thermally broken envelope assemblies.
Retrofitting holds the largest share; modular installation is gaining share fastest.
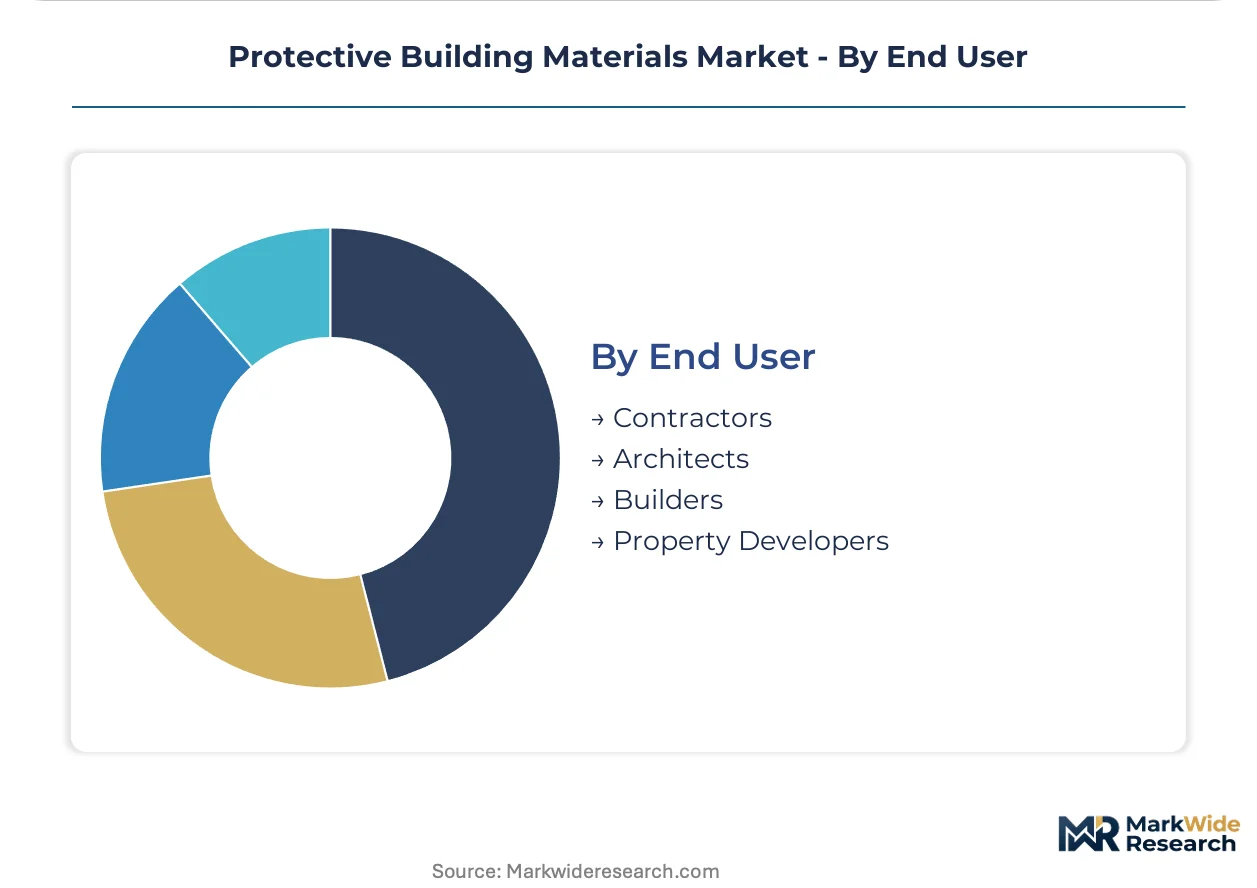
End User:
Supply concentration clusters specification influence with national-tier contractor groups capable of balance-sheet backing for performance-guarantee contracts.
- Contractors:Installation firms execute procurement decisions for specified materials. Spray foam installer certification gaps and OSHA workplace exposure limits shape contractor training requirements and product substitution patterns in US markets.
- Architects:Design professionals control early-stage specification authority. EU F-Gas Regulation phase-down is compressing hydrofluorocarbon blowing agent availability, forcing architects to specify hydro-olefin and water-blown polyurethane formulations in Nordic and Alpine markets.
- Builders:Construction firms managing vertical development projects. Carbon-border adjustment preparation under developing EU CBAM rules will determine which material chemistries retain specification access for builders targeting high-value construction markets.
- Property Developers:Asset owners and development firms optimizing lifecycle returns. Building-integrated photovoltaics convergence creates unpenetrated specification space for fire-rated backsheet and mounting insulation combinations in commercial rooftop solar deployments.
Contractors hold the largest share; property developers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal implementation is compressing specification windows across European construction markets, while US federal infrastructure spending and coastal resilience programs pull demand for fire-rated and waterproof systems in distinct regional patterns.
Germany
Industrial retrofit mandates and Energieeinsparverordnung regulations are accelerating mineral wool specifications in existing commercial envelopes. REACH restrictions on halogenated flame retardants are forcing phosphorus-based chemistry transitions in polyurethane foam lines. The Rhine-Ruhr industrial corridor concentrates high-temperature insulation demand from petrochemical and power generation facilities.
United States
OSHA respiratory protection compliance and spray foam installer certification requirements are reshaping contractor availability in commercial renovation markets. EPA regulations on formaldehyde emissions from composite wood products drive reformulation across insulation binders. Gulf Coast port authorities and Texas petrochemical clusters are pulling specification volume for cementitious fire-resistant systems in coastal infrastructure resilience programs.
Netherlands
Climate-adaptive waterproofing demand is concentrating specification pull from port authorities and flood-defense contractors in delta protection infrastructure. The EU F-Gas Regulation phase-down is compressing hydrofluorocarbon blowing agent availability for closed-cell spray foam. The Rotterdam-The Hague metropolitan region anchors specification velocity for liquid-applied membrane systems in below-grade and marine applications.
France
CE marking under the Construction Products Regulation is collapsing competitive fields for passive fire protection systems across new commercial construction. Direct contractor digital platforms are bypassing traditional distribution channels through specification-software integration. The Paris-Saclay research cluster and Lyon industrial basin concentrate demand for security-sensitive federal and institutional impact-resistant glazing specifications.
China
Dual carbon goals and national building energy efficiency codes are accelerating demand for low-thermal-conductivity insulation in commercial envelope retrofits. GB standards for fire-rated construction materials are tightening test protocols for intumescent coating systems. The Yangtze River Delta manufacturing corridor concentrates production capacity for mineral fiber and advanced thermal barrier composites serving domestic and export markets.
Protective Building Materials Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and specification channel control. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with polyurethane and coating chemistry depth, mineral fiber manufacturers with high-temperature industrial scale, and waterproofing system integrators with direct contractor relationships. Dominant competitive moves include backward integration into petrochemical feedstocks and geographic expansion through specification-software platform acquisitions.
Among European chemical conglomerates, BASF SE and Sika AG occupy positions representing distinct competitive vectors—polyurethane chemistry leadership versus waterproofing system integration. Owens Corning anchors the mineral fiber scale tier with industrial insulation manufacturing concentration. These three exemplify how specification authority in protective building materials flows through chemistry control, channel proximity, and production scale rather than brand recognition alone.
| Leading Market Players |
|---|
| BASF SE |
| 3M |
| Owens Corning |
| Sika AG |
| DuPont |
| Knauf Insulation |
| Trelleborg AB |
| Cymat Building Materials |
| CBC Group |
| Others |
Value Chain & Pricing Dynamics
CE marking under the Construction Products Regulation gates both supplier qualification and price differentiation simultaneously, compressing competitive fields for novel chemistries while expanding margin pools for certified incumbents serving German and French retrofit markets. Mineral wool and spray polyurethane foam specifications diverge sharply on certification burden, with phosphorus-based foam alternatives commanding premium positioning against legacy halogenated systems facing REACH phase-out deadlines.
Pricing Analysis
Certification level creates the primary spread between CE-marked premium tiers and uncertified commodity mineral fiber, with fire-resistance ratings measured in minutes driving step-function price premiums for intumescent coatings in Dutch port infrastructure. Three-tier pricing structure across certified-premium, standard-grade, and economy-batt levels separates specification authority between architect-driven commercial projects and cost-sensitive residential retrofits. Cost compression in spray polyurethane foam is intensifying because polyol and isocyanate feedstock volatility feeds directly into project-based contractor pricing. Residential builders exhibit highest price sensitivity, while data center operators and coastal flood-defense authorities prioritize thermal performance over unit economics.
Supply Chain Analysis
Inventory cycles for high-temperature mineral wool extend lead times during European energy cost spikes, forcing contractors into forward-contracting for Rhine-Ruhr industrial insulation deployments. Manufacturing gravity centers on Germany, the United States, and China for mineral fiber and polyurethane foam, with specialized aerogel composites traveling through concentrated export channels from Nordic production sites. Raw material flows draw from petrochemical feedstocks, silica precursors, and bio-based binder chemistries displaced by formaldehyde emission regulations. Single-source vulnerability concentrates in isocyanate supply for spray foam formulations. Distribution runs through specification-software platforms bypassing traditional merchant distributors in French and Italian commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protective building materials sit in early-cycle expansion as EU Green Deal retrofit mandates penetrate below the commercial surface into residential stock and industrial envelopes, with waterproof membrane specifications accelerating fastest across Netherlands coastal resilience programs.
For Market Incumbents: Fortify specification control through backward integration into phosphorus-based flame-retardant chemistry ahead of REACH halogenated phase-out deadlines, while anchoring contractor relationships via performance-guarantee contracting models that assume lifecycle liability in UK social housing. Mineral wool capacity concentration in limited European high-temperature sites creates geographic vulnerability that demands redundant production footprinting or captive energy supply arrangements. For New Entrants and Emerging Players: Direct contractor digital platform gaps in French and Italian markets offer white-space entry where incumbent system houses under-serve mid-tier installation firms lacking specification-software integration. Modular offsite construction growth in Nordic markets favors standardized fire-rated panel systems with pre-installed thermal breaks, a segment penetrable through building-integrated photovoltaics convergence for commercial rooftop solar backsheet specifications. Go-to-market traction requires CE marking investment and notified body relationships that compress 12-18 month launch timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aerogel composite manufacturing as silica-precursor processing and vacuum-free blanket production demand specialized equipment scales. Five-to-ten year viability favors acquisition targets with embodied-carbon disclosure capabilities positioned for EU carbon-border adjustment mechanism compliance, particularly low-chemistry insulation system houses with certified supply chains. The signal to watch is hydro-olefin blowing agent formulation transitions accelerating in Nordic and Alpine markets ahead of F-Gas Regulation phase-down deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Polyol and isocyanate supply security anchors spray foam margin stability against crude volatility. |
| CE Marking and Notified Body Certification | Construction Products Regulation compliance gates specification access across German and French commercial markets. |
| Performance-Guarantee Contracting Model | UK social housing retrofits concentrate authority with balance-sheet-backed national-tier installation groups. |
| Phosphorus-Based Flame-Retardant Transition | REACH restrictions on halogenated chemistries pull reformulated polyurethane into specification dominance. |
| Direct Contractor Digital Platform | French and Italian specification-software integration bypasses traditional distribution for system supplier channel control. |
Study Parameters
Operator-level perspectives from plant managers at mineral wool and polyurethane manufacturing facilities, procurement leads at German industrial retrofit contractors, specification architects in French commercial construction, and technical R&D directors at coating system houses anchored the qualitative base. Secondary validation drew from ECHA REACH substance registrations, EU Construction Products Regulation notified body documentation, SEC 10-K filings from listed chemical conglomerates, and customs data tracking mineral fiber trade flows. Bottom-up volume builds across product type, application, installation method, and end-user segments triangulated against top-down macroeconomic construction spend models.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning insulation grade tier, fire-resistance rating class, waterproof membrane chemistry family, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation adjusted for policy inflection points including EU F-Gas Regulation phase-down schedules and national building energy efficiency code adoption curves. Modeled inputs incorporated contractor certification gap constraints from OSHA respiratory protection requirements and embodied-carbon disclosure preparation timelines for EU CBAM implementation.
Forecasts assume regulatory continuity in REACH chemical restrictions and Construction Products Regulation CE marking regimes; material policy shifts including accelerated flame-retardant bans or carbon-border adjustment scope expansion would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Insulation Products Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Global Glass Insulation Market