
 Multi-Layer Cryogenic Insulation Market | 2026-2036
Multi-Layer Cryogenic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Layer Cryogenic Insulation Market Foresight
The gap between aerospace-grade vacuum insulation and commodity flexible wraps for LNG transport is consolidating around certification depth and layer count precision. Chart Industries leverages its integrated cold box manufacturing to anchor North American LNG infrastructure demand. BASF SE competes through advanced polymer science for rigid panel substrates that sustain extreme thermal cycling.
Multi-layer cryogenic insulation comprises alternating radiation shields and low-conductivity spacers, typically operating below 77 Kelvin with effective thermal conductivity below 0.0001 W/m·K, engineered to minimize boil-off in liquid hydrogen, oxygen, and natural gas containment systems. Flexible insulation dominates installation economics across retrofit LNG pipelines, while vacuum insulation captures the highest margin pools in spacecraft and research laboratory applications where weight constraints override cost sensitivity. Aerogel insulation extends performance boundaries in energy sector storage tanks where hydrophobicity and compression resistance prove critical.
EPA methane regulations and the EU F-Gas framework tighten permissible boil-off rates, forcing energy sector buyers to validate insulation performance through third-party thermal testing. ISO 12217 and NASA-STD-5019 establish material qualification protocols that determine supplier eligibility for aerospace and research laboratory contracts. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as liquid hydrogen transport protocols will redefine layer count specifications and installation certification requirements.
Market Dynamics
The EPA's methane regulations and the EU F-Gas Regulation are compressing permissible boil-off rates, forcing buyers to validate insulation performance through third-party thermal testing. This regulatory tightening is reshaping procurement specifications across LNG infrastructure, aerospace, and hydrogen storage applications.
Growth Catalysts
- LNG infrastructure buildout:The United States, Qatar, and Australia are expanding liquefaction capacity. Terminal operators require higher-layer-count insulation to meet stricter thermal performance mandates.
- EU F-Gas Regulation:This framework tightens permissible boil-off rates for cryogenic systems. End users are upgrading to multi-layer solutions that demonstrate verified thermal conductivity below 0.0001 W/m·K.
- Spacecraft insulation procurement:NASA's Artemis program and ESA's Ariane 6 are accelerating demand for vacuum insulation panels. Weight constraints in orbital vehicles override cost sensitivity.
Market Restraints
- Aerogel raw material volatility:Silica precursor costs fluctuate with semiconductor sector demand. This input price instability compresses margins for rigid panel manufacturers.
- Specialized fabrication concentration:Vacuum insulation panel production clusters in Germany and Japan. Geographic supply concentration creates vulnerability to export control disruptions.
- Technical limitation in flexible wraps:Layer count precision above 30 layers degrades during field installation. This constrains performance validation for retrofit LNG pipeline projects.
Strategic Opportunities
- Liquid hydrogen transport protocols:Germany and the Netherlands are developing infrastructure codes for hydrogen economy buildout. These standards will redefine layer count specifications and installation certification requirements.
- Research laboratory expansion:Quantum computing facilities require extreme thermal isolation. This emerging application segment values performance over procurement cost.
- ISO 12217 convergence:Global standardization of material qualification protocols reduces supplier re-certification burden. Qualified vendors gain accelerated access to aerospace and energy sector contracts.
Industry Challenges
- Multi-physics simulation talent scarcity:Cryogenic thermal modeling requires expertise in radiation heat transfer and vacuum physics. Engineering departments compete with semiconductor and aerospace sectors for this specialized workforce.
- NASA-STD-5019 certification timeline:Aerospace material qualification extends 18-24 months. This duration blocks rapid product iteration for suppliers targeting spacecraft insulation procurement cycles.
- Legacy pipeline retrofit integration:Existing LNG terminals operate on single-layer insulation specifications. Upgrading to multi-layer systems requires coordinated shutdown scheduling with terminal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Layer Cryogenic Insulation Market |
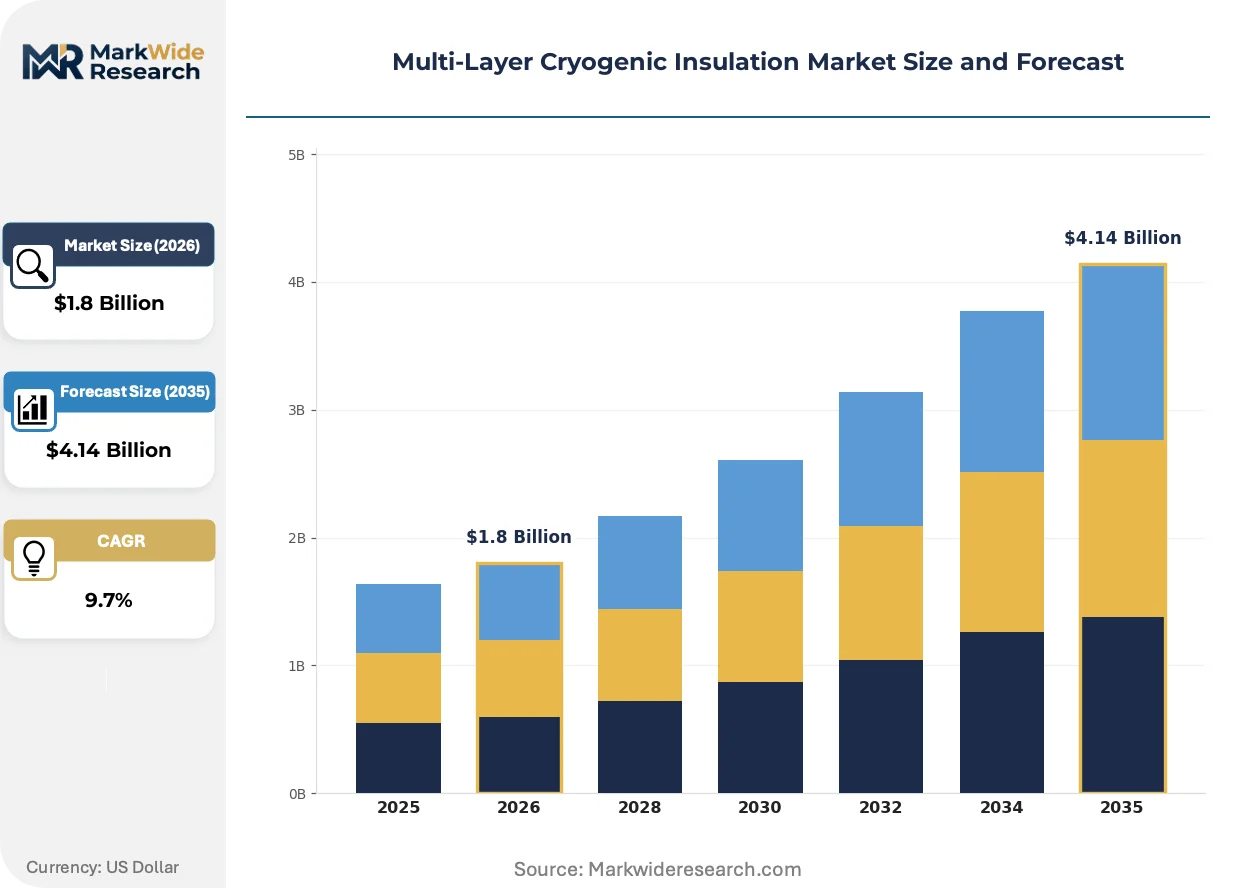
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Insulation, Rigid Panels, Vacuum Insulation, Aerogel Insulation Application: Storage Tanks, LNG Pipelines, Cryogenic Transportation, Spacecraft End User: Energy Sector, Aerospace, Food Industry, Research Laboratories Installation Type: Onshore, Offshore, Fixed, Mobile |
| Companies Covered | Lydall Inc., Chart Industries, Inc., BASF SE, L'Air Liquide S.A., Linde plc, Saint-Gobain, Aspen Aerogels, Dunmore Corporation, Armacell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Layer Cryogenic Insulation Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape insulation procurement. Buyers now prioritize verified thermal performance over installed cost, compressing supplier qualification timelines.
Polymer-reinforced aerogel composites are electrifying performance boundaries in energy sector storage tanks. Hydrophobic silica formulations sustain compression resistance during thermal cycling. Major LNG terminal operators in Qatar and the United States are specifying these materials for new-build capacity. This technology is electrifying margin pools away from conventional fiberglass wraps toward certified high-performance substrates.
REACH compliance requirements in Europe are forcing reformulation of reflective radiation shield materials. Aluminum-polymer laminates face substitution pressure from copper-based alternatives with lower embodied carbon. German and French insulation fabricators are retooling deposition lines to meet substance restriction deadlines. Aerospace-grade suppliers with pre-qualified material portfolios capture accelerated procurement cycles.
Specification-driven procurement now dominates large-capacity LNG terminal contracts. Engineering-procurement-construction firms bundle insulation performance guarantees into turnkey agreements. This unbundles after-sales service from material supply, compressing standalone insulation vendor margins. The pattern is most visible in United States Gulf Coast projects where FERC permitting timelines incentivize single-source accountability.
Multi-Layer Cryogenic Insulation Market Segmentation
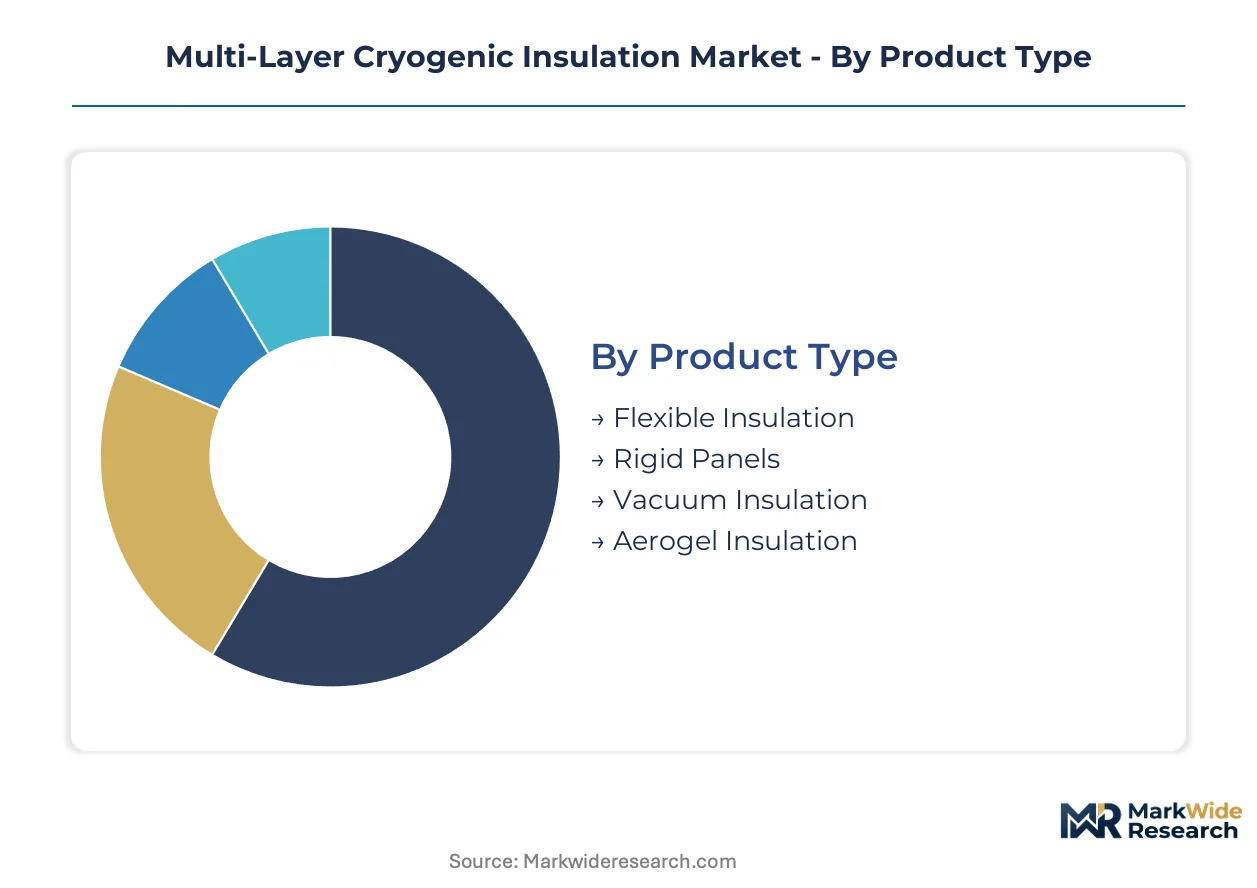
Segmentation in multi-layer cryogenic insulation reveals how thermal performance requirements diverge across installation constraints, regulatory environments, and end-use criticality. Procurement specifications vary dramatically between retrofit LNG infrastructure and aerospace qualification protocols.
Product Type:
The customization-to-standardization spectrum stretches from field-fabricated flexible wraps to precision-manufactured vacuum panels with 18-24 month certification timelines.
- Flexible Insulation:Alternating radiation shields and low-conductivity spacers in blanket form enable rapid deployment across curved surfaces. Demand concentrates in United States Gulf Coast LNG retrofit projects where FERC-permitted shutdown windows compress installation schedules.
- Vacuum Insulation:Evacuated panels with multi-layer getter systems achieve thermal conductivity below 0.0001 W/m·K. NASA's Artemis program and ESA's Ariane 6 drive procurement in spacecraft applications where weight constraints override cost sensitivity.
- Rigid Panels:Polymer-reinforced substrates sustain compression loads in stationary storage systems.
- Aerogel Insulation:Hydrophobic silica formulations resist thermal cycling degradation in energy sector tanks.
Leading the category by volume: Flexible Insulation. Expanding most quickly: Vacuum Insulation.
Application:
Volume concentration follows LNG infrastructure buildout patterns while margin pools concentrate in qualification-intensive segments.
- Storage Tanks:Large-capacity containment systems for liquid hydrogen, oxygen, and natural gas require layer counts above 30 for boil-off compliance. Qatar and United States terminal operators specify polymer-reinforced aerogel composites for new-build capacity.
- Spacecraft:Orbital vehicles demand vacuum insulation with NASA-STD-5019 qualification. ESA's Ariane 6 program accelerates procurement cycles for pre-certified material portfolios.
- LNG Pipelines:Retrofit installations face layer count precision degradation above 30 layers during field deployment.
- Cryogenic Transportation:Mobile containment systems balance weight constraints against thermal performance validation.
Dominant by revenue: Storage Tanks. Steepest expansion trajectory: Spacecraft.
End User:
Procurement authority varies between engineering-procurement-construction firms bundling performance guarantees and direct aerospace agency qualification.
- Energy Sector:LNG terminal operators and hydrogen infrastructure developers drive bulk volume. EPA methane regulations and EU F-Gas framework force upgrades from single-layer to multi-layer specifications.
- Aerospace:NASA and ESA procurement cycles prioritize pre-qualified suppliers with existing NASA-STD-5019 portfolios. Material qualification timelines block rapid product iteration for new entrants.
- Research Laboratories:Quantum computing facilities require extreme thermal isolation with performance prioritization over procurement cost.
- Food Industry:Cryogenic freezing applications utilize standardized flexible insulation with shorter validation cycles.
Highest volume purchaser: Energy Sector. Gaining share fastest: Research Laboratories.
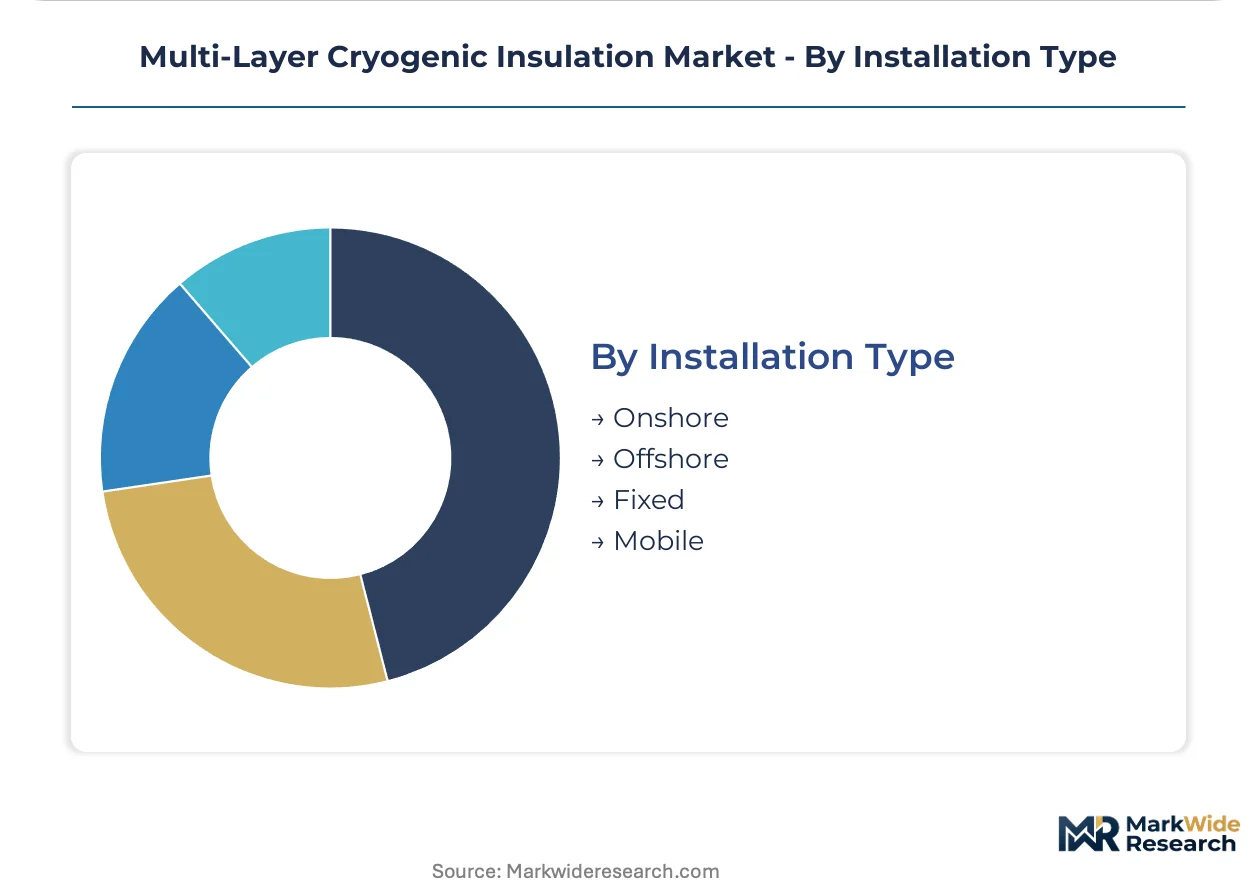
Installation Type:
Geographic and mobility constraints determine layer count precision achievable during deployment.
- Onshore:Fixed terrestrial installations permit controlled fabrication environments. United States Gulf Coast and Qatari LNG terminals specify onshore application for maximum layer count precision.
- Offshore:Marine environments demand hydrophobic formulations and corrosion-resistant radiation shields. North Sea and Australian offshore projects require specialized deposition line retooling for salt spray resistance.
- Fixed:Stationary systems allow thermal performance validation through third-party testing protocols.
- Mobile:Cryogenic transportation containers and spacecraft applications prioritize weight reduction over installation economics.
Largest installed base: Onshore. Climbing the fastest: Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the world's most concentrated LNG infrastructure cluster, with liquefaction terminals along the Texas and Louisiana coasts driving procurement volumes for multi-layer cryogenic insulation systems.
United States
Gulf Coast terminal operators in Texas and Louisiana are expanding liquefaction capacity to serve European and Asian export markets. EPA methane regulations under the Inflation Reduction Act tighten permissible boil-off rates, forcing upgrades from single-layer to multi-layer specifications. Cheniere Energy's Sabine Pass and Corpus Christi facilities anchor North American demand for flexible insulation with layer counts above 30.
Germany
Hydrogen economy infrastructure development in Hamburg and the Ruhr industrial corridor accelerates demand for liquid hydrogen storage systems. REACH compliance requirements force reformulation of reflective radiation shield materials, with aluminum-polymer laminates facing substitution pressure from copper-based alternatives. German fabricators in Bavaria and North Rhine-Westphalia are retooling deposition lines to meet substance restriction deadlines.
Qatar
North Field expansion projects position the Ras Laffan Industrial City as the world's largest LNG production hub. QatarEnergy's new-build capacity specifies polymer-reinforced aerogel composites for storage tank applications. The country's national oil company bundles insulation performance guarantees into engineering-procurement-construction contracts with single-source accountability requirements.
France
ESA's Ariane 6 program at the Guiana Space Centre drives aerospace-grade vacuum insulation procurement for launch vehicle propellant tanks. French fabricators in the Île-de-France region supply multi-layer insulation with NASA-STD-5019 qualification for orbital vehicle applications. CNES procurement cycles prioritize pre-qualified material portfolios with existing certification timelines.
Japan
Tokyo Bay industrial complexes and Osaka-Kobe manufacturing corridors sustain demand for cryogenic systems in semiconductor and research laboratory applications. METI hydrogen roadmap targets drive liquid hydrogen transport protocol development, with Kawasaki Heavy Industries advancing marine containment systems. Japanese vacuum insulation panel production concentrates in industrial zones around Nagoya and Yokohama.
Multi-Layer Cryogenic Insulation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the multi-layer cryogenic insulation market. Integrated cold box manufacturers and specialized material suppliers occupy distinct competitive tiers, with consolidation pressure mounting around certification depth and layer count precision. Three strategic archetypes dominate: integrated system builders with captive insulation production, advanced materials specialists with polymer science capabilities, and precision fabricators with vacuum panel expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, as engineering-procurement-construction firms bundle performance guarantees into turnkey terminal contracts.
Within the integrated system builder tier, Chart Industries exemplifies the vertically positioned competitor with cold box manufacturing capabilities. BASF SE occupies the advanced materials specialist position through its polymer science portfolio. Among precision fabricators, Aspen Aerogels represents the hydrophobic silica formulation segment serving energy sector storage applications. Lydall Inc. and Dunmore Corporation anchor the flexible insulation supply base for retrofit LNG pipeline projects. Saint-Gobain and Armacell International sit within the diversified industrial materials tier with cross-segment thermal management capabilities.
| Leading Market Players |
|---|
| Lydall Inc. |
| Chart Industries, Inc. |
| BASF SE |
| L'Air Liquide S.A. |
| Linde plc |
| Saint-Gobain |
| Aspen Aerogels |
| Dunmore Corporation |
| Armacell International |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power for multi-layer cryogenic insulation manufacturers serving LNG and hydrogen infrastructure buyers. Certification depth and layer count precision separate pricing tiers, with NASA-STD-5019 qualified suppliers commanding substantial premiums over commodity flexible wrap producers.
Pricing Analysis
Verified thermal performance below 0.0001 W/m·K anchors value-based pricing across spacecraft and research laboratory procurement cycles. Pricing stratifies across aerospace-grade vacuum panels, energy-sector aerogel composites, and retrofit flexible wraps based on certification level and installation complexity. Cost compression in commodity flexible insulation intensifies as EPC firms bundle performance guarantees into turnkey terminal contracts. Energy sector buyers exhibit highest price sensitivity, while aerospace agencies prioritize weight reduction over procurement cost.
Supply Chain Analysis
Silica precursor supply rests on semiconductor sector demand fluctuations, creating input price volatility for aerogel composite manufacturers. Geographic concentration clusters vacuum insulation panel production in Germany and Japan, with flexible insulation fabrication distributed across United States Gulf Coast and Qatari industrial zones. Aluminum-polymer laminate radiation shields face REACH-driven substitution pressure toward copper-based alternatives. Single-source vulnerability in specialized getter systems for vacuum panels poses structural risk. Distribution runs through engineering-procurement-construction firms bundling material supply into terminal construction contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer cryogenic insulation supply remains constrained by 18-24 month NASA-STD-5019 certification timelines, propping pricing power for qualified incumbents while blocking rapid capacity expansion from new entrants.
For Market Incumbents: Anchor market position through captive cold box manufacturing integration and accelerated certification pipeline investment. Defensive consolidation around polymer-reinforced aerogel composite capacity in Qatar and United States Gulf Coast terminals counters emerging flexible wrap specialists. Backward integration into silica precursor supply buffers semiconductor sector demand volatility. For New Entrants and Emerging Players: Polymer-reinforced aerogel formulation expertise offers a technology-first wedge into energy sector storage tank specifications. White-space concentration exists in liquid hydrogen transport protocol development across Germany and Netherlands infrastructure codes. Research laboratory quantum computing facility expansion presents penetrable demand with performance-over-cost procurement bias. Target direct qualification with hydrogen economy engineering standards bodies ahead of codified layer count specifications. For Investors and Strategic Acquirers: ESA Ariane 6 procurement acceleration is the leading indicator that aerospace-grade vacuum insulation demand is entering sustained expansion phase. Long-term viability centers on certification depth as durable competitive moat. Acquisition target archetype: precision fabricators with existing NASA-STD-5019 portfolios and untapped LNG energy sector crossover capability. Watch hydrogen economy infrastructure code finalization as demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursor Supply | Reduces semiconductor demand volatility exposure for aerogel composite margins. |
| NASA-STD-5019 Certification Pipeline Expansion | Accelerates supplier eligibility for Artemis and Ariane 6 spacecraft procurement cycles. |
| Hydrogen Economy Standards Body Engagement | Positions layer count specifications favorably before German and Dutch code finalization. |
| Polymer-Reinforced Aerogel Capacity Buildout | Captures QatarEnergy and US Gulf Coast terminal operator new-build specifications. |
| Copper-Based Radiation Shield Deposition Retooling | Meets REACH compliance deadlines for European aerospace and energy sector contracts. |
Research Methodology
Document review covered EIA liquefaction capacity filings, FERC terminal permitting records, ESA procurement disclosures, and NASA technical standards documentation, complemented by interviews with LNG terminal engineering directors, aerospace procurement officers at CNES and ESA, cryogenic insulation fabrication plant managers, and hydrogen infrastructure project developers. Secondary validation drew from customs trade data, SEC 10-K filings of listed industrial gas companies, and ISO certification registry databases. Bottom-up installation demand estimates triangulated against top-down energy sector capex projections.
Segment-level value and volume outputs across product type, application, end user, and installation type dimensions were generated through structured modeling of layer count specifications, certification tier penetration, and regional infrastructure buildout timelines. CAGRs were derived from regression analysis of historical procurement cycles against regulatory mandate implementation schedules. Industry-specific forecast inputs included EPA methane rule compliance deadlines and EU F-Gas Regulation phase-down trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hydrogen economy code delays or export control disruptions to vacuum panel supply. Forecasts reflect assumptions around Artemis program funding continuity and Qatar North Field expansion timelines. Regulatory acceleration in methane emissions standards or REACH substance restrictions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
High Temperature Insulation Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Insulation Products Market
Insulation Materials
Technical Foam Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Radiation Shielding Materials Market