
 Global Molded Foams Market | 2026-2036
Global Molded Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Foams Market Foresight
The EU Green Deal is expanding the addressable market for low-emission polyurethane foams across European manufacturing. BASF SE leverages its integrated polyol supply chain to serve automotive seating programs with certified sustainable content. Covestro AG anchors its competitive position through ISCC PLUS mass-balance allocations for MDI and TDI feedstocks. Huntsman Corporation differentiates via specialty catalyst systems that reduce VOC emissions during foam curing.
Molded foams are cellular polymer structures produced through reactive injection, compression, or bead-molding processes, typically achieving densities from 20 to 200 kg/m³ depending on end-use load-bearing requirements. These materials function primarily as energy-absorbing, thermally insulating, or vibration-isolating interfaces in engineered products. Polyurethane formulations dominate value capture due to their tunable stiffness and established supply chains, while polyethylene grades compete aggressively in packaging and protective cushioning where recyclability commands procurement preference. Rigid foam products concentrate margin pools in construction insulation and cold-chain logistics, whereas flexible molded parts sustain higher volumes in automotive and furniture applications.
REACH restrictions on isocyanate exposure and the EU F-Gas Regulation on blowing agents are reshaping formulation chemistry and equipment investment across European foam producers. The EPA in the United States enforces VOC emission limits through 40 CFR Part 63 that affect spray-applied polyurethane systems in building construction. China's MEE implements GB standards on formaldehyde release from interior foam materials, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory phase-in timelines for next-generation blowing agents and assess capital requirements for retrofitting molding lines to meet evolving emission thresholds.
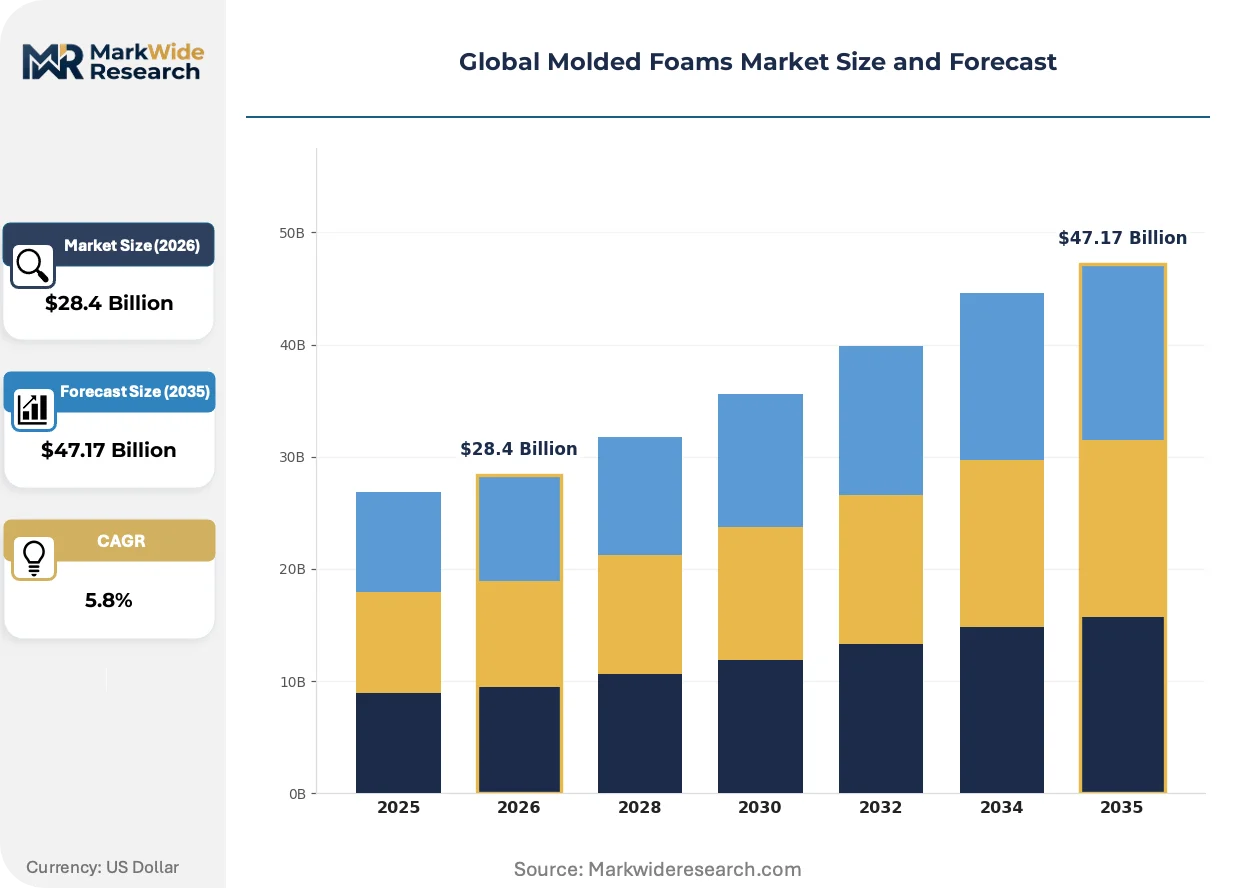
Market Dynamics
The molded foams sector is experiencing a fundamental chemistry pivot as REACH restrictions on isocyanate exposure and the EU F-Gas Regulation on blowing agents force simultaneous reformulation of polyurethane systems and capital reinvestment in molding equipment across European production facilities.
Growth Catalysts
- EU Green Deal compliance mandates:Binding carbon-neutrality targets for 2050 are compelling automotive OEMs to specify bio-based polyols and mass-balance certified feedstocks in seating and interior programs.
- Lightweighting imperatives in vehicle design:Fuel-efficiency regulations issued by NHTSA and the EPA are expanding procurement volumes for energy-absorbing foam structures in bumper cores and headliners.
- Cold-chain infrastructure buildout:Refrigerated logistics networks in India and Southeast Asia are sourcing rigid molded insulation panels for warehouse construction and transport container lining.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings directly compress margins on MDI, TDI, and polyol inputs, with limited pass-through elasticity in furniture and packaging segments.
- Blowing agent transition costs:The EU F-Gas Regulation and EPA SNAP program are phasing out HFC-based systems, requiring retooling investments that smaller molding operations cannot absorb without consolidation.
- Polyethylene substitution in protective packaging:Recyclable expanded polyethylene bead foams are displacing polyurethane in electronics cushioning where circular-economy procurement criteria dominate vendor selection.
Strategic Opportunities
- India construction insulation penetration:Energy-efficiency codes under BIS and state-level green building mandates are creating first-mover advantages for rigid polyurethane panel suppliers in commercial real estate.
- Medical device cushioning applications:Patient positioning and surgical support foams represent an underdeveloped vertical where ISO 13485 certification barriers limit incumbent competition.
- Chemical recycling infrastructure integration:Partnerships with pyrolysis and glycolysis operators are enabling closed-loop polyol recovery from post-industrial foam scrap, aligning with ECHA circular-economy guidance.
Industry Challenges
- Formulation chemistry expertise scarcity:The convergence of bio-based feedstock integration, low-VOC catalyst systems, and next-generation blowing agents requires polymer scientists with cross-functional competencies that technical training programs have not scaled to produce.
- Multi-jurisdiction certification timelines:Simultaneous compliance with REACH substance restrictions, EPA 40 CFR Part 63 emission limits, and China's GB formaldehyde standards extends product qualification cycles and fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Foams Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Foam Type: Polyurethane, Polyethylene, Polystyrene, Polyvinyl Chloride, Latex End Use Industry: Construction, Packaging, Automotive OEMs, Furniture Manufacturing, Electronics Application: Insulation, Cushioning, Vibration Dampening, Sealing, Soundproofing Product Form: Block Foam, Molded Foam Parts, Slab Stock, Flexible Foam, Rigid Foam |
| Companies Covered | BASF SE, Sealed Air Corporation, Huntsman Corporation, Dow Inc., Covestro AG, Recticel NV/SA, JSP Corporation, Armacell International, Zotefoams plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Foams Market Shifts & Advancements
Reactive processing technologies and feedstock traceability systems are redefining competitive advantage in molded foams, compressing the gap between laboratory formulation and production-scale qualification while embedding compliance documentation directly into supply chain data architectures.
Water-blown polyurethane systems with tunable cell structures are rewriting density-performance tradeoffs in automotive seating applications. Tier 1 suppliers in Germany and the Czech Republic are qualifying these formulations for premium vehicle programs where weight reduction targets have tightened. The technology is enabling thinner cross-sections without sacrificing durability metrics, compressing material usage per seat position.
REACH authorization requirements for diisocyanates are forcing systematic exposure-monitoring protocols and medical surveillance programs across European foam production facilities. Industrial hygiene investments now constitute a qualifying criterion for automotive OEM supplier status. The regulation is most acutely affecting small and mid-cap molders in Poland and Romania who lack occupational health infrastructure.
Automotive procurement departments are consolidating supplier panels and demanding ISCC PLUS or equivalent mass-balance certification as a condition of contract renewal. Direct material sourcing agreements between seating manufacturers and polyol producers are displacing distributor intermediaries in Western European supply chains. The behavior shift is most visible in Germany, where BMW, Mercedes-Benz, and Volkswagen Group have aligned sustainable purchasing criteria.
Global Molded Foams Market Segmentation
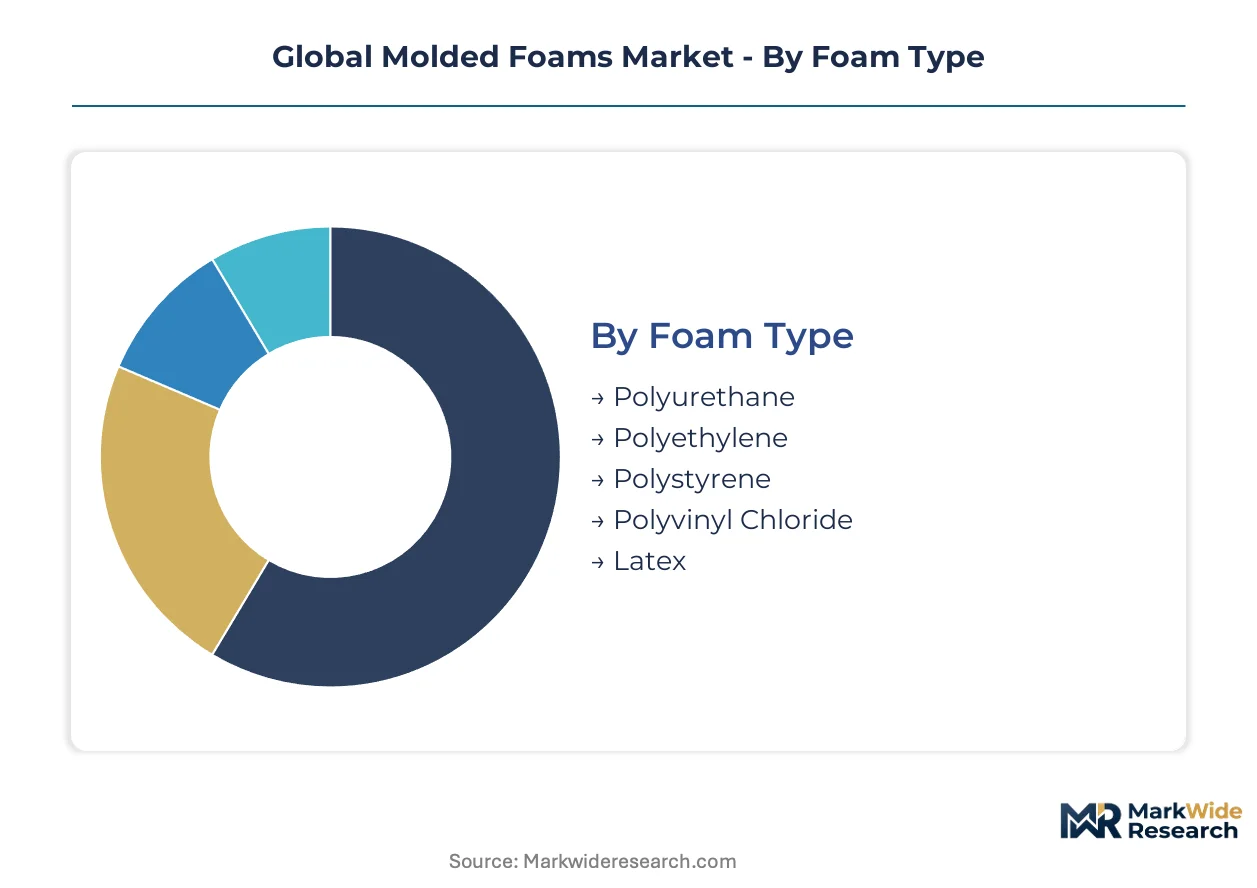
Segmentation in molded foams determines which regulatory frameworks govern production, which certification pathways suppliers must navigate, and where margin pools concentrate across chemistry and application boundaries. Buyers specify foam categories based on load-bearing requirements, thermal performance thresholds, and compliance with REACH, EPA, or BIS standards.
Foam Type:
REACH authorization for diisocyanates and EPA SNAP program phaseouts create divergent compliance burdens across chemistry platforms, with some formulations requiring medical surveillance protocols and others demanding blowing agent retooling.
- Polyurethane:Reactive polymer systems combining polyols with MDI or TDI isocyanates deliver tunable stiffness from 20 to 200 kg/m³. Automotive seating programs in Germany specify mass-balance certified polyurethane from BASF and Covestro to meet EU Green Deal procurement criteria, with ISCC PLUS documentation now mandatory for BMW, Mercedes-Benz, and Volkswagen Group contracts.
- Polyethylene:Expanded bead foams produced via compression molding achieve closed-cell structures ideal for repetitive impact absorption. Electronics packaging buyers in the United States and Southeast Asia specify recyclable polyethylene over polyurethane where circular-economy vendor scorecards dominate procurement decisions, displacing incumbent chemistries in protective cushioning applications.
- Polystyrene:Rigid molded insulation boards serve construction and cold-chain logistics with established supply chains in China and India.
- Polyvinyl Chloride:Plastisol-based open-cell formulations find niche applications in marine flotation and specialty sealing.
- Latex:Natural rubber-derived foams command premium positioning in furniture and medical cushioning where bio-based content differentiates supplier offerings.
Polyurethane sits at the top of the volume ranking, with polyethylene climbing the fastest.
End Use Industry:
Capital intensity and qualification timelines separate end-use verticals, with automotive and medical applications demanding ISO-certified production lines while packaging tolerates faster supplier onboarding.
- Construction:Rigid polyurethane panels and polystyrene boards insulate commercial and residential building envelopes. India's BIS energy-efficiency codes and state-level green building mandates are accelerating rigid foam specification in Mumbai, Delhi, and Bangalore commercial real estate, creating first-mover advantages for suppliers with local production.
- Packaging:Expanded polyethylene and polyurethane systems protect electronics, appliances, and pharmaceutical shipments. E-commerce fulfillment networks in the United States and Germany prioritize recyclable foam formats to meet extended producer responsibility frameworks, compressing demand for single-use polyurethane cushioning.
- Automotive OEMs:Seating, headliners, bumper cores, and interior trim specify energy-absorbing molded foam structures.
- Furniture Manufacturing:Flexible polyurethane and latex foams dominate mattress and upholstery applications.
- Electronics:Precision-molded cushioning protects semiconductors, displays, and battery assemblies during transport.
Construction commands the largest revenue pool, with automotive OEMs gaining share fastest on lightweighting mandates.
Application:
Performance specifications determine chemistry selection, with thermal conductivity targets favoring rigid polyurethane while dynamic compression set requirements drive flexible foam formulations.
- Insulation:Rigid polyurethane and polystyrene foams achieve lambda values below 0.025 W/mK for building envelopes and refrigerated logistics. Cold-chain infrastructure buildout in India and Southeast Asia is sourcing rigid molded panels for warehouse construction and transport container lining, with suppliers qualifying formulations under BIS and local fire safety codes.
- Cushioning:Flexible polyurethane and polyethylene structures absorb impact energy in seating, packaging, and patient positioning. Medical device manufacturers in the United States and Germany are qualifying surgical support foams under ISO 13485, where certification barriers limit incumbent competition and sustain premium pricing.
- Vibration Dampening:Elastomeric polyurethane isolates mechanical equipment and vehicle powertrains.
- Sealing:Closed-cell polyethylene and PVC foams provide environmental gasketing for automotive and industrial applications.
- Soundproofing:Open-cell polyurethane acoustic foams reduce NVH in vehicle cabins and building interiors.
Insulation leads by installed volume, with cushioning expanding most quickly on medical and protective packaging demand.
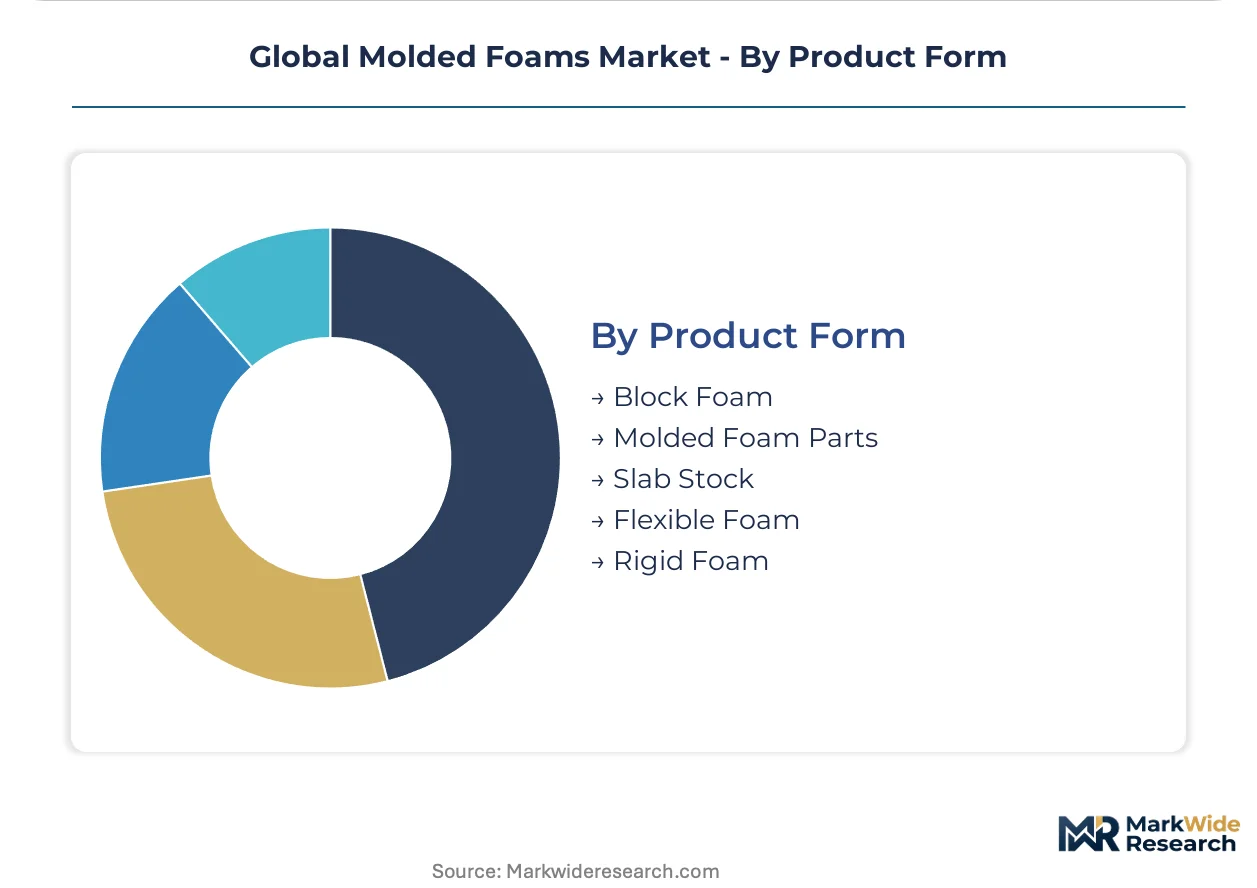
Product Form:
Processing technology and capital equipment requirements fragment supplier capabilities, with reactive injection molding demanding higher tooling investment than slab stock cutting operations.
- Molded Foam Parts:Reaction injection molding and compression molding produce complex geometries with integral skin surfaces for automotive and furniture applications. Tier 1 seating suppliers in the Czech Republic and Germany are qualifying water-blown polyurethane formulations for premium vehicle programs, achieving thinner cross-sections without sacrificing durability metrics.
- Block Foam:Continuous slab production enables downstream fabrication into cushions, packaging inserts, and insulation boards. Furniture manufacturers in the United States and Poland source cut-to-size polyurethane blocks from distributors, with density and indentation force deflection specifications driving vendor selection.
- Slab Stock:Bun stock for conversion into sheets and custom shapes serves fragmented fabrication channels.
- Flexible Foam:Low-density open-cell structures dominate seating and bedding comfort layers.
- Rigid Foam:High-density closed-cell boards serve structural insulation and composite core applications.
Molded foam parts generate the highest value per kilogram, with block foam scaling fastest on furniture and bedding volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial polyurethane chemistry in the 1930s, establishing the technical foundation that now supports automotive seating clusters across Europe. That heritage continues to shape where formulation expertise concentrates and which regulatory frameworks dominate supplier qualification.
Germany
Automotive OEM procurement mandates for mass-balance certified foams are concentrating supplier investment in Bavaria and Baden-Württemberg. The EU F-Gas Regulation and REACH diisocyanate authorization are forcing simultaneous retooling of molding lines and medical surveillance protocols. Stuttgart and Wolfsburg seating clusters now require ISCC PLUS documentation as a contract condition from BASF and Covestro supply chains.
United States
NHTSA fuel-efficiency standards and EPA 40 CFR Part 63 VOC limits are expanding demand for low-emission polyurethane in bumper cores and headliners. The EPA SNAP program is accelerating HFC blowing agent phaseouts, requiring capital investment that favors larger molders. Michigan and Ohio automotive corridors are consolidating supplier panels around Tier 1 seating manufacturers with integrated polyol sourcing.
China
MEE GB standards on formaldehyde release from interior materials are diverging from Western compliance pathways and fragmenting R&D allocation for multinational suppliers. Dual carbon goals under the national climate strategy are pressing domestic producers toward water-blown systems. Yangtze River Delta foam clusters in Jiangsu and Zhejiang are scaling rigid panel production for cold-chain logistics infrastructure.
India
BIS energy-efficiency codes and state-level green building mandates in Maharashtra and Karnataka are creating first-mover advantages for rigid polyurethane insulation suppliers. Construction volume in Mumbai, Delhi, and Bangalore commercial real estate is outpacing domestic molding capacity. Cold-chain warehouse buildout is sourcing imported panel technology while local production scales.
Japan
METI industrial standards and automotive lightweighting targets are sustaining premium demand for thin-cross-section seating foams. JIS certification requirements limit supplier turnover in electronics packaging applications. Kanto and Kansai manufacturing belts maintain specialized molding capabilities for precision medical and semiconductor cushioning where ISO 13485 barriers protect incumbent positions.
Global Molded Foams Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and formulation chemistry integration, with mass-balance documentation and low-VOC catalyst systems separating contract tiers. The supplier base concentrates around integrated polyol producers and specialized molders with automotive OEM qualification. Three archetypes dominate: diversified chemical conglomerates with captive feedstock supply, mid-cap foam specialists with regional molding networks, and packaging-focused recyclables players. Capacity consolidation and backward integration into polyol production are the prevailing competitive vectors as blowing agent transitions raise capital barriers.
Within the integrated chemical tier, BASF SE and Covestro AG exemplify archetypes combining polyol production with mass-balance certification infrastructure. Huntsman Corporation occupies a position bridging specialty catalyst systems and automotive seating supply chains. These German- and US-anchored entities represent the qualification-heavy segment where REACH and EPA compliance documentation has become a competitive moat against smaller regional molders.
| Leading Market Players |
|---|
| BASF SE |
| Sealed Air Corporation |
| Huntsman Corporation |
| Dow Inc. |
| Covestro AG |
| Recticel NV/SA |
| JSP Corporation |
| Armacell International |
| Zotefoams plc |
| Others |
Supply & Pricing Matrix
Crude oil and natural gas price indices cascade directly through MDI, TDI, and polyol cost structures, fragmenting molded foam suppliers into three distinct pricing tiers based on feedstock hedging capabilities and automotive OEM contract exposure. Buyers with ISCC PLUS mass-balance requirements absorb premium positioning, while furniture and packaging segments face compressed pass-through elasticity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with mass-balance certification and REACH compliance documentation commanding tier-one positioning. Price differentiation hinges on ISCC PLUS traceability and low-VOC catalyst integration. Cost compression in standard-tier furniture foams is intensifying because polyethylene substitution erodes polyurethane volumes. Packaging buyers exhibit highest price sensitivity, whereas automotive seating procurement tolerates premium positioning for certified sustainable content.
Supply Chain Analysis
MDI and TDI supply rests on German, Chinese, and American petrochemical complexes, with polyol production concentrated in integrated chemical parks across Belgium and the Netherlands. Feedstock dependencies span crude oil derivatives, bio-based castor and soybean oil streams, and next-generation blowing agent chemistries. Single-source vulnerability in specialty catalyst systems threatens smaller European molders during REACH diisocyanate transition periods. Distribution runs through Tier 1 automotive seating manufacturers and regional foam fabricators serving construction and furniture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded foam margins expand through bio-based polyol integration and mass-balance certification premiums that automotive OEMs now mandate. Water-blown formulation expertise compresses material usage per seat position while satisfying EU Green Deal procurement criteria.
For Market Incumbents: Anchor competitive position through backward integration into polyol production and captive supply of ISCC PLUS certified feedstocks. Consolidate smaller molders in Poland and Romania who lack medical surveillance infrastructure for REACH diisocyanate compliance. Deepen automotive seating relationships before chemical recycling infrastructure matures and fragments scrap-to-polyol value chains. For New Entrants and Emerging Players: BIS energy-efficiency codes in India open a window for rigid polyurethane panel suppliers with local production partnerships. Target Maharashtra and Karnataka commercial construction where cold-chain warehouse buildout outpaces domestic molding capacity. Pursue medical device cushioning applications where ISO 13485 certification barriers protect premium pricing and limit incumbent competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap foam specialists possessing automotive OEM qualification and regional molding networks. Long-term viability centers on water-blown formulation capabilities and pyrolysis partnership access for closed-loop polyol recovery. Watch for EPA SNAP program acceleration signals that would force HFC blowing agent retooling and trigger consolidation among undercapitalized molders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive supply of bio-based feedstocks secures mass-balance certification for BMW and Mercedes-Benz contracts. |
| Water-Blown Formulation Scale-Up | Thinner automotive seating cross-sections reduce material intensity without sacrificing durability metrics under NHTSA standards. |
| Chemical Recycling Partnership | Pyrolysis and glycolysis integration enables closed-loop polyol recovery aligned with ECHA circular-economy guidance. |
| ISO 13485 Certification Investment | Medical device cushioning qualification opens surgical support foam applications with limited incumbent competition. |
| India Local Production Expansion | BIS code compliance and state green building mandates create first-mover positioning in Mumbai and Bangalore commercial real estate. |
Research Methodology
Bottom-up automotive and construction demand modeling reconciled against top-down polyol production and trade flow tracking forms the analytical core of this study. Primary interviews with Tier 1 seating procurement directors, plant managers at European molding facilities, distribution channel partners, and technical R&D directors at integrated chemical producers combined with secondary validation from customs data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Cross-referencing bottom-up volume builds against top-down feedstock consumption patterns ensures consistency across chemistry platforms and regional clusters.
Historical trendline analysis of polyurethane and polyethylene foam shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated foam type chemistry, end-use industry vertical, application performance requirements, and regional regulatory framework clusters. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity expansion schedules, with particular weighting applied to EU Green Deal procurement mandate timelines and EPA SNAP program phaseout schedules as demand-shaping inputs.
Revisions become necessary when REACH authorization timelines for diisocyanates accelerate, EPA SNAP enforcement intensifies HFC blowing agent phaseouts, or crude oil price volatility exceeds historical bands. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and automotive OEM sustainable sourcing adoption curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
OEM Insulation Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Active Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Global Fire Protection Materials Market