
 Microporous Insulation Material Market | 2026-2036
Microporous Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Microporous Insulation Material Market Foresight
Aftermarket service revenue for furnace relining and insulation retrofit is narrowing as original equipment manufacturers bundle longer-life microporous systems into initial sales. Promat International NV leverages its European manufacturing footprint to sustain technical service relationships with steel mills. Morgan Advanced Materials anchors its position through specialized high-temperature board formulations for aerospace heat shields. Johns Manville competes on scale, operating broad sheet and blanket production lines that feed North American industrial contractors.
Microporous insulation consists of inorganic oxides, primarily fumed silica, compacted with opacifiers to achieve thermal conductivity below 0.025 W/m·K at elevated temperatures, functioning as a barrier against conductive, convective, and radiative heat transfer in systems exceeding 800°C. Sheet and board formats dominate current volume due to mature installation protocols in industrial furnaces and kilns, while blanket segments gain traction in aerospace turbine applications where conformability to complex geometries commands premium positioning. Silica-based materials lead the material category on proven longevity above 1000°C, though calcium silicate variants penetrate marine and construction end uses where moderate temperatures and moisture resistance matter.
EPA emissions standards for industrial boilers and the EU Green Deal carbon border adjustments tighten thermal efficiency requirements, directly expanding specification of high-performance microporous insulation in retrofits and new builds. China's MEE enforces stricter energy intensity targets for steel and cement producers, compelling furnace upgrades that displace legacy refractory with lower-thickness microporous alternatives. Stakeholders must monitor how evolving carbon accounting rules in Europe and North America reshape total-cost-of-ownership calculations for insulation procurement decisions.
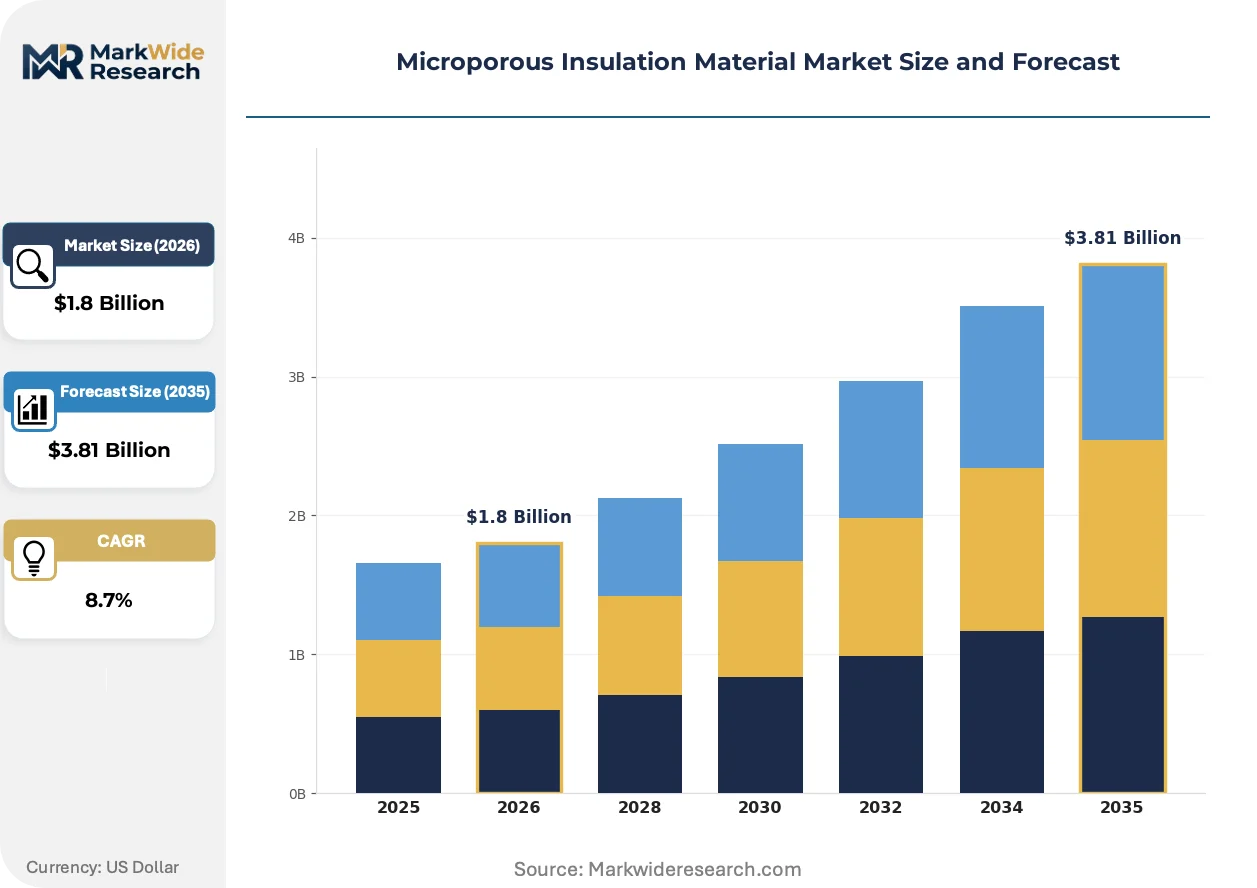
Market Dynamics
The EU F-Gas Regulation and industrial decarbonization mandates are compressing specification cycles for legacy refractory materials, forcing steelmakers and petrochemical operators to justify total-cost-of-ownership calculations that favor thinner, higher-performance microporous systems despite upfront premiums.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases eliminates competitive insulation alternatives in German and French steel clusters, redirecting furnace retrofit specifications toward silica-based microporous boards.
- China MEE energy intensity enforcement:Mandatory furnace efficiency upgrades for steel and cement producers displace conventional refractory thickness requirements with lower-profile microporous alternatives that reduce thermal mass.
- Aerospace turbine blade manufacturing:Heat treatment processes exceeding 1100°C drive blanket format adoption for conformability to complex aerodynamic geometries, commanding sustained premium positioning.
Market Restraints
- Fumed silica feedstock concentration:Supply of primary microporous raw material concentrates among specialty chemical producers in Germany and Japan, exposing formulators to input cost volatility and allocation risk.
- Calcium silicate substitution in marine applications:Moderate-temperature specifications below 800°C favor moisture-resistant calcium silicate variants that undercut silica-based pricing in shipbuilding and offshore construction.
- Installation protocol lock-in:Mature furnace construction practices in established steel regions create technical friction against thinner-profile microporous retrofits that require modified anchoring and expansion joint designs.
Strategic Opportunities
- India steel capacity expansion:Greenfield electric arc furnace installations in Odisha and Jharkhand lack legacy refractory infrastructure, enabling direct specification of microporous systems without retrofit conversion costs.
- EU Green Deal carbon border adjustments:Embedded carbon accounting in imported steel and aluminum tightens thermal efficiency requirements for European smelters, expanding addressable market for high-performance insulation procurement.
- Digital twin integration:Convergence of thermal modeling software with IoT furnace monitoring enables predictive insulation lifecycle management, creating service attach opportunities for microporous system suppliers.
Industry Challenges
- High-temperature installation certification:Qualified technicians capable of microporous board placement in active furnace environments remain scarce in expanding steel regions, extending project timelines.
- Legacy refractory removal costs:Retrofit projects require complete furnace decommissioning and refractory demolition before microporous installation, inflating total project capex and complicating ROI justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microporous Insulation Material Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Board, Blanket, Pipe Application: Industrial, Marine, Aerospace, Automotive Material: Silica, Calcium Silicate, Fiber, Polymer End User: Construction, HVAC, Oil & Gas, Power Generation |
| Companies Covered | Alkegen, TECHNO-PHYSIK Engineering GmbH, Etex Group, Unicorn Insulations Ltd, Elmelin Ltd, Johns Manville, NICHIAS Corporation, Promat International NV, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microporous Insulation Material Market Shifts & Advancements
Material science advances and regulatory carbon accounting are converging to compress specification thresholds, with thermal performance data now transmitted digitally to procurement platforms before physical samples reach engineering review.
Opacifier-enhanced fumed silica formulations achieve thermal conductivity below 0.020 W/m·K across 600-1000°C operating bands, enabling thinner insulation profiles that reduce furnace shell mass and accelerate heat-up cycles. Aerospace heat shield manufacturers in California and Toulouse adopt these grades for reusable thermal protection systems. This technology is virtualizing the traditional trade-off between insulation thickness and thermal efficiency, collapsing engineering review cycles from months to weeks.
REACH authorization requirements for synthetic amorphous silica classifications are tightening occupational exposure documentation obligations for European formulators, accelerating investment in closed-loop manufacturing and automated packaging systems. German steel clusters now require extended safety data sheets for all high-temperature insulation materials. Silica-based microporous producers with pre-validated exposure bands capture specification share from competitors facing regulatory lag.
Steelmakers in China and India now bundle insulation procurement into multi-year furnace maintenance contracts, consolidating vendor relationships and compressing spot-market transactions. Original equipment manufacturers respond by embedding longer-life microporous systems into initial equipment sales, narrowing the aftermarket relining segment. This consolidation is most visible in East Asian petrochemical corridors where integrated operators favor single-source accountability over component-level sourcing.
Microporous Insulation Material Market Segmentation
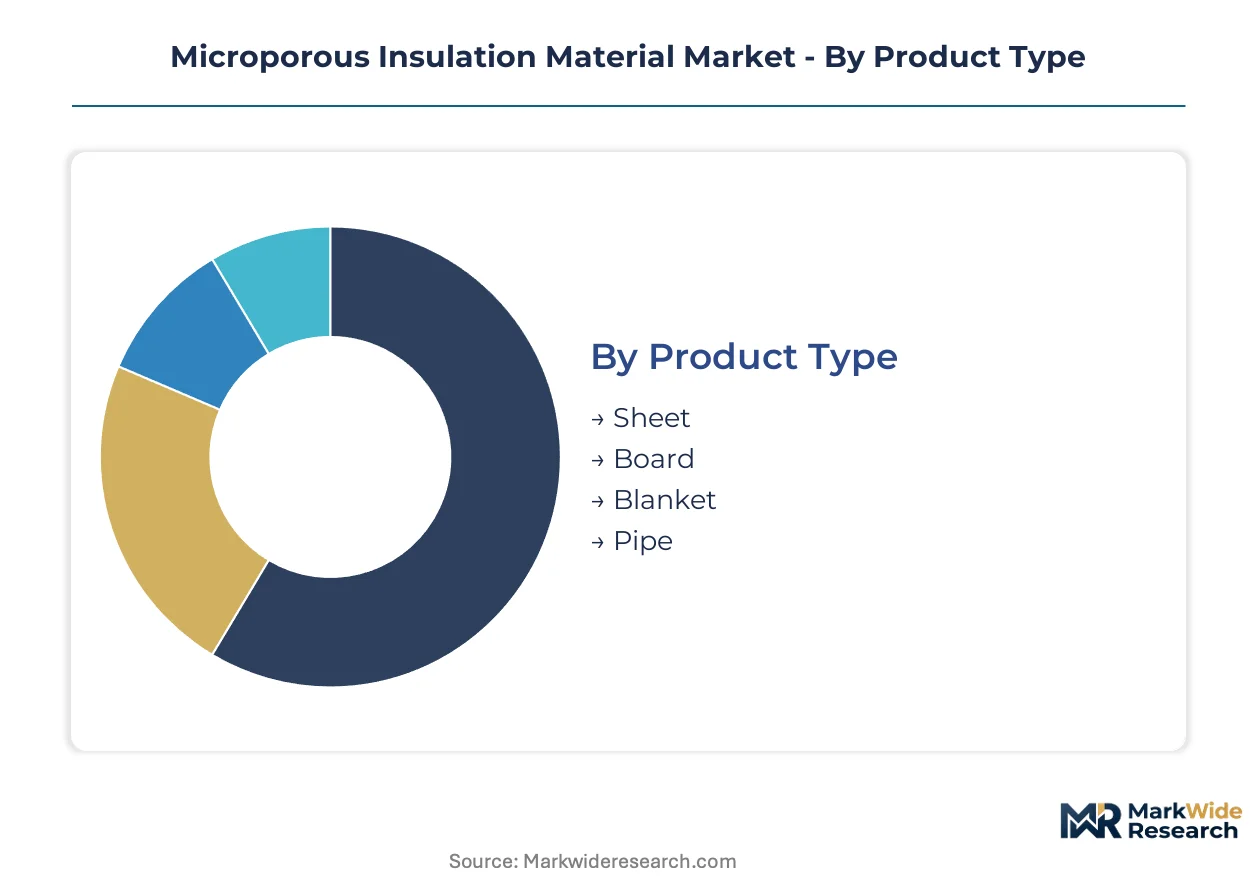
Microporous insulation procurement decisions hinge on thermal performance thresholds, installation geometry constraints, and lifecycle cost modeling across divergent end-use environments. Segment boundaries blur when steelmakers bundle insulation into furnace maintenance contracts or aerospace OEMs specify conformable formats for complex heat shield geometries.
Product Type:
Aftermarket service intensity varies sharply by format, with board and sheet installations demanding specialized technician certification while blanket formats require less intrusive replacement protocols in active furnace environments.
- Sheet:Thin-profile silica sheets achieve thermal conductivity below 0.025 W/m·K in 600-1000°C bands, enabling furnace shell mass reduction. German steel clusters specify these for electric arc furnace retrofits where rapid heat-up cycles compress maintenance windows.
- Board:Rigid board formats dominate industrial furnace linings in China and India due to mature anchoring protocols and established expansion joint engineering. China's MEE energy intensity enforcement accelerates displacement of conventional refractory thickness with lower-profile microporous alternatives.
- Blanket:Conformable blanket segments penetrate aerospace turbine applications in California and Toulouse where complex aerodynamic geometries command premium positioning.
- Pipe:Pre-formed pipe insulation serves petrochemical corridors in East Asia with standardized diameter coverage and reduced field fabrication requirements.
Board holds the largest share; momentum sits with blanket formats in aerospace heat treatment applications.
Application:
Cost tier stratification separates premium aerospace specifications from commodity marine procurement, with industrial applications occupying the volume-heavy middle ground where total-cost-of-ownership calculations dominate vendor selection.
- Industrial:Furnace and kiln applications in steel, cement, and glass production constitute the volume anchor. EU F-Gas Regulation phase-down eliminates competitive fluorinated alternatives in German and French steel clusters, redirecting specifications toward silica-based microporous systems.
- Marine:Shipbuilding and offshore construction favor moisture-resistant calcium silicate variants below 800°C, undercutting silica-based pricing in moderate-temperature specifications where salt exposure and humidity resistance matter.
- Aerospace:Heat shield manufacturing for reusable thermal protection systems in California and Toulouse drives blanket adoption for conformability to complex geometries above 1100°C.
- Automotive:Exhaust system and battery thermal management applications emerge as specification targets for thin-profile microporous sheets in electric vehicle production.
Industrial commands absolute volume; aerospace delivers the steepest expansion trajectory on premium heat treatment demand.
Material:
Supply concentration in fumed silica feedstock creates margin pressure for formulators while calcium silicate alternatives exploit regional availability of mineral inputs.
- Silica:Fumed silica compacted with opacifiers achieves thermal conductivity below 0.020 W/m·K across critical operating bands. Supply concentrates among specialty chemical producers in Germany and Japan, exposing formulators to input cost volatility.
- Calcium Silicate:Moderate-temperature performance below 800°C with inherent moisture resistance penetrates marine and construction end uses where silica-based pricing faces substitution pressure.
- Fiber:Alumina-silica fiber blends serve intermediate temperature applications with enhanced mechanical durability for vibration-prone industrial environments.
- Polymer:Emerging polymer-based microporous formulations target sub-600°C automotive and HVAC applications where flexibility and lower weight justify performance trade-offs.
Silica dominates revenue; calcium silicate gains share fastest in moisture-exposed marine specifications.
End User:
Customer type segmentation reveals divergent procurement behaviors, with integrated steel operators bundling multi-year contracts and construction contractors spot-purchasing for discrete project timelines.
- Construction:Building envelope and fire protection applications favor calcium silicate boards for moderate-temperature specifications where code compliance and moisture resistance outweigh extreme thermal performance.
- HVAC:Commercial and industrial climate systems specify microporous insulation for ductwork and equipment enclosures where space constraints favor thin-profile solutions.
- Oil & Gas:Refinery furnace and pipeline applications in East Asian petrochemical corridors drive board and sheet procurement through integrated maintenance contracts.
- Power Generation:Gas turbine and boiler applications face tightening EPA emissions standards and EU Green Deal carbon border adjustments that expand specification of high-performance microporous systems in retrofits and new builds.
Oil & Gas anchors current volume; power generation climbs the fastest on decarbonization-driven thermal efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical producers in Germany and Japan concentrate fumed silica feedstock supply, exposing formulators elsewhere to input cost volatility and allocation risk. China and India dominate steel furnace retrofit demand, while European decarbonization mandates accelerate specification shifts in German and French industrial clusters.
China
Steelmakers in Hebei and Jiangsu provinces execute high-temperature furnace retrofits with microporous boards to meet MEE energy intensity enforcement. The Ministry of Ecology and Environment mandates efficiency upgrades that displace conventional refractory thickness. Tangshan steel clusters drive volume procurement through integrated maintenance contracts.
Germany
Electric arc furnace operators in the Ruhr region specify thin-profile silica sheets for rapid heat-up cycles under EU F-Gas Regulation phase-down. ECHA REACH authorization requirements tighten occupational exposure documentation for synthetic amorphous silica. Duisburg steel mills redirect specifications toward silica-based microporous systems as fluorinated alternatives face elimination.
India
Greenfield electric arc furnace installations in Odisha and Jharkhand enable direct microporous specification without legacy refractory conversion costs. The Bureau of Indian Standards develops high-temperature insulation certification protocols for industrial furnace applications. Rourkela and Jamshedpur steel corridors bundle multi-year insulation procurement into furnace maintenance contracts.
United States
EPA emissions standards for industrial boilers tighten thermal efficiency requirements across steel and petrochemical facilities. Aerospace heat shield manufacturers in California adopt blanket formats for conformability to complex geometries above 1100°C. Houston petrochemical corridors drive board and sheet procurement through integrated operator contracts.
France
Aerospace OEMs in Toulouse command premium positioning for blanket segments in reusable thermal protection systems. EU Green Deal carbon border adjustments tighten embedded carbon accounting for imported steel and aluminum. Dunkirk steel clusters face thermal efficiency mandates that expand high-performance insulation procurement.
Microporous Insulation Material Market Competitive Landscape
Specialty chemical conglomerates and dedicated insulation fabricators split the market along feedstock control versus application engineering vectors. Three archetypes dominate: fumed silica producers with captive microporous formulation capabilities, refractory specialists pivoting from legacy brick-and-castable portfolios, and aerospace-focused conformable insulation engineers. Consolidation pressure intensifies as steelmakers bundle procurement into multi-year contracts, favoring suppliers with integrated technical service networks. Capacity expansion and backward integration into opacifier supply represent the dominant competitive moves.
Among European manufacturing footprint holders, Promat International NV anchors the technical service archetype for steel mill relationships, while Morgan Advanced Materials exemplifies specialized high-temperature formulation positioning. Johns Manville occupies the scale-driven end with broad sheet and blanket production lines feeding North American industrial contractors. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Alkegen |
| TECHNO-PHYSIK Engineering GmbH |
| Etex Group |
| Unicorn Insulations Ltd |
| Elmelin Ltd |
| Johns Manville |
| NICHIAS Corporation |
| Promat International NV |
| Morgan Advanced Materials |
| Others |
Supply & Pricing Matrix
Tangshan steel clusters in Hebei province concentrate microporous board consumption, with integrated procurement contracts compressing spot-market transactions and shifting pricing power toward original equipment manufacturers bundling long-life systems into initial furnace sales. Fumed silica feedstock volatility in German and Japanese specialty chemical hubs transmits downstream through formulation costs, forcing insulation fabricators to absorb margin compression or renegotiate multi-year supply agreements.
Pricing Analysis
Aftermarket service revenue for furnace relining and retrofit maintenance drives lifetime value capture, though bundling trends narrow this tier as OEMs embed extended-life microporous systems into equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates aerospace blanket specifications from commodity calcium silicate marine grades. Pricing pressure stems from legacy refractory removal costs inflating total project capex and complicating ROI justification for retrofit conversions. Industrial steel operators exhibit highest price sensitivity due to total-cost-of-ownership scrutiny, while aerospace OEMs accept premium positioning for conformable high-temperature performance.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become critical for insulation fabricators managing fumed silica inventory cycles against volatile input costs. Feedstock supply concentrates in Germany, Japan, and select Chinese specialty chemical producers, exposing formulators to allocation risk during capacity constraints. Raw material dependencies center on fumed silica, opacifier compounds, and calcium silicate mineral inputs. Single-source vulnerability in aerospace-grade opacifier supply creates chokepoint exposure for premium formulation lines. Distribution runs through integrated steel mill procurement desks, petrochemical operator maintenance contracts, and industrial contractor spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microporous insulation functions as a substitution defense market where calcium silicate variants and legacy refractory systems threaten incumbent silica-based positioning. Incumbents must navigate moisture-resistant alternatives undercutting pricing in moderate-temperature marine and construction specifications.
For Market Incumbents: Entrench technical service relationships with steel mill procurement desks through predictive lifecycle management and digital twin integration. Backward integration into opacifier supply secures margin control against specialty chemical feedstock volatility. Certification pre-validation under ECHA REACH authorization requirements captures specification share from competitors facing regulatory documentation lag.
For New Entrants and Emerging Players: Greenfield electric arc furnace corridors in Odisha and Jharkhand present white-space entry points lacking legacy refractory infrastructure and retrofit conversion barriers. Automotive battery thermal management applications for electric vehicle production offer penetrable thin-profile sheet demand with less entrenched incumbent relationships. Go-to-market positioning should emphasize direct OEM furnace specification bypassing established contractor networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from refractory conglomerates pivoting from legacy brick-and-castable portfolios toward high-performance microporous formulation capabilities. Long-term viability hinges on carbon border adjustment enforcement tightening thermal efficiency procurement mandates across European steel and aluminum smelters. Watch for EU Green Deal implementation intensity as inflection signal for premium insulation specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Opacifier Supply | Captive sourcing from German and Japanese specialty chemical producers reduces feedstock allocation risk exposure. |
| Digital Twin Integration | IoT furnace monitoring convergence with thermal modeling software creates predictive maintenance service attach opportunities. |
| REACH Authorization Pre-Validation | Pre-validated synthetic amorphous silica exposure bands accelerate European specification capture under tightening ECHA documentation. |
| Greenfield Direct Specification | Odisha and Jharkhand electric arc furnace installations enable microporous adoption without legacy refractory conversion costs. |
| Aerospace Blanket Format Expansion | Conformable insulation engineering for Toulouse and California heat shield manufacturers commands sustained premium positioning above 1100°C. |
Research Methodology
Desk research of customs and trade flow databases, ECHA regulatory filings, and steel industry association technical reports preceded structured interviews with furnace maintenance directors, petrochemical procurement leads, insulation fabricator plant managers, and aerospace heat treatment engineers. Primary fieldwork with downstream OEM specification teams and channel distribution partners combined with secondary validation against MEE enforcement documentation and EU F-Gas Regulation implementation tracking. Bottom-up volume modeling triangulated against top-down market sizing across product format, application, and material grade segments.
Assumption sets held regulatory enforcement timelines and carbon accounting rule evolution within documented implementation patterns while varying steel capacity expansion trajectories and aerospace production rates across sensitivity scenarios. Segmentation dimensions modeled include product format tier, end-use industry vertical, thermal performance grade, and regional production cluster. CAGRs derived from installed base turnover analysis and specification substitution elasticity. Forecast inputs incorporated fumed silica price indices, furnace retrofit cycle timing, and EU Green Deal border adjustment intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by Chinese state-affiliated refractory conglomerates would shift competitive dynamics and pricing trajectories. Macroeconomic deviation in steel production volumes, regulatory acceleration in carbon accounting enforcement, or breakthrough advances in polymer-based sub-600°C alternatives would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Technical Foam Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
High-Performance Insulation Materials Market