
 Europe Phase Change Material Market | 2026-2036
Europe Phase Change Material Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Phase Change Material Market Insights
Cold-chain logistics is restructuring demand profiles across European phase change material applications. Pharmaceutical distributors and fresh-food retailers in Germany and the Netherlands now specify bio-based PCM formulations for temperature-controlled transport. Croda International Plc anchors its position through lipid-derived organic PCMs with tailored melting points for pharmaceutical cold chains. Rubitherm Technologies GmbH dominates salt-hydrate inorganic systems for building thermal mass applications. Axiotherm GmbH specializes in macroencapsulated panels that integrate directly into concrete core activation systems.
Phase change materials are substances that absorb or release latent heat at nearly constant temperature during solid-liquid transitions, typically formulated with paraffin waxes, fatty acids, or salt hydrates engineered to specific enthalpy values between 100 and 250 kJ/kg. These materials function as passive thermal buffers that stabilize temperature excursions without active energy input, serving industrial applications from building envelope regulation to sensitive electronics protection. Organic PCMs lead volume consumption due to chemical stability and tunable phase-transition windows, though microencapsulated formats command premium positioning where leakage prevention and surface compatibility determine specification. Inorganic salt-hydrate systems compete on cost in bulk thermal energy storage for district heating networks, while macroencapsulated panels capture margin pools in new construction where architect-specified integration drives value. Powder and granule forms serve retrofit markets with lower installation barriers than rigid panel alternatives.
The EU Green Deal and F-Gas Regulation are mandating lower-GWP alternatives for building climate control, directly expanding addressable demand for passive PCM thermal management. ECHA REACH compliance requirements govern chemical composition disclosures and restrict certain hydrate formulations, filtering supplier eligibility across member states. National building codes in Germany, France, and Sweden now reference dynamic thermal performance metrics that favor materials with demonstrated latent heat capacity. Stakeholders must monitor evolving CE marking protocols for construction products incorporating PCM layers, as harmonized standards under the Construction Products Regulation will determine cross-border market access for integrated building systems.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing thermal performance requirements for building envelopes, forcing passive PCM solutions into specification pipelines that previously defaulted to active HVAC systems. This regulatory compression is restructuring competitive positioning around enthalpy density and encapsulation reliability rather than first-cost metrics.
Growth Catalysts
- EU Green Deal building mandates:Dynamic thermal performance requirements in Germany, France, and Sweden now reference latent heat capacity, pulling PCM panels into retrofit specifications and new construction.
- Cold-chain logistics expansion:Pharmaceutical distributors and fresh-food retailers across the Netherlands and Germany specify bio-based PCM formulations for temperature-controlled transport, expanding addressable volume beyond building applications.
- Salt-hydrate cost positioning:Inorganic systems compete favorably against battery thermal storage in district heating networks, capturing bulk thermal energy storage contracts where capital efficiency determines award.
Market Restraints
- Input cost volatility:Refined paraffin wax and specialty fatty acid feedstocks track crude oil and palm oil indices, compressing margin stability for organic PCM formulators.
- ECHA REACH compliance friction:Chemical composition disclosure requirements and restricted hydrate formulations filter supplier eligibility, raising qualification costs for cross-border market access.
- Mechanical ventilation substitution:Heat recovery ventilation systems with lower upfront capital compete for the same building envelope thermal management budgets, particularly in Nordic residential retrofits.
Strategic Opportunities
- Underpenetrated Southern European markets:Spain and Italy building codes lag Northern counterparts in dynamic thermal metrics, creating first-mover windows as EU harmonization pressures national adoption.
- Concrete core activation convergence:Macroencapsulated PCM panels integrating directly into structural thermal mass systems enable architect-specified value capture in premium commercial construction.
- CE marking protocol evolution:Harmonized standards under the Construction Products Regulation will determine cross-border market access, rewarding early compliance investment with preferential positioning.
Industry Challenges
- Microencapsulation technical talent scarcity:Formulation chemists with dual competence in polymer shell engineering and phase-transition thermodynamics command premium compensation, constraining R&D scaling.
- Legacy HVAC contractor education:Installation networks trained on active mechanical systems require retraining on passive thermal buffer specification and commissioning, slowing specification velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Phase Change Material Market |
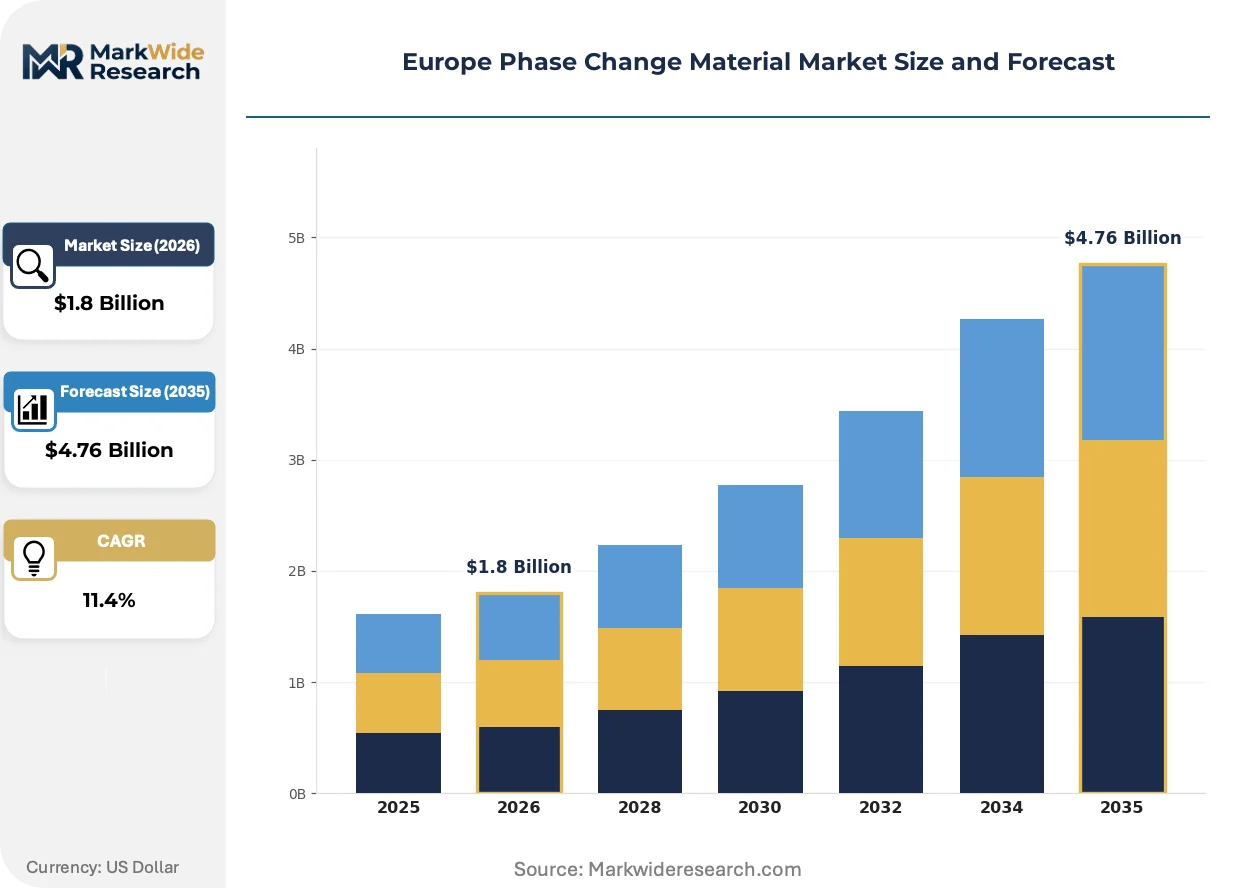
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Inorganic, Macroencapsulated, Microencapsulated End User: Building & Construction, Electronics, Automotive, Textiles Application: Heating & Cooling, Thermal Energy Storage, Temperature Control, Refrigeration Form: Panels, Coatings, Powders, Granules |
| Companies Covered | Henkel AG & Co. KGaA, Croda International Plc, BASF SE, Rubitherm Technologies GmbH, Axiotherm GmbH, Climator Sweden AB, Parker Hannifin Corp, Sasol Germany GmbH, Outlast Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Phase Change Material Market Trends and Innovations
Encapsulation technology and regulatory chemistry mandates are fragmenting the supplier base into specialists by thermal range and application. Material science advances are compressing the performance gap between organic stability and inorganic cost.
Microencapsulated paraffin systems are modularizing across building envelope applications. Shell-and-core architectures with melamine-formaldehyde or acrylic polymer barriers prevent leakage while maintaining surface compatibility with gypsum board and concrete substrates. German and French facade integrators now specify these formats for architect-driven commercial projects where aesthetic and thermal performance must coexist. The technology is modularizing specification workflows, separating thermal design from structural engineering disciplines.
REACH restrictions on certain salt-hydrate formulations are redirecting R&D investment toward bio-derived organic alternatives. ECHA compliance timelines now govern product development roadmaps, with formulators prioritizing fatty acid esters and lipid-derived PCMs that preempt regulatory friction. Pharmaceutical cold-chain specifications in the Netherlands and Germany are tightening purity thresholds, filtering suppliers unable to document batch-level chemical provenance.
Pharmaceutical distributors are consolidating supplier relationships around full-service temperature assurance rather than commodity PCM procurement. Dutch and German logistics operators now bundle PCM container leasing with real-time monitoring and reverse logistics, displacing spot-market material purchases. Fresh-food retailers in France are piloting subscription-based thermal packaging programs where packaging return and PCM regeneration are vendor responsibilities, compressing total cost of ownership calculations for buyers.
Europe Phase Change Material Market Segmentation
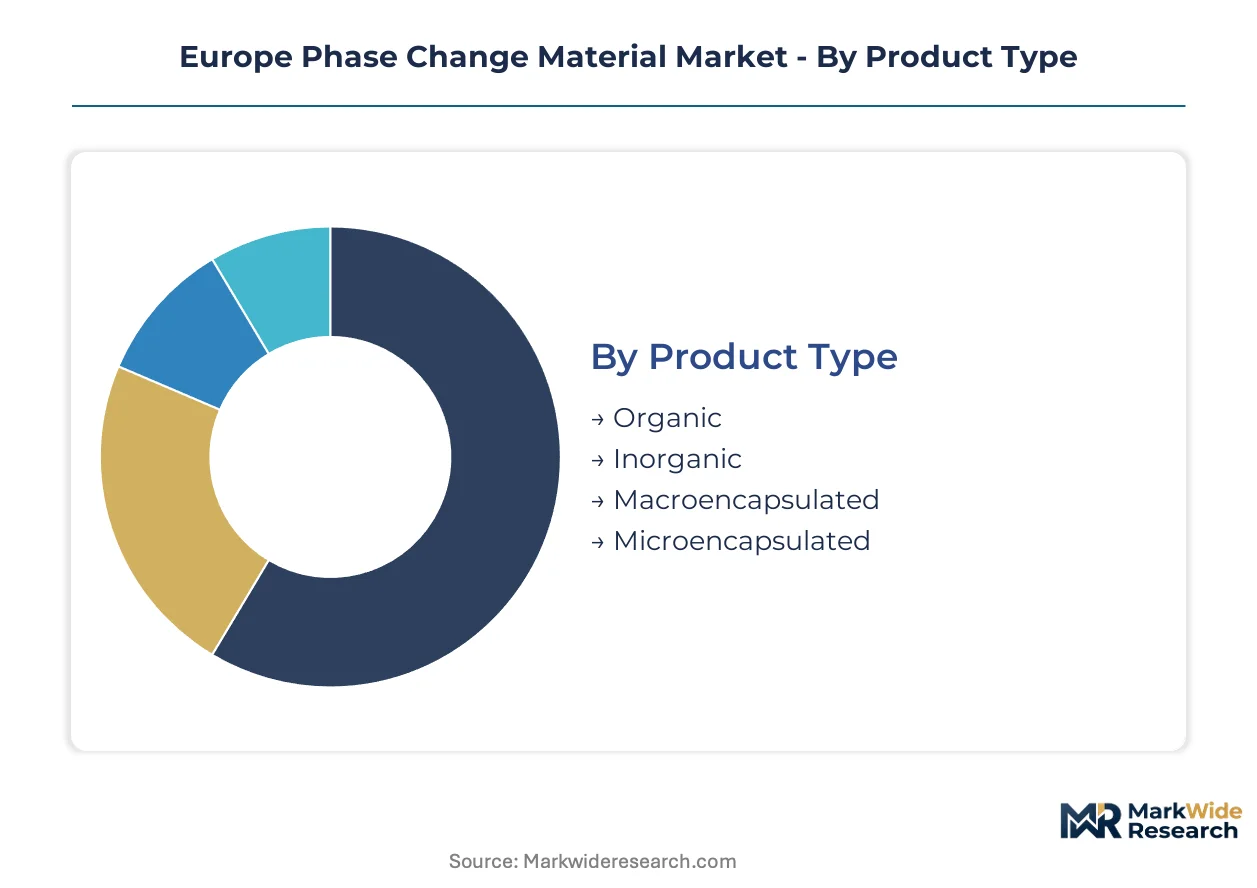
PCM specification in Europe fragments across thermal range, encapsulation format, and installation geometry. Buyers select formulations based on enthalpy density requirements, leakage risk tolerance, and integration complexity with host substrates.
Product Type:
Organic systems dominate volume consumption while inorganic alternatives compete on raw material cost. Premium positioning concentrates in microencapsulated formats where shell integrity determines specification.
- Organic:Paraffin waxes and fatty acid esters engineered to 100-250 kJ/kg enthalpy values provide chemical stability across repeated thermal cycling. German building retrofit contractors specify these for envelope integration where degradation resistance outweighs first-cost premiums.
- Inorganic:Salt-hydrate systems leverage lower feedstock costs for bulk thermal energy storage in district heating networks. Swedish and Danish utilities award these contracts where capital efficiency trumps cycle stability concerns.
- Macroencapsulated:Rigid panels integrate directly into concrete core activation systems for architect-specified commercial construction in France and Germany.
- Microencapsulated:Polymer-shell architectures prevent leakage while maintaining gypsum board compatibility, commanding premium positioning in facade-integrated applications.
Today's leader: Organic. Tomorrow's challenger: Microencapsulated.
End User:
Application pull concentrates in thermally regulated environments where passive buffering displaces active mechanical systems. Building codes and logistics specifications are restructuring demand concentration across verticals.
- Building & Construction:Dynamic thermal performance metrics in German, French, and Swedish building codes now reference latent heat capacity, pulling PCM panels into envelope specifications for both new construction and energy retrofit projects.
- Electronics:Thermal management of sensitive components leverages PCM passive buffering to stabilize temperature excursions without active cooling energy input in data center and telecommunications applications.
- Automotive:Battery thermal regulation and cabin climate buffering applications specify PCM formulations compatible with automotive temperature ranges and vibration environments.
- Textiles:Apparel and technical textile manufacturers integrate phase change fibers for personal thermal comfort in protective equipment and outdoor performance clothing.
Building & Construction anchors current volume. Cold-chain logistics requirements are accelerating Electronics and Automotive specification velocity fastest.
Application:
Functional deployment splits between stationary thermal mass and mobile temperature assurance. Regulatory mandates and logistics network expansion are redistributing growth trajectories.
- Heating & Cooling:Building envelope integration for passive thermal regulation displaces mechanical HVAC capacity in German and French commercial construction where EU Green Deal compliance tightens performance requirements.
- Thermal Energy Storage:District heating networks in Denmark and Sweden deploy bulk salt-hydrate storage to shift thermal load and integrate renewable heat sources.
- Temperature Control:Pharmaceutical and fresh-food cold chains across the Netherlands and Germany specify bio-based PCM formulations for transport container thermal assurance.
- Refrigeration:Commercial and industrial cooling systems integrate PCM thermal buffers to reduce compressor cycling and improve coefficient of performance.
Heating & Cooling commands installed base. Temperature Control climbs fastest on pharmaceutical logistics expansion.
Form:
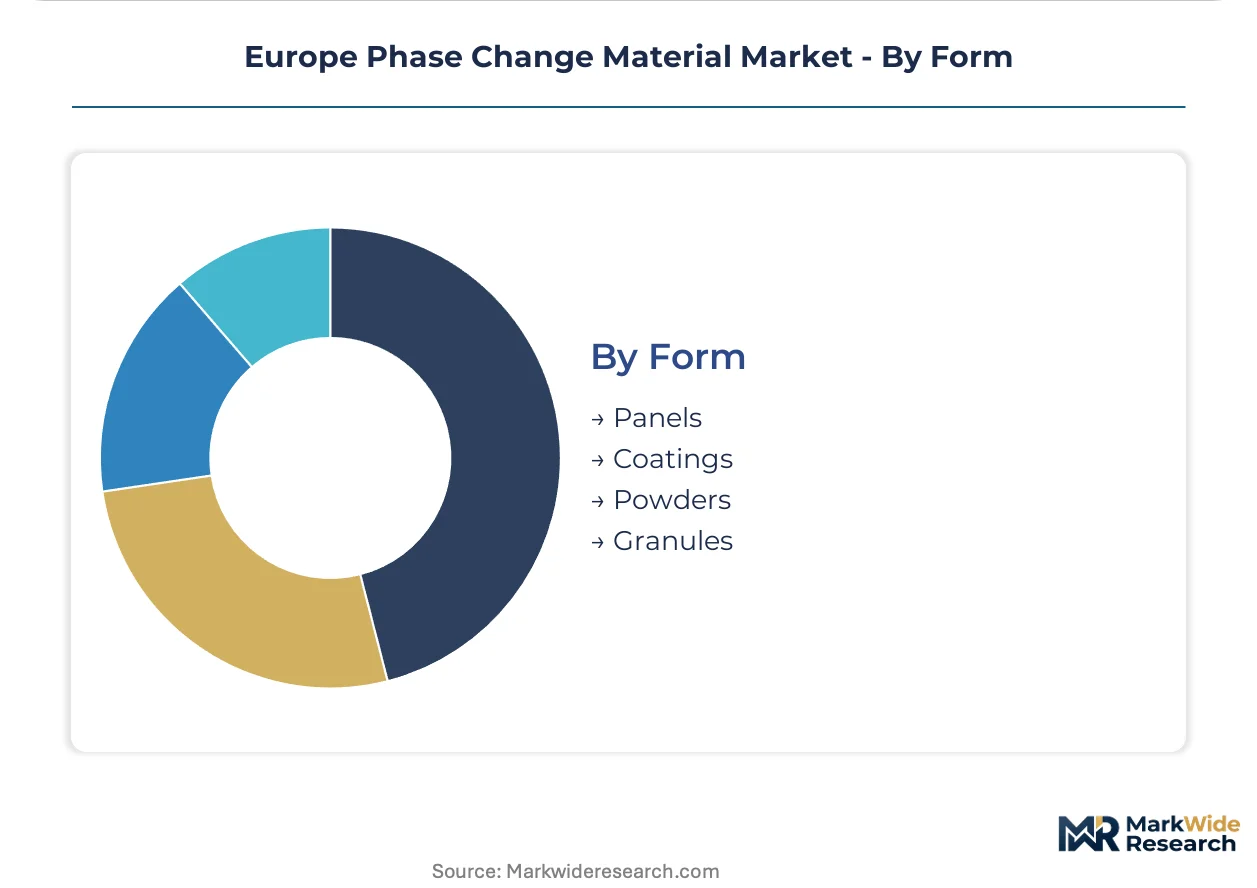
Physical configuration determines installation labor, substrate compatibility, and retrofit feasibility. Specification workflows separate thermal engineering from structural disciplines based on form factor.
- Panels:Rigid macroencapsulated formats integrate into concrete core activation and facade systems, enabling architect-specified value capture in premium commercial projects across Germany and France.
- Coatings:Surface-applied PCM layers provide thermal management for electronics enclosures and specialized building envelope applications requiring minimal thickness.
- Powders:Dispersible formats serve composite material integration and specialized industrial applications where mixing with host matrices enables custom thermal profiles.
- Granules:Free-flowing forms fill void spaces in packaging and container applications, dominating pharmaceutical cold-chain retrofit markets with lower installation barriers than rigid alternatives.
Panels lead specification value. Granules expand volume fastest through logistics packaging proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European phase change material demand through its concentration of building retrofit contractors and district heating operators. National building codes and EU-level environmental mandates are redistributing specification authority across member states.
Germany
Cold-chain logistics operators in the Netherlands border region specify bio-based PCM formulations for pharmaceutical transport containers. The EU Green Deal implementation through national building codes mandates dynamic thermal performance metrics for envelope retrofits. The Stuttgart-Munich corridor hosts facade integrators embedding macroencapsulated panels into concrete core activation systems for commercial construction.
France
Fresh-food retailers in the Paris basin pilot subscription-based thermal packaging programs with vendor-managed PCM regeneration. ECHA REACH compliance requirements filter supplier eligibility for salt-hydrate formulations used in building applications. The Lyon-Grenoble cluster concentrates R&D investment in fatty acid ester alternatives that preempt regulatory friction on chemical composition.
Sweden
Utility operators in Stockholm and Malmö deploy bulk salt-hydrate storage for district heating network load shifting. The F-Gas Regulation drives substitution toward passive thermal management in HVAC system specifications. The Gothenburg industrial zone houses formulators serving Nordic residential retrofit markets where heat recovery ventilation systems compete for envelope thermal budgets.
Netherlands
Pharmaceutical distributors in Rotterdam and Amsterdam consolidate supplier relationships around full-service temperature assurance leasing models. National logistics regulations align with EU cold-chain integrity standards for vaccine and biologic transport. The Eindhoven-Tilburg corridor specializes in microencapsulated formats for electronics thermal management applications.
Denmark
Renewable heat integration projects in Copenhagen specify inorganic PCM systems for bulk thermal energy storage. CE marking protocols under the Construction Products Regulation determine cross-border market access for integrated building systems. The Aarhus-Odense axis hosts district heating network operators capturing capital efficiency advantages over battery thermal storage alternatives.
Europe Phase Change Material Market Competitive Landscape
Portfolio diversification dominates the current landscape as formulators extend from commodity paraffin waxes into microencapsulated and bio-derived alternatives. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with integrated feedstock positions, specialized German thermal engineering firms with architect-specified integration capabilities, and Nordic cold-chain logistics specialists with reverse-logistics service bundling. M&A activity concentrates on encapsulation technology acquisition, while capacity expansion targets Southern European markets where building code harmonization creates first-mover windows.
Among diversified chemical conglomerates, BASF SE and Henkel AG & Co. KGaA occupy positions spanning organic PCM feedstocks through formulated building products. Specialized German engineering firms exemplified by Rubitherm Technologies GmbH and Axiotherm GmbH anchor the architect-specified commercial construction segment. Croda International Plc represents the bio-based formulation archetype serving pharmaceutical cold-chain specifications with lipid-derived alternatives. These named entities illustrate the competitive structure without exhaustively mapping market positions.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Croda International Plc |
| BASF SE |
| Rubitherm Technologies GmbH |
| Axiotherm GmbH |
| Climator Sweden AB |
| Parker Hannifin Corp |
| Sasol Germany GmbH |
| Outlast Technologies |
| Others |
Pricing and Supply Chain Analysis
Refined paraffin wax and specialty fatty acid feedstocks track crude oil and palm oil indices, transmitting upstream commodity volatility through three distinct pricing tiers downstream. Microencapsulated formats for German facade integrators command substantial premiums over bulk salt-hydrate contracts awarded by Swedish district heating utilities.
Pricing Analysis
Distributor margins compress most severely at the standard tier, where organic PCM formulators compete on enthalpy density specifications without differentiation. Price differentiation separates CE-marked macroencapsulated panels for French architect-specified commercial construction from commodity granules serving Dutch pharmaceutical logistics. Cost compression in the economy tier intensifies because ECHA REACH compliance investments filter smaller suppliers, while buyer price sensitivity concentrates among Nordic residential retrofit contractors evaluating passive PCM against heat recovery ventilation alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil derivatives that anchor bio-based organic PCM formulations for pharmaceutical cold chains. Feedstock dependencies rest on German petrochemical refineries for paraffin waxes, Swedish salt deposits for hydrate systems, and French lipid processing for fatty acid esters. Supply chain risk centers on regulatory restriction as ECHA REACH disclosure timelines govern product development roadmaps. Distribution runs through specialized thermal engineering firms in the Rhine-Ruhr corridor and Nordic logistics operators bundling PCM container leasing with reverse logistics services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in microencapsulated formats where polymer shell engineering competence commands premium positioning, while salt-hydrate cost positioning in district heating networks captures volume through capital efficiency.
For Market Incumbents: Extend encapsulation technology portfolios from commodity paraffin into bio-derived alternatives that preempt ECHA REACH friction on chemical composition. Add capacity in Southern European markets before EU building code harmonization closes first-mover windows. Deepen architect-specified relationships through concrete core activation integration capabilities that mechanical ventilation substitutes cannot replicate. For New Entrants and Emerging Players: The price-point gap between premium microencapsulated panels and economy salt-hydrate bulk contracts creates entry space for mid-tier formulators with hybrid organic-inorganic systems. Target Spanish and Italian building retrofit markets where dynamic thermal performance metrics remain underpenetrated relative to German and French codes. Pursue pharmaceutical cold-chain logistics operators in the Netherlands with subscription-based thermal packaging programs that bundle PCM regeneration services. For Investors and Strategic Acquirers: Consolidation pressure builds where microencapsulation technical talent scarcity constrains R&D scaling for mid-cap specialists. Long-term viability favors formulators with dual competence in polymer shell engineering and phase-transition thermodynamics, positioned across the analysis window for CE marking protocol evolution under the Construction Products Regulation. Watch for inflection where harmonized standards determine cross-border market access for integrated building systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive supply of refined paraffin wax insulates margin stability from crude oil index volatility. |
| Microencapsulation Capacity Expansion | Added polymer-shell production lines serve German and French facade integrator specification pipelines. |
| Bio-Derived Formulation R&D Investment | Fatty acid ester alternatives preempt ECHA REACH restrictions on legacy salt-hydrate chemistries. |
| Southern European Market Entry | Early positioning in Spain and Italy captures windows before EU building code harmonization completes. |
| Full-Service Temperature Assurance Bundling | PCM container leasing with real-time monitoring displaces spot-market commodity purchases among Dutch pharmaceutical distributors. |
Research Methodology
Direct dialogue with PCM formulator R&D directors, German facade integrator procurement leads, Swedish district heating utility planning officers, Dutch pharmaceutical logistics operators, and ECHA regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from EU Construction Products Regulation harmonization documents, ECHA REACH substance registration databases, national building code amendments in Germany and France, and trade flow data for paraffin wax and palm oil derivatives. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the European market.
Segment-level outputs for organic, inorganic, macroencapsulated, and microencapsulated product types were modeled across building and construction, cold-chain logistics, electronics, and automotive end-use verticals. Geographic splits followed national regulatory cluster adoption patterns. CAGRs were derived from elasticity-adjusted demand projections incorporating EU Green Deal implementation timelines and F-Gas Regulation substitution effects. Industry-specific inputs included enthalpy density specifications, encapsulation integrity thresholds, and CE marking compliance status.
Caveats apply where ECHA REACH substance restriction expansions, feedstock commodity price spikes, or mechanical ventilation technology cost reductions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and building code adoption velocity that may revise with political transitions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Roofing Underlying Materials Market