
 Insulation Boards Market | 2026-2036
Insulation Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Boards Market Foresight
Aftermarket building envelope retrofit services is reshaping margin distribution in the insulation value chain, pulling profitability from commodity board sales toward turnkey installation and energy auditing. Owens Corning leverages its roofing and insulation bundling to capture integrated retrofit contracts across North America. Saint-Gobain anchors European demand through its multi-brand distribution network spanning Isover glass wool and Weber facade systems. Rockwool International specializes in non-combustible stone wool solutions, positioning its offerings against tightening fire safety codes in high-rise residential towers.
Insulation boards are rigid or semi-rigid panels engineered from foam polymers, mineral fibers, or organic materials, typically manufactured through continuous lamination or batch molding processes to achieve thermal conductivity values between 0.022 and 0.040 W/m·K, serving primarily to reduce heat transfer in building envelopes and industrial equipment. Polystyrene boards dominate volume in below-grade and cavity wall applications where moisture resistance and compressive strength prove critical, while polyurethane panels command premium positioning in space-constrained commercial roofing due to superior R-value per inch. Mineral wool boards lead in fire-rated assemblies and industrial process insulation where temperatures exceed 750°C, with fiberboard gaining traction in sustainable construction projects specifying bio-based binders.
The US Department of Energy building codes and EPA energy efficiency mandates tighten minimum insulation levels for new residential and commercial structures, directly expanding addressable board volume per square foot of construction. REACH restrictions on flame retardant chemistries and the EU F-Gas Regulation phase-down of blowing agents force reformulation of polyurethane and polystyrene products, elevating compliance costs for manufacturers serving European markets. Stakeholders must monitor evolving carbon accounting rules under the EU CSRD and emerging embodied carbon thresholds in green building certifications, as these frameworks will increasingly determine material eligibility for publicly funded construction projects.
Market Dynamics
Building envelope retrofit mandates across mature economies are compressing specification cycles and forcing insulation manufacturers to bundle installation services with board supply, fundamentally altering how value is captured in the value chain.
Growth Catalysts
- EnerPHit passive house protocols:Germany's renovation standard mandates thermal bridge-free construction, driving specification of high-performance rigid boards in residential retrofits across German-speaking Europe.
- EU Green Deal building performance standards:The framework's tightening minimum thermal resistance requirements are expanding board thickness specifications and accelerating replacement cycles in existing building stock.
- Below-grade waterproofing integration:Polystyrene board manufacturers are capturing foundation and basement envelope work by combining insulation with drainage membranes, consolidating trades on commercial and residential projects.
Market Restraints
- Blowing agent supply concentration:European polyurethane board production depends on HFO-1234ze and pentane supply chains concentrated among three chemical producers, creating input cost volatility during F-Gas Regulation phase-down transitions.
- Mineral wool fiber processing bottleneck:High-temperature industrial insulation demand exceeds spinning capacity at European stone wool facilities, extending lead times for fire-rated assemblies.
- Cross-laminated timber substitution:Mass timber construction systems integrate cellulose and wood fiber insulation directly into structural panels, displacing rigid board specifications in mid-rise commercial projects.
Strategic Opportunities
- Industrial process heat decarbonization:Cement, steel, and chemical facilities in Germany and Poland are retrofitting furnaces and kilns with calcium silicate and microporous boards to meet EU ETS carbon pricing thresholds.
- Direct-to-contractor digital platforms:Insulation distributors are bypassing traditional merchant channels through B2B procurement portals that bundle energy auditing, specification software, and just-in-time delivery.
- Embodied carbon scoring integration:The EU CSRD's Scope 3 disclosure requirements are creating first-mover advantage for manufacturers with verified Environmental Product Declarations and biogenic carbon-negative fiberboard offerings.
Industry Challenges
- Fire safety testing backlog:EN 13501-1 classification delays at notified bodies are extending product launch timelines by eight to fourteen months for novel facing materials and core formulations.
- Installation labor scarcity:Qualified envelope contractors capable of executing continuous insulation and air barrier integration remain concentrated in Germany, Austria, and Switzerland, limiting retrofit project scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Boards Market |
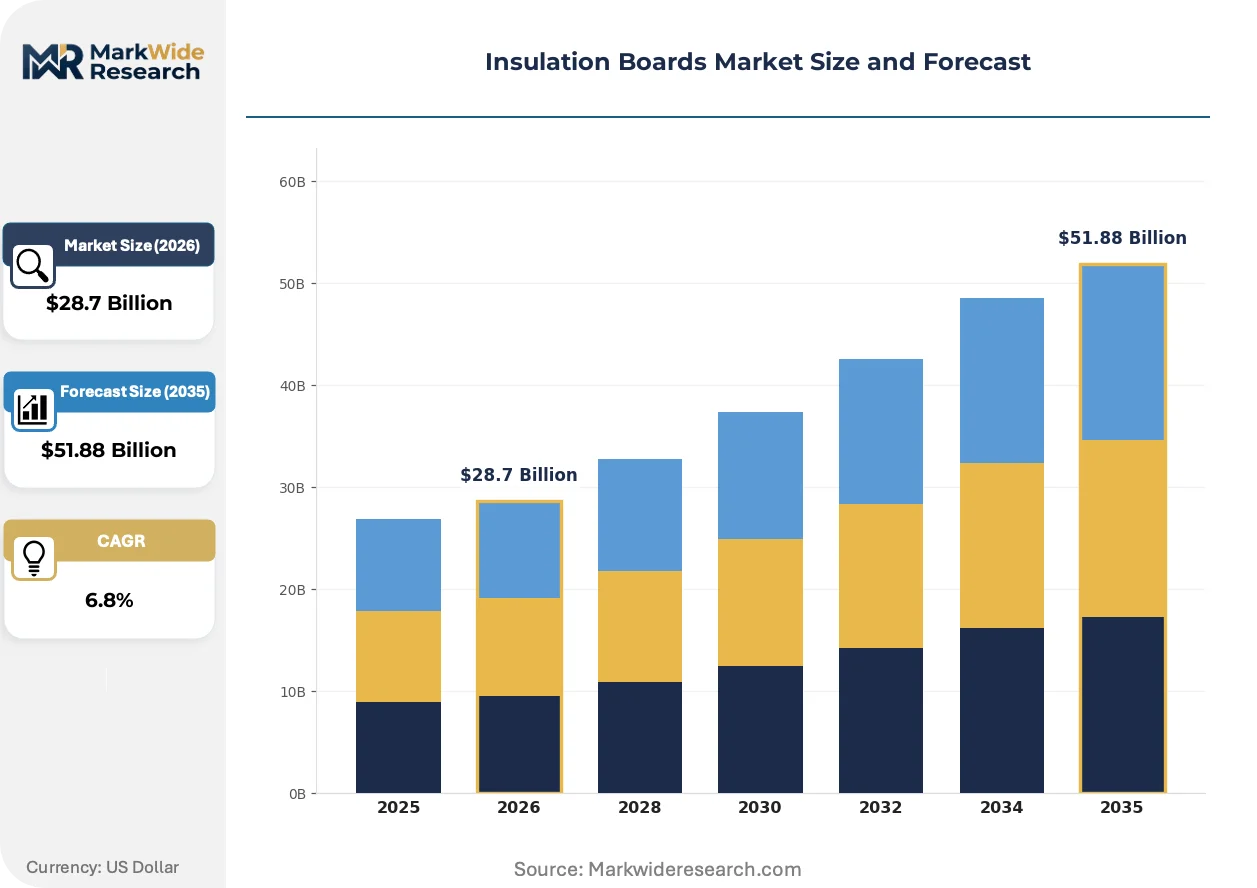
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Fiberboard, Mineral Wool Application: Residential, Commercial, Industrial, HVAC Installation Type: Wall, Roof, Floor, Ceiling Material: Cellulose, Foam, Glass Wool, Others |
| Companies Covered | Kingspan Group, Knauf Insulation, Owens Corning, Armacell International, BASF, Saint-Gobain, Johns Manville Corporation, Huntsman Corporation, Rockwool International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Boards Market Shifts & Advancements
Computational design tools and material science advances are collapsing the traditional separation between thermal performance specification and structural envelope engineering, compressing decision timelines and elevating systems-level competition over commodity board attributes.
Aerogel-infused blanket laminates are penetrating commercial roofing assemblies where space constraints previously limited insulation thickness. Building owners in London, Paris, and Milan are specifying these composites for heritage building renovations where floor-to-floor heights cannot accommodate conventional rigid boards. The technology is virtualizing the trade-off between thermal resistance and spatial efficiency that has historically constrained retrofit feasibility.
The EU F-Gas Regulation's staged reduction in GWP-blowing agent quotas is forcing polyurethane board reformulation across European production facilities. Manufacturers serving German and French markets are qualifying next-generation HFO blends and CO2-water hybrid systems ahead of 2027 step-down thresholds. Industrial cold storage and refrigerated warehouse construction, which depends on high-R-value panels, faces the most acute compliance cost pressure and is driving collaborative supplier-buyer R&D programs.
Energy service companies are unbundling insulation installation from general contracting scopes, creating dedicated retrofit contracting entities that aggregate residential envelope projects at neighborhood scale. This model concentrates purchasing power and standardizes specification packages across German and Dutch housing association portfolios. The channel shift is most visible in multi-family residential districts where block-by-block scheduling achieves labor efficiencies impossible in one-off homeowner contracts.
Insulation Boards Market Segmentation
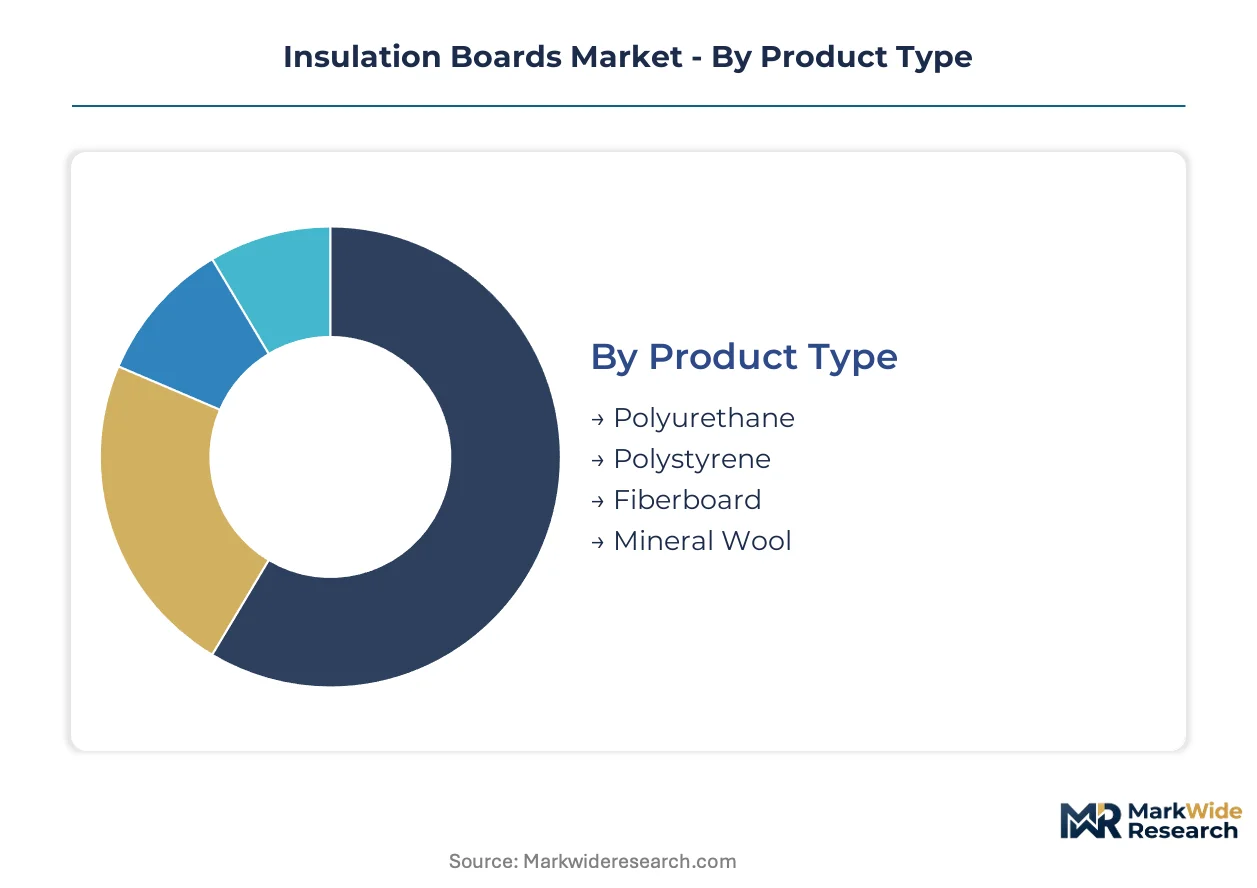
Insulation board specification hinges on matching thermal performance targets to structural constraints across envelope assemblies. Product selection cascades through installation logistics, fire code compliance, and embodied carbon accounting. Segmentation clarity enables manufacturers to align R&D pipelines with retrofit-driven demand concentration.
Product Type:
After-sales intensity varies sharply by chemistry, with polyurethane requiring contractor certification programs and mineral wool demanding fire classification documentation support.
- Polyurethane:Closed-cell rigid foam manufactured through continuous lamination delivers thermal conductivity near 0.022 W/m·K, the lowest among commercial options. Demand clusters in German commercial roofing retrofits where EnerPHit protocols mandate thermal bridge elimination and space constraints prohibit thicker assemblies.
- Polystyrene:Expanded and extruded variants dominate below-grade applications where moisture resistance and compressive strength above 200 kPa prove essential. Foundation contractors in Poland and Czech Republic specify these boards for basement perimeter insulation bundled with drainage composites.
- Fiberboard:Bio-based binders and recycled cellulose content position these panels for sustainable construction certifications. Architects in Nordic markets specify fiberboard for low-rise residential projects targeting carbon-negative material palettes.
- Mineral Wool:Stone wool boards lead fire-rated assemblies with melting points exceeding 1000°C. High-rise residential towers across EU member states mandate these products under EN 13501-1 classifications tightening after Grenfell-era regulatory reforms.
Polystyrene holds the largest share; momentum sits with polyurethane as EnerPHit renovation volume accelerates.
Application:
Cost tier stratification separates commodity new construction from premium retrofit services where energy auditing and air sealing bundle with board supply.
- Residential:Single-family and multi-family envelope retrofits drive specification of rigid boards for facade and roof assemblies. German housing associations aggregate block-scale projects, concentrating purchasing power and standardizing 200-300 mm board thicknesses.
- Commercial:Office and retail buildings prioritize space-efficient insulation in roofing where floor-to-floor height restrictions limit assembly depth. London and Paris heritage renovations specify aerogel-laminated composites for thermal upgrade without structural modification.
- Industrial:Process heat equipment and cold storage facilities demand boards rated for temperature extremes from -50°C to 750°C. Cement and steel producers in Germany retrofit kilns with calcium silicate boards to meet EU ETS carbon pricing thresholds.
- HVAC:Ductwork and mechanical room insulation specifies glass wool and foam boards for thermal efficiency and condensation control. Data center construction across Netherlands and Ireland drives demand for high-R-value chilled water piping insulation.
Residential captures the greatest volume; industrial applications are climbing the fastest as decarbonization mandates tighten.
Installation Type:
Volume concentration in wall systems reflects the scale of residential retrofit programs, while roof applications command premium pricing for access complexity.
- Wall:External thermal insulation composite systems dominate European residential retrofit, combining boards with render and reinforcement layers. German contractors execute continuous insulation across entire housing blocks, achieving labor efficiencies impossible in fragmented single-home projects.
- Roof:Inverted and warm roof assemblies specify high-compressive-strength boards for pedestrian and vehicular traffic loads. Commercial buildings in urban cores favor these systems for plant equipment mounting and maintenance access.
- Floor:Ground-bearing and suspended floor insulation addresses thermal bridging at foundation junctions. Passive house construction in Austria and Switzerland mandates 200-400 mm sub-slab boards to eliminate perimeter heat loss.
- Ceiling:Acoustic and thermal ceiling boards serve retrofit applications where facade work is restricted by heritage preservation. Parisian apartment renovations deploy these for inter-floor noise reduction combined with thermal upgrade.
Wall systems hold the largest share; roof applications gain share fastest as commercial building energy audits identify thermal losses.
Material:
Supply concentration in foam chemistries contrasts with distributed cellulose sourcing, shaping margin structures and carbon accounting methodologies.
- Cellulose:Recycled paper and wood fiber boards with bio-based binders serve sustainable construction projects targeting biogenic carbon credits. Swedish and Finnish manufacturers lead production with integrated forestry supply chains.
- Foam:Polyurethane and polystyrene foams depend on petrochemical feedstocks and blowing agent supply chains concentrated among European chemical producers. REACH restrictions on flame retardants and F-Gas Regulation phase-downs force continuous reformulation.
- Glass Wool:Recycled glass content and rotary fiber spinning yield boards for HVAC and light commercial applications. Saint-Gobain's Isover brand anchors European distribution through multi-channel contractor networks.
- Others:Calcium silicate, microporous silica, and emerging bio-aerogel materials address niche high-temperature and space-constrained applications. Industrial furnace retrofits in Poland specify these for EU ETS compliance.
Foam materials hold the largest share; cellulose alternatives are expanding most quickly as embodied carbon thresholds tighten in green building certifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German buyers accept premium rigid boards for EnerPHit compliance; Polish and Czech contractors prioritize cost-efficient polystyrene for foundation work. Regulatory stringency, not purchasing power, drives specification divergence.
Germany
EnerPHit passive house renovation protocols mandate thermal bridge-free construction, accelerating specification of 200-300 mm polyurethane boards. The Federal Ministry for Economic Affairs and Climate Action enforces building energy codes through the Building Energy Act (GEG). Housing associations in Berlin and Hamburg aggregate block-scale retrofit projects, standardizing high-performance envelope packages across thousands of units.
United States
Below-grade waterproofing integration pulls polystyrene boards into foundation and basement envelope work, bundling insulation with drainage membranes. The Department of Energy building codes tighten minimum insulation levels for new residential and commercial structures. Contractors in Texas and Florida specify high-compressive-strength extruded polystyrene for slab-edge and perimeter applications in humid climates.
Poland
Industrial process heat decarbonization drives furnace and kiln retrofits with calcium silicate and microporous boards. The EU ETS carbon pricing thresholds force cement and steel producers to upgrade thermal envelopes. Facilities in the Silesian industrial cluster retrofit kilns with high-temperature insulation to manage compliance costs under tightening emission allowances.
France
Heritage building renovations in dense urban cores specify aerogel-laminated composites where floor-to-floor heights cannot accommodate conventional rigid boards. The EU Green Deal building performance standards tighten minimum thermal resistance requirements across member states. Parisian apartment renovations deploy ceiling-mounted thermal-acoustic boards for inter-floor noise reduction combined with thermal upgrade.
Netherlands
Data center construction across Amsterdam and Eindhoven drives demand for high-R-value chilled water piping insulation. The EU F-Gas Regulation phase-down of blowing agents forces reformulation of polyurethane products. Energy service companies unbundle insulation installation from general contracting scopes, creating dedicated retrofit contracting entities that aggregate residential envelope projects at neighborhood scale in Rotterdam and Utrecht.
Insulation Boards Market Competitive Landscape
Capability concentration sits with specialized mineral wool and aerogel producers; scale advantage sits with diversified building materials conglomerates. The vendor base spans three tiers: integrated building envelope systems providers, standalone insulation board manufacturers, and regional distributors with installation capabilities. Strategic archetypes include chemistry-agnostic portfolio players, fire-safety specialists, and retrofit service integrators. Competitive moves center on backward integration into blowing agent supply and acquisition of energy auditing platforms.
Among diversified materials conglomerates, BASF and Saint-Gobain occupy positions spanning multiple chemistries and geographies. Owens Corning exemplifies the bundling archetype, leveraging roofing and insulation integration to capture turnkey retrofit contracts. Rockwool International represents the fire-safety specialization vector, positioning non-combustible stone wool against tightening high-rise residential codes. These three anchors illustrate how scale, chemistry breadth, and application focus segment competitive positioning.
| Leading Market Players |
|---|
| Kingspan Group |
| Knauf Insulation |
| Owens Corning |
| Armacell International |
| BASF |
| Saint-Gobain |
| Johns Manville Corporation |
| Huntsman Corporation |
| Rockwool International |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's volatile container rates compress margins for polyurethane board manufacturers serving German EnerPHit contractors, concentrating pricing power with blowing agent suppliers while forcing downstream tiering between certified installation bundles and commodity board sales.
Pricing Analysis
Long-term offtake contracts dominate procurement between major housing associations and insulation manufacturers, locking in volume commitments for 200-300mm rigid board specifications across multi-year retrofit programs. Three-tier pricing structure across premium, standard, and economy levels separates EnerPHit-certified systems with thermal bridge-free detailing from basic EN-compliant boards and unbranded commodity alternatives. Pricing pressure stems from REACH-driven reformulation costs for flame-retardant chemistries, particularly burdening mid-tier producers lacking backward integration into specialty additive supply. German housing associations exhibit lowest price sensitivity due to aggregated purchasing power and GEG compliance mandates, while Polish foundation contractors prioritize cost-efficient polystyrene specifications for perimeter drainage-integrated systems.
Supply Chain Analysis
Contract manufacturing for blowing agent blends concentrates at Honeywell, Chemours, and Arkema facilities in Belgium and France, controlling HFO-1234ze and pentane supply for European polyurethane board production. Raw material flows draw from petrochemical feedstocks in the Netherlands and Germany alongside recycled glass streams from Saint-Gobain's integrated European network. Single-source vulnerability runs through the F-Gas Regulation's staged quota reductions, which threaten supply continuity for high-R-value cold storage panel manufacturers during 2027 transition deadlines. Distribution runs through merchant builders' yards for new construction volume, while retrofit contracting aggregates demand through energy service companies and direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: building code compliance creates switching costs that lock specification decisions through multi-decade building lifecycles, insulating incumbents from price-based competition.
For Market Incumbents: Pre-empt cross-laminated timber substitution by acquiring cellulose insulation specialists and certifying hybrid envelope systems for mid-rise commercial projects. Secure captive supply of next-generation HFO blends through joint development agreements with Belgian chemical producers ahead of 2027 quota step-downs. Channel control represents the priority lever for defending margin position against emerging direct-to-contractor platforms.
For New Entrants and Emerging Players: Establish a beachhead in industrial process heat insulation by qualifying calcium silicate and microporous boards for EU ETS compliance retrofits at Polish cement and steel facilities. Target the most penetrable segment of heritage building ceiling renovations in Paris and Milan, where aerogel-laminated composites command premium positioning without competing against incumbent mineral wool distribution networks. A go-to-market angle through computational design tool integration enables specification capture before traditional merchant channels engage.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates seeking to divest non-core insulation assets amid portfolio rebalancing toward specialty chemicals. Long-term viability over the next decade hinges on embodied carbon accounting dominance under EU CSRD disclosure requirements. Acquisition archetypes include regional distributors with captive installation capabilities and verified Environmental Product Declaration portfolios. The signal to watch is EN 13501-1 classification approval velocity at notified bodies, which indicates product pipeline readiness and regulatory capture capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Supply | Captive HFO-1234ze access insulates margins from F-Gas Regulation quota volatility. |
| Acquisition of Energy Auditing Platforms | Digital retrofit aggregation concentrates purchasing power and standardizes specifications. |
| Certification Investment in EnerPHit Systems | Thermal bridge-free detailing commands premium positioning in German housing association tenders. |
| Joint Venture for Bio-Based Fiberboard Production | Swedish forestry integration enables carbon-negative material claims under EU CSRD. |
| Long-Term Supply Agreement with Industrial EPCs | Furnace retrofit contracting at Polish cement producers secures EU ETS compliance volume. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant managers at polyurethane and mineral wool production facilities, procurement leads at German housing associations and Polish foundation contractors, energy service company executives, and EN 13501-1 notified body technical assessors; alongside secondary validation through customs and trade data, European Chemical Industry Council reports, Building Energy Act implementation guidance, and SEC filings from listed building materials conglomerates. Bottom-up segmentation modeling triangulated against top-down construction spend projections.
Forecast inputs considered product chemistry, application end-use, installation type, and material feedstock across the analysis window, with CAGRs derived from regression against historical building permit volumes and regulatory compliance deadline clustering. Modeled variables included EnerPHit renovation acceleration curves, F-Gas Regulation quota phase-down impact on polyurethane production economics, and industrial decarbonization capital allocation patterns under EU ETS carbon pricing thresholds.
Sensitivities concentrate around EN 13501-1 classification timeline delays, blowing agent supply disruptions during regulatory transitions, and cross-laminated timber substitution rates in mid-rise commercial construction. Quarterly review of notified body approval backlogs, housing association tender aggregation patterns, and industrial EPC contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Insulation Products Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Active Insulation Market