
 India Aroma Chemicals Market | 2026-2036
India Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Aroma Chemicals Market Insights
Buyer concentration across India's fragrance manufacturers is rebalancing as mid-tier flavor houses expand formulation capacity while legacy perfume houses diversify supplier rosters. Eternis leverages captive petrochemical feedstock to sustain margin stability in synthetic aroma compound production. Privi Speciality Chemicals Limited anchors its position through backward integration into terpene chemistry at its Maharashtra facilities. S H Kelkar and Company Limited differentiates via heritage brand equity and deep relationships with domestic cosmetic companies.
Aroma chemicals comprise volatile organic molecules—esters, aldehydes, ketones, and terpenoids—synthesized or extracted to impart scent in formulated consumer products, with purity grades typically exceeding 95% for fine fragrance applications and 90% for functional perfumery. Synthetic aroma compounds dominate volume throughput due to cost consistency and scalable batch production, while natural essential oils command premium positioning in ayurvedic personal care and export-oriented fragrance houses. The food and beverage application segment channels steady demand for GRAS-certified flavor chemicals, whereas pharmaceutical-grade aroma chemicals face tighter CDSCO documentation requirements that elevate entry barriers.
BIS mandatorily certifies aroma chemical purity and labeling standards under IS 4709, while the PLI scheme for specialty chemicals subsidizes capital investment in domestic manufacturing. CDSCO oversight of pharmaceutical excipients and FSSAI food-grade additive rules collectively shape product registration timelines and reformulation costs. Stakeholders must monitor evolving BIS standards for natural isolate authenticity and state-level pollution control mandates that affect solvent recovery investments.
Market Dynamics
Buyer concentration across India's fragrance manufacturers is rebalancing as mid-tier flavor houses expand formulation capacity while legacy perfume houses diversify supplier rosters. The PLI scheme for specialty chemicals is redirecting capital toward domestic terpene extraction and natural isolate production, compressing import dependence for key aroma precursors.
Growth Catalysts
- PLI scheme subsidies:Capital investment incentives for specialty chemicals manufacturing are accelerating domestic production of natural isolates and synthetic aroma compounds.
- Ayurvedic personal care expansion:Heritage wellness brands in Maharashtra and Gujarat are scaling procurement of terpene-based natural essential oils for premium positioning.
- BIS certification harmonization:Mandatory IS 4709 purity standards are streamlining quality benchmarks across fragrance manufacturers in the western industrial corridor.
Market Restraints
- Petrochemical feedstock volatility:Crude-linked benzene and xylene prices expose synthetic aroma compound margins to input cost swings.
- Western corridor supply concentration:Over 60% of domestic production capacity clusters across Mumbai, Vadodara, and Pune, creating geographic vulnerability.
- CDSCO documentation barriers:Pharmaceutical-grade aroma chemical registration requires extensive toxicology dossiers that delay market entry by 18-24 months.
Strategic Opportunities
- Southern India underpenetration:Tamil Nadu and Karnataka fragrance formulators remain underserved by domestic aroma chemical suppliers.
- Biotechnology convergence:Microbial fermentation pathways for terpenoid synthesis are opening renewable alternatives to petrochemical routes.
- FSSAI tailwinds:GRAS certification streamlining for food-grade flavor chemicals is reducing reformulation costs for beverage manufacturers.
Industry Challenges
- Specialized synthesis talent scarcity:Organoleptic chemists with fine fragrance formulation expertise command premium compensation in Mumbai and Pune.
- Solvent recovery capex intensity:State-level pollution control mandates require capital-intensive closed-loop extraction systems for natural isolate producers.
- BIS standardization delays:Evolving authenticity protocols for natural versus synthetic labeling create compliance uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aroma Chemicals Market |
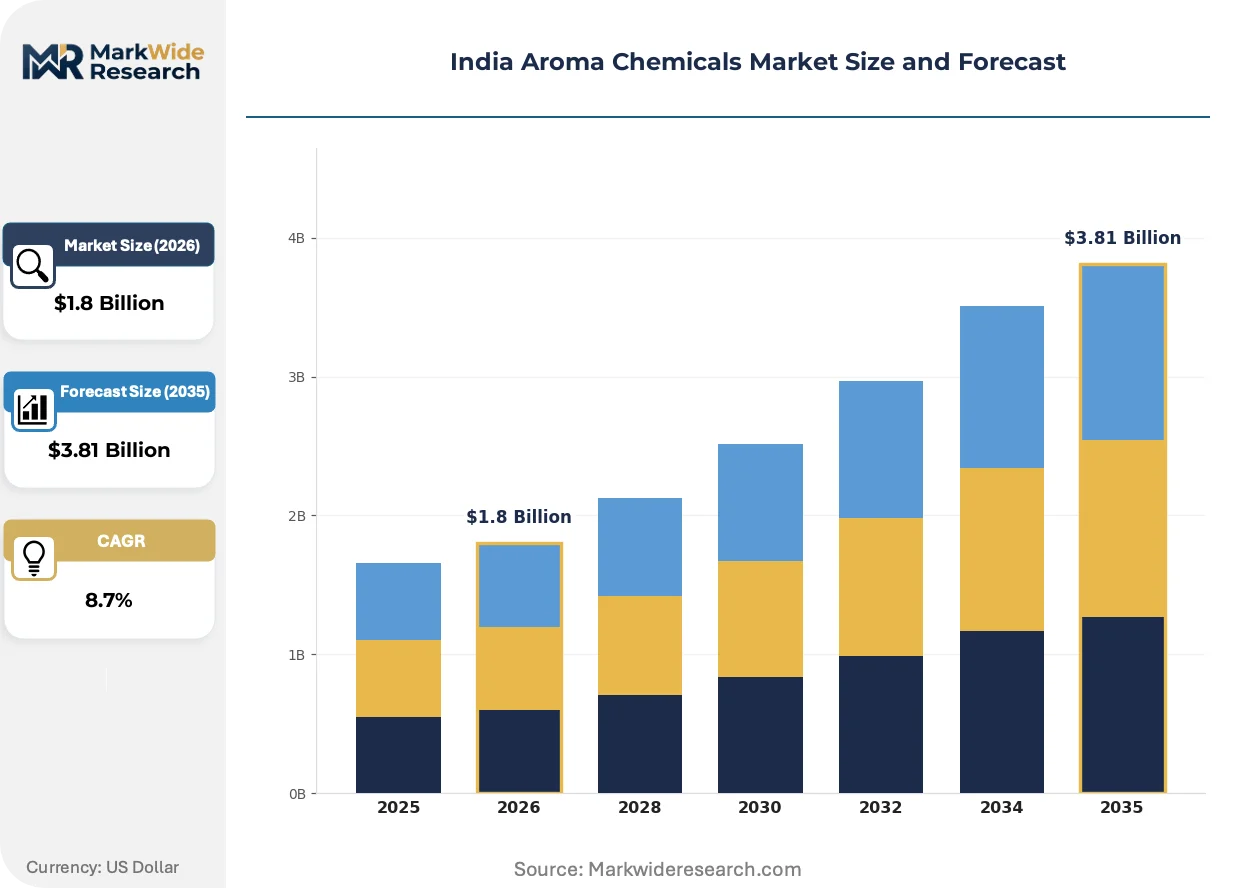
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Essential Oils, Aroma Compounds Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products End User: Fragrance Manufacturers, Flavor Houses, Cosmetic Companies, Food Processors Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | Oriental Aromatics Ltd, Eternis, Privi Speciality Chemicals Limited, Kalpsutra Chemicals Pvt., Ltd., Hindustan Mint and Agro Products Pvt. Ltd., Anuvi Chemicals Limited, S H Kelkar and Company Limited, Kelkar Foods and Fragrances, Atul Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aroma Chemicals Market Trends and Innovations
Continuous processing technology and biotechnology-derived precursors are compressing batch cycle times and enabling renewable feedstock substitution. These shifts are reshaping cost structures and sustainability positioning across synthetic and natural aroma chemical segments.
Continuous flow reactor technology is modularizing production architecture for high-volume synthetic aroma compounds such as linalool and citronellal. Mid-tier fragrance houses in Gujarat are adopting skid-mounted systems to reduce solvent inventory and accelerate batch turnover. This modularization is enabling smaller production footprints without sacrificing throughput consistency.
BIS is tightening IS 4709 standards for natural isolate authenticity, requiring carbon-14 testing to verify botanical origin claims. The regulation is forcing reformulation cycles for ayurvedic personal care brands that previously relied on undisclosed synthetic adulterants. Maharashtra-based exporters are investing in in-house isotope testing to preserve European and Middle Eastern market access.
Direct procurement contracts between fragrance manufacturers and specialty chemical producers are displacing traditional distributor intermediaries in the western corridor. Large personal care formulators in Mumbai are negotiating multi-year supply agreements with captive volume commitments. This channel consolidation is most pronounced among unicorn D2C brands seeking supply security for rapid SKU expansion.
India Aroma Chemicals Market Segmentation
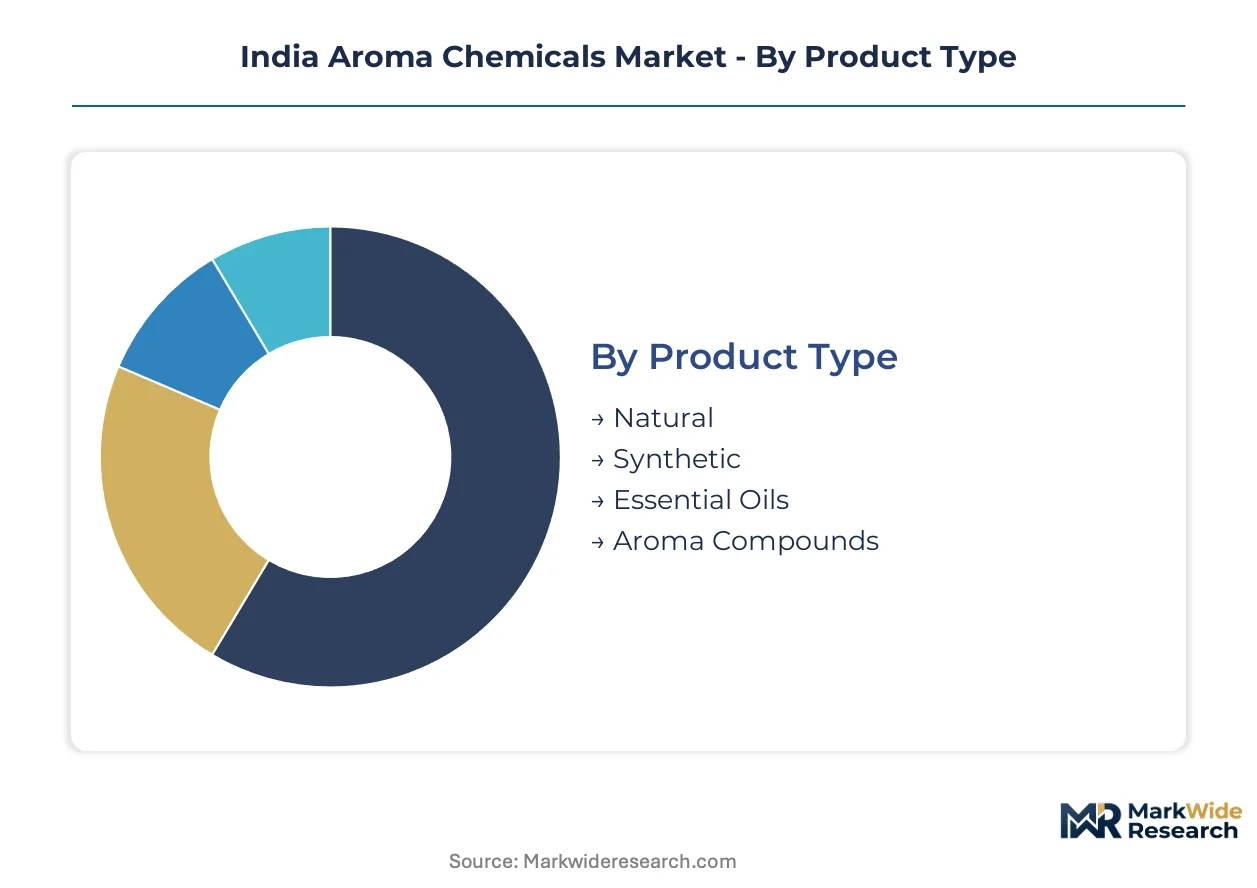
Segmentation in India's aroma chemicals market reveals how supply chain configuration, regulatory pathways, and end-use specifications fragment procurement patterns. Each dimension carries distinct margin profiles and compliance burdens that shape supplier selection and investment priorities across Maharashtra and Gujarat manufacturing clusters.
Product Type:
Synthetic aroma compounds concentrate production capacity in the western industrial corridor due to feedstock proximity to petrochemical complexes.
- Natural:Carbon-14 testing under tightening BIS IS 4709 protocols now verifies botanical origin claims for terpene-based isolates. Maharashtra exporters to European fragrance houses are absorbing capital costs for in-house isotope laboratories to preserve market access.
- Synthetic:Benzene and xylene derivatives manufactured through continuous flow reactor technology dominate volume throughput. Eternis and similar producers leverage captive petrochemical feedstock to buffer margin exposure from crude price volatility.
- Essential Oils:Steam-distilled and cold-pressed botanical extracts serve ayurvedic personal care formulators in Gujarat seeking premium positioning.
- Aroma Compounds:Purified single-molecule odorants exceeding 95% purity for fine fragrance applications command specification premiums from Mumbai-based perfume houses.
Synthetic compounds absorb the bulk of installed capacity; natural isolates are expanding most quickly as PLI scheme subsidies redirect capital toward domestic terpene extraction.
Application:
Application segments diverge sharply in regulatory intensity, with pharmaceutical and food-grade pathways imposing documentation burdens that elevate effective entry costs.
- Food & Beverage:GRAS-certified flavor chemicals face FSSAI additive rules that streamline reformulation timelines for beverage manufacturers. Steady demand channels through flavor houses in Maharashtra supplying carbonated and alcoholic drink producers.
- Personal Care:Fine fragrance and functional perfumery formulations split between premium ayurvedic brands sourcing natural essential oils and mass-market synthetic compounds. D2C unicorn brands in Mumbai are consolidating direct procurement contracts to secure supply for rapid SKU expansion.
- Pharmaceuticals:CDSCO excipient registration demands toxicology dossiers that delay market entry by 18-24 months, compressing supplier rosters to established players with documentation capabilities.
- Household Products:Functional perfumery for detergents and air fresheners prioritizes cost consistency over olfactory complexity, favoring synthetic benzene derivatives from Vadodara manufacturing clusters.
Personal care absorbs the bulk of installed capacity; food and beverage applications are climbing the fastest as FSSAI certification streamlining reduces reformulation friction.
End User:
End-user concentration patterns reveal a rebalancing buyer landscape where mid-tier flavor houses expand formulation capacity while legacy perfume houses diversify supplier rosters.
- Fragrance Manufacturers:Mumbai and Pune-based perfume houses split procurement between heritage natural isolates for export markets and synthetic compounds for domestic functional perfumery. Direct multi-year supply agreements are displacing traditional distributor intermediaries.
- Flavor Houses:Mid-tier Gujarat formulators are scaling capacity to capture beverage and savory flavor contracts, driving demand for GRAS-certified aroma chemicals with batch consistency guarantees.
- Cosmetic Companies:Domestic cosmetic manufacturers leverage S H Kelkar's heritage brand equity and deep relationships for formulation support.
- Food Processors:Integrated food manufacturers in the western corridor procure directly for captive flavor requirements, bypassing external flavor houses on volume accounts.
Fragrance manufacturers command the bulk of supplier attention; flavor houses are gaining share fastest as beverage and savory segments expand formulation outsourcing.
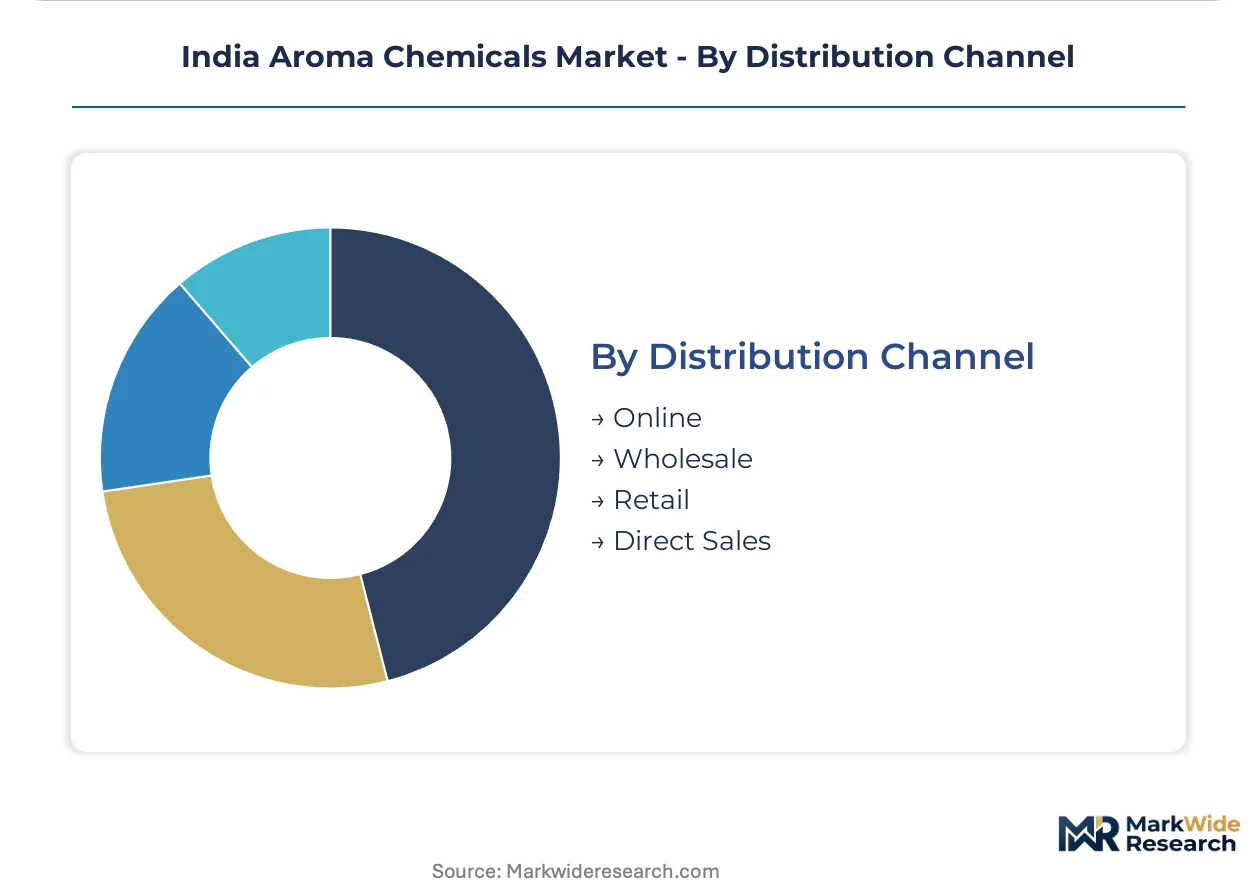
Distribution Channel:
Channel structure reflects the geographic concentration of production capacity and the consolidation of procurement power among large western corridor formulators.
- Online:Digital procurement platforms serve smaller Tamil Nadu and Karnataka fragrance formulators underserved by domestic supplier direct sales teams.
- Wholesale:Traditional distributor networks retain relevance for spot purchases and specialty aroma compounds with irregular demand profiles.
- Retail:Limited to essential oils and small-volume natural isolates for artisanal perfumers and regional ayurvedic compounders.
- Direct Sales:Multi-year supply agreements with volume commitments dominate synthetic aroma compound procurement among large Mumbai personal care formulators and D2C brands.
Direct sales capture the bulk of synthetic compound volume; online channels are expanding most quickly as southern India formulators seek supply access outside traditional geographic clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in India's aroma chemicals market clusters along the western industrial corridor, with fragrance manufacturers and flavor houses driving procurement volumes across Maharashtra and Gujarat.
Maharashtra
Mumbai and Pune anchor personal care formulation demand, with D2C unicorn brands consolidating direct procurement contracts for rapid SKU expansion. BIS IS 4709 certification requirements are tightening purity standards for natural isolates exported to European fragrance houses. The Mumbai-Thane industrial belt concentrates backward-integrated terpene chemistry operations serving domestic and export markets.
Gujarat
Vadodara manufacturing clusters dominate synthetic benzene derivative production for functional perfumery applications in household products. The PLI scheme for specialty chemicals is redirecting capital investment toward domestic natural isolate production facilities. Mid-tier flavor houses in Ahmedabad and Surat are scaling formulation capacity to capture beverage and savory flavor contracts.
Karnataka
Bangalore-based fragrance formulators remain underserved by domestic aroma chemical suppliers, creating procurement dependence on western corridor distributors. FSSAI food-grade additive rules are streamlining GRAS certification pathways for flavor chemicals entering South Indian beverage markets. The state lacks integrated production infrastructure, forcing reliance on external supply chains.
Tamil Nadu
Chennai and Coimbatore personal care manufacturers source synthetic aroma compounds through wholesale distributor networks rather than direct supplier relationships. CDSCO pharmaceutical excipient documentation requirements delay market entry for imported specialty chemicals. The absence of captive petrochemical feedstock proximity limits domestic production investment.
Telangana
Hyderabad's emerging cosmetic manufacturing base is attracting fragrance house satellite operations seeking southern market access. State-level pollution control mandates are elevating solvent recovery capital requirements for potential natural isolate entrants. The region represents the fastest-growing untapped demand pocket for domestic aroma chemical suppliers.
India Aroma Chemicals Market Competitive Landscape
Maharashtra producers anchor one tier; Gujarat specialists hold concentrated synthetic capacity. The vendor base splits between integrated petrochemical players with captive feedstock and standalone terpene chemistry operators. Three archetypes dominate: backward-integrated natural isolate producers, continuous-flow synthetic compound manufacturers, and heritage fragrance houses with formulation relationships. Competitive moves center on direct procurement contract consolidation and multi-year supply agreements with volume commitments.
Among Maharashtra-based operators, S H Kelkar and Company Limited, Privi Speciality Chemicals Limited, and Eternis occupy positions across the integration spectrum. S H Kelkar exemplifies heritage brand equity leveraged for domestic cosmetic relationships. Privi anchors terpene chemistry specialization through Maharashtra facility concentration. Eternis represents petrochemical-integrated synthetic production with margin stability from captive feedstock access. These three illustrate how geographic proximity to Mumbai demand clusters combines with distinct capability positioning to shape competitive differentiation.
| Leading Market Players |
|---|
| Oriental Aromatics Ltd |
| Eternis |
| Privi Speciality Chemicals Limited |
| Kalpsutra Chemicals Pvt., Ltd. |
| Hindustan Mint and Agro Products Pvt. Ltd. |
| Anuvi Chemicals Limited |
| S H Kelkar and Company Limited |
| Kelkar Foods and Fragrances |
| Atul Ltd. |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock costs cascade through synthetic aroma compound pricing tiers, with benzene and xylene derivatives commanding premium stability through Eternis-style captive sourcing while natural isolates face volatile terpene extraction economics. Maharashtra and Gujarat production clusters translate feedstock proximity into margin advantages that compress pricing power for southern India formulators forced into distributor markups.
Pricing Analysis
Volume throughput concentrates in synthetic benzene derivatives where Eternis leverages captive petrochemical access for margin stability, while natural isolates extract premiums through BIS IS 4709 carbon-14 certification tiers. Price differentiation hinges on purity grade thresholds and direct procurement contract scale, with Mumbai D2C brands least sensitive due to SKU expansion urgency and Tamil Nadu formulators most exposed through wholesale dependency. Cost compression in functional perfumery synthetic compounds is intensifying because Vadodara manufacturing clusters compete on batch consistency guarantees rather than olfactory complexity premiums.
Supply Chain Analysis
BIS IS 4709 certification gating now requires carbon-14 isotope verification for natural isolate authenticity, forcing Maharashtra exporters to absorb in-house testing laboratory capex or forfeit European market access. Supply concentrates in India, with limited alternative sourcing for terpene-based botanical precursors outside domestic Maharashtra-Gujarat extraction infrastructure. Raw material dependencies center on petrochemical benzene-xylene streams, imported specialty solvents, and regionally cultivated aromatic crops. Single-source vulnerability runs through Mumbai-Thane terpene chemistry backward integration. Distribution runs through direct multi-year supply agreements for large western corridor formulators, with wholesale networks serving southern India spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream terpene chemistry control and downstream direct procurement contracting determine margin capture. Players pursue captive feedstock access and formulation relationships as the decisive levers.
For Market Incumbents: Lock in multi-year direct supply agreements with Mumbai D2C unicorn brands before biotechnology-derived terpenoid fermentation matures as a substitute pathway. Defend margin position by accelerating Maharashtra in-house carbon-14 isotope testing certification to preserve European export access against tightening BIS IS 4709 protocols. Capacity addition in Gujarat natural isolate production captures PLI scheme subsidies while compressing import dependence. For New Entrants and Emerging Players: Microbial fermentation pathways for terpenoid synthesis offer a technology-first wedge against petrochemical-dependent incumbents. Southern India underpenetration in Tamil Nadu and Karnataka fragrance formulators represents the most penetrable geography, with digital procurement platforms as the go-to-market angle to bypass entrenched western corridor distributor relationships. Target beverage flavor houses in Ahmedabad and Surat scaling GRAS-certified capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor backward-integrated natural isolate producers in Maharashtra with existing BIS certification infrastructure and European export relationships. Long-term viability over the projection horizon rests on terpene chemistry specialization rather than commodity synthetic production. The signal to watch is PLI scheme subsidy allocation velocity toward domestic extraction facilities versus biotechnology fermentation capex.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpene Chemistry | Captures PLI scheme subsidies while securing BIS IS 4709 compliance for European export access. |
| Continuous Flow Reactor Technology Adoption | Reduces solvent inventory and accelerates batch turnover for Gujarat mid-tier fragrance houses. |
| Direct Procurement Contract Consolidation | Displaces distributor intermediaries for Mumbai D2C brands seeking supply security. |
| In-House Carbon-14 Isotope Testing Investment | Preserves market access as BIS tightens natural isolate authenticity protocols. |
| Southern India Distribution Channel Expansion | Addresses Tamil Nadu and Karnataka formulator underservice through digital procurement platforms. |
Research Methodology
Multi-period observation of BIS certification adoption rates, PLI scheme capital allocation patterns, and direct procurement contract velocity anchored the trend analysis, supplemented by interviews with Maharashtra plant managers, Gujarat procurement leads at downstream fragrance manufacturers, Mumbai-based cosmetic company R&D directors, and distribution channel partners across the western industrial corridor. Secondary validation drew from CDSCO pharmaceutical excipient filings, FSSAI GRAS certification databases, customs trade data for aroma chemical imports, and SEC disclosures from listed specialty chemical producers. Bottom-up capacity installation tracking and top-down end-use demand estimation were triangulated against regional production cluster surveys.
Segment-weighting across product type, application, and end-user dimensions informed the analytical framework, with grade tier and regional production hub as additional modeling layers. CAGRs were derived from installed capacity expansion trajectories and formulation outsourcing intensity trends throughout the forecast period. Industry-specific forecast inputs included petrochemical feedstock price correlation coefficients and FSSAI certification streamlining velocity for food-grade flavor chemicals.
Several conditions sit outside the modeled scope, including sudden BIS standard revisions for natural isolate authenticity, state-level pollution control mandate enforcement intensity, and crude oil price volatility spikes beyond historical bands. Forecasts reflect documented assumptions about PLI scheme continuity and CDSCO documentation pathway stability. A model refresh is warranted upon material change in biotechnology-derived terpenoid synthesis cost parity or European fragrance house carbon-14 testing requirement harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Deodorization Systems Market