
 Global Insulation Coating Materials Market | 2026-2036
Global Insulation Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulation Coating Materials Market Foresight
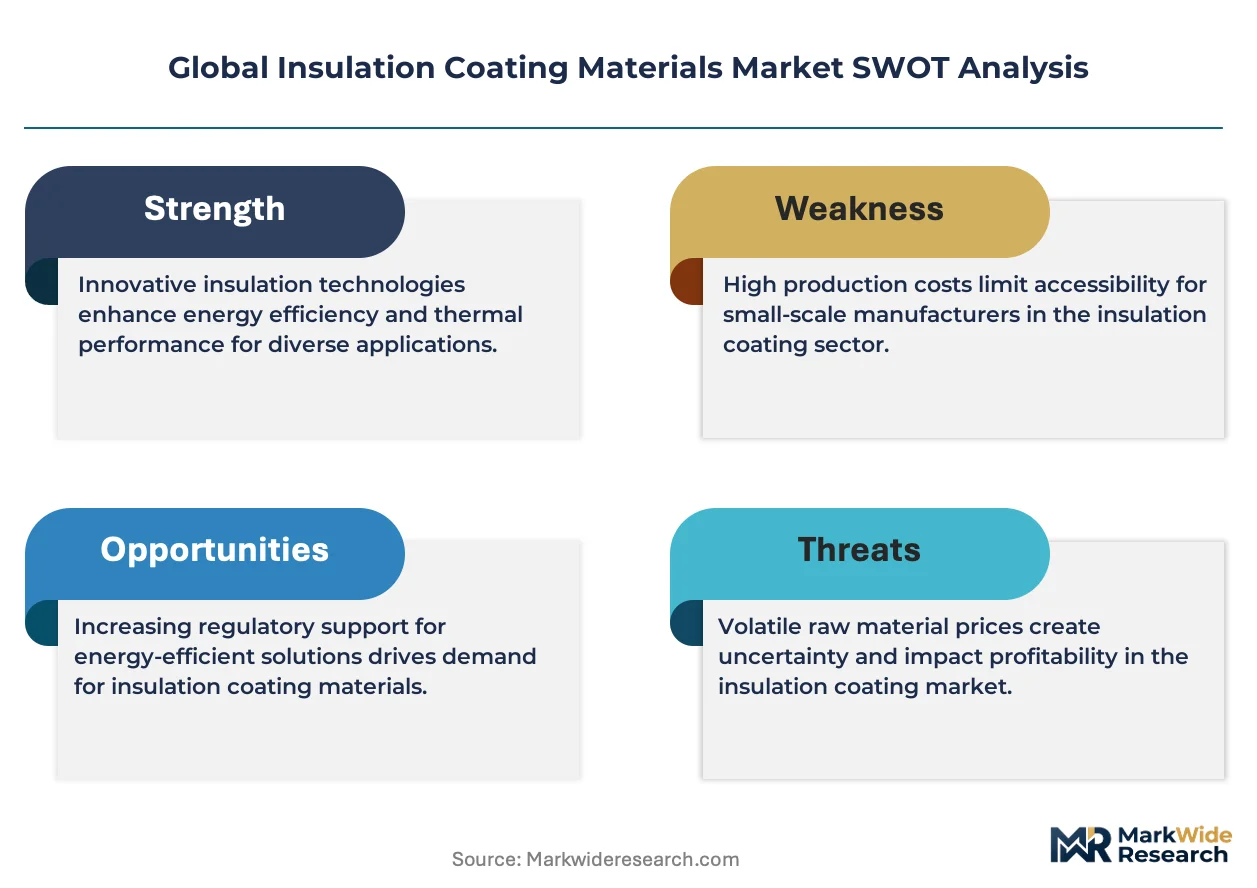
Modular coating kits combining primer, base insulation layer, and topcoat in single-SKU configurations is restructuring procurement patterns for maintenance contractors and EPC firms. AkzoNobel N.V. leverages its marine and protective coatings heritage to dominate offshore platform specifications. PPG Industries, Inc. sustains R&D intensity in powder-based thermal barrier technologies for electrical equipment. BASF SE anchors European supply through integrated resin production and captive additive supply.
Insulation coating materials are engineered formulations—typically polymer-based or ceramic-filled systems applied at thicknesses from 0.5 mm to 10 mm—that reduce thermal transfer, prevent electrical conduction, or inhibit corrosion on substrates operating across extreme temperatures. Their primary industrial purpose is extending asset life while maintaining operational efficiency in energy infrastructure, transportation equipment, and building envelopes. Epoxy coatings lead in electrical insulation applications where dielectric strength and chemical resistance command premium positioning, while ceramic coatings represent the fastest-growing product type as heavy industry pursues surface temperature reductions above 300°C without supplemental cladding. Acrylic coatings occupy the mature residential and light commercial segment where moisture barrier specifications dominate buyer specifications.
EPA NESHAP standards and REACH Annex XVII restrictions on chromium compounds and isocyanates are forcing reformulation across solvent-borne polyurethane and epoxy product lines, elevating compliance costs for importers into the United States and European Union. China's GB standards on volatile organic compound emissions and Japan's JIS K 5660 for building coatings add parallel certification burdens for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants deliver superior returns on compliance investment.
Market Dynamics
REACH Annex XVII restrictions on chromium compounds and EPA NESHAP standards on hazardous air pollutants are forcing simultaneous reformulation across solvent-borne polyurethane and epoxy product lines, compressing formulation cycles and elevating compliance costs for multinational suppliers.
Growth Catalysts
- Oil and gas pipeline thermal barrier procurement:Operators in the Permian Basin and North Sea are expanding specifications for ceramic-filled systems that reduce surface temperatures above 300°C without supplemental cladding, driving specification pull-through for high-temperature formulations.
- China's GB standards on volatile organic compound emissions:State-backed infrastructure builds and power grid expansion in provinces including Guangdong and Jiangsu are consuming large volumes of epoxy and ceramic insulation formulations, concentrating demand in utility-scale applications.
- Ceramic coating technology maturation:Heavy industry in steel processing and petrochemical refining is adopting spray-applied ceramic composites that extend asset life in thermal cycling environments, displacing traditional multi-layer insulation systems.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol A and epichlorohydrin price swings tied to crude oil derivatives and Asian petrochemical capacity expansions are compressing formulation margins for insulation coating producers.
- Solvent-borne system regulatory friction:REACH restrictions on isocyanates and EPA emissions thresholds are forcing capital-intensive reformulation of established polyurethane product lines, extending time-to-market for legacy portfolios.
- Pre-formed insulation substitution threat:Aerogel blankets and calcium silicate boards in power generation and LNG infrastructure are capturing specification share in applications above 600°C where coating thickness limitations constrain performance.
Strategic Opportunities
- India's PLI scheme for domestic manufacturing:The production-linked incentive framework for specialty chemicals and advanced materials is attracting formulation investments targeting thermal barrier demand from refinery expansions along the west coast.
- Modular coating kit distribution innovation:Single-SKU configurations combining primer, base insulation layer, and topcoat are restructuring procurement patterns for maintenance contractors and EPC firms, compressing specification complexity and inventory carrying costs.
- Japan's JIS K 5660 building coating standards:Moisture-cure polyurethane and water-borne acrylic systems meeting these specifications are opening specification pathways for insulation coatings in commercial building envelope retrofits across earthquake-prone urban corridors.
Industry Challenges
- Formulation chemist talent scarcity:The convergence of thermal performance, dielectric strength, and VOC compliance requirements demands expertise in hybrid polymer-ceramic systems that outpaces current technical training pipeline output in Europe and North America.
- Multi-jurisdiction certification timelines:Parallel GB standard testing in China, REACH dossier preparation in Europe, and EPA registration in the United States are extending product launch cycles by 18-24 months for novel insulation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulation Coating Materials Market |
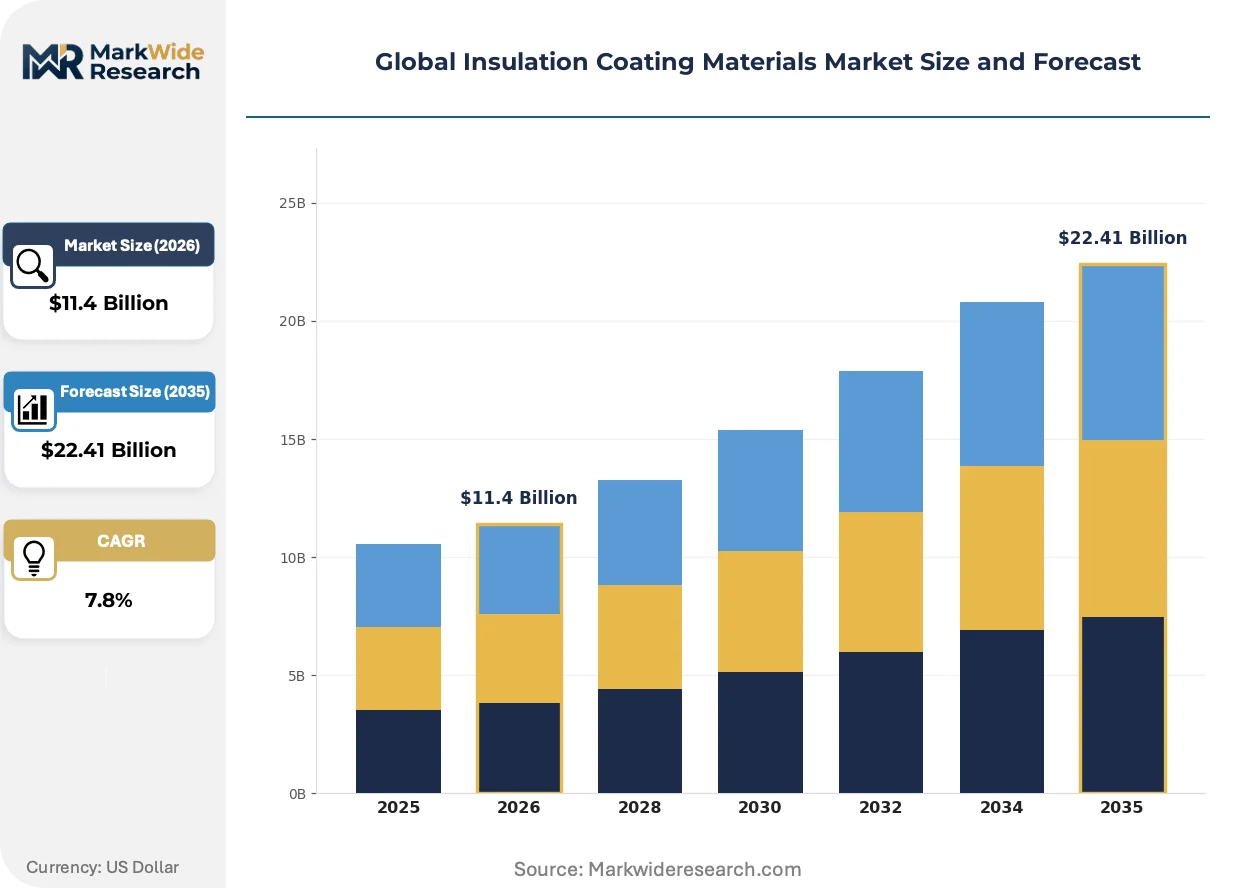
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Coatings, Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings, Ceramic Coatings Application: Thermal Insulation, Electrical Insulation, Fire Protection, Moisture Barrier, Corrosion Resistance End User Industry: Construction Contractors, Electrical Equipment Manufacturers, Fire Safety Firms, Marine Engineering, HVAC Service Providers Form: Liquid, Powder, Aerosol, Paste, Film |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Dow Chemical Company, Jotun A/S, Nippon Paint Holdings Co., Ltd., Hempel A/S, Carboline Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulation Coating Materials Market Shifts & Advancements
Formulation science and application technology are converging to compress installation timelines and expand addressable temperature ranges. Three developments are restructuring competitive positioning and procurement patterns across energy infrastructure and industrial asset protection.
Ceramic-filled spray systems are modularizing field application workflows. These formulations combine alumina-silicate microspheres with inorganic binders to achieve surface temperature reductions above 400°C in single-pass applications. Offshore platform operators and refinery maintenance crews are adopting these systems to eliminate scaffolding and cladding removal steps, compressing turnaround schedules by 40-60% versus traditional multi-layer insulation. The technology is modularizing contractor labor models and reducing specialized craft dependency in high-temperature environments.
EPA NESHAP standards for hazardous air pollutants from coating operations are tightening permissible solvent content thresholds for industrial maintenance applications. These rules are forcing accelerated migration from solvent-borne epoxies to water-borne and high-solids alternatives in US-based petrochemical and power generation facilities. Formulators serving the Gulf Coast refining corridor are investing in hybrid water-borne ceramic systems that maintain corrosion resistance and thermal performance while meeting emissions limits during spray application.
Asset owner engineering teams are consolidating specification authority and demanding performance warranties that bundle material supply with application supervision. This procurement compression is displacing traditional distributor-led selling models in favor of direct manufacturer-EPC relationships for large infrastructure projects. The shift is most visible in China's state-backed power grid expansion, where grid operators are mandating turnkey thermal barrier packages with 15-20 year performance guarantees from formulation suppliers.
Global Insulation Coating Materials Market Segmentation
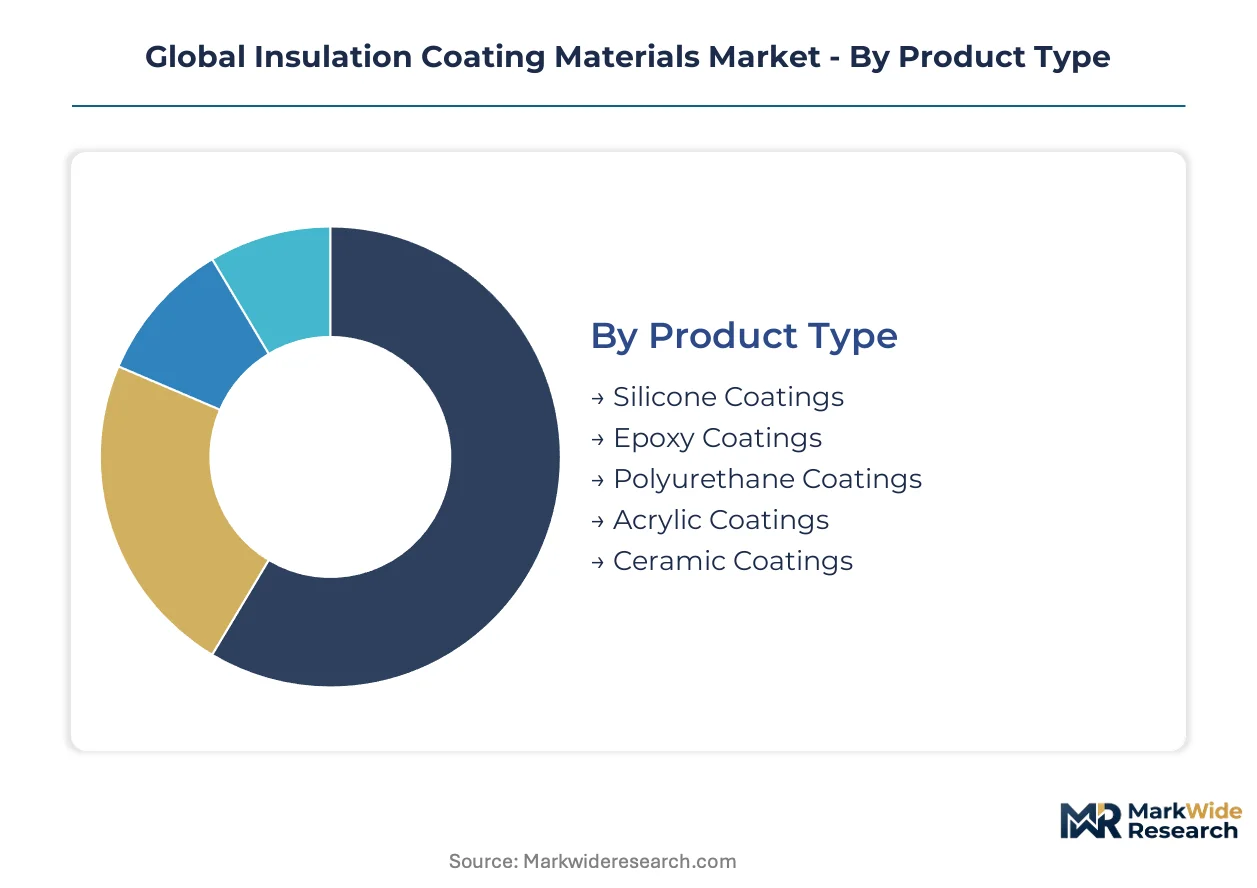
Segmentation in insulation coating materials reveals how formulation chemistry, application method, and end-use severity create distinct procurement ecosystems. Buyers prioritize dielectric strength, temperature tolerance, or regulatory compliance depending on their asset exposure.
Product Type:
Buyer differentiation hinges on thermal ceiling requirements and substrate compatibility rather than price alone.
- Epoxy Coatings:These thermosetting polymer systems deliver superior dielectric strength and chemical resistance for electrical infrastructure. Grid operators in China specify epoxy formulations for transformer housings and switchgear enclosures exposed to humid subtropical conditions.
- Ceramic Coatings:Alumina-silicate microsphere composites achieve surface temperature reductions above 400°C without supplemental cladding. Permian Basin pipeline operators and North Sea platform maintenance crews specify these for high-temperature corrosion protection.
- Silicone Coatings:Elastomeric formulations maintain flexibility across -60°C to 300°C thermal cycling for aerospace and cryogenic applications.
- Polyurethane Coatings:Moisture-cure and water-borne variants dominate commercial building envelopes under Japan's JIS K 5660 standards.
- Acrylic Coatings:Water-based systems serve residential moisture barrier specifications with lower VOC footprints than solvent alternatives.
Epoxy coatings lead volumes today; ceramic coatings are gaining share fastest.
Application:
Performance specifications diverge sharply between passive thermal management and active electrical isolation functions.
- Thermal Insulation:Ceramic-filled and silicone-based systems reduce heat transfer in energy infrastructure operating above 300°C. Steel processing facilities in Germany and petrochemical refineries along the US Gulf Coast specify spray-applied thermal barriers to eliminate traditional cladding.
- Electrical Insulation:Epoxy and polyurethane formulations provide dielectric isolation for motors, generators, and power distribution equipment. China's state-backed power grid expansion consumes large volumes of these formulations for substation and transmission infrastructure.
- Fire Protection:Intumescent coatings expand under heat exposure to protect structural steel in commercial and industrial construction.
- Moisture Barrier:Acrylic and silicone systems prevent water ingress in building envelopes and below-grade structures.
- Corrosion Resistance:Epoxy and ceramic coatings protect offshore platforms, pipelines, and chemical processing equipment from salt spray and acidic environments.
Thermal insulation commands the largest application spend; electrical insulation shows the steepest expansion trajectory.
End User Industry:
Procurement authority concentrates with asset owners in capital-intensive sectors versus distributed contractor networks in construction.
- Construction Contractors:Commercial and residential builders specify moisture barrier acrylics and fire protection intumescents. Japan's earthquake-prone urban corridors drive demand for JIS K 5660 compliant building envelope systems.
- Electrical Equipment Manufacturers:OEMs integrate epoxy and polyurethane insulation into motors, transformers, and switchgear for domestic and export markets. Chinese manufacturers supply both state grid expansion and Southeast Asian infrastructure projects.
- Fire Safety Firms:Specialized applicators install passive fire protection systems in high-rise and industrial facilities.
- Marine Engineering:Shipbuilders and offshore platform operators specify corrosion-resistant epoxy and ceramic systems for saltwater exposure.
- HVAC Service Providers:Maintenance contractors apply thermal insulation coatings to ductwork and refrigeration equipment in commercial buildings.
Electrical equipment manufacturers lead volumes today; construction contractors are expanding procurement fastest.
Form:
Application economics and field conditions determine whether liquid spray, powder coating, or pre-formulated kits prevail.
- Liquid:Solvent-borne and water-borne formulations dominate high-volume industrial application. EPA NESHAP emissions standards are accelerating migration to water-borne and high-solids alternatives in US petrochemical facilities.
- Powder:Thermosetting epoxy and polyurethane powders serve electrical equipment manufacturers requiring thick, uniform coatings without solvent emissions. PPG Industries sustains R&D intensity in powder-based thermal barrier technologies.
- Aerosol:Portable touch-up and maintenance applications in HVAC and marine sectors.
- Paste:Trowel-applied ceramic composites for irregular surfaces and repair scenarios.
- Film:Pre-cured silicone and polymer sheets for precise thickness control in electronics and aerospace.
Liquid formulations dominate current volumes; powder coatings are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial coating chemistry scaled first in Germany's Ruhr industrial corridor during the post-war reconstruction era, then migrated to US Gulf Coast petrochemical complexes and China's coastal manufacturing zones. Today formulation demand concentrates where energy infrastructure investment, regulatory enforcement, and domestic manufacturing policy intersect.
United States
Permian Basin pipeline operators and Gulf Coast refinery maintenance crews are expanding procurement of ceramic-filled thermal barrier systems for surface temperature management above 300°C. EPA NESHAP standards on hazardous air pollutants from coating operations are accelerating migration from solvent-borne to water-borne and high-solids formulations in Texas and Louisiana petrochemical corridors.
Germany
Steel processing facilities in the Ruhr region and chemical complexes along the Rhine specify spray-applied ceramic composites to displace traditional multi-layer insulation in thermal cycling environments. REACH Annex XVII restrictions on chromium compounds and isocyanates are forcing simultaneous reformulation across solvent-borne polyurethane and epoxy product lines, compressing formulation cycles for European suppliers.
China
State-backed power grid expansion in Guangdong and Jiangsu provinces consumes large volumes of epoxy and ceramic insulation formulations for transformer housings and transmission infrastructure. GB standards on volatile organic compound emissions are tightening certification requirements for industrial coatings, adding parallel compliance burdens for multinational suppliers serving utility-scale applications.
India
Refinery expansions along the west coast in Gujarat and Maharashtra are generating thermal barrier demand from petrochemical infrastructure investments. The PLI scheme for specialty chemicals and advanced materials is attracting formulation investments targeting domestic manufacturing of insulation coating systems for industrial asset protection.
Japan
Commercial building envelope retrofits across earthquake-prone urban corridors in Tokyo and Osaka are opening specification pathways for moisture-cure polyurethane and water-borne acrylic systems. JIS K 5660 building coating standards are shaping procurement patterns for insulation materials in seismic-resistant construction applications.
Global Insulation Coating Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth, with integrated resin producers commanding structural advantages over toll blenders. The vendor base fragments across multinational chemical conglomerates, regional coating specialists, and niche ceramic composite formulators. Three archetypes dominate: integrated chemical majors with captive raw material supply, protective coatings specialists with marine and offshore heritage, and regional players serving localized certification requirements. Capacity expansion and portfolio diversification toward water-borne and high-solids alternatives represent the dominant competitive vectors as regulatory pressure intensifies.
Among integrated chemical majors, AkzoNobel N.V., PPG Industries, Inc., and BASF SE exemplify distinct strategic positions within the competitive structure. AkzoNobel's heritage in marine and protective coatings anchors its positioning in offshore platform specifications. PPG Industries represents the scale-driven end with sustained technical investment in powder-based thermal barrier technologies. BASF SE's integrated resin production and captive additive supply demonstrate backward integration advantages in European formulation markets.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| BASF SE |
| Dow Chemical Company |
| Jotun A/S |
| Nippon Paint Holdings Co., Ltd. |
| Hempel A/S |
| Carboline Company |
| Others |
Supply & Pricing Matrix
Captive resin production by integrated chemical majors anchors both supply security and pricing power in insulation coating materials, with BASF SE's backward integration into epichlorohydrin and bisphenol A derivatives insulating European formulators from Asian petrochemical volatility while compressing margin capture opportunities for toll blenders dependent on spot resin markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment, with UL-listed electrical insulation formulations commanding substantial premiums over uncertified commodity alternatives. Price differentiation hinges on REACH dossier completeness and EPA registration status, with fully certified suppliers extracting margin from utility-scale buyers in China and the United States. Cost compression in solvent-borne epoxy tiers is intensifying because of bisphenol A feedstock volatility tied to crude derivative markets. Construction contractors exhibit the highest price sensitivity, while electrical equipment manufacturers prioritize dielectric performance over unit cost.
Supply Chain Analysis
Freight cost escalation on resin shipments from Germany and the Netherlands to Asian formulation plants is compressing margins for European suppliers serving China's state-backed infrastructure builds. Raw material sourcing concentrates in Germany, China, and the United States for specialty epoxy resins, ceramic microspheres, and isocyanate curing agents. Single-source vulnerability around Asian epichlorohydrin capacity creates exposure for non-integrated formulators. Distribution runs through direct manufacturer-EPC relationships for large infrastructure projects, displacing traditional distributor-led models in utility-scale applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where formulation investments in India under the PLI scheme capture cost advantages against REACH-burdened European production while accessing identical refinery demand from Gujarat's west coast expansions.
For Market Incumbents: Acquire ceramic composite formulation capabilities to defend against aerogel blanket substitution in power generation applications above 600°C. Deepen backward integration into specialty resin production to offset bisphenol A price volatility compressing epoxy formulation margins. Prioritize direct EPC relationships in China's state-backed power grid expansion to lock in 15-20 year performance guarantee contracts before specification authority consolidates further. For New Entrants and Emerging Players: Water-borne hybrid ceramic systems meeting EPA NESHAP emissions thresholds represent the most penetrable wedge for Gulf Coast petrochemical corridor entry. Target India's PLI-supported domestic manufacturing incentives for specialty chemicals to bypass established European supply chains serving refinery expansions in Gujarat and Maharashtra. Lead with application supervision bundled into material supply to mirror turnkey procurement patterns displacing distributor models. For Investors and Strategic Acquirers: Roll-up economics work for regional coating specialists with captive certification in specific jurisdictions because multi-jurisdiction compliance timelines extend product launch cycles by 18-24 months, creating acquisition premiums for pre-certified assets. Five-to-ten year viability favors formulators with water-borne and high-solids portfolios positioned ahead of solvent-borne regulatory phase-outs. Monitor EPA NESHAP enforcement intensity in Texas and Louisiana as the signal for accelerated migration timelines and stranded asset risk in legacy solvent-borne capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | BASF SE's captive epichlorohydrin supply insulates margins from Asian petrochemical volatility. |
| Water-Borne Formulation Migration | EPA NESHAP compliance in Gulf Coast refineries accelerates hybrid ceramic system adoption. |
| Direct EPC Relationship Development | Turnkey procurement in China's grid expansion locks in long-term performance guarantee contracts. |
| Ceramic Composite Capability Acquisition | Spray-applied alumina-silicate systems displace traditional multi-layer insulation in North Sea platforms. |
| PLI-Aligned Manufacturing Investment | India's production-linked incentives attract formulation capacity targeting west coast refinery demand. |
Research Methodology
Multiple input streams — technical interviews with formulation chemists and plant managers at coating manufacturing facilities, procurement discussions with EPC contractors and maintenance directors at oil and gas operators, and regulatory consultations with REACH dossier preparers and EPA compliance officers — were reconciled against customs data on resin trade flows, SEC filings from integrated chemical majors, and GB standard certification databases. Bottom-up volume estimates from end-use industry consumption patterns were triangulated with top-down value projections derived from raw material cost structures.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions by product type, application function, end-user industry, and regional regulatory cluster. Modeled dimensions included thermal performance tier, dielectric strength grade, VOC compliance level, and project scale category. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure investment pipelines and regulatory phase-in schedules. Forecast inputs incorporated ceramic coating technology maturation curves and solvent-borne formulation displacement rates under tightening emissions standards.
The model holds under stable regulatory enforcement timelines and continuous infrastructure investment flows; deviation in EPA NESHAP implementation pace or China's state-backed grid expansion deceleration would shift volume trajectories materially. Forecasts reflect documented assumptions about technology substitution thresholds and certification timeline compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Flame-Retardant Foams and Insulation Market