
 Flexible Insulation Market | 2026-2036
Flexible Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Insulation Market Analysis
China is fragmenting as domestic producers expand fiberglass mat capacity to serve regional construction markets. Owens Corning leverages its North American mineral wool infrastructure to sustain pricing power in commercial roofing. Johns Manville anchors its position through vertical integration into recycled glass feedstock for fiberglass production. Knauf Insulation competes aggressively on European HVAC ductwork specifications through its formaldehyde-free binder technology.
Flexible insulation comprises low-density, conformable thermal and acoustic barrier materials typically manufactured through rotary fiberization, polymer extrusion, or aerogel synthesis processes, with thickness tolerances engineered to bend radii as tight as 50 millimeters for curved duct and pipe applications. Fiberglass products dominate volume shipments across the analysis window due to established supply chains and cost-positioning, while aerogel segments capture disproportionate margin pools in aerospace and cryogenic applications where space constraints override material cost premiums. Polyurethane foam formulations lead growth in automotive underbody and HVAC equipment insulation as OEMs prioritize weight reduction alongside thermal performance targets.
The US Department of Energy appliance efficiency standards and EPA refrigerant phase-down rules under the AIM Act are redirecting HVAC equipment insulation specifications toward higher R-value-per-inch materials. REACH restrictions on flame retardant chemistries in Europe and China's GB 8624 fire classification standards are forcing reformulation investments across polyurethane and polystyrene product lines. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs for multi-territory suppliers are compounding faster than harmonization efforts advance.
Market Dynamics
Building energy code tightening across developed economies is compressing specification cycles and forcing material upgrades faster than supply chains can normalize inventory positions.
Growth Catalysts
- US federal efficiency incentives:Commercial retrofit tax credits under the Inflation Reduction Act are accelerating HVAC equipment replacement schedules and insulation specification upgrades in existing building stock.
- Bio-based polyurethane formulations:Plant-derived polyol feedstocks are displacing petrochemical inputs as manufacturers respond to Scope 3 emissions targets and customer sustainability scorecards.
- REACH flame retardant restrictions:ECHA's phased limitations on halogenated chemistries are pulling demand toward mineral wool and fiberglass alternatives in European construction applications.
Market Restraints
- Silica sand supply concentration:High-purity glass-grade feedstock availability clusters with Chinese and US Midwest suppliers, exposing fiberglass producers to logistics cost volatility and tariff exposure.
- Aerogel manufacturing scale limits:Supercritical drying equipment requirements and solvent handling complexity constrain production expansion despite aerospace and cryogenic demand premiums.
- Polyurethane blowing agent transition costs:EPA AIM Act hydrofluorocarbon phase-down rules are forcing capital-intensive reformulation of foam systems before amortization of existing product lines.
Strategic Opportunities
- Data center thermal management:Hyperscale facility construction in Northern Virginia, Frankfurt, and Singapore is creating specification pull for high-R-value, space-constrained insulation in cooling distribution systems.
- Electric vehicle battery pack insulation:Cell-to-pack architectures are opening volume demand for compressible thermal barriers that accommodate cell swelling while maintaining dielectric properties.
- EU F-Gas Regulation:The 2024-2030 quota reduction schedule is redirecting cold chain equipment specifications toward vacuum insulation panels and advanced foam systems with lower global warming potential.
Industry Challenges
- Refrigerant-handling certification gaps:HVAC contractor workforce shortages in low-GWP system installation are delaying equipment commissioning and insulation completion timelines.
- Multi-jurisdiction compliance complexity:Divergent fire classification testing protocols between GB 8624 in China, EN 13501 in Europe, and ASTM E84 in the United States are fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Insulation Market |
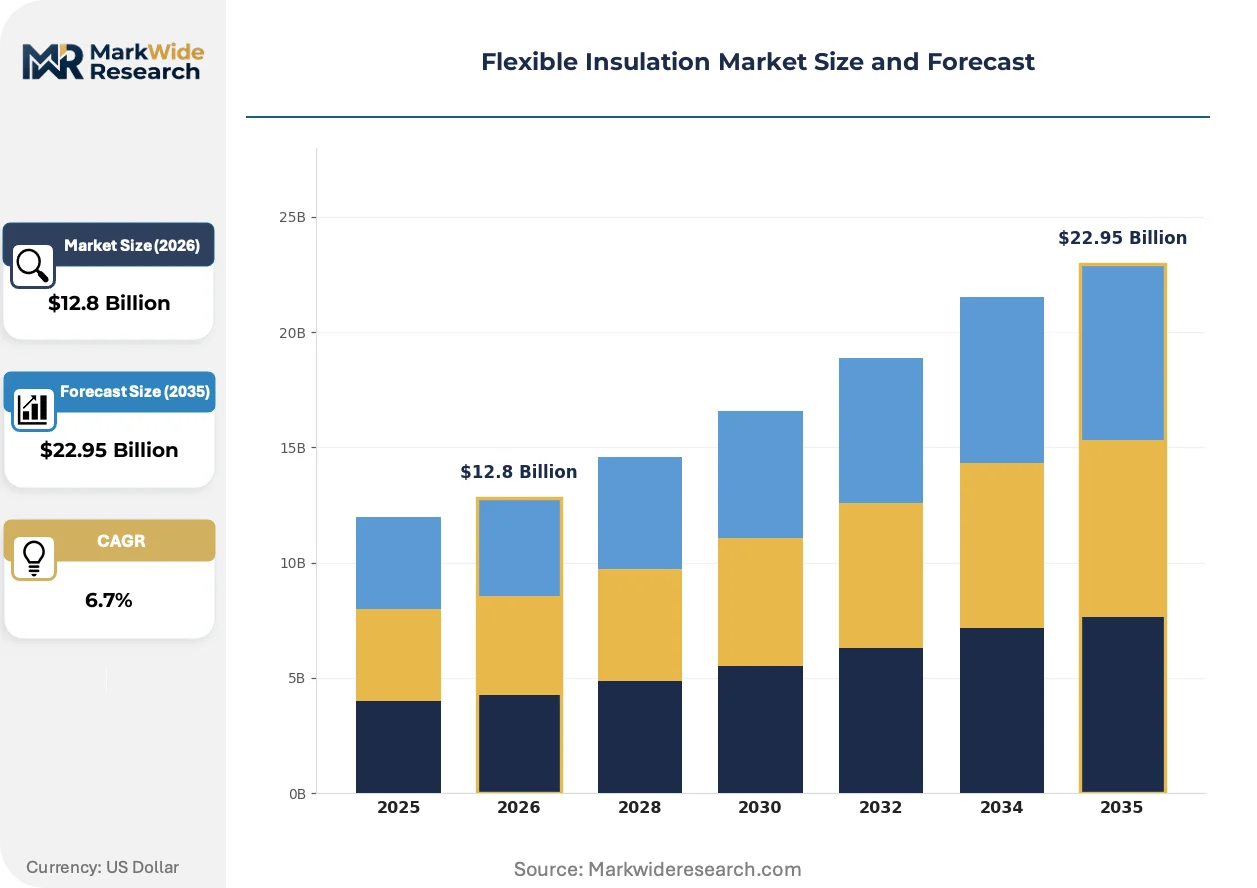
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam, Rock Wool, Aerogel Material: Polystyrene, Polyurethane, PVC, Cellulose End User: Construction, HVAC, Automotive, Aerospace Application: Thermal Insulation, Acoustic Insulation, Fire Insulation, Moisture Control |
| Companies Covered | Saint-Gobain, Owens Corning, Johns Manville, Knauf Insulation, Armacell, BASF SE, Cabot Corporation, Rockwool International, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Insulation Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are compressing traditional product lifecycles while opening margin pools in performance-specialized segments.
Aerogel blanket manufacturing is collapsing the cost premium versus traditional high-performance insulation through continuous production methods that eliminate batch supercritical drying. Aerospace OEMs and LNG shipping operators are absorbing volume as the technology crosses from satellite and probe applications into commercial thermal protection. The structural consequence is margin compression in premium insulation tiers as aerogel displaces multilayer vacuum insulation in space-constrained cryogenic systems.
REACH restrictions on halogenated flame retardants are forcing polyurethane foam reformulation across European construction and appliance segments. Manufacturers are pivoting toward phosphorus-based and mineral filler alternatives that maintain fire performance without SVHC classification. HVAC ductwork and commercial roofing applications in Germany, France, and the Netherlands are experiencing the most acute specification turbulence as compliance deadlines approach.
Building owners are consolidating mechanical system procurement under performance contracting arrangements that bundle insulation specification with energy savings guarantees. Engineering-procurement-construction firms are displacing traditional distributor channels in commercial new build and deep retrofit projects. The United States and Nordic markets show the fastest channel migration as federal and national efficiency incentives tighten payback thresholds for bundled system upgrades.
Flexible Insulation Market Segmentation
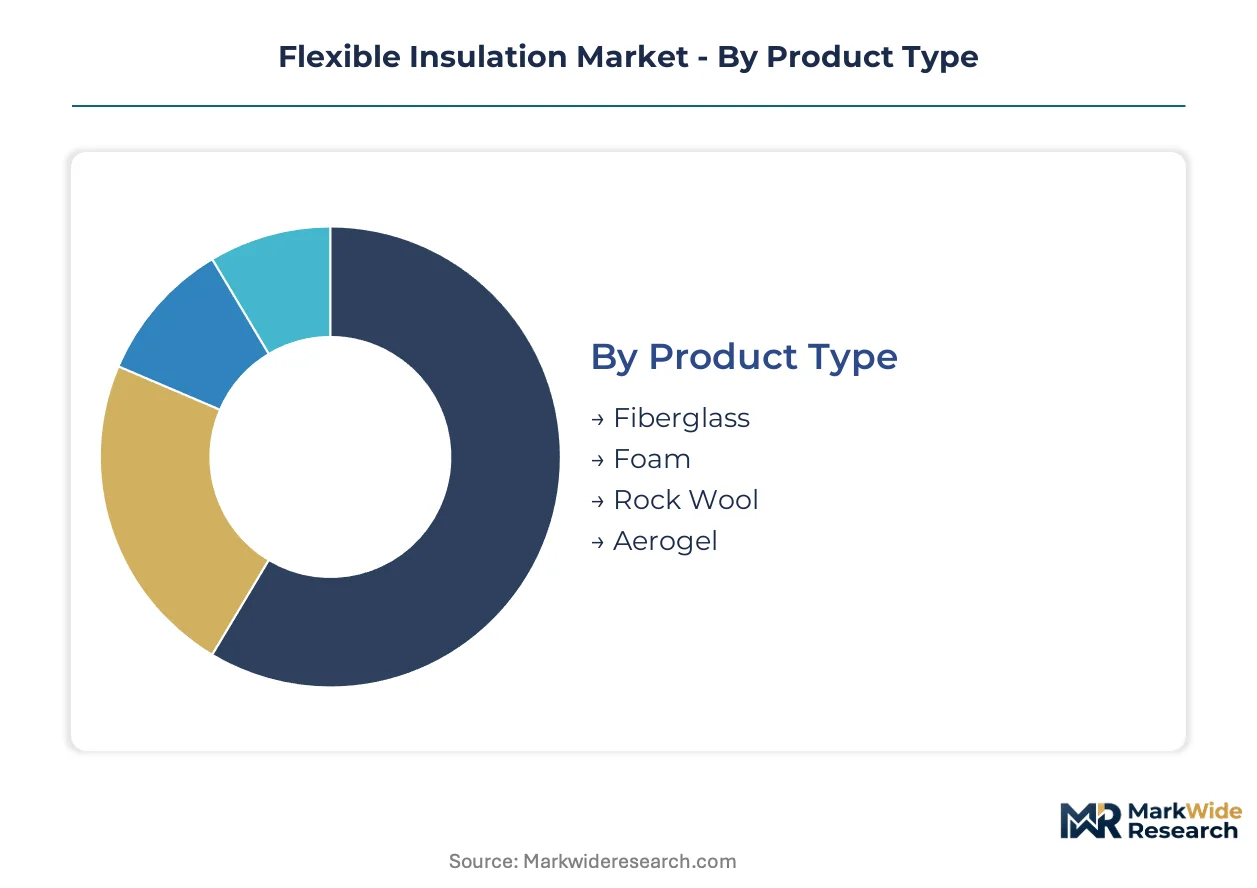
Segmentation in flexible insulation reveals how material properties, regulatory constraints, and end-use performance requirements fragment manufacturing strategies and distribution economics. Technical specifications diverge sharply between commodity construction applications and aerospace-grade thermal barriers, forcing suppliers to maintain parallel product architectures.
Product Type:
After-sales service intensity varies dramatically across product categories, with aerogel and specialized foam systems requiring technical field support while fiberglass operates through distributor self-service models.
- Fiberglass:Rotary-fiberized borosilicate glass wool dominates volume economics through established melt-forming infrastructure and recycled glass feedstock integration. Demand concentrates in United States commercial roofing and HVAC ductwork as federal efficiency incentives compress payback thresholds for thermal upgrades.
- Foam:Polyurethane and polystyrene extrusions lead automotive underbody and appliance cavity applications where weight reduction targets override material cost premiums. European REACH flame retardant restrictions are forcing phosphorus-based reformulation investments before existing product lines amortize.
- Rock Wool:Mineral fiber spun from molten basalt or diabase serves fire-rated commercial construction and industrial process insulation with service temperatures exceeding 750°C.
- Aerogel:Silica-based nanoporous solids manufactured through supercritical drying capture aerospace and cryogenic margins where space constraints dominate specification decisions.
Fiberglass holds the largest share; momentum sits with aerogel as continuous production methods collapse cost premiums versus multilayer vacuum insulation.
Material:
Cost tier stratification separates petrochemical-derived feedstocks facing regulatory chemistry restrictions from bio-based alternatives commanding sustainability premiums in corporate procurement scorecards.
- Polystyrene:Expanded and extruded forms serve cold chain packaging and building envelope applications where moisture resistance and compressive strength balance thermal performance. China's GB 8624 fire classification standards are restricting specification in high-rise construction.
- Polyurethane:Spray-applied and boardstock formulations lead HVAC equipment and refrigerated transport insulation as EPA AIM Act hydrofluorocarbon phase-down rules redirect blowing agent chemistry toward lower-GWP alternatives. Plant-derived polyol feedstocks are displacing petrochemical inputs among manufacturers targeting Scope 3 emissions reductions.
- PVC:Flexible vinyl foams provide acoustic damping and thermal barriers in automotive interior applications with established supply chains through polymer compounding specialists.
- Cellulose:Recycled paper fiber treated with borate flame retardants serves residential cavity fill and loose-fill attic applications at the economy tier of building insulation.
Polyurethane commands the dominant position; polystyrene faces steepest headwinds from fire safety regulation tightening across multiple jurisdictions.
End User:
Application maturity separates established construction markets with specification inertia from emerging electric vehicle battery pack insulation demanding compressible thermal barriers with dielectric integrity.
- Construction:Commercial new build and deep retrofit projects absorb fiberglass and mineral wool volume as building energy codes tighten across Germany, France, and the Netherlands. Engineering-procurement-construction firms are displacing traditional distributor channels in bundled mechanical system procurement.
- HVAC:Equipment OEMs and commercial retrofit contractors drive specification toward higher R-value-per-inch materials as US Department of Energy appliance efficiency standards compress allowable energy consumption. Northern Virginia and Frankfurt hyperscale data center construction is creating pull for space-constrained cooling distribution insulation.
- Automotive:Cell-to-pack battery architectures are opening volume demand for compressible thermal barriers accommodating lithium-ion cell swelling while maintaining electrical isolation properties.
- Aerospace:OEM thermal protection systems and LNG shipping operators absorb aerogel volume as continuous production methods displace legacy multilayer vacuum insulation in cryogenic applications.
Construction retains the volume base; automotive battery insulation represents the steepest expansion trajectory as electric vehicle production scales.
Application:
Functional performance requirements fragment manufacturing capabilities, with acoustic and fire-rated applications demanding specialized binder chemistries and testing certifications that thermal-only products bypass.
- Thermal Insulation:R-value-per-inch optimization dominates HVAC equipment and building envelope specifications as energy code compliance thresholds tighten. Singapore and Frankfurt data center construction is pulling high-performance foam and aerogel systems for cooling distribution efficiency.
- Acoustic Insulation:Fiberglass and mineral wool mat products with tuned density profiles serve commercial building interior partitions and automotive NVH reduction where sound transmission class ratings determine specification.
- Fire Insulation:Mineral wool and intumescent coatings command premium positioning in commercial high-rise and industrial process applications where service temperature and fire resistance ratings override thermal performance metrics.
- Moisture Control:Vapor retarder-faced foam boards and desiccant-integrated systems protect building assemblies and cold chain equipment from condensation damage in humid climates.
Thermal insulation anchors revenue; fire-rated applications are gaining share fastest as regulatory safety margins expand across European and Chinese construction codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity glass-grade silica sand availability clusters with Chinese and US Midwest suppliers, exposing fiberglass producers to logistics cost volatility. This feedstock concentration shapes regional manufacturing footprints and tariff exposure across the industry.
United States
Commercial retrofit activity and federal efficiency incentives under the Inflation Reduction Act are accelerating HVAC equipment replacement schedules. The US Department of Energy appliance efficiency standards compress allowable energy consumption for insulated systems. Northern Virginia's hyperscale data center construction cluster is pulling specification upgrades for space-constrained cooling distribution insulation.
China
Domestic producers are expanding fiberglass mat capacity to serve regional construction markets, fragmenting supply concentration. GB 8624 fire classification standards are restricting polystyrene specification in high-rise construction applications. The Yangtze River Delta manufacturing corridor hosts expanding rotary fiberization capacity serving both domestic and export demand.
Germany
REACH restrictions on halogenated flame retardants are forcing polyurethane foam reformulation investments across construction and appliance segments. ECHA's phased limitations pull demand toward mineral wool alternatives in commercial building applications. The Rhine-Ruhr industrial corridor maintains dense concentrations of HVAC equipment manufacturing driving insulation procurement.
France
Commercial roofing and HVAC ductwork applications face acute specification turbulence as REACH compliance deadlines approach. The country's national building efficiency regulator enforces tightening energy code thresholds for retrofit projects. The Île-de-France region concentrates engineering-procurement-construction firms displacing traditional distributor channels in bundled mechanical upgrades.
Singapore
Hyperscale data center construction is creating specification pull for high-R-value, space-constrained insulation in tropical cooling distribution systems. The tropical climate drives moisture control performance requirements distinct from temperate markets. The island's advanced manufacturing zone hosts regional headquarters for insulation suppliers serving Southeast Asian infrastructure projects.
Flexible Insulation Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material feedstock and intermediate processing. The vendor base stratifies across three tiers: multinational building materials conglomerates with mineral wool and fiberglass infrastructure, chemical majors with polyurethane formulation expertise, and specialized aerogel manufacturers with supercritical drying capabilities. Dominant competitive moves include backward integration into recycled glass feedstock for cost position and capacity expansion in bio-based polyol production to capture sustainability premiums.
Among European-based building materials specialists, Saint-Gobain and Rockwool International exemplify the integrated platform model spanning mineral wool production through distribution channel control. Owens Corning occupies a position representing North American fiberglass concentration with captive supply of high-purity silica feedstock. These three anchors illustrate how geographic feedstock access and regulatory compliance capabilities determine competitive positioning across fragmented national markets.
| Leading Market Players |
|---|
| Saint-Gobain |
| Owens Corning |
| Johns Manville |
| Knauf Insulation |
| Armacell |
| BASF SE |
| Cabot Corporation |
| Rockwool International |
| Kingspan Group |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on Chinese and US Midwest silica sand feedstock determines both the premium-to-economy pricing spread across fiberglass grades and the geographic clustering of rotary fiberization capacity. Buyers face escalating logistics cost volatility as high-purity glass-grade supply concentrates with these dual-source dependencies, compressing margins on standard-density products while insulating premium-tier pricing power.
Pricing Analysis
EPA AIM Act hydrofluorocarbon phase-down rules dictate the pricing tier structure across polyurethane foam systems, separating premium low-GWP formulations from standard HFC-based products facing stranded asset risk. Price differentiation hinges on certification grade for fire safety compliance and geographic delivery cost to data center construction clusters. Cost compression in commodity fiberglass runs through distributor self-service channels as Chinese capacity expansion intensifies competition. Commercial roofing contractors exhibit highest price sensitivity, while aerospace OEMs absorb aerogel premiums without volume negotiation.
Supply Chain Analysis
High-purity silica sand deposits in China and the US Midwest anchor upstream fiberglass production, while plant-derived polyol feedstocks draw from agricultural processing regions in Brazil and Southeast Asia. Raw material dependencies include borosilicate glass cullet, petroleum-derived isocyanates, and supercritical drying solvents for aerogel synthesis. Single-source vulnerability concentrates with Chinese fiberglass mat capacity serving regional construction markets. Distribution runs through engineering-procurement-construction firms displacing traditional distributor channels in bundled mechanical system procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical field support for aerogel and specialized foam systems expands faster than commodity hardware shipments. Recurring specification consulting and fire-testing certification services generate margin pools that product-only vendors cannot access.
For Market Incumbents: Entrench pricing power through backward integration into recycled glass feedstock for fiberglass cost position, while accelerating bio-based polyol production to capture sustainability premiums. Cell-to-pack battery insulation entrants threaten mineral wool dominance in thermal barrier applications. Certification investment in multi-jurisdiction fire testing protocols defends specification control as REACH and GB 8624 deadlines converge. For New Entrants and Emerging Players: Southeast Asian data center construction clusters represent the most penetrable geographic underpenetration for high-R-value foam and aerogel systems. Electric vehicle battery pack insulation offers white-space demand for compressible thermal barriers with dielectric integrity. Partner with regional EPC firms on performance contracting arrangements to bypass established distributor relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors platform integrators with compliance capabilities across REACH, EPA AIM Act, and GB 8624 frameworks. Long-term viability favors conglomerates with captive mineral wool infrastructure and formaldehyde-free binder technology. Watch for inflection in cold chain equipment specifications as EU F-Gas Regulation quotas tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Glass Feedstock | Captive supply of high-purity cullet insulates Owens Corning and Johns Manville from silica sand tariff volatility. |
| Bio-Based Polyol Production Scale-Up | Plant-derived feedstock investments position BASF and Covestro for Scope 3 emissions scorecard compliance. |
| Continuous Aerogel Manufacturing Deployment | Cabot Corporation's supercritical drying automation collapses cost premiums versus multilayer vacuum insulation. |
| Multi-Jurisdiction Fire Certification Investment | Simultaneous EN 13501, ASTM E84, and GB 8624 testing unlocks specification access across German, US, and Chinese construction markets. |
| Performance Contracting Channel Partnership | Engineering-procurement-construction bundling displaces distributor intermediaries in Northern Virginia and Frankfurt data center projects. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC equipment OEM procurement directors, commercial roofing contractor operations managers, EPC firm mechanical system specifiers, and aerogel manufacturing technical leads. Secondary validation drew from EPA refrigerant phase-down filings, ECHA REACH restriction updates, US Department of Energy appliance efficiency standard dockets, and Chinese GB 8624 fire classification regulatory notices. Bottom-up volume modeling triangulated against top-down construction spending and automotive production forecasts.
Calibration against historical specification upgrade cycles and regulatory compliance cost trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, end-use application thermal performance requirement, fire safety certification grade, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating energy code tightening schedules and federal incentive program windows. Electric vehicle battery pack content-per-vehicle assumptions and data center cooling distribution insulation intensity informed automotive and HVAC segment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese fiberglass capacity expanders or bio-based polyol specialists would shift outcomes beyond modeled ranges. Cross-checking against construction material customs trade flows and automotive OEM thermal management procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market