
 Global PVC Foam Sheet Market | 2026-2036
Global PVC Foam Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Global PVC Foam Sheet Market Intelligence
Market Context with Strategic Players
Buyer concentration among building and construction firms is expanding as large-scale contractors consolidate procurement for interior fit-out and insulation packages. Palram Industries leverages extrusion scale across multiple continents to serve these consolidated buyers with consistent lead times. 3A Composites differentiates through specialized substrate solutions for signage and display applications. Röchling Group anchors industrial demand with engineering-grade formulations for automotive and marine end uses.
Technical Definition and Structural Segments
PVC foam sheet is a closed-cell thermoplastic material produced through controlled expansion of polyvinyl chloride resin, yielding densities from 0.35 to 0.9 g/cm³ that deliver high stiffness-to-weight ratios for structural and decorative applications. Rigid PVC foam dominates current volume owing to its established use in construction insulation and exterior cladding systems where dimensional stability under thermal cycling matters most. Flexible PVC foam captures faster expansion in marine interiors and furniture manufacturing, where conformability to complex geometries commands premium positioning. Cross-linked PVC foam occupies a specialized tier in automotive components, where elevated service temperatures and chemical resistance justify higher formulation costs.
Regulatory Frame and Forward-Looking Close
REACH in the European Union, EPA standards in the United States, and GB standards under China's SAMR collectively restrict phthalate plasticizers and mandate flame-retardant performance in enclosed-space applications. These frameworks compel reformulation investments that favor producers with captive R&D and testing infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment supply chains into incompatible regional product lines.
Market Dynamics
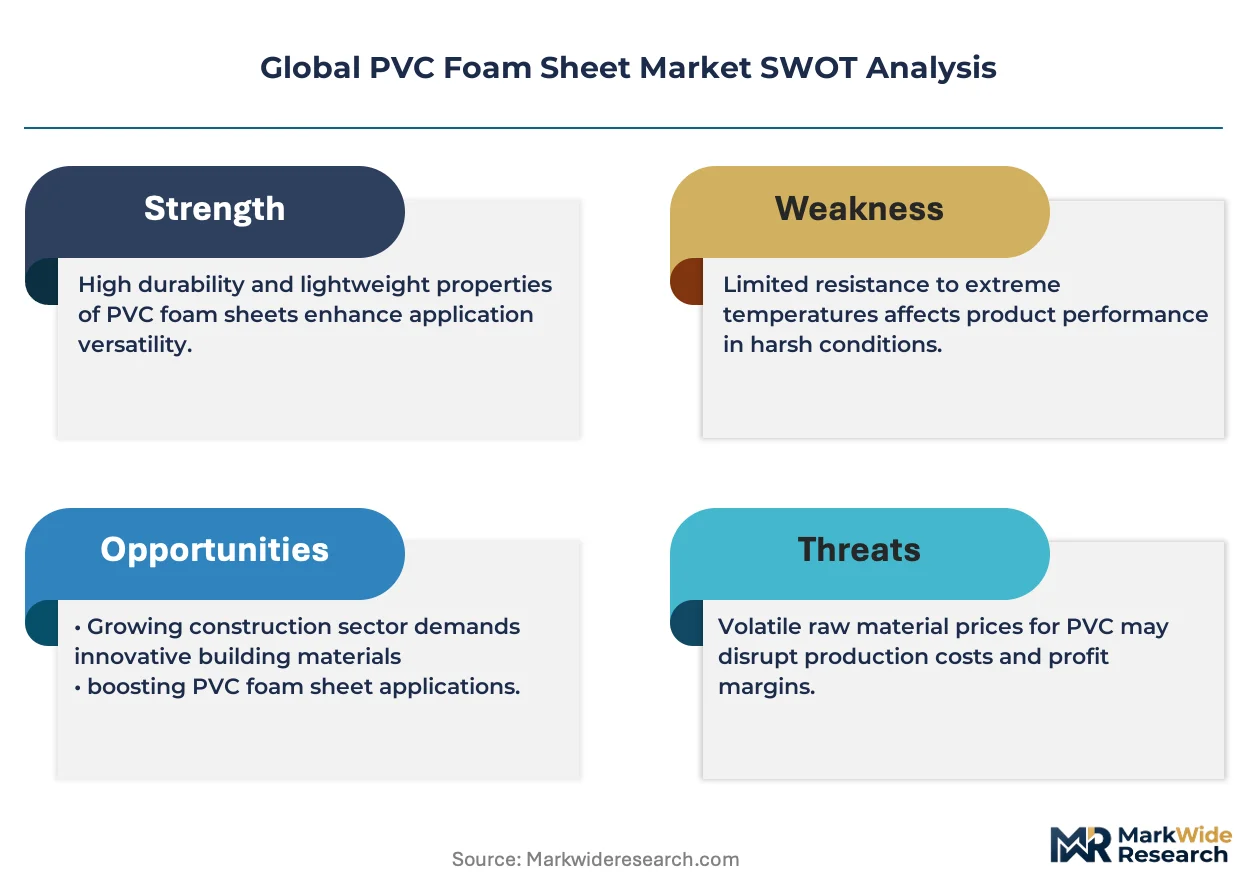
REACH compliance deadlines in the European Union and evolving EPA flame-retardant standards in the United States are forcing simultaneous reformulation across rigid and flexible PVC foam grades, compressing product development cycles and favoring producers with captive testing infrastructure.
Growth Catalysts
- Commercial building retrofit mandates:Energy efficiency codes in Germany and France are accelerating insulation board specifications in facade renovation projects, pulling volume toward higher-density rigid formulations.
- REACH Article 33 disclosure requirements:Supply chain transparency obligations are consolidating procurement among contractors who demand certified material passports, favoring established extruders with documentation systems.
- Marine interior fabrication clusters:Yacht builders in the Netherlands and Italy are specifying cross-linked PVC foam for lightweight cabinetry and bulkhead panels, creating premium demand pockets.
Market Restraints
- Chlor-alkali feedstock volatility:PVC resin costs fluctuate with chlorine and ethylene pricing, squeezing margin predictability for sheet extruders without backward integration into vinyl compound production.
- Phthalate plasticizer restrictions:ECHA's expanding SVHC candidate list limits formulation flexibility in flexible foam grades, forcing R&D redirection toward bio-based alternatives with unproven scale economics.
- Polypropylene honeycomb substitution:Automotive panel suppliers in Japan and South Korea are trialing thermoplastic composite cores that match PVC foam stiffness at lower weight, threatening marine and transport applications.
Strategic Opportunities
- India's PLI scheme for construction chemicals:Domestic manufacturing incentives are attracting extrusion investment to serve infrastructure build-out in Maharashtra and Gujarat, bypassing import duty exposure.
- Digital printing substrate convergence:UV-curable ink adhesion improvements on foamed PVC are capturing share from traditional foamboard in retail display applications across North American and European markets.
- China's dual carbon goals:Provincial energy intensity targets in Shandong and Jiangsu are accelerating low-emission extrusion line upgrades, creating technology export opportunities for equipment suppliers.
Industry Challenges
- Flame-retardant certification timelines:UL 94 and EN 13501-1 testing backlogs extend product qualification cycles, delaying contract awards for speculative building projects.
- Skilled extrusion technician scarcity:Aging workforce demographics in Germany and the United States constrain output scaling at mid-cap producers competing for experienced die designers and process engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PVC Foam Sheet Market |
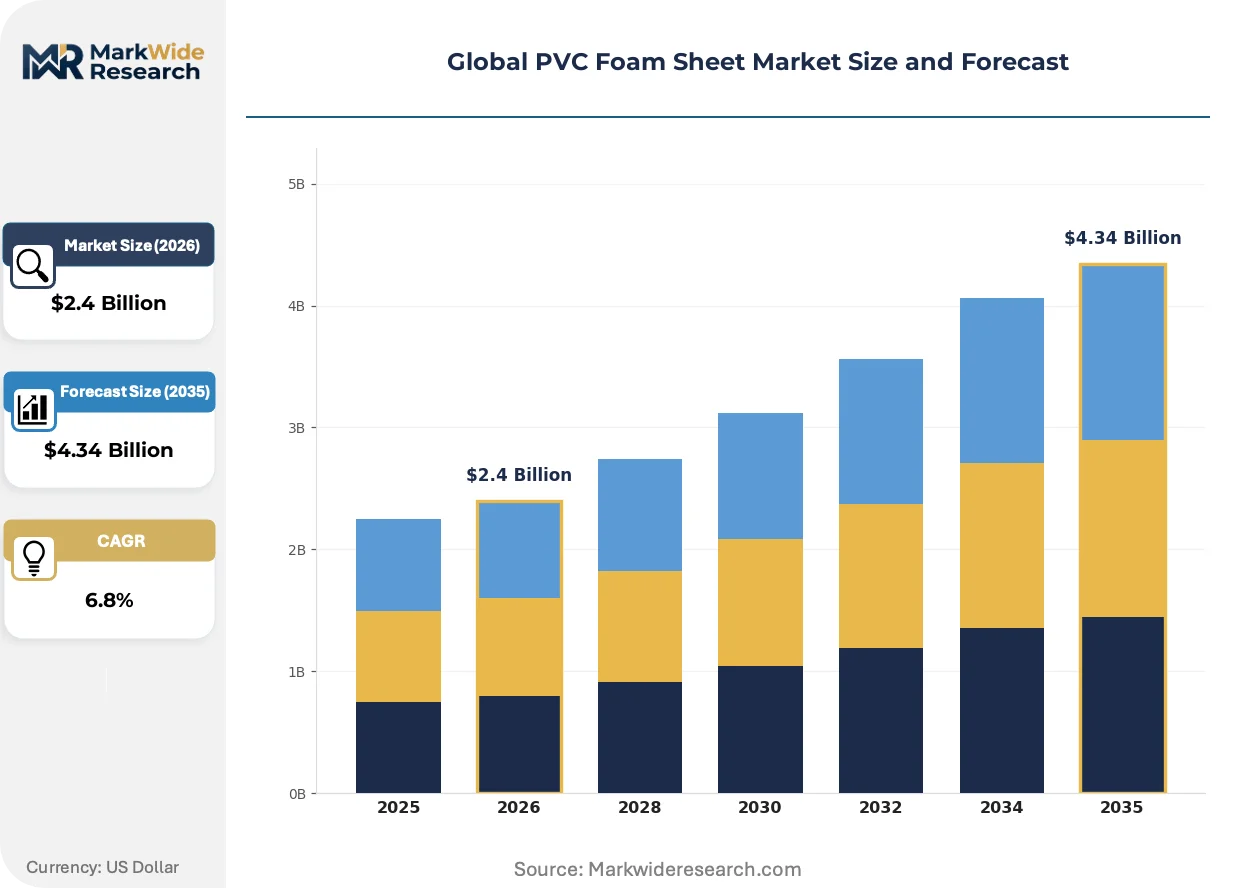
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC Foam, Rigid PVC Foam, Semi-Rigid PVC Foam, Cross-Linked PVC Foam Application: Construction Insulation, Signage & Display, Automotive Components, Marine Interiors, Furniture Manufacturing End User Industry: Building & Construction Firms, Vehicle Manufacturers, Marine Equipment Suppliers, Furniture Producers Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Wholesale Traders |
| Companies Covered | Palram Industries, Sealed Air Corporation, 3A Composites, Sika AG, Röchling Group, Armacell International, Simona AG, Benecke-Kaliko AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PVC Foam Sheet Market Strategic Shifts & Innovations
Digital manufacturing integration and regulatory chemistry restrictions are compressing traditional formulation-development timelines while opening white space in bio-based and recycled-content grades. Material suppliers must now synchronize R&D with compliance documentation systems.
Co-extruded surface layers with enhanced UV stability are integrating into rigid PVC foam sheet production, enabling direct exterior cladding applications without secondary lamination. Construction contractors in Australia and Spain are specifying these grades for rainscreen systems, compressing installation labor costs and reducing field failure rates from delamination.
EPA Significant New Use Rules on halogenated flame retardants are forcing reformulation investments across North American building product lines. Sheet producers are responding with phosphorus-nitrogen systems that maintain UL 94 V-0 ratings while satisfying emerging LEED v4.1 material health criteria, particularly affecting high-rise insulation specifications in California and New York.
Consolidated procurement among multinational fit-out contractors is compressing supplier qualification cycles and unbundling technical service from material supply. Distributors in the United Kingdom and Netherlands are responding with specification-support teams that bridge fabricator knowledge gaps, capturing margin that previously accrued to manufacturer direct sales forces.
Global PVC Foam Sheet Market Segmentation
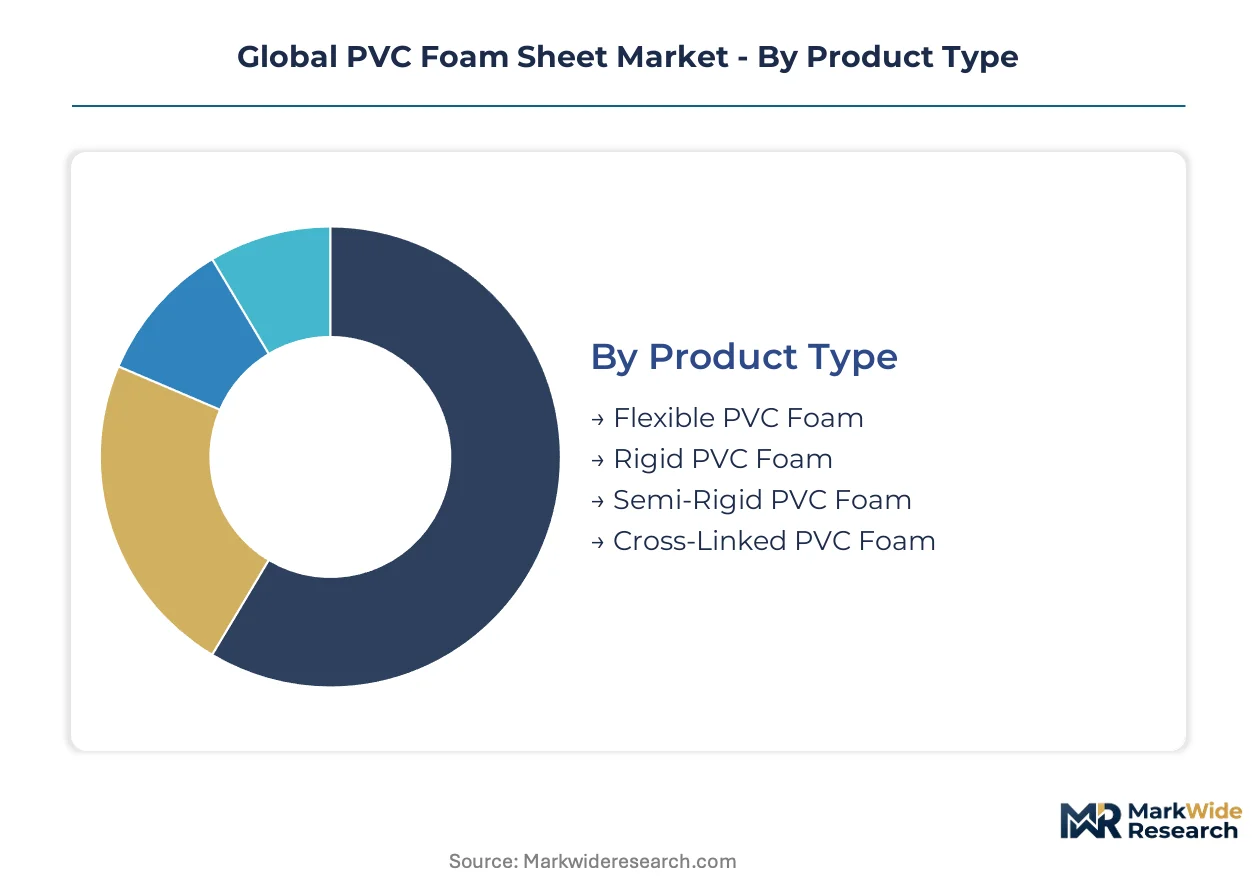
Segmentation in PVC foam sheet markets reveals how capital allocation and technical specialization concentrate competitive advantage. Producers align extrusion infrastructure with specific density grades and surface finish requirements, creating distinct margin profiles across product categories.
Product Type:
Capital intensity varies sharply across formulation chemistries, with cross-linked grades demanding specialized curing equipment and extended quality validation cycles.
- Rigid PVC Foam:High-density closed-cell structure (0.5-0.9 g/cm³) delivers dimensional stability under thermal cycling. Demand concentrates in German and French facade renovation projects where energy efficiency codes mandate insulation board specifications. REACH Article 33 disclosure requirements favor established extruders with certified material passport systems.
- Flexible PVC Foam:Lower-density open-cell formulation (0.35-0.5 g/cm³) enables conformability to complex geometries. Yacht builders in the Netherlands and Italy specify these grades for lightweight cabinetry and bulkhead panels, creating premium positioning in marine fabrication clusters.
- Semi-Rigid PVC Foam:Intermediate density range balances stiffness with limited flexural capacity for furniture manufacturing in Poland and Vietnam.
- Cross-Linked PVC Foam:Thermoset molecular structure withstands elevated service temperatures and chemical exposure for automotive underhood components.
Most installed capacity flows through rigid formulations. Expansion is steepest in cross-linked grades serving automotive thermal management applications.
Application:
Application segmentation tracks how end-use performance requirements dictate formulation investment priorities and certification burdens.
- Construction Insulation:Rigid boards specified for commercial building retrofits in Germany, France, and Australia deliver thermal resistance values meeting stringent energy codes. Australian contractors specify co-extruded UV-stable grades for rainscreen systems, eliminating secondary lamination steps and reducing field failure rates from delamination.
- Signage & Display:Smooth surface finish and consistent cell structure enable UV-curable ink adhesion for retail environments. North American and European markets show accelerating substitution of traditional foamboard as digital printing substrate convergence captures share in point-of-purchase displays.
- Automotive Components:Cross-linked grades for interior panels and underhood insulation face substitution pressure from polypropylene honeycomb cores trialed by Japanese and South Korean suppliers.
- Marine Interiors:Moisture-resistant formulations serve yacht and commercial vessel fabrication in Italian and Dutch shipyards.
- Furniture Manufacturing:Semi-rigid and flexible grades supply upholstered frame components and edge banding in Vietnamese and Polish production clusters.
Construction insulation commands the largest equipment footprint. Signage and display applications are climbing the fastest as digital printing technology advances.
End User Industry:
Customer concentration patterns determine contract structure, with consolidated procurement among multinational contractors compressing supplier qualification timelines.
- Building & Construction Firms:Large-scale contractors in Germany and the United States consolidate procurement for interior fit-out and insulation packages, demanding consistent lead times and certified compliance documentation. Procurement consolidation favors extruders with multi-continent production scale.
- Vehicle Manufacturers:Automotive OEMs in Japan and South Korea drive cross-linked foam specifications for lightweighting initiatives, though polypropylene honeycomb substitution trials threaten volume retention.
- Marine Equipment Suppliers:Yacht builders and commercial vessel outfitters in the Netherlands and Italy specify premium grades with complex geometry conformance.
- Furniture Producers:Manufacturing clusters in Vietnam and Poland absorb semi-rigid and flexible formulations for frame components and upholstery substrates.
Building and construction firms anchor procurement volume. Vehicle manufacturers are gaining share fastest as electrification intensifies lightweighting priorities.
Distribution Channel:
Channel structure reflects technical service requirements and the unbundling of specification support from pure material supply.
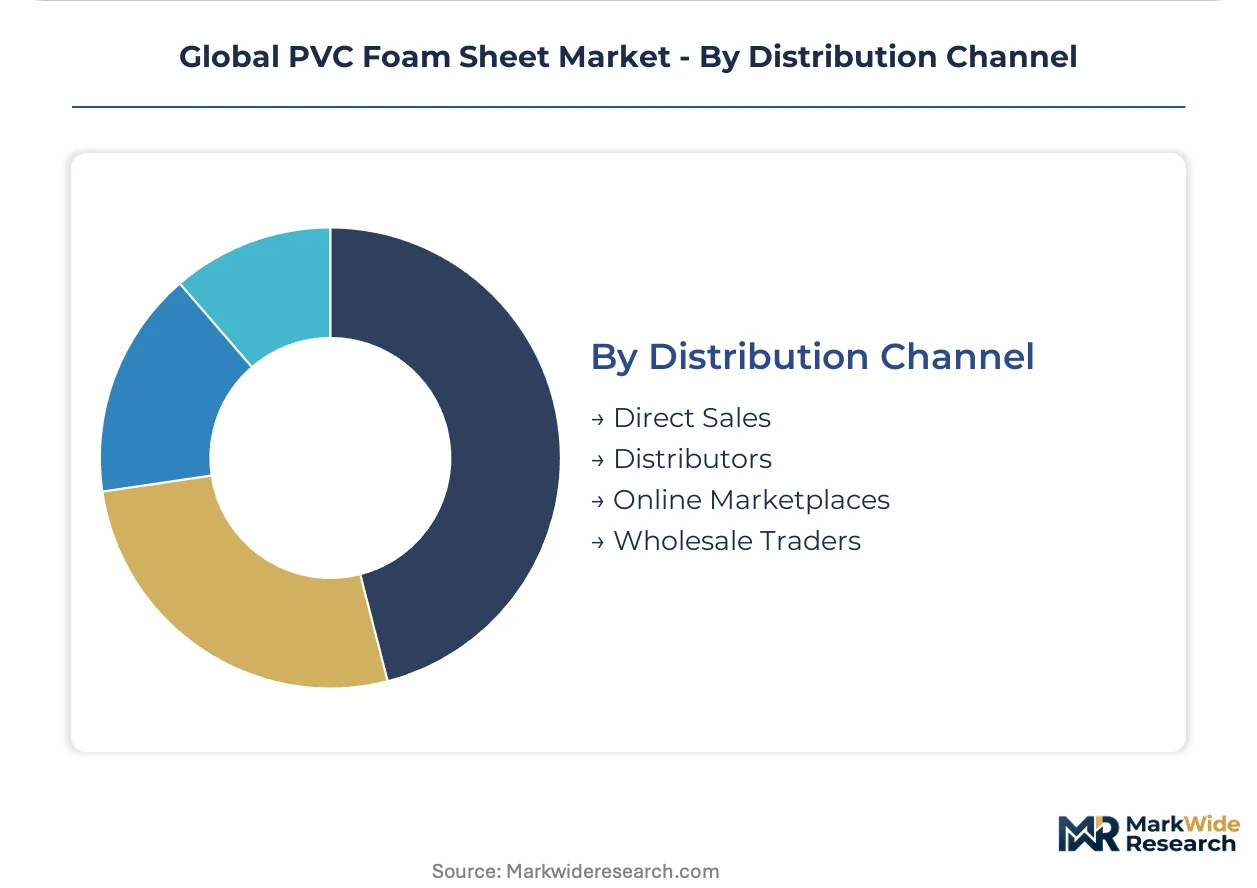
- Distributors:Specification-support teams in the United Kingdom and Netherlands bridge fabricator knowledge gaps, capturing margin previously accruing to manufacturer direct sales forces. Distributors invest in technical staff to serve consolidated contractor procurement.
- Direct Sales:Large-volume contracts with multinational fit-out firms bypass intermediary margin, requiring captive logistics and inventory positioning.
- Online Marketplaces:Standard grades for small-batch signage and display applications flow through digital procurement platforms serving North American and European small fabricators.
- Wholesale Traders:Bulk volume movements across Asian manufacturing corridors serve downstream fabrication clusters with minimal technical service overlay.
Distributors hold the deepest technical service infrastructure. Online marketplaces are expanding most quickly for standardized grades in small-lot applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled extrusion technicians in Germany's Ruhr Valley and China's Shandong province anchor the industry's technical workforce, concentrating formulation expertise in corridors where downstream fabrication clusters absorb bulk supply.
Germany
Energy efficiency retrofits in Berlin and Hamburg drive rigid foam specifications for facade insulation boards. REACH Article 33 disclosure requirements favor established extruders with certified material passport systems. The Ruhr Valley hosts concentrated extrusion capacity serving Benelux and French renovation contractors.
United States
Commercial building retrofit mandates in California and New York accelerate high-density rigid foam adoption for thermal envelopes. EPA Significant New Use Rules on halogenated flame retardants force phosphorus-nitrogen reformulation investments. Midwestern extrusion plants supply consolidated national contractors with consistent lead times.
China
Provincial energy intensity targets in Shandong and Jiangsu accelerate low-emission extrusion line upgrades. SAMR-administered GB standards restrict phthalate plasticizers in flexible grades. The eastern manufacturing corridor downstream from Shanghai absorbs bulk supply for signage and display fabrication clusters.
Netherlands
Yacht builders in Amsterdam and Rotterdam specify cross-linked PVC foam for lightweight cabinetry and bulkhead panels. ECHA's expanding SVHC candidate list limits formulation flexibility in marine interior grades. Dutch distributors invest in specification-support teams bridging fabricator knowledge gaps.
India
Infrastructure build-out in Maharashtra and Gujarat attracts extrusion investment under the PLI scheme for construction chemicals. Domestic manufacturing incentives bypass import duty exposure for rigid insulation boards. Mumbai-Pune fabrication clusters absorb regional supply for commercial interior fit-out projects.
Global PVC Foam Sheet Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where captive R&D infrastructure separates premium-positioned producers from commodity extruders. The vendor base spans three strategic archetypes: multi-continent extrusion scale players, specialized substrate solution providers, and engineering-grade formulation specialists. Dominant competitive moves include backward integration into vinyl compound production and geographic expansion through distributor technical service investments.
Among diversified chemical conglomerates, BASF SE and Sika AG exemplify scale-driven archetypes with captive supply chain control over resin and additive inputs. Palram Industries represents the focused extrusion specialist model with multi-continent production footprint. These three anchors illustrate how competitive positioning stratifies between upstream-integrated conglomerates and downstream-specialized fabricators.
| Leading Market Players |
|---|
| Palram Industries |
| Sealed Air Corporation |
| 3A Composites |
| Sika AG |
| Röchling Group |
| Armacell International |
| Simona AG |
| Benecke-Kaliko AG |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Consolidated procurement among multinational building contractors is forcing extruders to absorb certification documentation costs into base pricing, compressing margins for mid-cap producers without captive R&D infrastructure while rewarding scale players with backward integration into vinyl compound production.
Pricing Analysis
Capacity additions in China's Shandong and Jiangsu provinces are reshaping price floors for standard-density rigid grades. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified material passport holders from commodity extruders. Price differentiation hinges on flame-retardant certification tier and volume scale commitments. Pricing pressure stems from chlor-alkali feedstock volatility squeezing non-integrated producers. Small-batch signage fabricators exhibit highest price sensitivity, while marine yacht builders accept premium positioning for complex geometry conformance.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr Valley and China's eastern manufacturing corridor operate hub-and-spoke patterns serving downstream fabrication clusters. Supply concentrates in Germany, China, and the United States, with India emerging under PLI scheme incentives. Raw material dependencies rest on chlorine-alkali capacity, ethylene feedstock, and specialized flame-retardant additives. Single-source vulnerability around phthalate-free plasticizer alternatives poses structural risk. Distribution runs through specification-support distributors in the Netherlands and United Kingdom bridging fabricator technical knowledge gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in the European Union exceed India's PLI scheme subsidies by a structural margin, rewarding extrusion investment in Maharashtra and Gujarat to serve regional infrastructure build-out.
For Market Incumbents: Deepen backward integration into vinyl compound production to insulate margin from chlor-alkali volatility. Expand captive testing infrastructure to compress UL 94 and EN 13501-1 certification timelines. Polypropylene honeycomb substitution trials by Japanese automotive suppliers threaten cross-linked foam volumes in transport applications.
For New Entrants and Emerging Players: Capture India's construction chemicals PLI scheme incentives to establish domestic rigid insulation board capacity bypassing import duty exposure. Target Maharashtra and Gujarat fabrication clusters with technical service investments. Partner with specification-support distributors to bridge fabricator knowledge gaps without building direct sales infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap extruders possessing REACH-certified material passport systems and multi-continent production scale. Long-term viability centers on producers with captive R&D infrastructure navigating regulatory divergence between jurisdictions. Watch for ECHA SVHC candidate list expansions as inflection indicators forcing reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Compound Production | Captive supply of PVC resin insulates margin from chlorine-alkali volatility affecting German and Chinese extruders. |
| Low-Emission Extrusion Line Upgrades | Shandong and Jiangsu provincial energy intensity targets create technology export opportunities for equipment suppliers. |
| Specification-Support Distributor Investments | UK and Netherlands technical teams capture margin previously accruing to manufacturer direct sales forces. |
| Phosphorus-Nitrogen Flame Retardant Reformulation | EPA Significant New Use Rules on halogenated systems force R&D redirection maintaining UL 94 V-0 ratings. |
| Regional Distribution Center Expansion | Hub-and-spoke logistics in Ruhr Valley and eastern China compress lead times for consolidated contractor procurement. |
Research Approach
Bottom-up construction insulation modeling reconciled against top-down extrusion capacity tracking forms the analytical core. Primary interviews with plant managers at sheet extrusion facilities, procurement leads at building contractors, distribution channel partners, and technical R&D directors informed demand-side validation. Secondary sources included customs and trade flow data, SEC 10-K filings of diversified chemical conglomerates, ECHA REACH registration databases, and SAMR GB standard documentation. Triangulation between stakeholder interview insights and published regulatory filings anchored volume estimates.
Input-output matrices mapped PVC resin consumption through density-grade extrusion lines to end-use applications across the projection horizon. Segmentation dimensions modeled include product type tier, application vertical, end-user industry concentration, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates cross-referenced with energy efficiency retrofit mandate timelines. Forecast inputs incorporated chlor-alkali feedstock pricing trajectories and flame-retardant certification backlog durations.
Feedstock volatility, regulatory divergence between REACH and EPA frameworks, and polypropylene honeycomb substitution traction are the dominant revision risks. Forecasts reflect documented assumptions around compliance timeline adherence and infrastructure investment realization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Technical Foam Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market