
 North America Phase Change Materials Market | 2026-2036
North America Phase Change Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Phase Change Materials Market Insights
North American specialty chemical producers is consolidating around advanced thermal management capabilities. Honeywell International Inc. leverages its fluorocarbon expertise to dominate high-performance PCM formulations for aerospace and electronics cooling. DuPont de Nemours, Inc. sustains polymer science leadership through proprietary microencapsulation platforms that extend material cycle life. Croda International Plc anchors bio-based PCM development, positioning its vegetable-derived paraffin alternatives to capture sustainability-driven procurement shifts.
Phase change materials are substances that absorb and release latent heat at nearly constant temperature during solid-liquid transitions, typically formulated with melting points between minus ten and eighty degrees Celsius for commercial thermal buffering applications. Organic PCM, particularly paraffin-based formulations, currently leads volume shipments due to established manufacturing infrastructure and predictable thermal cycling behavior. Bio-based PCM represents the fastest-expanding product category as polymer blends technology matures and brand owners in textiles and packaging prioritize renewable feedstock credentials. Microencapsulation dominates technology selection for building and construction end users, where shell integrity determines decades-long performance in wallboard and concrete admixtures.
The US Department of Energy enforces Federal Energy Management Program standards that directly specify PCM performance thresholds for government building retrofits, while EPA refrigerant phase-down rules under the AIM Act indirectly boost solid-state PCM alternatives in commercial refrigeration. Health Canada and PMRA evaluate PCM chemistries for food-contact and pharmaceutical cold-chain applications, creating dual-jurisdiction compliance requirements for cross-border suppliers. Stakeholders must monitor evolving state-level building codes in California and New York, where thermal storage mandates are tightening faster than federal baselines and will determine regional procurement specifications.
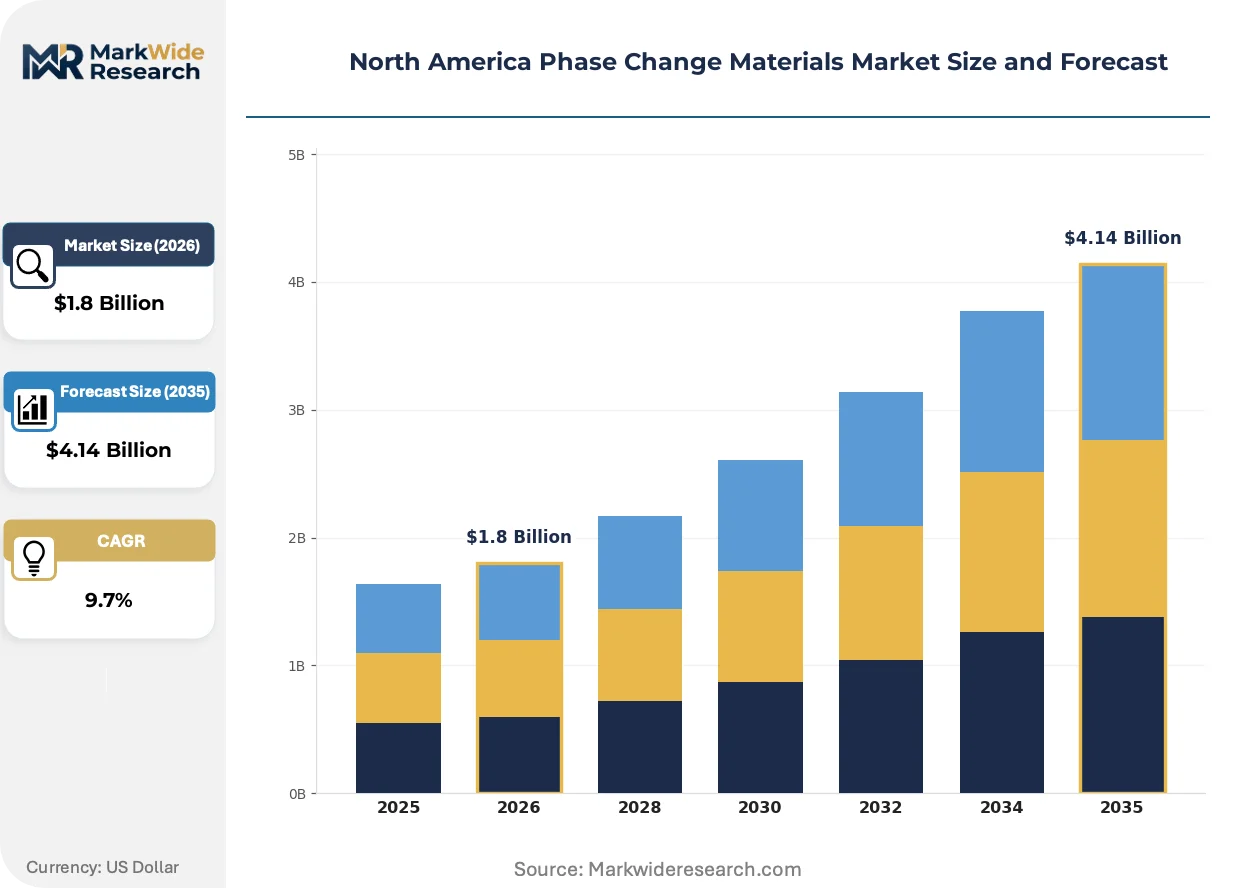
Market Dynamics
Federal retrofit mandates and AIM Act refrigerant phase-downs are compressing adoption timelines for solid-state thermal storage across US building and cold-chain infrastructure. Supply concentration around fluorocarbon and bio-based formulation expertise is reshaping competitive access to high-performance grades.
Growth Catalysts
- AIM Act Implementation:EPA refrigerant phase-down rules accelerate solid-state PCM substitution in commercial refrigeration systems across US food retail and pharmaceutical distribution.
- Building Envelope Codes:US Department of Energy Federal Energy Management Program standards mandate PCM performance thresholds for government building retrofits, locking in specification demand.
- Cold-Chain Expansion:Temperature-sensitive biologics distribution growth drives PCM adoption for pharmaceutical transport from Northeast US manufacturing clusters to distribution hubs.
Market Restraints
- Petrochemical Feedstock Volatility:Paraffin wax price swings tied to crude oil markets compress margin predictability for organic PCM producers serving building materials customers.
- Microencapsulation Concentration:Shell integrity technology for decades-long building performance remains concentrated among polymer science specialists, limiting supplier base breadth.
- Cross-Border Compliance Friction:Dual Health Canada and PMRA evaluation requirements for food-contact and pharmaceutical cold-chain applications extend product registration timelines for US suppliers.
Strategic Opportunities
- California and New York Code Acceleration:State-level thermal storage mandates tightening faster than federal baselines create premium specification tiers for high-performance envelope materials.
- Bio-Based Formulation White Space:Vegetable-derived paraffin alternatives capture sustainability-driven procurement shifts in textiles and packaging as polymer blend technology matures.
- Electronics Cooling Convergence:Thermal interface material integration with PCM layers opens aerospace and data center segments requiring precise temperature buffering.
Industry Challenges
- Retrofit Installation Skill Gaps:Wallboard and concrete admixture PCM deployment requires specialized contractor training that lags behind specification volume in aging US Northeast building stock.
- Decades-Long Performance Certification:Microencapsulation shell integrity testing protocols extend validation timelines, compressing product development cycles against tightening code deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Phase Change Materials Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic PCM, Inorganic PCM, Bio-based PCM, Salt Hydrates End User: Building & Construction, Automotive, Electronics, Textiles Application: Energy Storage, Thermal Management, Temperature Control, Refrigeration Technology: Microencapsulation, Polymer Blends, Composite Materials, Innovative Formulations |
| Companies Covered | Honeywell International Inc., DuPont de Nemours, Inc., Croda International Plc, Phase Change Energy Solutions, Entropy Solutions LLC, Microtek Laboratories, Inc., BASF Corporation, Henkel Corporation, PureTemp LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Phase Change Materials Market Trends and Innovations
Formulation chemistry, encapsulation architecture, and procurement specifications are converging to redefine performance benchmarks and supplier qualification criteria across North American thermal management applications.
Microencapsulation shell engineering is automating quality assurance in building-grade PCM production. Shell integrity monitoring systems now embed real-time thermal cycling validation into continuous manufacturing lines. US wallboard and concrete admixture producers are adopting these platforms to compress decades-long performance certification timelines. The technology is automating supplier qualification protocols that previously required extended field testing.
AIM Act refrigerant regulations are forcing cold-chain equipment redesign across US pharmaceutical and food retail sectors. Solid-state PCM alternatives displace vapor-compression systems in last-mile delivery vehicles and stationary storage units. Commercial refrigeration OEMs in the Midwest and Southeast US are accelerating PCM integration roadmaps to maintain EPA compliance without performance degradation.
Buyers in pharmaceutical cold-chain logistics are consolidating supplier relationships around dual-jurisdiction certification capability. Health Canada and PMRA compliance is becoming a non-negotiable qualifier for cross-border contract awards, displacing single-market suppliers. This concentration is most visible in Northeast US to Ontario/Quebec distribution corridors serving temperature-sensitive biologics manufacturers.
North America Phase Change Materials Market Segmentation
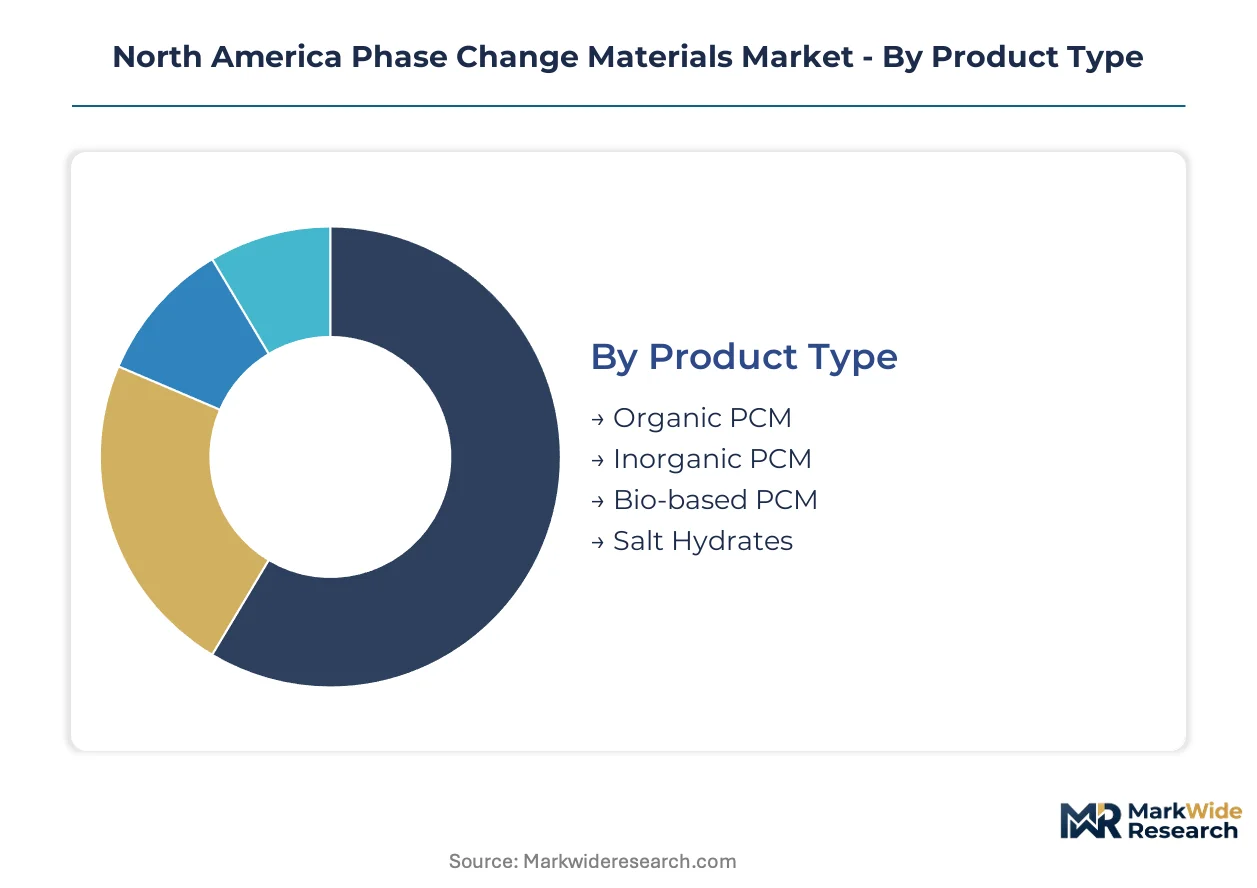
PCM segmentation in North America reveals distinct capital requirements and technical barriers that shape supplier positioning. Formulation chemistry, encapsulation architecture, and end-use thermal specifications determine which segments reward scale economies versus specialized expertise.
Product Type:
Capital intensity varies sharply across formulation platforms, with encapsulation infrastructure and feedstock processing driving divergent investment thresholds.
- Organic PCM:Paraffin-based formulations dominate commercial volumes through established petroleum refining integration. US Gulf Coast petrochemical corridors supply feedstock at scale, though crude-linked price volatility compresses margin predictability for Northeast building materials customers.
- Bio-based PCM:Vegetable-derived paraffin alternatives command premium positioning as polymer blend technology matures. Procurement shifts in textiles and packaging favor renewable credentials, with Croda International Plc and specialty chemical producers consolidating around fermentation and hydrogenation capabilities.
- Inorganic PCM:Salt hydrate formulations require controlled nucleation engineering to prevent phase separation during thermal cycling.
- Salt Hydrates:Low-cost mineral feedstocks attract price-sensitive refrigeration applications despite corrosion compatibility challenges.
Organic PCM absorbs the bulk of installed capacity; bio-based PCM is expanding most quickly.
End User:
Application maturity determines customer concentration, with decades-old building codes creating specification lock-in versus emerging electronics demand.
- Building & Construction:Wallboard and concrete admixture integration commands the longest validation timelines. US Department of Energy Federal Energy Management Program standards mandate PCM performance thresholds for government retrofits, locking in specification demand across aging Northeast corridor building stock.
- Electronics:Thermal interface material convergence with PCM layers opens aerospace and data center segments. Honeywell International Inc. leverages fluorocarbon expertise for precise temperature buffering in high-reliability applications.
- Automotive:Battery thermal management and cabin comfort systems drive OEM specification development.
- Textiles:Apparel and technical fabric producers prioritize bio-based credentials for sustainability-driven procurement.
Building & Construction holds the deepest specification entrenchment; Electronics demonstrates the steepest expansion trajectory.
Application:
Functional requirements segment the market by thermal precision demands and duty cycle intensity.
- Energy Storage:Grid-scale and building-integrated thermal storage systems require decades-long performance certification. Microencapsulation shell integrity testing protocols extend validation timelines, compressing product development cycles against tightening code deadlines.
- Thermal Management:Electronics cooling and automotive battery applications demand narrow temperature bandwidths. DuPont de Nemours, Inc. sustains leadership through proprietary microencapsulation platforms that extend material cycle life under aggressive thermal cycling.
- Temperature Control:Pharmaceutical cold-chain logistics concentrates demand around dual-jurisdiction certification capability.
- Refrigeration:AIM Act refrigerant phase-downs accelerate solid-state PCM substitution in commercial systems.
Energy Storage anchors capital deployment; Thermal Management is gaining share fastest.
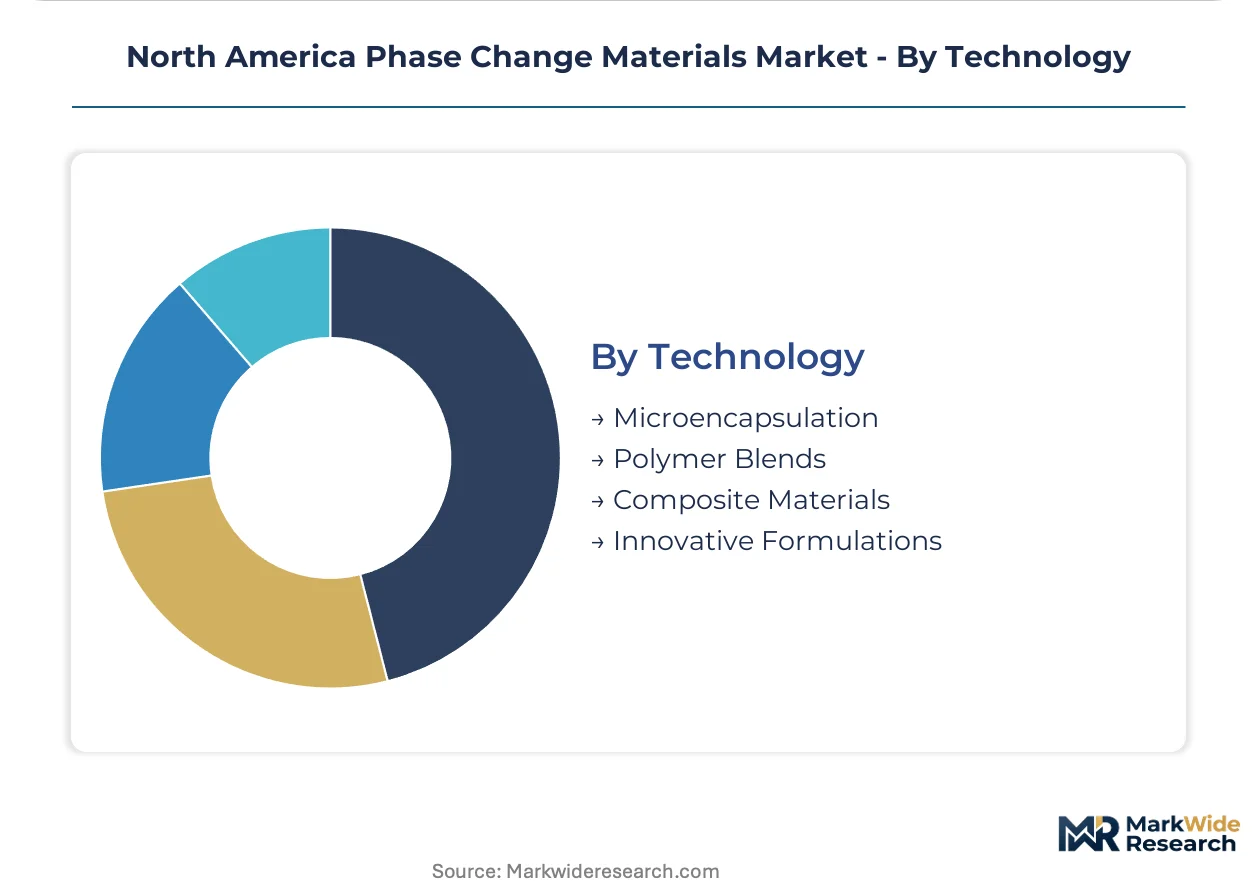
Technology:
Process sophistication creates tiered supplier access, with shell engineering and continuous manufacturing separating qualified producers from commodity competitors.
- Microencapsulation:Shell integrity monitoring systems now embed real-time thermal cycling validation into continuous manufacturing lines. US wallboard and concrete admixture producers adopt these platforms to compress decades-long performance certification timelines previously requiring extended field testing.
- Polymer Blends:Bio-based PCM development centers on vegetable oil hydrogenation and copolymer architecture. Croda International Plc anchors this segment, positioning renewable feedstock alternatives to capture sustainability-driven procurement shifts.
- Composite Materials:Matrix-PCM integration serves structural thermal management in automotive and aerospace applications.
- Innovative Formulations:Eutectic mixtures and shape-stabilized configurations address emerging performance specifications.
Microencapsulation commands the highest technical barriers; Polymer Blends shows the most rapid capability accumulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical corridors along the US Gulf Coast supply paraffin feedstock that underpins organic PCM manufacturing across the continent. Canadian oil sands operations and Mexican petrochemical infrastructure provide complementary feedstock streams. Regional demand concentrates in temperature-sensitive logistics networks and aging building stock requiring thermal retrofit.
United States
Cold-chain pharmaceutical distribution from Northeast manufacturing clusters drives PCM specification for temperature-controlled transport. EPA AIM Act refrigerant phase-down rules accelerate solid-state thermal storage adoption in commercial refrigeration systems. Boston and New York Metro corridor building retrofits concentrate microencapsulated wallboard demand under Federal Energy Management Program mandates.
Canada
Cross-border biologics distribution to Ontario and Quebec requires dual-jurisdiction certified PCM packaging systems. Health Canada and PMRA evaluation requirements for food-contact applications extend product registration timelines for US suppliers. Toronto and Montreal pharmaceutical manufacturing hubs anchor temperature-sensitive logistics demand across the Great Lakes corridor.
Mexico
Nearshoring expansion in automotive and electronics assembly creates thermal management demand for battery and component cooling applications. Mexican federal energy efficiency codes for commercial buildings remain less stringent than US counterparts but are tightening. Monterrey and Mexico City industrial corridors concentrate manufacturing investment requiring process temperature control systems.
North America Phase Change Materials Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and encapsulation technology dimensions. The vendor base separates into three tiers: integrated petrochemical conglomerates with backward feedstock control, specialty chemical houses with proprietary polymer science platforms, and application-focused compounders serving niche thermal specifications. Market structure rewards fluorocarbon expertise for aerospace-grade performance and bio-based hydrogenation capabilities for sustainability credentials. Consolidation pressure concentrates around microencapsulation shell integrity technology and cross-border regulatory certification capacity.
Within the integrated chemical conglomerate tier, Honeywell International Inc., DuPont de Nemours, Inc., and Croda International Plc exemplify divergent strategic positioning. Honeywell represents fluorocarbon-based high-performance thermal management, DuPont anchors polymer science and microencapsulation platforms, and Croda occupies the bio-based formulation vector with vegetable-derived feedstock alternatives. These three entities sit at the intersection of petrochemical scale, specialty chemical innovation, and renewable chemistry transition.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| DuPont de Nemours, Inc. |
| Croda International Plc |
| Phase Change Energy Solutions |
| Entropy Solutions LLC |
| Microtek Laboratories, Inc. |
| BASF Corporation |
| Henkel Corporation |
| PureTemp LLC |
| Others |
Pricing and Supply Chain Analysis
AIM Act refrigerant phase-down mandates gate qualified supply access and premium-tier pricing power for solid-state thermal storage alternatives across US commercial refrigeration and cold-chain logistics. Suppliers bearing dual EPA certification and Health Canada PMRA compliance command pricing premiums, while uncertified competitors face exclusion from cross-border pharmaceutical distribution contracts.
Pricing Analysis
Decades-long performance warranty bundling separates premium microencapsulated PCM suppliers from unbundled commodity paraffin vendors. Three-tier pricing structure across certified-premium, standard-grade, and economy-unencapsulated levels tracks shell integrity testing depth and thermal cycling validation rigor. Price differentiation hinges on Federal Energy Management Program specification compliance and Health Canada dual-jurisdiction certification status. Cost compression in organic paraffin feedstock tiers is intensifying because crude-linked volatility compresses margin predictability for Gulf Coast petrochemical suppliers serving Northeast building retrofit contractors.
Supply Chain Analysis
Paraffin wax feedstock rests on US Gulf Coast petroleum refining corridors, Canadian oil sands bitumen processing, and Mexican petrochemical infrastructure integration. Specialty chemical producers draw from fluorocarbon intermediates, vegetable oil hydrogenation platforms, and salt hydrate mineral feedstocks. Single-source vulnerability concentrates around microencapsulation shell integrity technology held by polymer science specialists. Distribution runs through building materials distributors, cold-chain packaging OEMs, and direct pharmaceutical logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
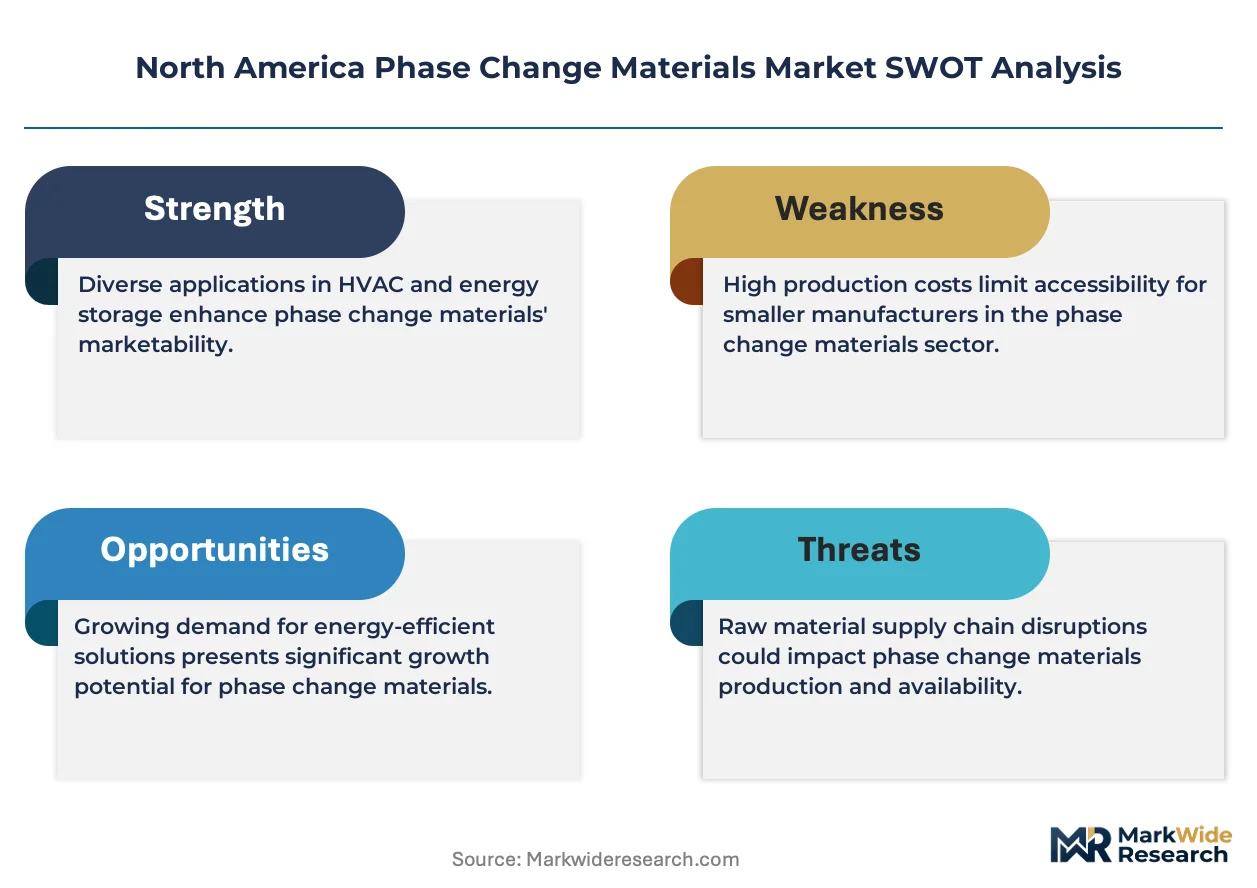
This market functions as a consolidation play where microencapsulation shell engineering expertise and cross-border regulatory certification capacity force weaker, undifferentiated paraffin compounders toward exit or acquisition.
For Market Incumbents: Anticipate bio-based formulation entrants attacking sustainability-driven procurement segments by accelerating proprietary polymer blend R&D and securing backward integration into vegetable oil hydrogenation capacity. Lock in Health Canada PMRA dual-certification ahead of tightening cross-border pharmaceutical logistics mandates to defend specification access in Northeast US to Ontario/Quebec distribution corridors. For New Entrants and Emerging Players: Mid-size pharmaceutical logistics providers lacking dual-jurisdiction certified packaging partners represent the most penetrable buyer archetype for specialized PCM certification services. Electronics thermal interface material convergence with PCM layers offers white-space entry for aerospace and data center segments requiring narrow temperature bandwidth buffering. Lead with application engineering partnerships rather than commodity volume to bypass incumbent feedstock scale advantages. For Investors and Strategic Acquirers: Accelerating state-level thermal storage mandates in California and New York tightening faster than federal baselines is the leading indicator that specification-grade envelope material suppliers will command sustained premium positioning. Target acquisition profiles center on microencapsulation technology specialists with validated shell integrity monitoring systems and existing EPA FEMP specification track records. Watch Health Canada PMRA evaluation timeline compression as the signal for cross-border certification scarcity value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Hydrogenation | Croda International Plc anchors bio-based PCM positioning through captive renewable feedstock supply security. |
| Microencapsulation Shell Integrity Technology Acquisition | DuPont de Nemours sustains decades-long building performance certification through proprietary polymer science platforms. |
| Dual-Jurisdiction Certification Infrastructure Buildout | Health Canada PMRA compliance capability unlocks cross-border pharmaceutical cold-chain contract awards. |
| AIM Act Compliance Product Line Expansion | EPA refrigerant phase-down rules accelerate solid-state PCM substitution in commercial refrigeration OEM roadmaps. |
| State-Level Code Acceleration Pre-Positioning | California and New York thermal storage mandates create premium specification tiers ahead of federal baseline tightening. |
Research Methodology
Document review covered EPA AIM Act implementation guidance, US Department of Energy Federal Energy Management Program standards, Health Canada PMRA evaluation protocols, and state-level building code amendments, complemented by interviews with specialty chemical R&D directors, cold-chain logistics procurement leads, building materials distributors, and microencapsulation plant managers. Secondary validation drew from customs trade data, American Chemistry Council reports, SEC 10-K filings of integrated petrochemical conglomerates, and pharmaceutical cold-chain packaging OEM technical disclosures. Bottom-up capacity and demand modeling triangulated against top-down regulatory mandate impact assessment.
Cross-reference between historical adoption curves in building envelope retrofits and expert panel input on AIM Act compliance timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, encapsulation technology sophistication, end-use application thermal precision requirements, and regional regulatory cluster stringency. CAGRs derived from installed base expansion rates in government building retrofits, pharmaceutical biologics distribution growth, and electronics cooling convergence applications.
Revisions become necessary when EPA refrigerant phase-down rule enforcement intensity shifts, Health Canada PMRA evaluation protocols extend timelines beyond current baselines, or crude oil volatility disrupts paraffin feedstock cost structures. Forecasts reflect assumptions on microencapsulation shell integrity validation automation rates and state-level thermal storage mandate adoption speed. A small set of named triggers—EPA enforcement calibration, Health Canada timeline compression, and Northeast corridor retrofit subsidy allocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Thin Insulation Market