
 North America Frac Sand Market | 2026-2036
North America Frac Sand Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frac Sand Market Intelligence
Market Context with Strategic Players
Permian Basin capacity expansion is tilting supply geography toward West Texas and southeastern New Mexico. U.S. Silica Holdings anchors its position through integrated mine-to-wellsite logistics across multiple basins. Covia Holdings Corporation differentiates via broad product specialization spanning Northern White and regional brown sand grades. Smart Sand, Inc. leverages dedicated unit-train rail infrastructure to sustain cost-competitive delivery into the Marcellus and Utica plays.
Technical Definition and Structural Segments
Frac sand consists of high-purity silica quartz proppant, typically screened to 20/40, 30/50, or 40/70 mesh sizes, that hydraulically fractures shale formations to maintain conductive pathways for hydrocarbon extraction. The material must meet API/ISO sphericity and roundness thresholds alongside crush resistance exceeding 7,000 psi closure stress. White sand commands premium positioning due to superior crush strength in deep-basin high-pressure applications, while brown sand occupies cost-sensitive Permian and Eagle Ford demand. Oil extraction remains the dominant application segment, though reservoir enhancements represent the fastest-growing category as operators deploy diverting agents and tail-in proppant strategies to maximize EUR per well.
Regulatory Framework and Outlook
OSHA enforces permissible exposure limits for respirable crystalline silica through its Respirable Crystalline Silica standard, compelling operators to invest in dust suppression systems and enclosed conveyor infrastructure. The EPA coordinates with state-level environmental agencies to regulate mine runoff and air quality permitting, while DOT and FRA oversee railcar and trucking safety standards governing bulk proppant transport. Stakeholders must monitor evolving silica litigation trends and state-level pit reclamation mandates that could reshape mine economics and regional supply availability.
Market Dynamics
Permian Basin well intensity is compressing proppant consumption per lateral foot while total stage counts rise, creating a structural tension between volume efficiency and absolute tonnage demand across North American shale corridors.
Growth Catalysts
- OSHA Silica Standards:Stricter respirable crystalline silica exposure limits are forcing capital deployment into dust suppression infrastructure, raising compliance-driven equipment demand for enclosed conveyor systems and automated loadout facilities.
- Parent-Child Well Interference:Refracturing campaigns and infill drilling density are extending proppant consumption cycles beyond initial completions, sustaining replacement demand in mature Texas and New Mexico acreage.
- Regional Brown Sand Acceptance:Permian operators are specifying locally mined 100-mesh and 40/70 brown sand grades, reducing transport cost burdens and shortening supply chains from mine to wellsite across West Texas.
Market Restraints
- Natural Gas Feedstock Volatility:Energy input costs for rotary drying and natural gas-fired processing create margin compression for wet plant operators when Henry Hub pricing spikes.
- Northern White Concentration:Premium crush-resistant proppant supply clusters in Wisconsin and Minnesota deposits, exposing buyers to rail capacity bottlenecks and weather-related logistics disruptions.
- Ceramic Proppant Substitution:High-pressure deep-basin applications in the Delaware and Anadarko are shifting toward bauxite-based and resin-coated ceramic alternatives where closure stress exceeds 10,000 psi.
Strategic Opportunities
- Last-Mile Logistics Integration:Mine-to-silo containerized proppant delivery via pneumatic bulk systems is eliminating transload costs and reducing wellsite silica exposure for Permian and Eagle Ford operators.
- Reclamation Credit Markets:Texas Railroad Commission pit restoration bonding requirements are creating secondary markets for engineered fill and construction aggregate derived from processed fines.
- Real-Time Proppant Monitoring:IoT-enabled railcar and silo inventory tracking is converging with operator drilling schedules, enabling just-in-time delivery models that reduce working capital requirements.
Industry Challenges
- Specialized Equipment Operator Shortage:Mobile mining equipment technicians and pneumatic bulk haul drivers with hazmat endorsements command wage premiums that elevate contractor costs across the Permian and Bakken.
- API Certification Timeline Compression:Third-party crush resistance and turbidity testing backlogs at ISO-accredited laboratories are extending product qualification cycles for new mine entrants seeking baseline specification approval.
Report Scope
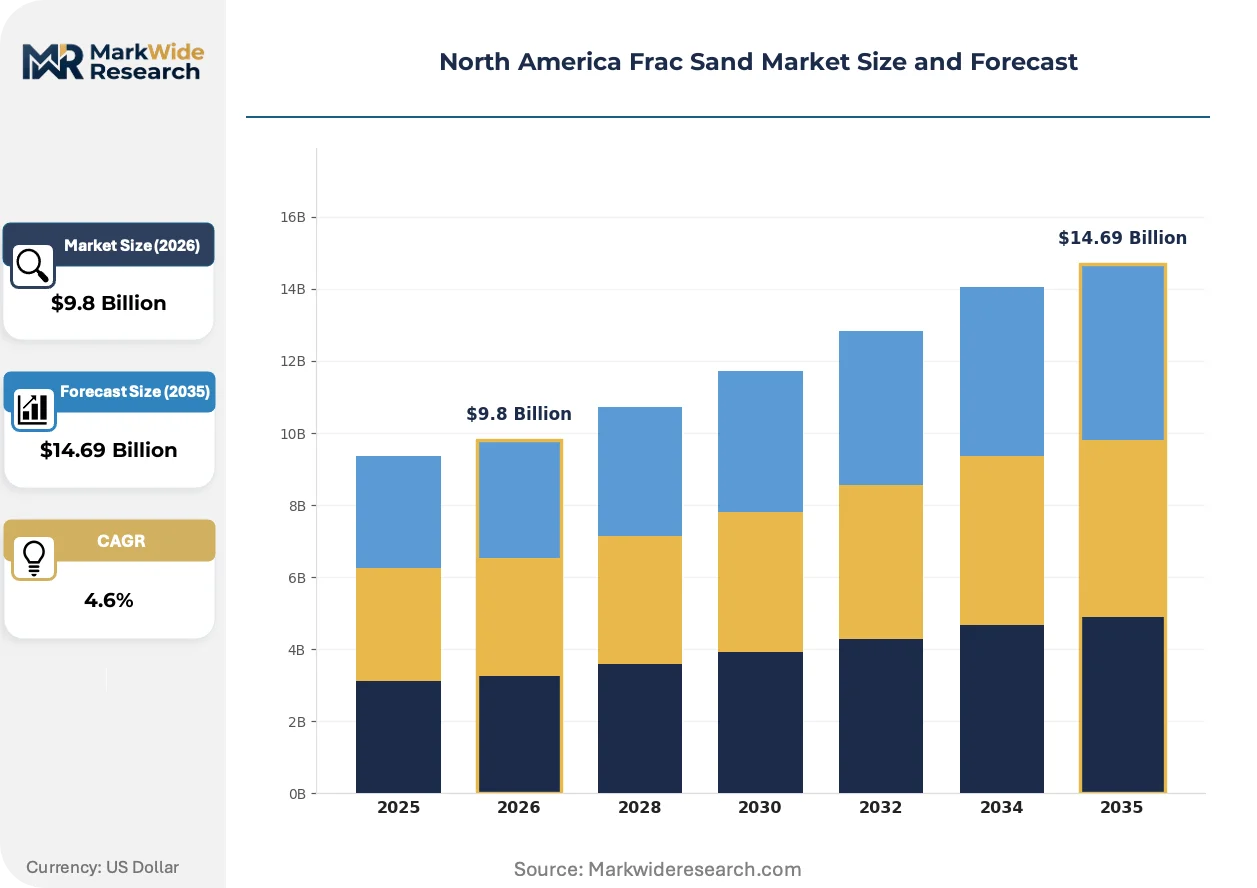
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frac Sand Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Sand, White Sand, Coated Sand, Specialty Sand Application: Oil Extraction, Natural Gas Extraction, Well Stimulation, Reservoir Enhancements Distribution Channel: Direct Sales, Distributors, Online Retail, E-commerce End User: Energy Companies, Oilfield Services, Construction Companies, Mining Companies |
| Companies Covered | Smart Sand, Inc., Black Mountain Sand, U.S. Silica Holdings, Atlas Sand Company, Source Energy Services, Hi-Crush Inc., Badger Mining Corporation, Emerge Energy Services, Covia Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frac Sand Market Strategic Shifts & Innovations
Proppant supply chains are compressing through direct sourcing relationships and on-site storage infrastructure, eliminating traditional distributor layers while silica exposure mitigation technologies reshape mine and wellsite operations.
Dune-mounted wet sand processing is collapsing the traditional wash-plant-to-dry-plant logistics chain by locating coarse processing directly at extraction faces. Permian pure-play operators are adopting this configuration to eliminate double-handling costs. The structural consequence is collapsing capital requirements for regional brown sand entrants who bypass legacy infrastructure investments.
EPA coordination with state environmental agencies on mine runoff permitting is tightening discharge standards for total suspended solids in Wisconsin and Minnesota surface water systems. Industrial consequence includes mandatory sedimentation pond upgrades and constructed wetland requirements. Northern White sand producers are responding with closed-loop water recycling systems that reduce freshwater withdrawal intensity.
Spot-market procurement through digital freight platforms is displacing annual volume commitments for non-core proppant grades. Mid-size Permian producers are leveraging these channels to arbitrage railcar availability and capture distressed inventory. This pattern is most visible among second-tier operators in the Midland Basin who lack dedicated logistics contracts with integrated sand suppliers.
North America Frac Sand Market Segmentation
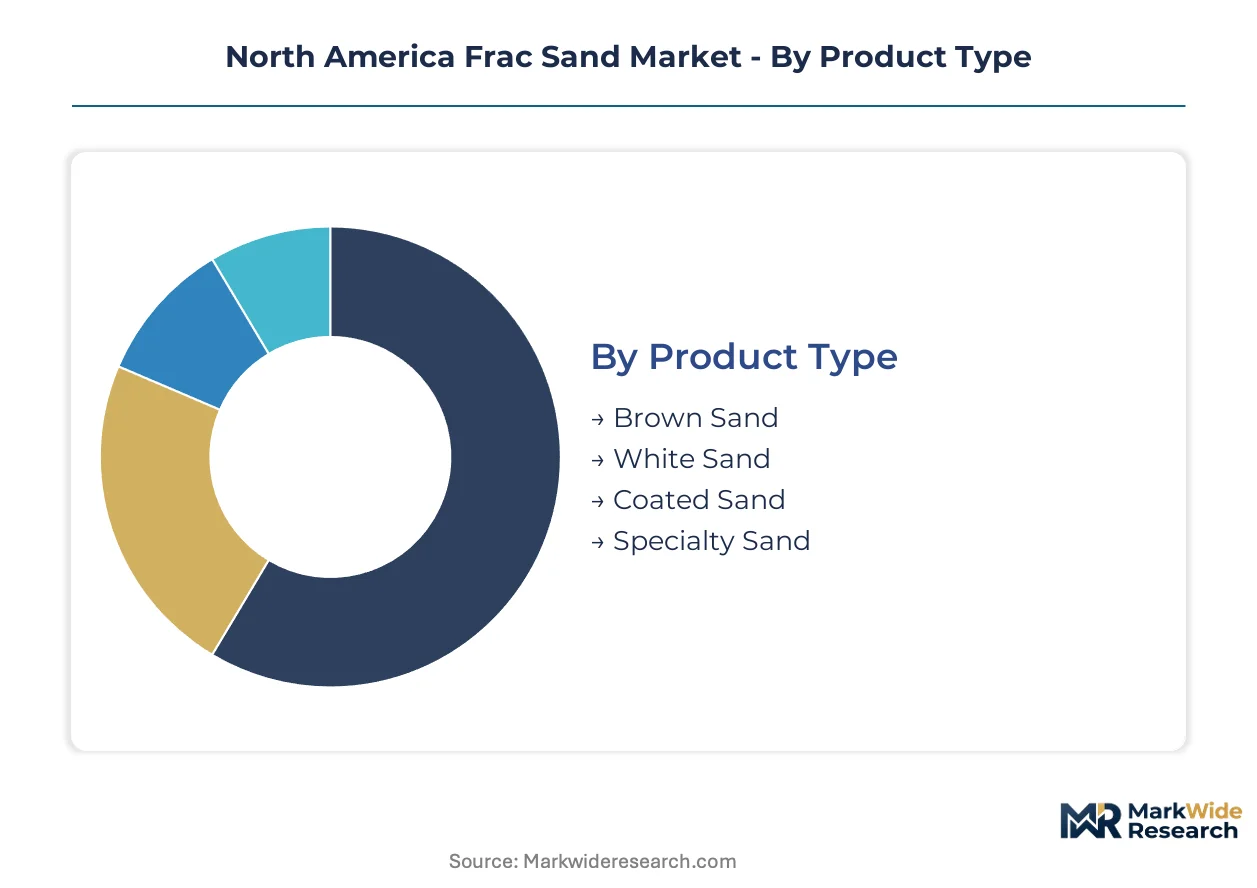
Frac sand procurement patterns diverge sharply across product grades and application intensity, with Permian operators optimizing for transport economics while deep-basin drillers prioritize crush performance. Understanding these segment boundaries clarifies where capital deployment concentrates and where margin compression threatens incumbent positions.
Product Type:
Use-case spectrum spans cost-driven Permian completions to high-pressure Delaware Basin wells where closure stress dictates specification.
- White Sand:High-purity Northern White quartz from Wisconsin and Minnesota deposits delivers crush resistance exceeding 8,000 psi for deep-basin unconventional plays. Demand concentrates in the Delaware Basin and Anadarko where 10,000+ psi closure stress eliminates brown sand viability; EPA-coordinated silica exposure standards elevate wet-sand processing adoption to reduce respirable dust at wellsite.
- Brown Sand:Regionally mined 100-mesh and 40/70 grades from West Texas and Oklahoma deposits dominate Midland Basin and Eagle Ford completions. Operators specify brown sand for cost-sensitive 6,000-8,000 psi applications; dune-mounted wet processing at extraction faces collapses traditional wash-to-dry logistics chains and halves capital requirements for new entrants.
- Coated Sand:Resin-coated and curable proppant variants reduce flowback and embedment in moderate-stress reservoirs.
- Specialty Sand:High-conductivity engineered substrates target refracturing campaigns and parent-child well interference mitigation.
Established volume favors Brown Sand; emerging adoption favors Specialty Sand.
Application:
Drilling intensity and well maturity create divergent proppant consumption profiles across completion types.
- Oil Extraction:Horizontal laterals in the Permian and Bakken consume 3,000-5,000 tons per well across 30-60 stage completions; parent-child interference and infill density are extending consumption cycles beyond initial completions into refracturing campaigns that sustain replacement demand.
- Reservoir Enhancements:Diverting agents, tail-in proppant strategies, and far-field diversion maximize EUR per well in mature Texas and New Mexico acreage; this segment climbs fastest as operators deploy capital-efficient workovers versus greenfield drilling.
- Natural Gas Extraction:Marcellus and Utica dry gas windows specify 100-mesh sand for lower-pressure reservoirs.
- Well Stimulation:Acidizing and fracturing combinations in carbonate formations require specialized proppant placement.
Primary completion activity anchors Oil Extraction volume; capital efficiency priorities elevate Reservoir Enhancements.
Distribution Channel:
Supply chain compression is eliminating intermediary layers through direct mine-to-silo relationships and digital freight arbitrage.
- Direct Sales:Integrated suppliers deploy dedicated unit-train rail and pneumatic bulk systems to deliver containerized proppant directly to operator silos; this channel captures distressed inventory and eliminates transload costs for Permian producers lacking long-term logistics contracts.
- Distributors:Regional inventory holders buffer spot-market volatility for mid-size operators with irregular completion schedules.
- Online Retail:Digital procurement platforms aggregate railcar availability for non-core proppant grades.
- E-commerce:Emerging channels target small-scale exploration companies and specialty blend orders.
Volume consolidation favors Direct Sales; spot-market flexibility favors Online Retail.
End User:
Procurement sophistication varies sharply across integrated majors, service companies, and construction-adjacent miners.
- Energy Companies:Supermajors and Permian pure-plays negotiate multi-basin volume commitments with integrated sand suppliers; OSHA silica compliance investments and enclosed conveyor infrastructure are mandatory for direct procurement relationships with tier-one operators.
- Oilfield Services:Halliburton, Schlumberger, and Liberty Oilfield Services maintain captive proppant logistics networks; wage premiums for pneumatic bulk haul drivers with hazmat endorsements elevate contractor costs across their Permian and Bakken operations.
- Construction Companies:Secondary markets for processed fines and engineered fill serve Texas Railroad Commission pit restoration requirements.
- Mining Companies:Raw material extractors supply regional brown sand processors or export to industrial silica markets.
Contracting leverage favors Energy Companies; logistics integration favors Oilfield Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proppant consumption patterns diverge sharply across North American shale corridors. The United States dominates absolute tonnage demand through Permian Basin intensity, while Canadian operators prioritize logistics efficiency for remote Montney and Duvernay completions. Mexican unconventional development remains nascent but regulatory opening signals prospective supply chain extension.
United States
Permian Basin well intensity drives sustained proppant consumption across West Texas and southeastern New Mexico. OSHA enforces respirable crystalline silica exposure limits through workplace standards that compel dust suppression infrastructure investment. Midland-Odessa logistics clusters anchor mine-to-silo pneumatic bulk delivery systems that eliminate transload costs for regional operators.
Canada
Montney and Duvernay shale plays in Alberta and British Columbia specify Northern White sand grades for high-pressure reservoir applications. Health Canada coordinates with provincial regulators on mine runoff permitting and air quality standards for Saskatchewan and Manitoba extraction operations. Calgary-based logistics networks integrate unit-train rail capacity with wellsite storage infrastructure to serve remote northern completions.
Mexico
Burgos Basin shale prospects in northern Tamaulipas and Coahuila represent prospective unconventional demand as constitutional energy reforms mature. The country's national hydrocarbons regulator oversees exploration licensing that could extend proppant supply chains southward. Monterrey industrial corridors position for potential distribution hub development pending upstream investment acceleration.
North America Frac Sand Market Key Industry Players
Capability concentration sits with integrated mine-to-wellsite operators; scale advantage sits with regional brown sand specialists. The vendor base organizes around three strategic archetypes: Permian pure-plays with dune-mounted wet processing, multi-basin integrated suppliers with captive rail infrastructure, and Northern White specialists with API-certified premium grades. Dominant competitive moves include last-mile logistics integration through pneumatic bulk systems and brown sand capacity expansion to capture Permian transport cost arbitrage.
Among North American frac sand suppliers, U.S. Silica Holdings exemplifies multi-basin integration through dedicated logistics networks spanning multiple shale corridors. Covia Holdings Corporation occupies a position bridging premium Northern White and cost-optimized regional brown sand portfolios. Smart Sand, Inc. represents the specialized archetype with focused rail infrastructure deployment into Appalachian and Midwestern plays.
| Leading Market Players |
|---|
| Smart Sand, Inc. |
| Black Mountain Sand |
| U.S. Silica Holdings |
| Atlas Sand Company |
| Source Energy Services |
| Hi-Crush Inc. |
| Badger Mining Corporation |
| Emerge Energy Services |
| Covia Holdings Corporation |
| Others |
Cost & Logistics Intelligence
Midland-Odessa logistics clusters concentrate wet-sand processing capacity within 150 miles of Permian wellheads, compressing delivered cost spreads and amplifying pricing power for regional brown sand operators against rail-dependent Northern White suppliers. This geographic tightness creates divergent margin structures: dune-mounted processors capture transport arbitrage while Wisconsin-origin proppant faces railcar availability volatility and fuel surcharge pass-throughs.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between integrated sand suppliers and Permian pure-play operators, though spot-market digital platforms are capturing distressed inventory flows among second-tier buyers. Pricing stratifies across premium Northern White grades for Delaware Basin deep wells, standard regional brown sand for Midland Basin infill drilling, and economy 100-mesh options for cost-sensitive Eagle Ford completions. Cost compression in economy tiers is intensifying because dune-mounted wet processing halves capital requirements for new brown sand entrants. Mid-size operators lacking dedicated logistics contracts exhibit highest price sensitivity, while supermajors prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes on mining equipment and pneumatic bulk handling systems limit technology transfer to prospective Mexican market entrants, constraining capacity expansion south of the border. Raw material flows draw from Wisconsin and Minnesota quartz deposits, West Texas dune fields, and Oklahoma sedimentary formations. Supply chain risk centers on rail capacity bottlenecks through BNSF and Union Pacific corridors serving Northern White origins. Distribution runs through mine-to-silo pneumatic bulk systems for tier-one operators, regional inventory buffers for spot-market buyers, and emerging digital freight platforms for non-core grade arbitrage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening across last-mile logistics and real-time inventory management as operator procurement sophistication diverges between integrated majors and mid-size pure-plays.
For Market Incumbents: Pre-empt ceramic proppant substitution in deep-basin Delaware and Anadarko applications by accelerating resin-coated sand qualification timelines and securing API certification backlogs at ISO-accredited laboratories. Backward integration into captive railcar fleets and pneumatic bulk haul capacity defends margin position against spot-market digital entrants. Enclosed conveyor infrastructure investments lock in tier-one operator relationships as OSHA silica enforcement tightens. For New Entrants and Emerging Players: Pursue dune-mounted wet processing deployment in underdeveloped Oklahoma sedimentary corridors to capture Eagle Ford and Anadarko transport cost arbitrage. Target refracturing campaign proppant demand in mature Texas acreage where parent-child well interference sustains replacement consumption cycles. Go-to-market leverage rests on digital freight platform integration enabling just-in-time delivery without legacy rail contract burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated mine-to-silo operators with captive logistics infrastructure over pure-play mining assets exposed to rail rate volatility. Long-term viability across the analysis window hinges on silica exposure mitigation technology deployment and pit reclamation credit market development. Watch ceramic proppant market share inflection in 10,000+ psi closure stress applications as the signal for Northern White demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Last-Mile Logistics Integration | Mine-to-silo pneumatic bulk systems eliminate transload costs and reduce wellsite silica exposure for Permian operators. |
| Dune-Mounted Wet Processing Deployment | Coarse processing at extraction faces collapses traditional wash-to-dry logistics chains and halves capital requirements. |
| API Certification Acceleration | Third-party crush resistance and turbidity testing backlogs at ISO-accredited laboratories extend product qualification cycles for new entrants. |
| Reclamation Credit Market Development | Texas Railroad Commission pit restoration bonding requirements create secondary markets for engineered fill from processed fines. |
| Real-Time Proppant Monitoring | IoT-enabled railcar and silo inventory tracking converges with operator drilling schedules for just-in-time delivery models. |
Research Approach
Operator-level perspectives from frac sand procurement directors, oilfield services logistics managers, pneumatic bulk haul contractors, and Texas Railroad Commission permitting officials anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from EIA drilling productivity reports, SEC 10-K filings of integrated sand suppliers, OSHA enforcement data, and BNSF/Union Pacific commodity flow disclosures. Bottom-up well completion intensity models and top-down proppant consumption estimates triangulated volume outputs.
Scenario-bracketing around Henry Hub volatility, Permian drilling permit approval rates, and ceramic proppant substitution thresholds bounded the forecast range across the analysis window. Segmentation dimensions modeled include product grade tier, application intensity, distribution channel structure, and end-user procurement sophistication. CAGRs derived from stage count trajectories, lateral length evolution, and proppant intensity per foot trends. Forecast inputs incorporated OSHA silica compliance investment cycles and state-level pit reclamation mandate timelines.
Macroeconomic conditions sit as an overlay; deviation in WTI price bands, natural gas processing economics, or federal unconventional leasing policy would shift the trajectory. Material shifts in ceramic proppant cost-performance ratios or EPA silica exposure standard enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Norway Oil and Gas Upstream Market