
 Norway Oilfield Equipment Market | 2026-2036
Norway Oilfield Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oilfield Equipment Market Analytics
The gap between premium subsea systems and commodity drilling consumables is rebalancing as capital allocation shifts toward long-cycle subsea infrastructure over short-cycle rig deployments. Aker Solutions leverages its integrated subsea production portfolio to anchor large-field engineering contracts on the Norwegian Continental Shelf. TechnipFMC differentiates through vertical integration of subsea trees and umbilical manufacturing. Subsea 7 specializes in SURF installation and life-of-field services, sustaining its position in brownfield expansion work.
Norway oilfield equipment encompasses engineered systems designed to extract, process, and transport hydrocarbons from offshore reservoirs, typically rated for pressures exceeding 10,000 psi and operating in water depths surpassing 300 meters across the harsh North Sea environment. These systems serve the primary commercial purpose of maintaining production flow assurance while minimizing unplanned downtime on subsea developments. Subsea equipment commands the dominant share of capital expenditure as operators prioritize electrification and all-electric trees for remote fields. Digital oilfield technology represents the fastest-expanding segment as real-time reservoir monitoring and predictive maintenance platforms reduce operational expenditure. Drilling rigs remain a mature, cyclical category where jackup and semisubmersible utilization fluctuates with exploration budgets.
Petroleumstilsynet, Norway's offshore safety regulator, enforces stringent well integrity and equipment qualification standards that shape supplier certification requirements and barrier system designs. The Norwegian Petroleum Directorate coordinates resource management policies that influence field development schedules and equipment procurement timelines through licensing rounds and area relinquishment rules. The EU F-Gas Regulation and Norway's alignment with EU climate frameworks are tightening restrictions on fluorinated greenhouse gases used in offshore refrigeration and gas processing systems. Stakeholders must monitor how electrification mandates and carbon intensity benchmarks reshape equipment specifications for new field developments.
Market Dynamics
Subsea electrification mandates are compressing field development timelines as operators abandon hydraulic control architectures for all-electric trees across remote Norwegian Continental Shelf assets.
Growth Catalysts
- Petroleumstilsynet well integrity standards:Mandatory barrier system upgrades on aging North Sea infrastructure generate replacement demand for subsea production equipment.
- Johan Sverdrup cluster expansion:Tieback developments from neighboring discoveries to existing processing infrastructure concentrate procurement volumes for subsea trees and manifolds.
- All-electric subsea technology:Elimination of hydraulic umbilicals reduces topside footprint and enables longer step-out distances from host platforms.
Market Restraints
- Specialized forging capacity concentration:High-pressure subsea component manufacturing concentrates among a limited supplier base in Western Europe, creating bottleneck risk for large-project delivery schedules.
- EU F-Gas Regulation compliance costs:Restrictions on fluorinated greenhouse gases force refrigeration system redesigns on offshore gas processing modules, extending engineering cycles.
- Arctic drilling economics:Barents Sea frontier developments face breakeven thresholds that compress capital allocation during crude price volatility periods.
Strategic Opportunities
- Northern Barents Sea licensing rounds:New acreage awards under Norwegian Petroleum Directorate area relinquishment rules open greenfield equipment specification windows.
- Subsea processing integration:Convergence of seabed compression and seawater injection technologies enables standalone field developments without fixed platforms.
- Digital twin deployment:Real-time asset performance monitoring creates aftermarket service revenue streams independent of original equipment sales cycles.
Industry Challenges
- Subsea systems engineering talent scarcity:Specialized expertise in high-pressure high-temperature component design concentrates among retiring workforce cohorts.
- Qualification timeline compression:Petroleumstilsynet equipment certification requirements extend from concept to deployment, misaligning with accelerated sanctioning schedules under temporary tax relief frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oilfield Equipment Market |
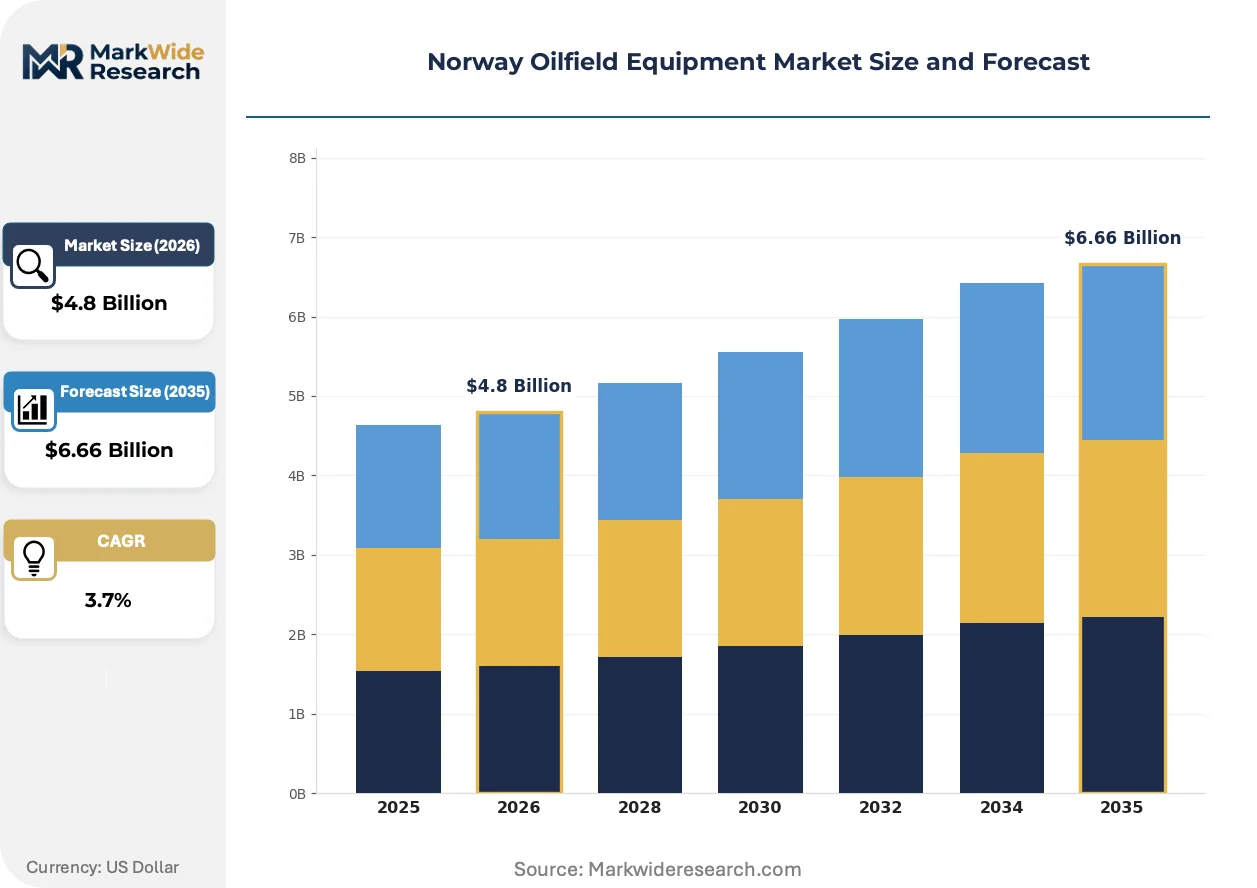
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Rigs, Blowout Preventers, Subsea Equipment, Completion Tools Service Type: Installation, Maintenance, Logistics, Consulting End User: Exploration Companies, Production Firms, Oilfield Services, Contractors Technology: Artificial Lift, Enhanced Oil Recovery, Digital Oilfield, Automation |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, TechnipFMC, Aker Solutions, National Oilwell Varco, Subsea 7, Equinor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oilfield Equipment Market Evolving Landscape
Electrification and digitalization are converging to redefine subsea architecture standards, with operators demanding integrated production systems that minimize topside intervention.
All-electric subsea trees are automating well intervention procedures by eliminating hydraulic fluid circulation requirements. Equinor and Aker BP are deploying these systems at Johan Sverdrup phase extensions and northern field developments. This architecture is automating remote valve operation sequences, reducing crew transfer vessel frequency and compressing opex per well.
EU F-Gas Regulation alignment through Norway's EEA obligations is restricting refrigerant selections for offshore gas dehydration and condensate stabilization units. Equipment suppliers must qualify alternative cooling chemistries or redesign heat exchange configurations. Subsea processing module manufacturers face the steepest compliance burden, as compact refrigeration systems lack retrofit space.
Integrated service contracting is displacing discrete equipment procurement on brownfield tiebacks. Operators now bundle subsea hardware, installation, and life-of-field support under single-source agreements. This pattern concentrates most visibly in the Johan Sverdrup cluster, where frame agreements cover multiple satellite field developments.
Norway Oilfield Equipment Market Segmentation
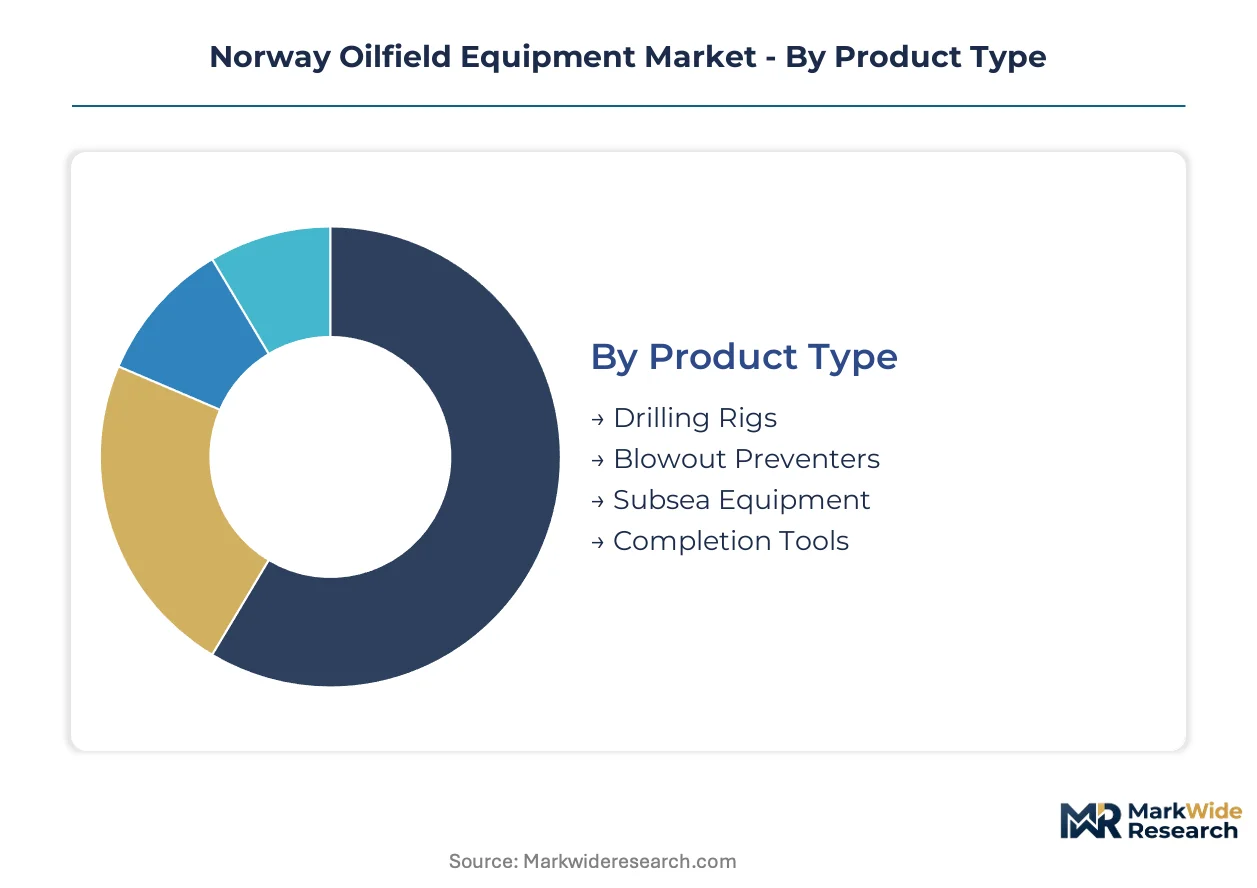
Segmentation in the Norway oilfield equipment market reflects how capital allocation priorities shift between development phases and operational maturity. Equipment categories align with distinct procurement cycles, from frontier exploration through brownfield optimization, each demanding specialized supplier capabilities and certification compliance.
Product Type:
Supply concentration among forged component manufacturers in Western Europe shapes availability windows for high-pressure rated systems.
- Subsea Equipment:All-electric trees, manifolds, and umbilicals rated for 10,000+ psi operation in water depths exceeding 300 meters. Demand concentrates at Johan Sverdrup cluster tiebacks and northern Barents Sea frontier developments where electrification mandates eliminate hydraulic architectures.
- Drilling Rigs:Jackup and semisubmersible units for North Sea and Barents Sea exploration. Procurement volumes fluctuate with Norwegian Petroleum Directorate licensing round timing and temporary tax relief framework windows that compress sanctioning schedules.
- Blowout Preventers:High-integrity barrier systems meeting Petroleumstilsynet well integrity standards for aging infrastructure replacement cycles.
- Completion Tools:Packers, bridge plugs, and stimulation hardware for reservoir isolation and flow assurance.
Today's leader: Subsea Equipment. Tomorrow's challenger: Blowout Preventers as barrier upgrade mandates accelerate.
Service Type:
Cost tier differentiation separates integrated frame agreements from discrete transactional procurement on brownfield expansions.
- Installation:SURF deployment, platform hookup, and subsea tieback execution requiring specialized vessel fleets. Integrated contracting bundles hardware and installation under single-source agreements at Johan Sverdrup cluster developments.
- Maintenance:Life-of-field support, predictive intervention, and barrier system recertification. Digital twin deployment creates aftermarket revenue streams independent of original equipment sales cycles.
- Logistics:Crew transfer, supply base coordination, and offshore warehousing for remote Norwegian Continental Shelf assets.
- Consulting:Reservoir engineering, field development planning, and regulatory compliance advisory.
Maintenance margins expand fastest as operators prioritize opex reduction through predictive platforms.
End User:
Customer type determines specification authority and procurement aggregation potential across the Norwegian Continental Shelf.
- Production Firms:Equinor, Aker BP, and independent operators holding Norwegian Petroleum Directorate production licenses. These entities specify subsea architectures and award integrated engineering contracts.
- Oilfield Services:Drilling contractors and completion service providers operating under operator-directed programs.
- Exploration Companies:License holders in frontier Barents Sea acreage facing breakeven threshold pressures during crude price volatility.
- Contractors:Subspecialized installation and intervention firms executing operator-procured scopes.
Production Firms retain specification control. Oilfield Services gain influence through integrated service contracting expansion.
Technology:
Technology maturity curves separate proven mechanical systems from digitally enabled platforms still navigating qualification timelines.
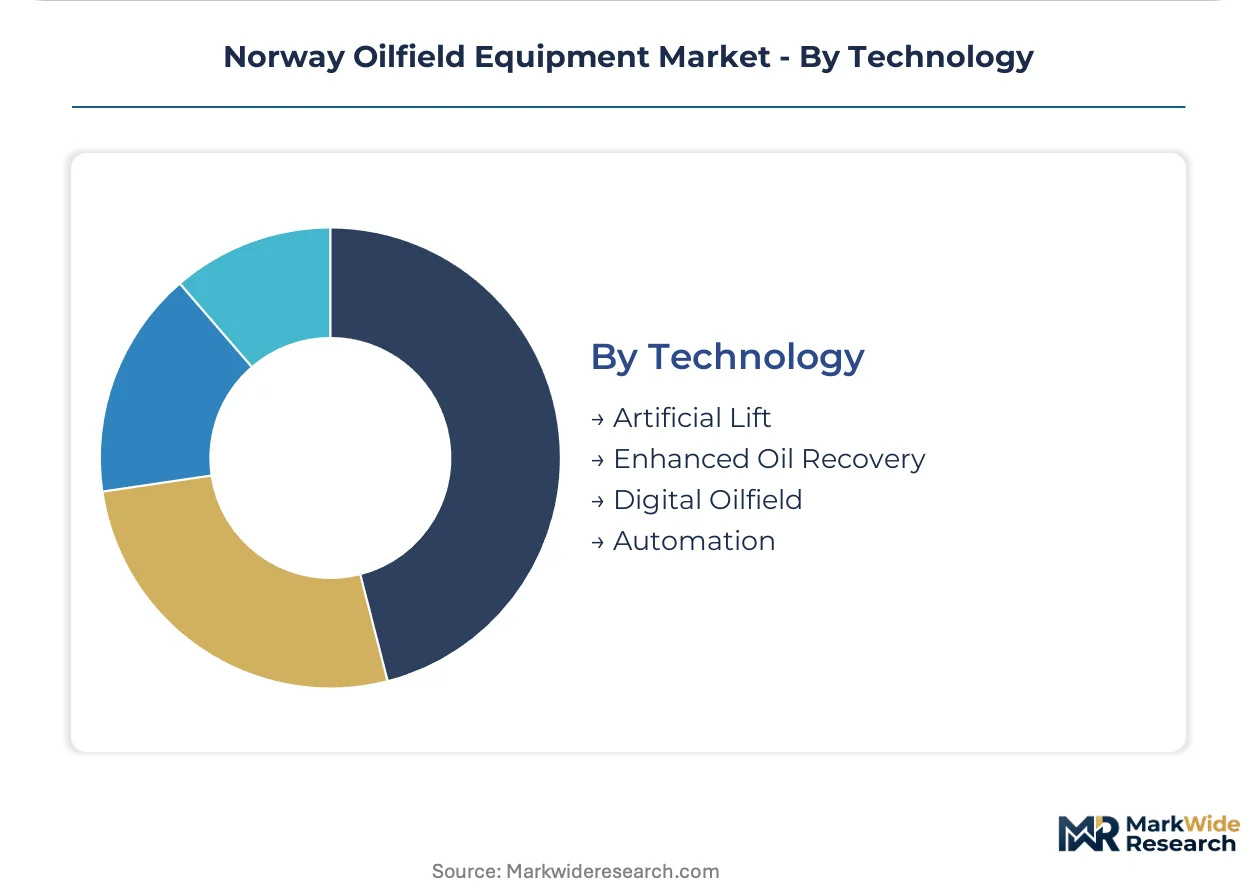
- Digital Oilfield:Real-time reservoir monitoring, predictive maintenance platforms, and remote operations centers reducing crew transfer vessel frequency. Petroleumstilsynet certification requirements extend deployment timelines for novel sensor architectures.
- Automation:Remote valve operation, automated well intervention, and topside-minimized production systems enabling longer step-out distances from host platforms.
- Enhanced Oil Recovery:Seawater injection, gas flooding, and chemical EOR for mature North Sea fields.
- Artificial Lift:Subsea compression and seabed pumping for pressure-depleted reservoirs.
Digital Oilfield climbs the fastest as operators target opex compression. Automation follows as electrification architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized subsea engineering talent clusters around Stavanger and Bergen anchor Norwegian Continental Shelf procurement decisions. These workforce concentrations shape where operators locate technical specification teams and supplier engineering support.
Northern North Sea
Johan Sverdrup cluster tiebacks concentrate subsea tree and manifold demand across this mature basin. Petroleumstilsynet well integrity mandates accelerate barrier system replacement cycles on aging platforms. Bergen hosts engineering centers where Aker Solutions and Subsea 7 coordinate integrated service contracts.
Southern North Sea
Decommissioning obligations and late-life field optimization sustain demand for intervention equipment and digital monitoring platforms. Norwegian Petroleum Directorate area relinquishment rules force operators to accelerate final production phases or surrender licenses. Stavanger remains the primary procurement hub where Equinor and Aker BP award brownfield expansion contracts.
Barents Sea Frontier
Arctic drilling economics and extended step-out distances from shore infrastructure compress development timelines for all-electric subsea architectures. EU F-Gas Regulation alignment through Norway's EEA obligations restricts refrigerant selections for offshore gas processing modules. Hammerfest serves as the logistics base for northern licensing round developments.
Mid-Norway Continental Shelf
Subsea processing integration and seabed compression technologies enable standalone field developments without fixed platform infrastructure. Temporary tax relief frameworks under Norway's offshore fiscal regime accelerate sanctioning schedules for marginal discoveries. Trondheim anchors research institutions collaborating with operators on electrification qualification programs.
Ekofisk Peripheral Zone
Enhanced oil recovery and seawater injection systems sustain production from pressure-depleted chalk reservoirs. Digital twin deployment creates aftermarket service revenue streams for predictive maintenance platforms. Kristiansand concentrates specialized completion tool manufacturers serving southern basin operators.
Norway Oilfield Equipment Market Competitive Landscape
Capital-heavy subsea fabricators compete with asset-light engineering specialists for Norwegian Continental Shelf contracts. The market structure consolidates around integrated service providers capable of bundling hardware, installation, and life-of-field support. Three archetypes dominate: full-system integrators commanding frame agreements, component specialists capturing niche forging and qualification work, and installation contractors deploying specialized vessel fleets. Competitive positioning sharpens through strategic partnerships for electrification technology access and capacity reservations at Western European forging facilities.
Among Norwegian-anchored engineering houses, Aker Solutions and Subsea 7 occupy positions within the integrated service tier, while TechnipFMC represents the vertically structured archetype combining subsea tree manufacturing with umbilical production. These entities exemplify how geographic proximity to Stavanger and Bergen engineering clusters shapes contract capture patterns on the Norwegian Continental Shelf.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| TechnipFMC |
| Aker Solutions |
| National Oilwell Varco |
| Subsea 7 |
| Equinor |
| Others |
Value Network & Pricing Analysis
Captive in-house production of high-pressure forged subsea components anchors supply positioning and pricing power for Norwegian Continental Shelf equipment suppliers. Operators seeking integrated frame agreements reward suppliers controlling critical forging capacity, compressing margins for asset-light competitors dependent on third-party component sourcing.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the Norwegian Continental Shelf. Project-based contracting dominates large-field developments where operators aggregate hardware, installation, and life-of-field support under single-source agreements. Price differentiation rests on Petroleumstilsynet certification tier and after-sales service bundling. Cost compression in standard subsea consumables is intensifying because integrated service providers leverage scale economies. Exploration companies in frontier Barents Sea acreage exhibit highest price sensitivity, while Equinor and Aker BP prioritize qualification reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for subsea tree refurbishment and barrier system recertification sustain aftermarket revenue independent of original equipment manufacturing. Geographic supply concentration centers on Norway, Germany, and France where specialized forging facilities produce high-pressure rated components. Raw material dependencies include nickel-alloy steel forgings, hydraulic control fluids, and fluorinated refrigerants now restricted under EU F-Gas Regulation alignment. Single-source vulnerability concentrates at Western European forging facilities with limited surge capacity. Distribution runs through Stavanger and Bergen engineering clusters coordinating specification authority and procurement aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway oilfield equipment market functions as a regulatory compounder where Petroleumstilsynet well integrity mandates generate recurring replacement demand regardless of crude price cycles.
For Market Incumbents: Extend frame agreement coverage across Johan Sverdrup cluster tiebacks before competitor qualification timelines mature. Secure capacity reservations at German and French forging facilities to eliminate delivery bottleneck exposure. All-electric subsea technology from emerging engineering specialists threatens incumbent specification control. For New Entrants and Emerging Players: EU F-Gas Regulation alignment in Norway opens a window for alternative refrigeration chemistry qualification in offshore gas processing modules. Target digital twin deployment for predictive maintenance platforms where Petroleumstilsynet certification requirements have slowed incumbent rollout. Pursue partnership routes with Trondheim research institutions to accelerate electrification technology access. For Investors and Strategic Acquirers: Roll-up economics work for specialized forging and qualification specialists because barrier system replacement cycles concentrate procurement volumes among certified suppliers. Acquisition targets include component manufacturers with Petroleumstilsynet-approved quality systems and established operator relationships. Monitor Barents Sea licensing round timing as inflection indicator for greenfield specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| All-Electric Subsea Technology Qualification | Petroleumstilsynet certification for all-electric trees enables longer step-out distances from host platforms. |
| Integrated Service Contracting Expansion | Single-source agreements at Johan Sverdrup cluster concentrate procurement volumes and lock out competitors. |
| Digital Twin Platform Deployment | Real-time asset monitoring creates recurring aftermarket revenue independent of equipment sales cycles. |
| Forging Capacity Reservation Agreements | Captive supply of high-pressure components eliminates delivery risk for large-project sanctioning timelines. |
| Alternative Refrigerant Chemistry Investment | EU F-Gas Regulation compliance opens specification windows for redesigned offshore gas processing modules. |
Research Methodology
Multiple input streams — executive interviews with subsea engineering directors, procurement leads at production firms, and regulatory affairs specialists — were reconciled against secondary validation from Norwegian Petroleum Directorate licensing databases, Petroleumstilsynet equipment certification records, and EU EEA obligation alignment documents. Bottom-up project sanctioning timelines and top-down fiscal regime impact modeling were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, service tier, end-user category, and technology maturity dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment procurement cycle analysis and field development schedule aggregation. Subsea electrification adoption curves and temporary tax relief framework windows served as industry-specific forecast inputs.
Revisions become necessary when Barents Sea breakeven thresholds shift materially, Petroleumstilsynet certification timelines extend unexpectedly, or EU F-Gas Regulation enforcement intensifies beyond current EEA alignment assumptions. Practitioners should monitor northern licensing round awards and forging facility utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Frac Services Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Injection Well Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Europe Hydraulic Fracturing Market