
 Oil and Gas Swell Packers Market | 2026-2036
Oil and Gas Swell Packers Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Swell Packers Market Analytics
Elastomer is decoupling from premium swell packer construction as composite formulations gain cost parity downhole. Weatherford International leverages its integrated manufacturing footprint to control raw material sourcing for composite packer elements. Schlumberger anchors its position through proprietary elastomer-blend R&D programs that extend temperature ratings beyond conventional thresholds. Halliburton competes by specializing in rapid-deployment swell packer systems for unconventional well architectures.
Oil and gas swell packers are downhole sealing devices manufactured from elastomeric or composite compounds that expand upon contact with wellbore fluids or hydrocarbons to create zonal isolation; they typically withstand differential pressures exceeding 10,000 psi and temperatures up to 350°F in standard configurations. Their primary purpose is to isolate production zones, seal annular spaces, and enable staged fracturing without mechanical setting tools. Hydraulic swell packers dominate installed base volumes due to proven reliability in high-pressure gas wells, while composite swell packers represent the fastest-expanding product category as operators push thermal limits in deepwater applications. Decommissioning functionality within the functionality segment carries outsized margin contribution as regulatory plug-and-abandonment obligations tighten across mature basins.
API 11D1 certification governs swell packer qualification testing in US jurisdictions, while ISO 14310 provides international validation protocols for packer performance envelopes. The EPA's methane emissions regulations and BSEE well integrity standards collectively shape product specification requirements by mandating zero-leak isolation barriers during production and abandonment phases. Stakeholders must monitor composite material qualification timelines and regional regulator harmonization efforts between API and ISO frameworks to anticipate certification-driven procurement shifts.
Market Dynamics
Composite swell packer formulations are compressing the traditional elastomer supply chain as API 11D1 testing protocols force material recertification across all major basins, creating a bifurcation between legacy suppliers and composite-qualified manufacturers.
Growth Catalysts
- Deepwater exploration intensity:Brazil's pre-salt basins and the Gulf of Mexico drive demand for high-pressure, high-temperature swell packer systems that seal during extended-reach drilling operations.
- EPA methane emissions regulations:Mandates for zero-leak isolation barriers during production and abandonment phases accelerate replacement of aging mechanical packer installations.
- Elastomer-to-composite material transitions:Cost parity between composite and elastomer formulations enables broader adoption in thermal-limited deepwater applications.
Market Restraints
- Raw material concentration:Specialized elastomer and resin feedstocks concentrate among a limited supplier base, exposing packer manufacturers to input volatility.
- API 11D1 certification timelines:Extended qualification testing for composite formulations delays product commercialization and locks out unqualified competitors.
- Mechanical packer substitution:Established mechanical setting tools retain preference in low-temperature, low-complexity well architectures where swell packer advantages diminish.
Strategic Opportunities
- Decommissioning service bundling:Regulatory plug-and-abandonment obligations in mature North Sea and Gulf of Mexico basins create demand for integrated swell packer deployment and removal services.
- West Africa offshore expansion:Underpenetrated deepwater blocks off Angola and Nigeria offer first-mover positioning for composite-qualified suppliers.
- ISO 14310 harmonization:Convergence between API and international validation protocols reduces duplicate certification costs for suppliers serving multiple jurisdictions.
Industry Challenges
- Composite qualification expertise:Shortage of materials engineers capable of navigating API 11D1 testing protocols for non-elastomer formulations constrains supplier expansion.
- Legacy well integration:Retrofitting swell packers into existing well architectures designed for mechanical tools requires customized engineering and extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Swell Packers Market |
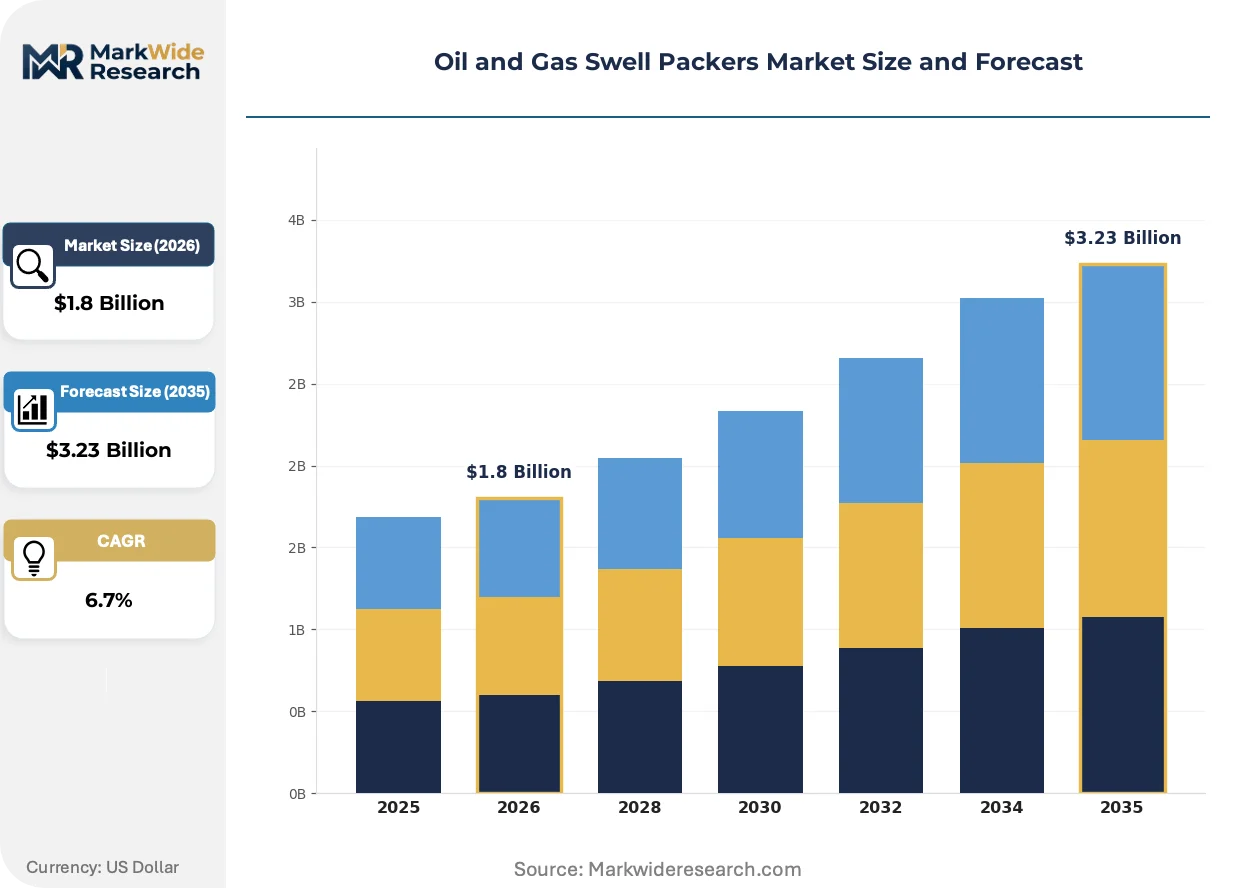
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Swell Packers, Mechanical Swell Packers, Composite Swell Packers, Dual-Wall Swell Packers Functionality: Sealing, Isolation, Decommissioning, Pressure Maintenance Well Type: Production Wells, Injection Wells, Gas Wells, Exploration Wells Application: Onshore Operations, Offshore Operations, Enhanced Oil Recovery, Well Rehabilitation |
| Companies Covered | Weatherford International, TAM International, Schlumberger, TechnipFMC, Packers Plus Energy Services, Halliburton, National Oilwell Varco, Tenaris, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Swell Packers Market Evolving Landscape
Material science breakthroughs and regulatory tightening are converging to reshape competitive positioning in swell packer supply, with composite formulations and integrated service models displacing standalone product sales.
Composite swell packer technology is electrifying the high-temperature segment by replacing elastomer elements with thermoplastic formulations that withstand sustained exposure above 350°F. Deepwater operators in Brazil and West Africa are adopting these systems for pre-salt and ultra-deepwater completions where thermal degradation previously limited elastomer reliability. This shift is compressing the addressable market for conventional elastomer suppliers while expanding the total serviceable market for extreme-environment applications.
BSEE well integrity standards and EPA methane regulations are mandating redundant isolation barriers throughout the production lifecycle, effectively prohibiting single-point-of-failure packer designs. Operators must now specify dual-seal configurations or demonstrate equivalent reliability through enhanced material testing. The Gulf of Mexico and Alaska North Slope exhibit the most stringent enforcement, driving procurement preference toward suppliers with demonstrated zero-leak field histories.
Integrated deployment contracting is displacing standalone product sales as national oil companies and international majors consolidate vendor relationships. Suppliers now compete on total cost of zonal isolation rather than unit packer pricing, with service bundling encompassing installation, monitoring, and abandonment retrieval. This pattern concentrates procurement volume among vertically integrated service companies and marginalizes pure-play packer manufacturers in the Middle East and Latin America.
Oil and Gas Swell Packers Market Segmentation
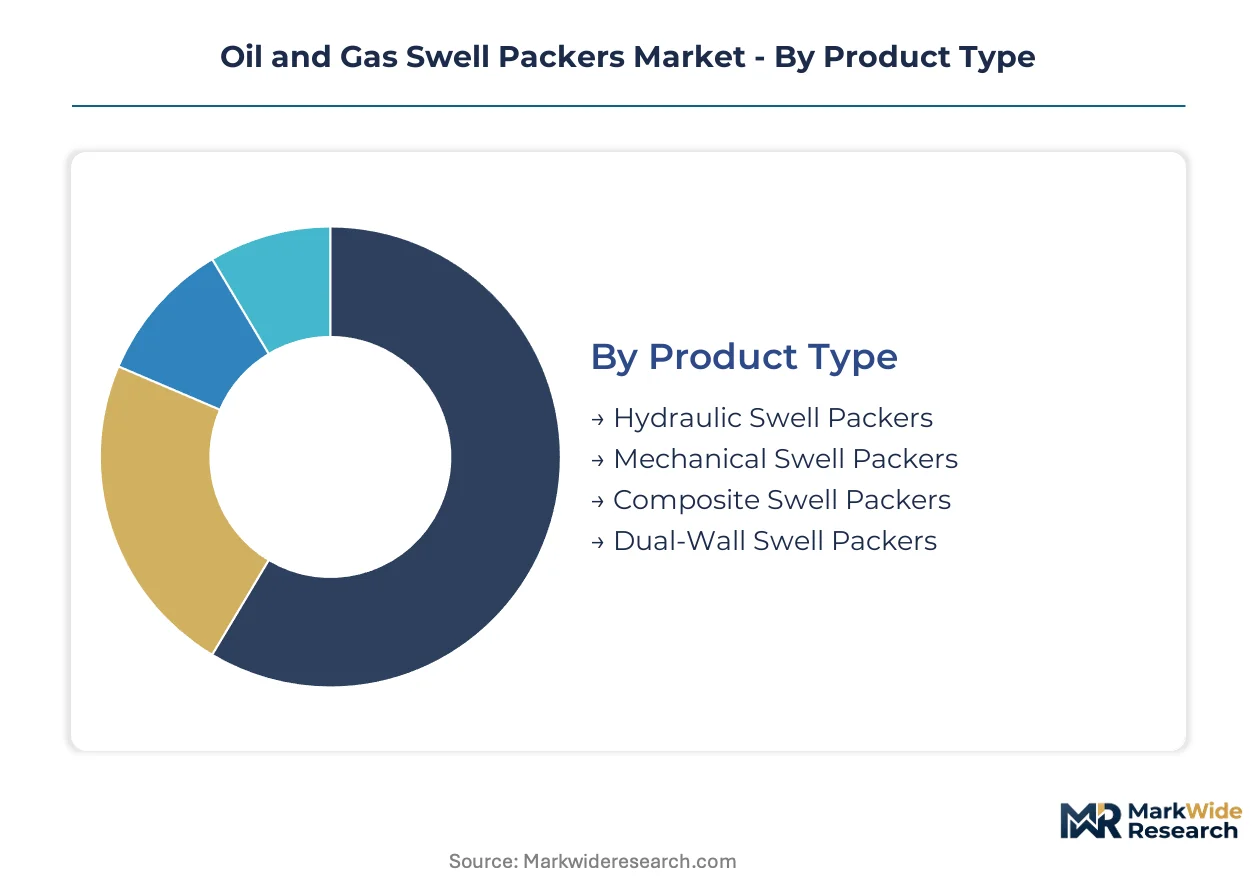
Swell packer segmentation reflects divergent engineering requirements across pressure regimes, thermal envelopes, and regulatory jurisdictions. Product architecture choices directly determine qualification pathways under API 11D1 and ISO 14310 protocols.
Product Type:
Customization intensity spans from standardized hydraulic systems to engineered composite formulations tailored for specific thermal-pressure envelopes.
- Hydraulic Swell Packers:Elastomeric elements expand through controlled fluid absorption, achieving annular seal without mechanical setting tools. Gulf of Mexico operators deploy these systems in high-pressure gas completions where differential loads exceed 10,000 psi. API 11D1 qualification timelines for hydraulic variants remain shorter than composite alternatives, sustaining procurement velocity.
- Composite Swell Packers:Thermoplastic formulations replace conventional elastomers to withstand sustained exposure above 350°F in Brazil's pre-salt basins. West Africa deepwater blocks are adopting these systems as thermal degradation risks limit elastomer reliability in ultra-deep completions. Material recertification under evolving API protocols constrains supplier expansion.
- Mechanical Swell Packers:Hybrid designs combine swell elements with mechanical backup for redundant isolation in critical well sections.
- Dual-Wall Swell Packers:Concentric barrier architecture addresses BSEE well integrity mandates for zero-leak redundancy in abandonment operations.
Most installed capacity flows through Hydraulic Swell Packers. Expansion is steepest in Composite Swell Packers.
Functionality:
Margin concentration tracks regulatory enforcement intensity, with decommissioning applications commanding premium pricing due to statutory liability exposure.
- Sealing:Primary zonal isolation creates annular barriers between formation and casing strings. Brazil's pre-salt developments specify sealing-grade packers for extended-reach laterals where differential pressure cycling degrades conventional elastomers.
- Isolation:Segregation of production zones enables staged fracturing and commingled production management. North Sea operators retrofit isolation packers into mature wellbores to comply with EPA methane emission barriers during production phase transitions.
- Decommissioning:Plug-and-abandonment obligations in mature Gulf of Mexico basins drive specification of retrievable swell packer systems.
- Pressure Maintenance:Injection well integrity applications require packers that withstand cyclic loading during waterflood and gas injection operations.
Decommissioning functionality captures the highest margin contribution per unit. Sealing applications dominate unit volume deployment.
Well Type:
Application complexity escalates from standardized exploration completions to engineered production systems with real-time monitoring integration.
- Production Wells:Long-term zonal isolation in flowing completions demands packers with verified fatigue resistance under cyclic pressure-temperature loading. Gulf of Mexico producers specify dual-seal configurations to satisfy BSEE well integrity standards for redundant barrier architecture.
- Gas Wells:High-pressure gas environments accelerate elastomer degradation through explosive decompression mechanisms. Composite formulations are displacing conventional materials in gas well completions where sustained pressure exposure exceeds 300°F.
- Injection Wells:Waterflood and CO2 injection operations require packers compatible with corrosive fluid chemistries.
- Exploration Wells:Temporary isolation applications prioritize rapid deployment and retrieval over extended service life.
Production Wells absorb the majority of qualified packer supply. Gas Wells are gaining share fastest as composite thermal ratings expand addressable applications.
Application:
Capital intensity bifurcates between onshore factory-style manufacturing and offshore engineered-to-order project execution.
- Offshore Operations:Deepwater completions in Brazil, West Africa, and the Gulf of Mexico specify high-temperature-high-pressure packers with integrated monitoring capabilities. Subsea installation complexity drives procurement preference toward suppliers offering bundled deployment and retrieval services.
- Onshore Operations:Unconventional well architectures in North American shale plays favor rapid-deployment swell packer systems that eliminate mechanical setting time. Standardized specifications enable inventory pooling across multi-well pad developments.
- Enhanced Oil Recovery:Thermal and chemical EOR methods impose material compatibility requirements beyond conventional hydrocarbon service envelopes.
- Well Rehabilitation:Workover applications require packers that deploy through existing completion hardware without pulling production tubing.
Offshore Operations command the highest average selling prices per installation. Onshore Operations provide the volume foundation for manufacturing scale economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins anchor the swell packer demand matrix, with deepwater exploration intensity cascading across the Atlantic margin into West Africa and the Gulf of Mexico.
Brazil
Petrobras-operated pre-salt developments drive specification of composite swell packers rated above 350°F for extended-reach laterals. Brazil's National Petroleum Agency enforces well integrity standards that mandate redundant isolation barriers in subsea completions. The Santos Basin cluster off Rio de Janeiro state absorbs premium-grade packer supply for ultra-deepwater wells.
United States
Gulf of Mexico deepwater operators deploy high-pressure hydraulic swell packers for gas completions exceeding 10,000 psi differential loads. The EPA's methane emissions regulations and BSEE well integrity standards collectively prohibit single-point-of-failure packer designs. Houston's energy corridor concentrates engineering talent for composite material qualification under API 11D1 protocols.
Nigeria
Offshore blocks in the Niger Delta basin generate demand for rapid-deployment swell packer systems that reduce rig time during exploration drilling. The country's Department of Petroleum Resources enforces casing integrity requirements that align with ISO 14310 validation frameworks. Lagos serves as the procurement hub for international oil companies operating West African deepwater concessions.
Norway
North Sea decommissioning obligations drive retrievable swell packer specifications for plug-and-abandonment campaigns in mature basins. The Norwegian Petroleum Safety Authority mandates zero-leak isolation barriers throughout the production lifecycle. Stavanger's subsea engineering cluster specializes in integrated deployment and retrieval service bundling.
Angola
Ultra-deepwater blocks off the Angolan coast adopt composite swell packers as thermal limits constrain elastomer reliability in high-temperature formations. The national petroleum regulator requires API 11D1 certification for all downhole isolation equipment. Luanda functions as the logistics coordination point for offshore developments in the Kwanza and Benguela basins.
Oil and Gas Swell Packers Market Competitive Landscape
Global majors compete with regional champions across technology licensing and integrated service bundling, creating a tiered structure where scale-driven players anchor premium segments and specialized fabricators occupy niche thermal envelopes. Three archetypes dominate: vertically integrated oilfield service conglomerates controlling raw material sourcing, mid-cap specialists with composite qualification expertise, and regional deployment contractors bundling installation with abandonment retrieval. M&A activity concentrates on composite material startups, while strategic partnerships link packer manufacturers with subsea installation contractors.
Within the integrated service tier, Weatherford International, Schlumberger, and Halliburton exemplify scale-driven positioning through captive manufacturing footprints and proprietary R&D programs. These entities anchor procurement relationships with national oil companies by offering total-cost-of-isolation contracting rather than standalone product sales. Halliburton occupies a position among rapid-deployment specialists, while Schlumberger sits within the premium materials tier. Weatherford exemplifies backward integration into composite element production.
| Leading Market Players |
|---|
| Weatherford International |
| TAM International |
| Schlumberger |
| TechnipFMC |
| Packers Plus Energy Services |
| Halliburton |
| National Oilwell Varco |
| Tenaris |
| Baker Hughes |
| Others |
Value Network & Pricing Analysis
National oil companies in Brazil and the Gulf of Mexico anchor procurement volume through integrated service contracts, compressing standalone product margins while elevating total-cost-of-isolation pricing models across deepwater basins.
Pricing Analysis
Specialized elastomer and thermoplastic resin costs pass directly through to packer unit pricing, with API 11D1 certification tiers creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on thermal rating thresholds and zero-leak field history documentation. Cost compression in standard hydraulic variants is intensifying because of inventory pooling across multi-well pad developments. Unconventional onshore operators exhibit highest price sensitivity; deepwater NOCs prioritize reliability over unit cost.
Supply Chain Analysis
Materials engineering talent scarcity in Houston, Rio de Janeiro, and Stavanger constrains composite formulation scale-up despite feedstock availability. Raw material sourcing draws from nitrile rubber suppliers in Asia, high-performance resin producers in Europe, and specialty additive compounders in North America. Single-source vulnerability concentrates in API-qualified testing laboratories, where extended queue times delay commercialization. Distribution runs through oilfield service company procurement networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite formulation cost-down curves and decommissioning service bundling are expanding margin capture for suppliers with integrated deployment capabilities.
For Market Incumbents: Anticipate mechanical packer substitution threats in low-temperature onshore applications by accelerating composite qualification investments under evolving API protocols. Anchor procurement relationships through captive manufacturing of thermoplastic elements and bundled abandonment retrieval services. For New Entrants and Emerging Players: Rapid-deployment swell packer systems for unconventional well architectures offer the most penetrable wedge, particularly in North American shale plays where standardized specifications enable inventory pooling. Target ISO 14310 harmonization gaps between API and international validation frameworks as a regulatory-first go-to-market angle. For Investors and Strategic Acquirers: Vertically integrated oilfield service conglomerates are the most active acquirer in this space, seeking composite material startups to fill thermal rating gaps. The long-term viability window favors suppliers with demonstrated zero-leak field histories in BSEE-regulated basins. Watch for EPA methane enforcement intensity as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | API 11D1 certification unlocks premium pricing in Brazil's pre-salt thermal envelopes. |
| Integrated Service Bundling | Installation-monitoring-retrieval contracts displace standalone product sales to NOCs. |
| Decommissioning Capability Buildout | Plug-and-abandonment obligations in the Gulf of Mexico drive retrievable system demand. |
| Regional Manufacturing Footprint | Houston and Rio de Janeiro clusters reduce logistics costs for deepwater deployment. |
| Zero-Leak Field History Documentation | BSEE well integrity standards mandate redundant barrier architecture procurement preference. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with drilling engineers, completion specialists, procurement managers at international operators, and regulatory affairs leads with secondary validation from API certification databases, BSEE incident reports, SEC oilfield service filings, and Petrobras technical disclosures. Bottom-up well count projections and top-down service revenue estimates were triangulated against composite adoption curves.
The forecast window anchored historical reference periods to documented installation volumes across hydraulic, composite, and hybrid packer categories, modeling segmentation across product type, functionality, well type, and application through the projection horizon. CAGRs were derived from regression against deepwater rig count trajectories and regulatory mandate implementation timelines, with elastomer-to-composite transition rates and decommissioning obligation schedules as primary industry-specific inputs.
The model holds under stable API 11D1 certification timelines and continued deepwater exploration intensity; deviation in composite material qualification delays or regulatory harmonization failures would shift supplier market share trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Global LNG Liquefaction Equipment Market