
 Drilling Bits Market | 2026-2036
Drilling Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Bits Market Analysis
Market Context
Petroleum engineering talent pools across North America and the Middle East are rotating toward digital drilling optimization, constraining traditional bit design capacity even as downhole complexity rises. Schlumberger Limited leverages integrated drilling services to bundle bit selection with real-time analytics, sustaining premium positioning in offshore markets. Baker Hughes Company anchors its portfolio through in-house production of thermally stable polycrystalline diamond cutters, controlling material quality from synthesis to final assembly. Halliburton Company differentiates via application-specific bit architectures for unconventional shale, navigating operator demands for longer laterals and faster rate-of-penetration.
Technical Definition and Segment Structure
Drilling bits are cutting tools attached to the bottom of a drill string, engineered with specified cutter layouts, blade counts, and hydraulic configurations to fragment rock formations under axial load and rotary torque. Their primary commercial purpose is to deliver measurable rate-of-penetration and footage-per-run economics across oil, gas, mining, and geothermal boreholes. PDC bits now lead value generation in soft-to-medium shale plays where their shearing action outperforms crushing mechanisms, while tricone bits retain structural importance in hard, interbedded formations where roller-cone impact resistance proves superior. Tungsten carbide and polycrystalline diamond material segments command margin concentration due to proprietary sintering processes and supply constraints on synthetic diamond feedstock.
Regulatory Environment and Outlook
The US Environmental Protection Agency and Bureau of Safety and Environmental Enforcement impose stringent wellbore integrity standards that directly shape bit selection criteria for pressure containment and cuttings management. API Specification 7-1 and ISO 10424-1 define dimensional and performance benchmarks that govern international market access and product interchangeability. The EU Green Deal methane reduction framework and emerging EPA methane rules are forcing operators to minimize non-productive time, which elevates demand for bits engineered to reduce trip frequency and associated venting events. Stakeholders must monitor how Scope 3 emissions accounting propagates through procurement criteria and whether material traceability requirements reshape supplier qualification protocols.
Market Dynamics
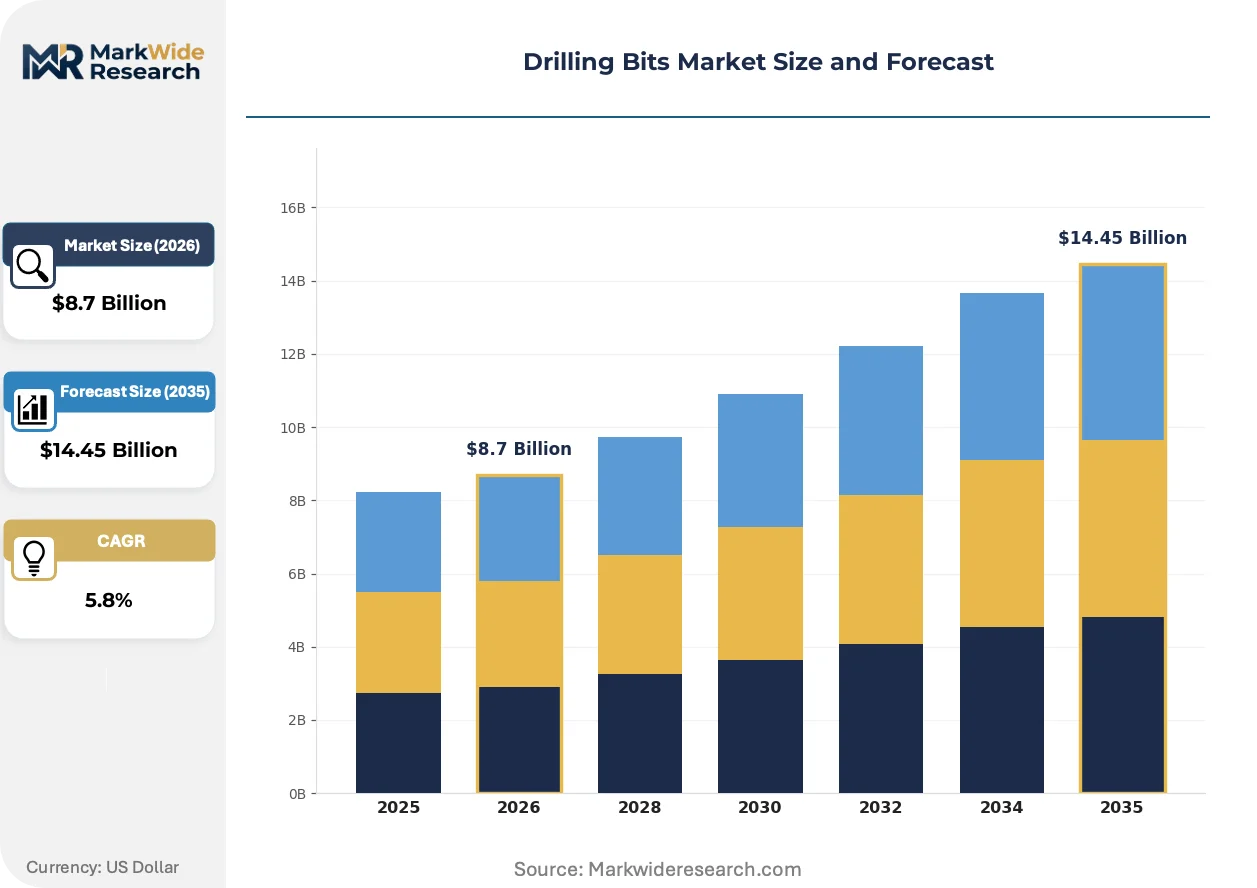
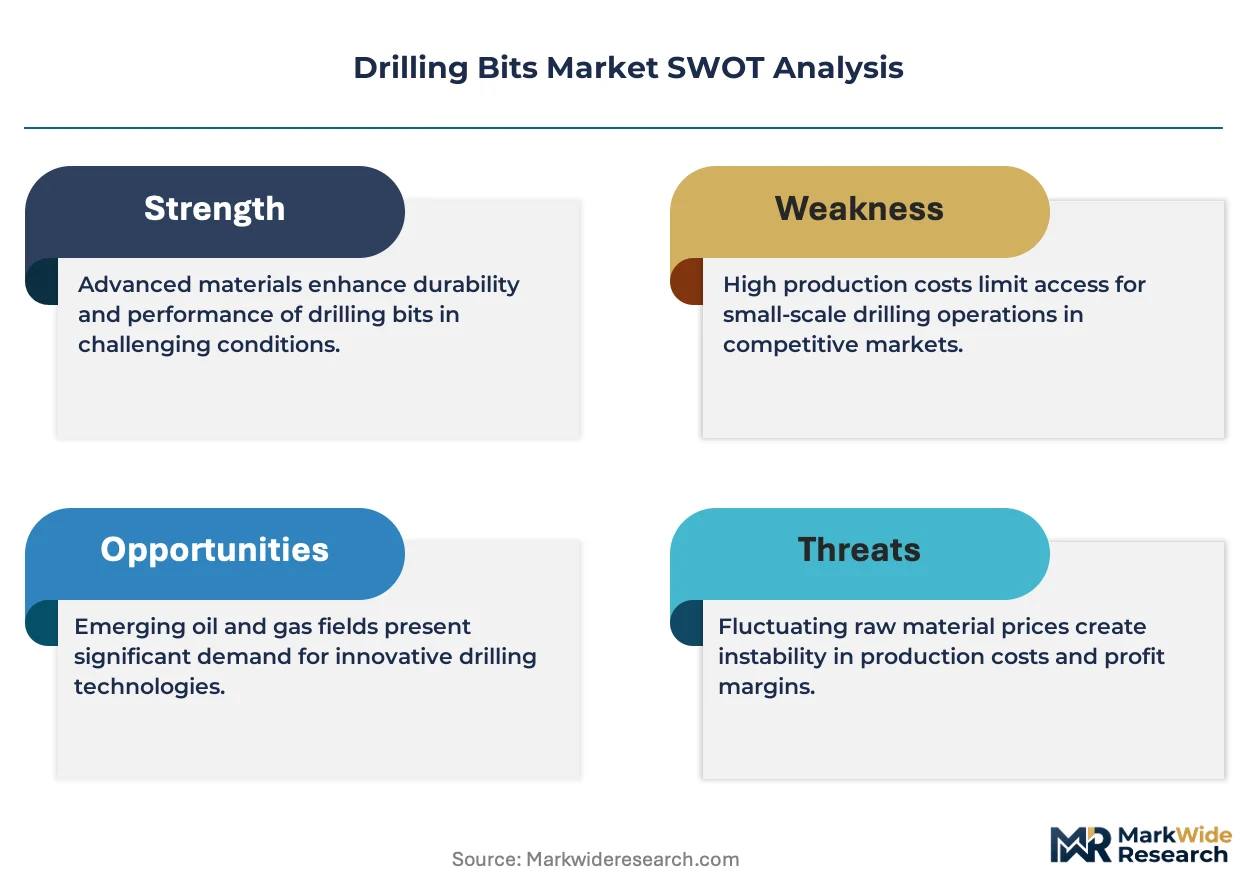
Polycrystalline diamond compact cutter technology is fragmenting the traditional roller-cone dominance in hard-rock applications, while API Specification 7-1 compliance costs compress margins for independent bit manufacturers lacking captive synthesis capacity.
Growth Catalysts
- Deepwater exploration expansion:Offshore drilling contractors in Brazil and West Africa are deploying advanced PDC bits for pre-salt carbonate formations, extending footage-per-run economics beyond legacy roller-cone limits.
- EU Green Deal methane framework:The regulation's venting reduction mandates force operators to minimize trip frequency, elevating demand for bits engineered for extended single-run durations in North Sea and Mediterranean gas plays.
- Polycrystalline diamond durability advances:Thermally stable cutter formulations now withstand 750°C bottom-hole temperatures, enabling shearing action in abrasive formations previously reserved for impact drilling.
Market Restraints
- Synthetic diamond feedstock concentration:Three specialized sintering facilities in the United States and Ireland control premium polycrystalline diamond substrate supply, creating single-source vulnerability for tier-two bit assemblers.
- Tricone bit infrastructure lock-in:Established rig fleets across Russia and Central Asia carry substantial roller-cone inventory, delaying capital rotation toward fixed-cutter architectures despite superior rate-of-penetration.
- EPA wellbore integrity enforcement:The Bureau of Safety and Environmental Enforcement's pressure-containment documentation requirements extend qualification timelines for new bit designs, freezing smaller manufacturers out of Gulf of Mexico offshore tenders.
Strategic Opportunities
- Geothermal energy expansion:High-temperature hard-rock formations in Iceland and Kenya's Rift Valley create demand for hybrid bit architectures combining PDC shearing with roller-cone impact resistance.
- Digital twin integration:Real-time cutter wear prediction algorithms are converging with automated rig controls, enabling predictive bit replacement before performance degradation triggers non-productive time.
- India PLI scheme for oilfield equipment:The production-linked incentive framework subsidizes domestic bit manufacturing capacity, attracting technology transfer partnerships for PDC cutter synthesis localization.
Industry Challenges
- Petroleum engineering talent rotation:Digital drilling optimization roles are absorbing experienced bit designers, leaving application-specific architecture development understaffed even as downhole complexity escalates.
- ISO 10424-1 certification timelines:International standard compliance testing for new cutter materials extends 14-18 months, delaying commercialization of next-generation thermal-stable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Bits Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tricone Bits, PDC Bits, Diamond Bits, Horizontal Directional Bits Application: Oil Extraction, Natural Gas Production, Water Well Drilling, Geothermal Energy End User: Oil & Gas Companies, Mining Operators, Construction Firms, Geophysical Surveyors Material: Steel, Tungsten Carbide, Polycrystalline Diamond, Composite Materials |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, National Oilwell Varco, Atlas Copco, Sandvik AB, Varel International, Ulterra Drilling Technologies, Kingdream Public Limited Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Bits Market Emerging Trajectories
Downhole telemetry and materials science are converging to redefine bit performance measurement, shifting procurement criteria from footage guarantees to real-time drilling efficiency optimization.
Hybrid bit architectures combining PDC cutters with rolling elements are fragmenting the traditional binary classification between shearing and crushing mechanisms. Operators in the Permian Basin and Vaca Muerta shale are piloting these designs for interbedded sandstone-limestone sequences where formation variability demands adaptive cutting action. The technology is fragmenting vendor specialization boundaries, forcing roller-cone specialists and PDC manufacturers into direct capability competition.
The EPA's emerging methane rules and EU Green Deal implementation are compressing allowable non-productive time windows, mandating bit designs that eliminate premature pull trips. Offshore operators in the Gulf of Mexico and North Sea are rewriting technical specifications to prioritize single-run lateral completion over upfront tool cost. Service companies are responding with proprietary cutter layouts optimized for specific formation abrasiveness profiles rather than generic basin applications.
Integrated drilling service bundling is displacing standalone bit procurement across offshore markets. National oil companies in Brazil and Norway are consolidating vendor relationships to capture real-time analytics value, compressing the addressable market for independent bit manufacturers lacking downhole sensor integration. This consolidation is most visible in deepwater pre-salt contracts where rate-of-penetration guarantees now span entire well sections rather than individual bit runs.
Drilling Bits Market Segmentation
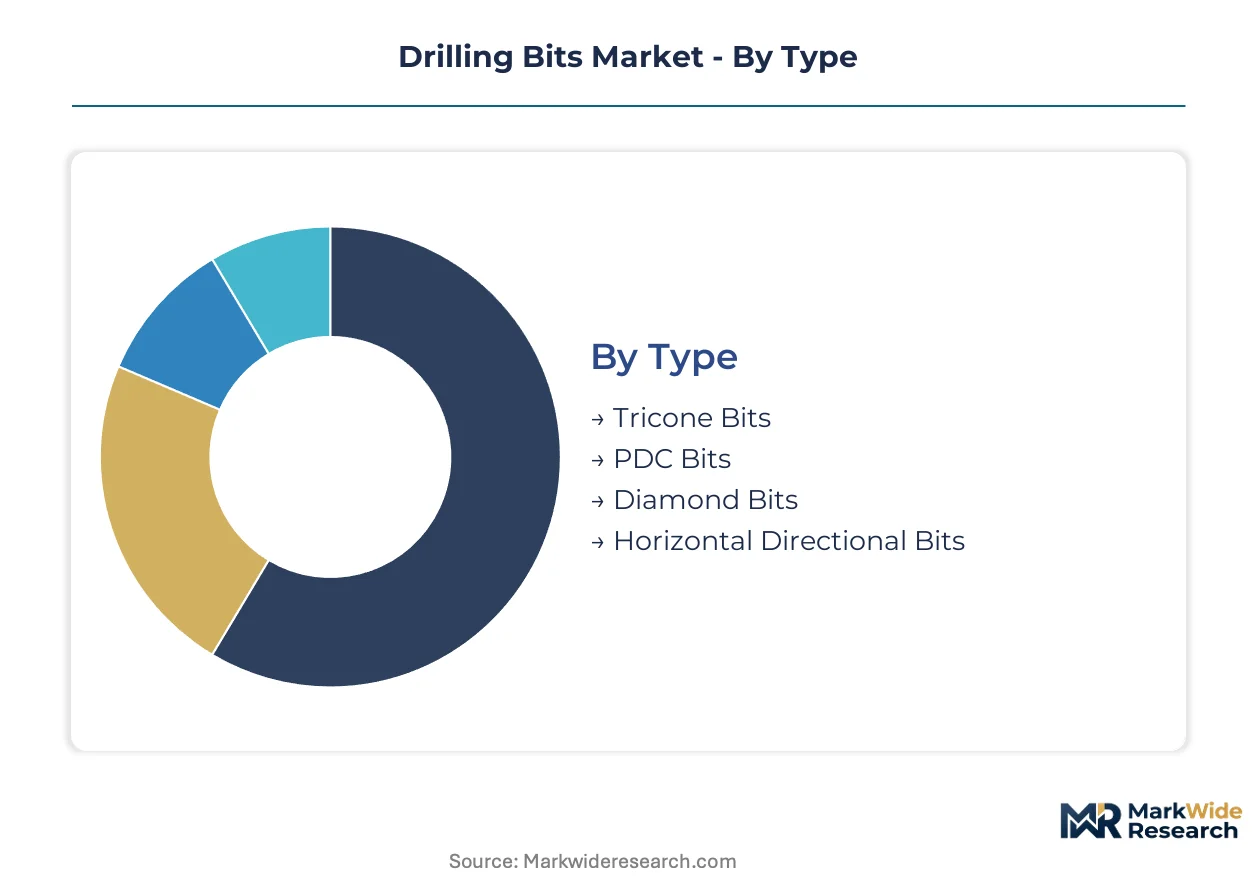
Bit selection criteria diverge sharply across formation hardness, thermal exposure, and wellbore geometry, making granular segmentation essential for matching cutter technology to specific drilling economics. Procurement patterns in offshore Brazil differ fundamentally from Permian Basin shale plays, requiring distinct material and design configurations.
Type:
PDC bits dominate export flows to deepwater markets, while tricone architectures retain domestic strength in legacy rig fleets across Russia and Central Asia.
- PDC Bits:Fixed-cutter designs employing polycrystalline diamond compact cutters shear rock through continuous scraping action rather than impact fracture. Demand concentrates in Brazil's pre-salt carbonate formations and West African deepwater blocks where footage-per-run economics override higher unit costs. Thermal-stable cutter formulations now withstand 750°C bottom-hole temperatures, expanding addressable formation hardness.
- Tricone Bits:Three-cone roller assemblies with tungsten carbide inserts crush rock via intermittent impact loading. These retain structural importance in Russia's Volga-Ural interbedded formations and Kazakhstan's hard dolomite sequences where rig fleets carry substantial roller-cone inventory and capital rotation lags.
- Diamond Bits:Natural or synthetic diamond impregnated matrices grind extremely hard crystalline formations through abrasive wear. Applications cluster in geothermal hard-rock drilling across Iceland's basalt provinces.
- Horizontal Directional Bits:Specialized bottom-hole assemblies engineered for curved wellbore trajectories in unconventional shale. The Permian Basin and Vaca Muerta formations drive specification requirements for extended-reach lateral durability.
PDC bits hold the largest share; momentum sits with hybrid architectures blending fixed-cutter shearing with rolling elements.
Application:
Cost tiers separate commodity onshore drilling from premium offshore contracts where non-productive time penalties reshape total cost of ownership calculations.
- Oil Extraction:Conventional and unconventional crude production drives the majority of bit consumption, with specification intensity varying by reservoir depth and viscosity. The Permian Basin's multi-stack laterals demand bits engineered for abrasive silica content and extended single-run footage.
- Natural Gas Production:Dry gas and liquids-rich plays in the Appalachian Basin and North Sea require pressure-containment-focused designs under EPA and EU methane reduction frameworks. Extended-reach horizontals in Qatar's North Field and Australia's Cooper Basin prioritize seal integrity over rate-of-penetration maximization.
- Water Well Drilling:Shallow to medium-depth boreholes for municipal and agricultural supply employ lower-specification tricone and drag bit configurations. India's Rajasthan aquifer programs and Saudi Arabia's groundwater independence initiatives sustain steady replacement demand.
- Geothermal Energy:High-temperature hard-rock formations in Kenya's Rift Valley and Iceland's Krafla field create specifications exceeding conventional oil and gas thermal limits. Hybrid bit architectures combining PDC and roller-cone elements gain traction here.
Oil extraction commands the premium tier by volume; geothermal applications are climbing the fastest as energy transition capital reallocates.
End User:
Customer sophistication stratifies procurement — integrated majors demand real-time performance analytics while independent operators prioritize upfront tool cost.
- Oil & Gas Companies:Supermajors and national oil companies in Brazil, Norway, and Saudi Arabia bundle bit procurement within integrated drilling service contracts. Petrobras and Equinor specifications now require downhole telemetry compatibility and rate-of-penetration guarantees spanning entire well sections.
- Mining Operators:Surface and underground mineral extraction employs larger-diameter bits for blast hole drilling, with wear resistance prioritized over directional precision. Chile's copper porphyry operations and Australia's iron ore pits sustain tungsten carbide insert demand.
- Construction Firms:Foundation drilling and tunnel boring applications utilize specialized auger and core bit configurations for concrete and unconsolidated overburden. Urban infrastructure projects in Dubai and Singapore drive specification requirements for vibration suppression.
- Geophysical Surveyors:Shallow coring operations for seismic shot hole placement and environmental sampling employ disposable bit economics. West African mineral exploration campaigns and Canadian Arctic permafrost studies sustain this segment.
Oil and gas companies represent the dominant customer base; mining operators are expanding most quickly as copper and lithium exploration accelerates.
Material:
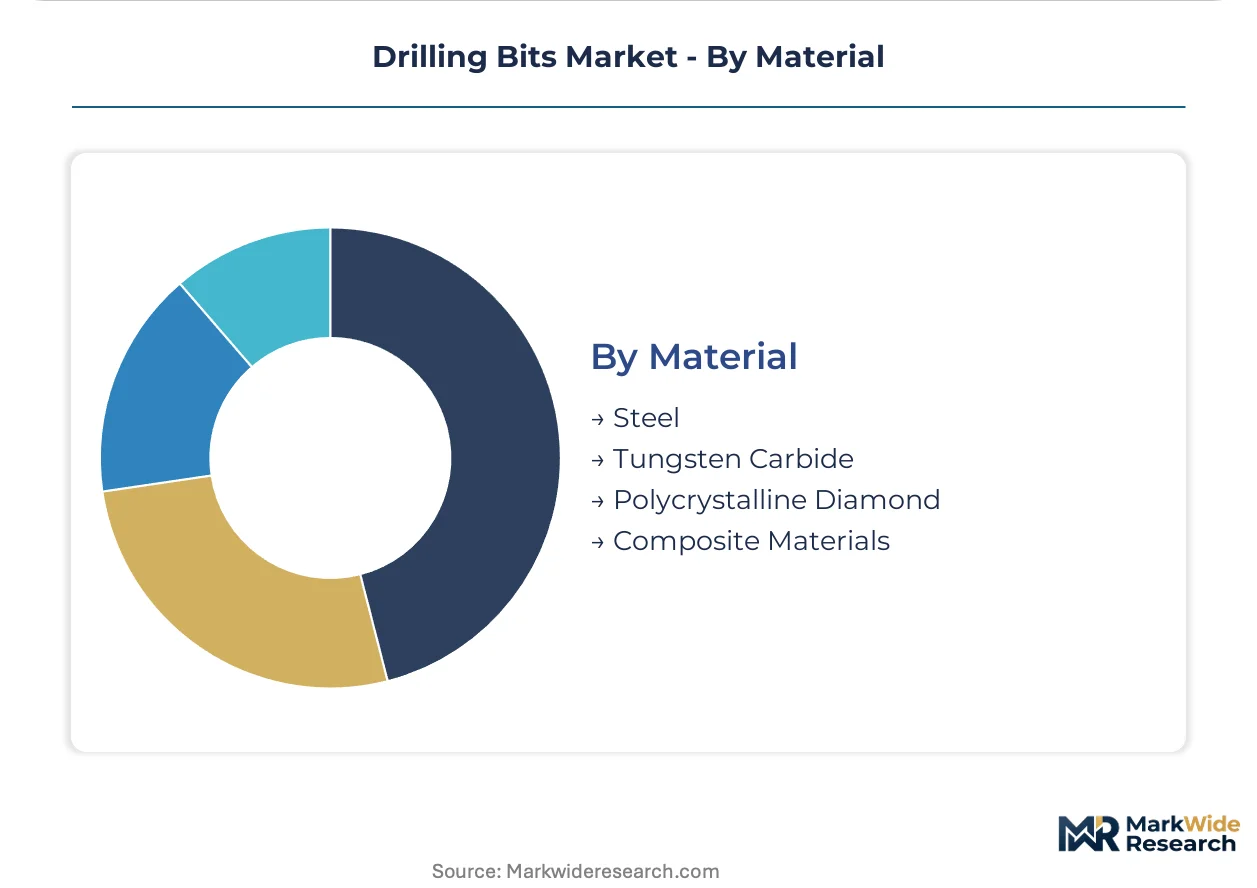
Supply concentration creates margin stratification — captive synthetic diamond synthesis confers cost advantages unavailable to steel-dependent assemblers.
- Polycrystalline Diamond:Sintered synthetic diamond layers bonded to tungsten carbide substrates deliver superior hardness and thermal conductivity for abrasive formations. Three specialized facilities in the United States and Ireland control premium substrate supply, creating single-source vulnerability for tier-two manufacturers.
- Tungsten Carbide:Cemented carbide compositions with cobalt binders provide impact resistance and fracture toughness for roller-cone inserts and PDC substrates. Powder metallurgy capabilities in Germany's Ruhr region and China's Hunan province govern global supply availability.
- Steel:Alloy steel bodies form the structural matrix for tricone bits and lower-specification fixed-cutter designs. Scrap volatility and electric arc furnace capacity in Turkey and India influence input cost structures.
- Composite Materials:Ceramic-matrix and polymer-composite hybrids address niche applications requiring weight reduction or corrosion resistance. Experimental deployments in geothermal hydrogen sulfide environments and deep-sea mining trials remain pre-commercial.
Polycrystalline diamond commands the steepest margin concentration; composite materials are gaining share fastest as extreme-environment applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA wellbore integrity enforcement and Bureau of Safety and Environmental Engineering standards anchor United States regulatory influence over bit qualification protocols and offshore procurement specifications.
United States
Permian Basin shale operators drive PDC bit consumption for extended laterals with abrasive silica content. EPA methane rules compress non-productive time allowances, elevating demand for single-run footage guarantees. Houston hosts the dominant cluster of bit design engineering and cutter synthesis R&D facilities.
Brazil
Pre-salt carbonate formations in the Santos Basin require thermally stable cutters for deepwater footage-per-run economics. ANP local content mandates force technology transfer partnerships for domestic bit assembly capacity. Macaé anchors offshore drilling contractor procurement and integrated service bundling negotiations.
Norway
North Sea gas field redevelopment prioritizes seal integrity and pressure containment under EU Green Deal methane frameworks. Equinor technical specifications now require downhole telemetry compatibility across entire well sections. Stavanger concentrates subsea drilling engineering and hybrid bit architecture pilot programs.
Saudi Arabia
North Field gas expansion and tight gas development drive specification intensity for extended-reach horizontals. Aramco procurement frameworks favor integrated drilling services with rate-of-penetration guarantees spanning multiple bit runs. Dhahran hosts the primary engineering cluster for high-temperature hard-rock applications.
China
Sichuan Basin shale gas development and Xinjiang tight oil plays absorb increasing volumes of fixed-cutter bits. MIIT industrial policy supports domestic cutter synthesis capacity expansion through technology licensing arrangements. Chengdu and Karamay anchor regional manufacturing clusters for PDC substrate production.
Drilling Bits Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with Schlumberger, Baker Hughes, and Halliburton commanding premium positioning through bundled drilling services. Independent bit manufacturers compete on application-specific architectures and regional price positioning. Three strategic archetypes define the field: integrated oilfield service conglomerates with captive cutter synthesis, pure-play bit specialists with formation-specific design expertise, and regional fabricators serving price-sensitive onshore markets. Competitive moves concentrate on backward integration into polycrystalline diamond substrate production and strategic partnerships for digital twin integration.
Among Houston-based integrated service providers, Schlumberger Limited and Halliburton Company exemplify the bundled-service archetype, while Baker Hughes Company represents the in-house materials control model through captive cutter synthesis. Kingdream Public Limited Company anchors the specialist tier as a Zhengzhou-based pure-play manufacturer occupying a position between global integrated leaders and regional price competitors.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| National Oilwell Varco |
| Atlas Copco |
| Sandvik AB |
| Varel International |
| Ulterra Drilling Technologies |
| Kingdream Public Limited Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day cutter substrate lead times concentrate pricing power among three sintering facilities in the United States and Ireland, forcing tier-two bit assemblers into premium feedstock premiums or inferior material substitutions. This inventory compression cascades through contract structures, elevating rate-of-penetration guarantees over unit pricing in deepwater procurement and squeezing margin recovery for steel-dependent regional fabricators.
Pricing Analysis
Brazil-to-Texas price spreads of 15-25% reflect ANP local content mandates and integrated service bundling premiums versus standalone bit procurement. Three-tier pricing structure across premium, standard, and economy levels separates thermally stable PDC configurations for pre-salt formations from commodity fixed-cutter designs for Permian shale and steel-body tricone replacements for Central Asian rig fleets. Cost compression in standard-tier fixed-cutter bits is intensifying because Chinese substrate capacity expansion feeds oversupply into Asian spot markets. National oil companies in Brazil and Norway exhibit least price sensitivity, prioritizing footage guarantees and telemetry integration, while Indian water well contractors and Russian onshore independents drive hardest bargain hunting.
Supply Chain Analysis
Forty-five to sixty days of synthetic diamond inventory coverage governs production scheduling for PDC substrate synthesis, with just-in-time cutter delivery contracts dominating offshore project logistics. Supply concentrates in the United States, Ireland, and China's Sichuan province for polycrystalline diamond substrates, Germany's Ruhr region and China's Hunan province for tungsten carbide powders, and Turkey and India for alloy steel bodies. Raw material dependencies rest on synthetic diamond feedstock from high-pressure sintering presses, cobalt binder powders for cemented carbides, and scrap steel flows from automotive shredder residue. Single-source vulnerability at the three premium substrate facilities exposes tier-two manufacturers to allocation rationing during demand spikes. Distribution runs through integrated service company warehouses in Houston, Macaé, and Stavanger for offshore markets, with regional stocking points in Chengdu and Dubai serving onshore spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment defensive moat. API Specification 7-1 and ISO 10424-1 certification timelines exceeding fourteen months freeze smaller competitors out of premium offshore tenders, cementing incumbent positioning.
For Market Incumbents: Compound captive synthesis advantages by expanding thermally stable cutter capacity in the United States or Ireland before Chinese substrate quality closes the performance gap. Deepen backward integration into synthetic diamond feedstock production to neutralize supply allocation risk during demand surges. Defend against hybrid bit specialists eroding the fixed-cutter versus roller-cone binary by acquiring formation-specific design boutiques in the Permian Basin or Vaca Muerta. For New Entrants and Emerging Players: Anchor in geothermal energy applications where hybrid bit architectures bypass entrenched PDC and tricone specialization boundaries and ISO certification requirements remain less stringent than offshore oil and gas. Target Kenya's Rift Valley and Iceland's basalt provinces where extreme temperature specifications favor nimble engineering over scale economies. Pursue technology transfer partnerships under India's PLI scheme for oilfield equipment to establish domestic cutter synthesis foothold without greenfield capital intensity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because integrated drilling service bundling compresses the addressable market for standalone bit manufacturers and regulatory compliance costs compound scale advantages. Target acquisition archetype: pure-play bit specialists with formation-specific IP in unconventional shale or geothermal hard-rock, trading below replacement cost of captive synthesis capacity. Watch EPA methane rule enforcement timelines as inflection signal—accelerated implementation compresses non-productive time allowances and elevates premium bit demand faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| Cutter Synthesis Capacity Expansion | Captive substrate production insulates margin from three-facility supply concentration. |
| Hybrid Bit Architecture Development | Combining PDC shearing with roller-cone impact fragments traditional vendor specialization boundaries. |
| Digital Twin Integration Partnership | Real-time wear prediction algorithms converge with automated rig controls in Brazil's pre-salt fields. |
| Geothermal Application Engineering | Kenya's Rift Valley and Iceland's Krafla field specifications exceed conventional thermal limits. |
| India PLI Scheme Localization | Production-linked incentive framework subsidizes domestic bit manufacturing capacity expansion. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance patterns and procurement specifications. Drilling engineering directors at offshore contractors, bit design leads at integrated service companies, procurement officers at national oil companies, and maintenance supervisors at onshore rig fleets provided operational validation. Secondary sources included API specification databases, ANP local content registries, EPA enforcement action records, and customs trade flows for cutter substrate imports. Bottom-up triangulation across individual well cost records and top-down reconciliation against drilling activity forecasts ensured segment-level consistency.
Sensitivity analysis around cutter durability assumptions and thermal stability thresholds frames the forecast envelope across the projection horizon. Segmentation dimensions modeled include bit type architecture, application intensity tier, end user sophistication level, and material grade specification. CAGRs derive from drilling activity trajectory modeling, rig fleet composition shifts, and replacement rate elasticity to footage-per-run economics. Industry-specific inputs encompass pre-salt carbonate formation hardness profiles, Permian Basin silica content abrasiveness indices, and geothermal bottom-hole temperature exposure bands.
Material uncertainties—regulatory enforcement acceleration, synthetic diamond feedstock supply disruption, and petroleum engineering talent rotation toward digital roles—sit outside the modeled envelope. Forecasts reflect assumptions about technology adoption curves and operator capital discipline without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Coal Mining Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Well Test Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Coiled Tubing Services Market