
 Russia Oil and Gas EPC Market | 2026-2036
Russia Oil and Gas EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Oil and Gas EPC Market Analytics
Modular fabrication and digital twin integration is fragmenting traditional project delivery models across Russia's hydrocarbon belt. Saipem SpA leverages its Arctic-class vessel fleet to anchor complex offshore installation campaigns in ice-prone waters. VELESSTROY sustains dominant domestic market share through deep relationships with Gazprom and Rosneft, while TechnipFMC PLC differentiates via subsea production system expertise tied to Sakhalin developments.
Russia Oil and Gas EPC encompasses the integrated engineering, procurement, and construction services required to deliver hydrocarbon production, processing, and transport infrastructure, typically involving steel-intensive modules rated for temperatures below minus fifty degrees Celsius and pressure vessels conforming to GOST R standards. The primary commercial purpose centers on converting geological reserves into monetizable flows through fixed-asset installation. Upstream project types absorb the largest capital allocation as greenfield developments in Eastern Siberia and the Arctic advance, while digital technology deployment represents the fastest-expanding service layer as operators mandate real-time asset monitoring. Maintenance services command durable margin pools given Russia's aging Soviet-era refining base and the technical complexity of sustaining output from mature fields.
Russia's Federal Agency for Technical Regulation and Metrology (Rosstandart) enforces GOST certification for equipment used in hazardous production facilities, directly shaping contractor qualification requirements and import substitution timelines. The Ministry of Natural Resources and Environment administers subsoil use licensing with escalating local content thresholds that redirect procurement toward domestic fabricators and engineering houses. Stakeholders must monitor how sanctions architecture evolution affects technology transfer pathways and whether Russian operators accelerate partnerships with Asian EPC firms to bridge capability gaps in liquefaction and Arctic construction.
Market Dynamics
Arctic LNG project development is forcing EPC contractors to reconfigure delivery models around modular fabrication yards and ice-class marine logistics. Rosstandart's evolving GOST certification timelines compress procurement windows while localization mandates redirect equipment sourcing toward domestic fabricators.
Growth Catalysts
- Ministry of Industry and Trade localization mandates:Domestic content thresholds in subsoil licensing agreements redirect procurement toward Russian engineering houses and module fabricators.
- Arctic LNG liquefaction capacity expansion:Novatek's Yamal and Gydan peninsula developments sustain contractor demand for cryogenic construction and ice-resistant infrastructure.
- Eastern Siberia greenfield development:Greenfield oil and gas projects in the Irkutsk and Krasnoyarsk regions require integrated EPC services for remote site development.
Market Restraints
- Specialized alloy input cost volatility:Nickel and chromium price fluctuations for cryogenic-grade stainless steel compress fixed-price contract margins.
- Arctic construction labor pool concentration:Qualified welders certified for sub-minus-forty-degree operations concentrate in the Yamal-Nenets Autonomous Okrug, creating geographic supply bottlenecks.
- Technology transfer restrictions:Sanctions architecture limits access to Western liquefaction heat exchanger designs and digital twin software platforms.
Strategic Opportunities
- Far Eastern Federal District LNG export infrastructure:Sakhalin and Vladivostok corridor developments offer underpenetrated geography for offshore pipeline and subsea system contractors.
- Digital twin and predictive maintenance convergence:Real-time asset monitoring integration with legacy Soviet-era refining infrastructure creates service expansion potential.
- Asian EPC partnership channels:Chinese and South Korean engineering firms offer alternative technology transfer pathways for liquefaction and Arctic marine construction.
Industry Challenges
- Cryogenic welding certification timelines:Rosstandart qualification requirements for hazardous production facilities extend project staffing lead times.
- Soviet-era refining base integration complexity:Modern automation systems must interface with legacy mechanical control infrastructure without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Oil and Gas EPC Market |
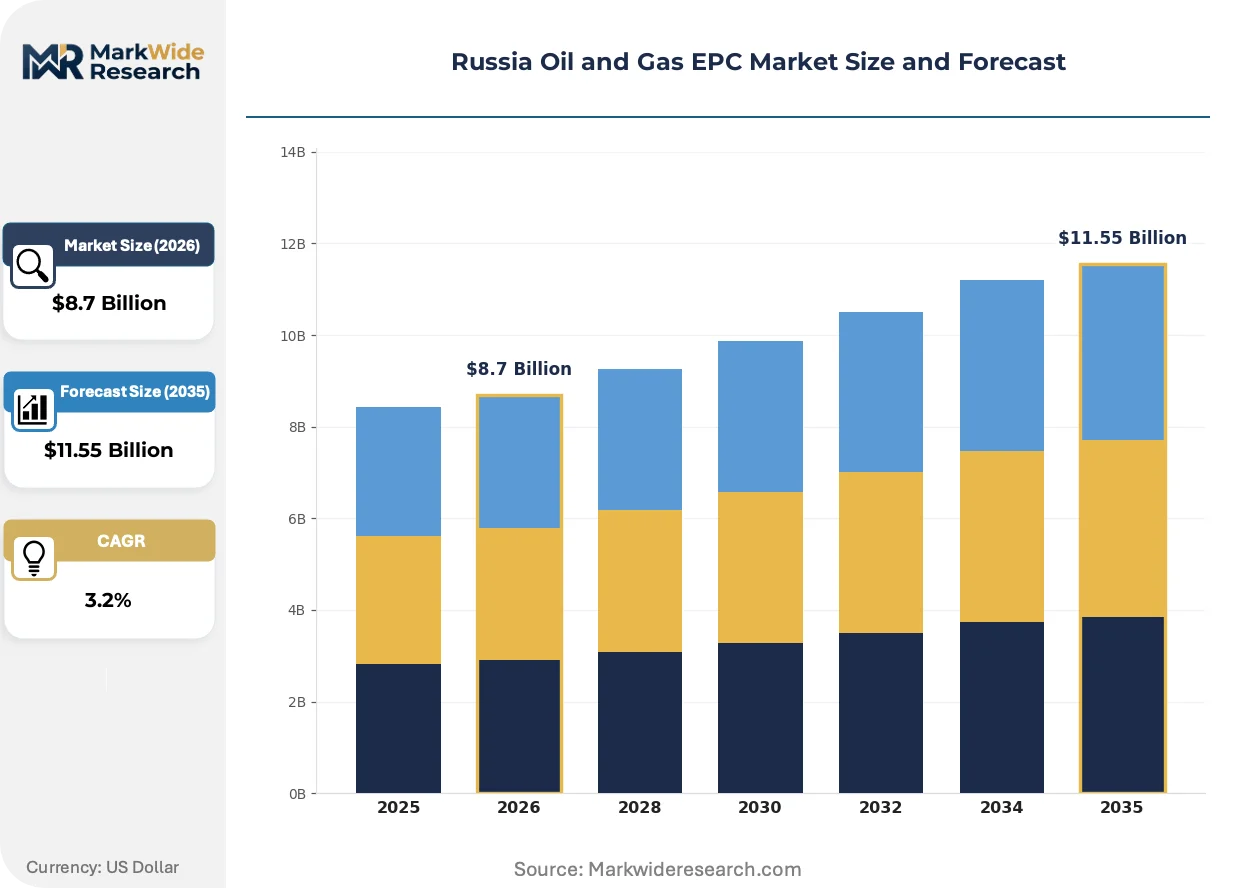
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Upstream, Midstream, Downstream, Refining Service Type: Engineering, Procurement, Construction, Maintenance Technology: Traditional, Digital, Automated, Hybrid End User: National Oil Companies, Independent Operators, Consortiums, Service Providers |
| Companies Covered | Petrofac Limited, VELESSTROY, Saipem SpA, Assystem SA, Linde plc, McDermott International Inc., Hyundai Heavy Industries Co. Ltd, Daelim Industrial Co., Ltd., TechnipFMC PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Oil and Gas EPC Market Evolving Landscape
Digital infrastructure deployment is compressing traditional EPC project timelines while Rosstandart certification evolution redefines equipment qualification protocols. Contractor differentiation increasingly hinges on Arctic execution capability and modular fabrication integration.
Digital twin technology is virtualizing asset commissioning and operational handover processes. Gazprom and Rosneft mandate real-time simulation platforms for greenfield developments in Eastern Siberia. This virtualization compresses mechanical completion schedules and reduces offshore installation campaigns.
Rosstandart's hazardous production facility certification framework tightens equipment traceability requirements for subsoil use licensees. GOST R conformity assessment now extends to imported digital control systems and safety instrumented functions. Arctic LNG developers accelerate domestic software platform adoption to maintain compliance timelines.
Integrated service contracting displaces discrete engineering and construction procurement. Operators bundle FEED, procurement, and commissioning under single-source agreements to reduce interface risk. This consolidation concentrates in the Yamal-Nenets Autonomous Okrug where project complexity and remote logistics favor unified accountability.
Russia Oil and Gas EPC Market Segmentation
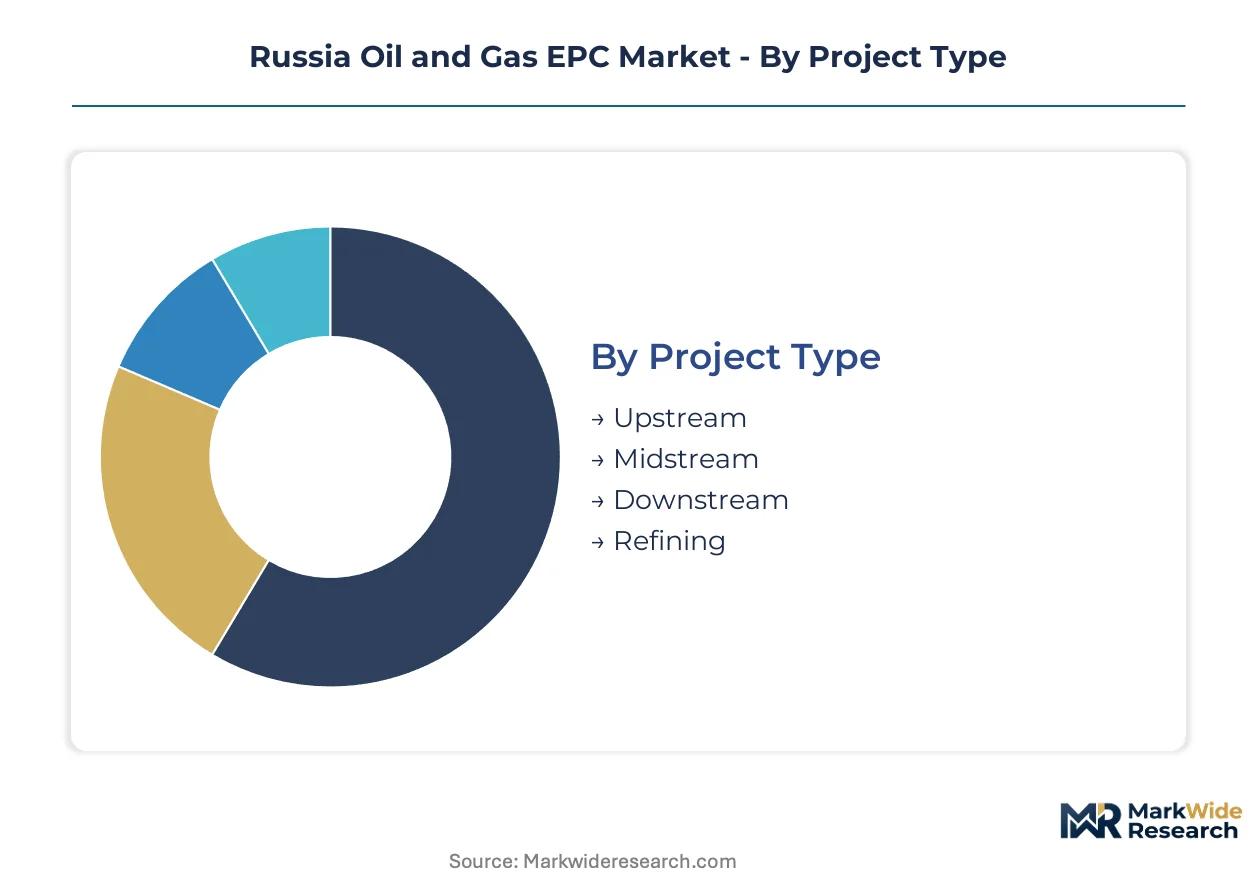
Segmentation in Russia's oil and gas EPC market reveals how Arctic project economics, localization mandates, and technology transfer constraints reshape contractor specialization. Each dimension exposes distinct capability requirements and margin structures.
Project Type:
Application focus determines capital intensity, execution risk, and regulatory exposure across the hydrocarbon value chain.
- Upstream:Greenfield developments in Eastern Siberia and the Arctic demand integrated drilling, production, and gathering systems rated for sub-minus-forty-degree operation. Novatek's Yamal LNG and Gazprom's Bovanenkovo field sustain contractor demand for cryogenic wellhead infrastructure and extended-reach drilling platforms.
- Midstream:Pipeline transport and gas processing infrastructure connects remote production to export corridors. The Power of Siberia trunkline and planned Far Eastern LNG export terminals concentrate procurement in the Irkutsk region and Sakhalin.
- Downstream:Natural gas liquids fractionation and condensate stabilization facilities serve domestic petrochemical feedstock needs.
- Refining:Soviet-era facility modernization and hydrocracker additions address product quality upgrades and capacity debottlenecking.
Upstream commands the established base. The steepest expansion runs through Midstream as export corridor development accelerates.
Service Type:
Margin capture varies by contract phase, with early-stage engineering and late-stage maintenance offering contrasting risk-return profiles.
- Engineering:Front-end engineering design and detailed engineering for Arctic-class facilities require GOST-certified design institutes and specialized cryogenic process simulation capability. FEED contracts for Yamal-Nenets developments increasingly bundle modularization planning with logistics optimization.
- Procurement:Equipment sourcing confronts Rosstandart certification timelines and Ministry of Industry and Trade localization thresholds. Cryogenic heat exchangers, subsea trees, and ice-class marine loading arms face extended qualification periods.
- Construction:Modular yard fabrication and remote site assembly dominate Arctic project delivery. Qualified welders certified for hazardous production facilities concentrate in the Yamal-Nenets Autonomous Okrug.
- Maintenance:Turnaround services and predictive asset management sustain recurring revenue from Russia's aging refining base and mature Western Siberian fields.
Construction commands the established base. The steepest expansion runs through Maintenance as operators prioritize asset life extension over greenfield capital.
Technology:
Technology tier shapes project timeline compression, labor requirements, and sanctions exposure for Russian operators.
- Traditional:Conventional mechanical control systems and manual inspection protocols remain prevalent in brownfield refining and mature Western Siberian production. Lower capital cost and established supply chains sustain deployment despite efficiency limitations.
- Digital:Real-time monitoring platforms, predictive analytics, and cloud-based asset management systems mandate software localization under Rosstandart's evolving certification framework. Gazprom and Rosneft pilot digital twins for Eastern Siberian greenfields.
- Automated:Unmanned wellhead platforms and robotic inspection systems reduce Arctic labor exposure and logistics burden.
- Hybrid:Integrated architectures combining legacy mechanical infrastructure with targeted digital overlays address Soviet-era facility modernization constraints.
Traditional technology commands the established base. The steepest expansion runs through Digital as operators mandate virtualization to compress commissioning schedules.
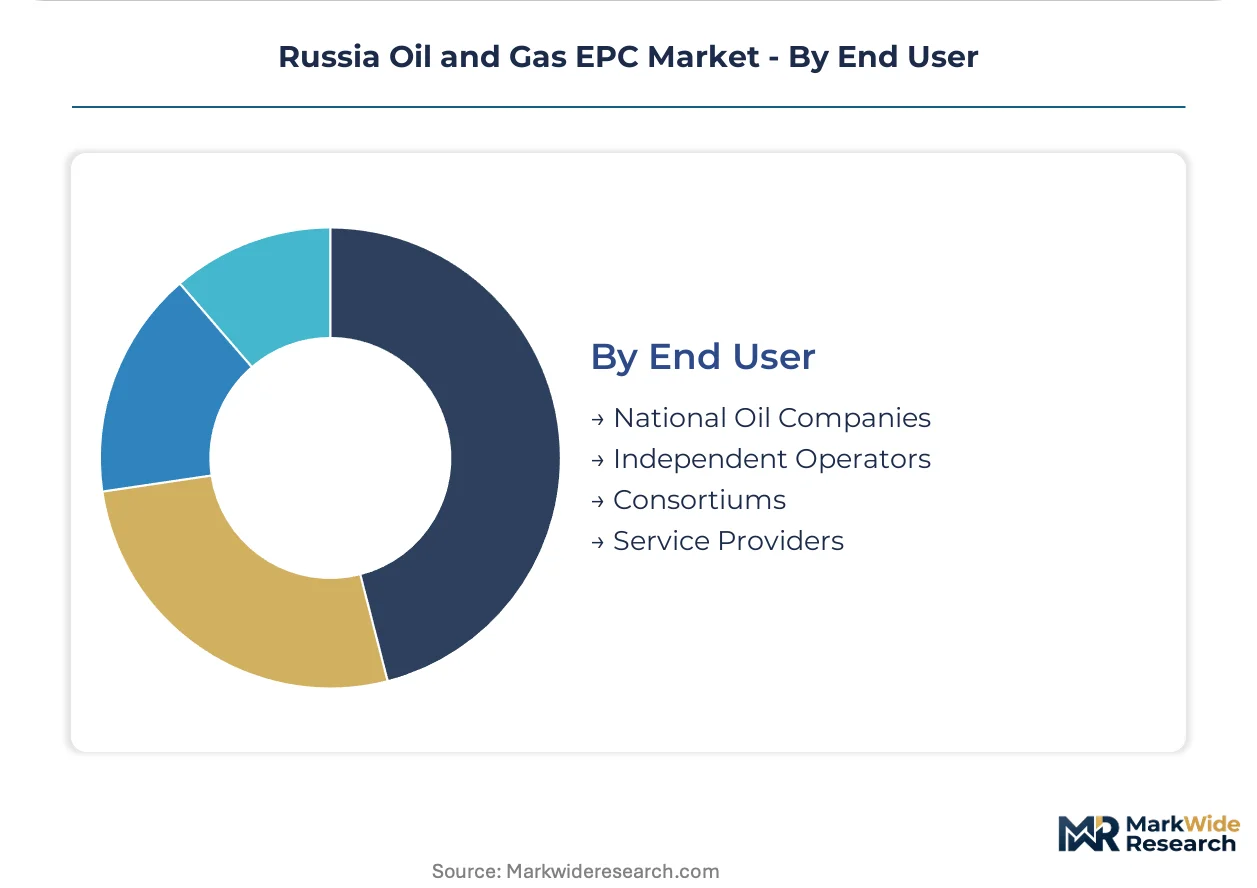
End User:
Customer type dictates contracting structure, local content requirements, and technology access pathways.
- National Oil Companies:Gazprom, Rosneft, and Transneft dominate capital allocation through state-mandated investment programs. Their procurement frameworks enforce stringent localization thresholds and favor established domestic EPC relationships.
- Independent Operators:Smaller producers in Eastern Siberia and the Volga-Ural region pursue fast-track development with simplified contracting structures and higher import tolerance.
- Consortiums:International partnerships for Arctic LNG and Far Eastern projects blend Russian state equity with Asian offtake commitments, creating hybrid procurement requirements.
- Service Providers:Drilling contractors and subsea specialists purchase modular support infrastructure and maintenance services through discrete procurement channels.
National Oil Companies command the established base. The steepest expansion runs through Consortiums as Novatek-led LNG projects attract Asian equity participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's LNG export corridors to Asian markets—principally China, Japan, and South Korea—channel EPC demand toward the Yamal-Nenets Autonomous Okrug and Far Eastern Federal District. These trade flows concentrate contractor activity in ice-prone construction zones.
Yamal-Nenets Autonomous Okrug
Novatek's Arctic LNG developments and Gazprom's Bovanenkovo field sustain demand for cryogenic wellhead infrastructure and modular fabrication yards. The Ministry of Industry and Trade enforces localization thresholds in subsoil licensing agreements. Nadym and Novy Urengoy host qualified welder pools certified for sub-minus-forty-degree operations.
Far Eastern Federal District
Sakhalin Island LNG export terminals and Vladivostok corridor infrastructure attract offshore pipeline and subsea system contractors. Rosstandart's GOST certification framework governs equipment qualification for hazardous production facilities. The Sakhalin-1 and Sakhalin-2 project clusters anchor marine construction activity.
Krasnoyarsk Krai
Eastern Siberia greenfield oil developments in the Vankor cluster require integrated drilling and production systems for remote site construction. The Ministry of Natural Resources and Environment administers subsoil use licensing with escalating local content requirements. Igarka and Norilsk serve as logistics hubs for Arctic module mobilization.
Irkutsk Oblast
The Power of Siberia trunkline and Kovykta gas condensate field drive midstream procurement for pipeline transport infrastructure. Federal Agency for Technical Regulation and Metrology certification timelines compress equipment sourcing windows. Bratsk and Ust-Kut concentrate fabrication capacity for eastern corridor development.
Murmansk Oblast
Arctic marine logistics and ice-class vessel support services enable LNG module export to Asian markets. Northern Sea Route transit regulations reshape seasonal construction scheduling. Murmansk port infrastructure anchors year-round marine operations despite ice constraints.
Russia Oil and Gas EPC Market Competitive Landscape
On the supply side, the industry is bifurcated between domestic fabricators with state-backed relationships and international specialists with Arctic execution capability. Tier-one contractors command integrated FEED-procurement-construction contracts for megaprojects. Three archetypes dominate: state-aligned domestic engineering houses, Western technology providers with sanctions-constrained access, and Asian fabricators offering alternative liquefaction pathways. Competitive moves center on modular yard capacity expansion and Asian partnership formation to bridge technology transfer gaps.
Among international specialists, Saipem SpA and TechnipFMC PLC occupy positions shaped by their respective vessel fleet and subsea system capabilities. VELESSTROY exemplifies the state-aligned domestic archetype through its established relationships with Gazprom and Rosneft. Hyundai Heavy Industries Co. Ltd represents the Asian fabrication pathway that Russian operators increasingly pursue for Arctic marine construction and module integration.
| Leading Market Players |
|---|
| Petrofac Limited |
| VELESSTROY |
| Saipem SpA |
| Assystem SA |
| Linde plc |
| McDermott International Inc. |
| Hyundai Heavy Industries Co. Ltd |
| Daelim Industrial Co., Ltd. |
| TechnipFMC PLC |
| Others |
Value Network & Pricing Analysis
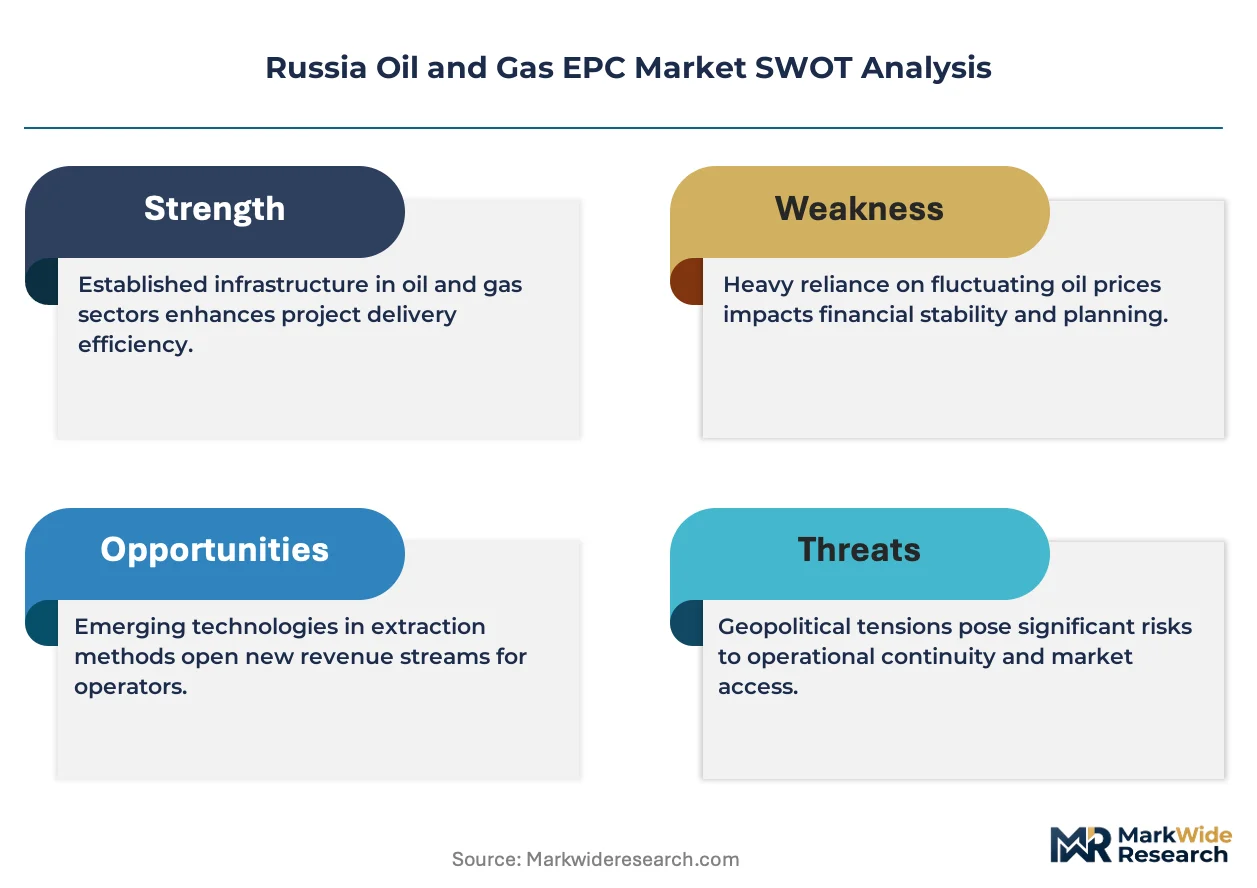
Nadym and Novy Urengoy's concentrated welder pools for sub-minus-forty-degree certification compress labor supply elasticity, amplifying contractor pricing power in fixed-price Arctic LNG contracts. The Ministry of Industry and Trade localization mandates redirect equipment procurement toward domestic fabricators, reshaping cost structures across the Yamal-Nenets Autonomous Okrug.
Pricing Analysis
Next-generation digital twin platforms command premium positioning over traditional mechanical control systems, while legacy Soviet-era infrastructure maintenance sits at discounted rates. Three-tier pricing structure across premium Arctic-class, standard onshore, and economy brownfield refurbishment levels stratifies the market. Pricing pressure stems from nickel and chromium volatility in cryogenic-grade stainless steel, squeezing fixed-price contract margins. National oil companies exhibit lowest price sensitivity given state-backed investment programs, while independent operators in Eastern Siberia prioritize cost minimization.
Supply Chain Analysis
Module fabrication capacity concentrates in South Korea, China, and domestic Russian yards near Murmansk and Novy Urengoy. Critical inputs draw from cryogenic heat exchangers, subsea production trees, and ice-class marine loading arms. Single-source vulnerability runs through Western liquefaction technology transfer restrictions under sanctions architecture. Distribution runs through integrated FEED-procurement-construction contracts that bundle accountability under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure anchored in regulatory entrenchment. Rosstandart's GOST certification timelines and Ministry of Industry and Trade localization thresholds create switching costs that protect incumbent positions.
For Market Incumbents: Entrench through backward integration into modular fabrication yards in the Yamal-Nenets Autonomous Okrug and certification investment in Rosstandart's hazardous production facility framework. Asian EPC partnership formation addresses technology transfer restrictions while defending against emerging Chinese engineering houses.
For New Entrants and Emerging Players: Pursue white-space in Far Eastern Federal District offshore pipeline and subsea system contracting, where Sakhalin corridor development remains underpenetrated. Target predictive maintenance services for Soviet-era refining infrastructure through digital twin integration as the most penetrable service layer.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-aligned domestic engineering houses seeking capital for Arctic vessel fleet expansion. Five-to-ten-year viability hinges on Northern Sea Route transit volume growth as the inflection signal to monitor for module export demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Yard Capacity Expansion | Arctic LNG developers require domestic fabrication to meet Ministry of Industry and Trade localization thresholds. |
| Asian EPC Partnership Formation | South Korean and Chinese engineering firms bridge liquefaction technology gaps created by sanctions restrictions. |
| Digital Twin Platform Deployment | Gazprom and Rosneft mandates for real-time asset monitoring compress commissioning schedules in Eastern Siberia. |
| Cryogenic Welder Certification Investment | Rosstandart qualification requirements extend project staffing lead times, creating certified labor scarcity premiums. |
| Ice-Class Vessel Fleet Acquisition | Northern Sea Route year-round operations demand marine logistics capabilities anchored in Murmansk port infrastructure. |
Research Methodology
Operator-level perspectives from EPC contract managers, procurement leads at Gazprom and Rosneft, Rosstandart certification officials, and modular fabrication yard directors anchored the qualitative base. Secondary validation drew from subsoil licensing records, customs equipment import data, Ministry of Natural Resources and Environment regulatory filings, and project development databases. Bottom-up project pipeline assessment triangulated against top-down hydrocarbon investment flow analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include project type, service type, technology tier, and end user category. CAGRs derived from capital expenditure flow analysis and contractor backlog trajectories. Forecast inputs incorporated Arctic LNG liquefaction capacity timelines and Northern Sea Route transit regulations.
Sensitivities concentrate around sanctions architecture evolution, Rosstandart certification timeline compression, and Asian technology transfer pathway durability. Quarterly review of module fabrication yard utilization rates and cryogenic-grade alloy price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada LNG Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Drilling Services Market