
 United States Coiled Tubing Market | 2026-2036
United States Coiled Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Coiled Tubing Market Analytics
Domestic steel mills and specialty alloy producers in the Ohio River Valley is pivoting toward higher-grade chromium-molybdenum feedstock output to serve coiled tubing OEMs. Baker Hughes Company leverages integrated metallurgy labs to sustain proprietary grade development for sour-service environments. Halliburton Company anchors Gulf Coast distribution through owned spooling and logistics yards in Houston and Corpus Christi. Schlumberger Limited differentiates via real-time fatigue-monitoring systems embedded in its coiled tubing fleet.
Coiled tubing consists of continuous, seam-welded steel or composite pipe manufactured in long continuous lengths, typically ranging from one to over six inches in outer diameter and engineered to withstand repeated bending cycles around a gooseneck and reel. The product enables live-well intervention, drilling, and completion operations without requiring costly well shut-ins or rig mobilization. Standard coiled tubing still occupies the largest volume share across the installed base, though special grade variants command disproportionate margin pools due to corrosion-resistant alloy premiums and shorter replacement cycles. Well intervention applications generate the most frequent deployment cycles, while completion work is expanding fastest as operators push longer lateral lengths in tight-rock formations.
FAA regulations govern air transport of coiled tubing reels and associated pressure-control equipment across state lines, while OSHA standards enforce rig-floor handling protocols that directly influence equipment specification requirements. API 5ST and ASTM A606 specifications set the baseline material and dimensional standards that manufacturers must meet for downstream operator acceptance. Stakeholders should monitor how EPA methane emission rules and evolving state-level flaring restrictions reshape the economics of well intervention frequency and coiled tubing utilization intensity.
Market Dynamics
Permian Basin operators are extending lateral lengths beyond 15,000 feet, forcing coiled tubing service providers to deploy larger-diameter strings and higher-tensile grades to reach toe-stage interventions without multiple trips. This geological imperative is compressing equipment replacement cycles and reshaping fleet composition across the domestic installed base.
Growth Catalysts
- EPA Methane Rules:Tightened emission monitoring mandates accelerate well intervention frequency as operators seal leaking completions and replace faulty gas-lift valves to avoid penalties.
- Hydrogen-Blended Natural Gas Pilots:Emerging hydrogen injection projects in Texas and Louisiana require corrosion-resistant coiled tubing alloys for blended-fuel well maintenance, creating incremental demand for sour-service grades.
- Extended-Reach Drilling:Permian and Bakken operators now routinely drill 3-mile laterals, necessitating continuous coiled tubing reach that conventional jointed pipe cannot match.
Market Restraints
- Chromium-Molybdenum Feedstock Concentration:Domestic specialty steel production clusters in the Ohio River Valley, exposing OEMs to single-region weather and logistics disruptions.
- API 5ST Certification Timeline:Material qualification protocols for new alloy grades require 18-24 months of fatigue testing, delaying product commercialization.
- Composite Pipe Substitution:Fiber-reinforced thermoplastic alternatives gain traction in low-pressure applications, displacing standard-grade steel coiled tubing in certain gas-well interventions.
Strategic Opportunities
- Real-Time Fatigue Monitoring:Embedded sensor systems that track cumulative bending cycles enable predictive maintenance contracts and extend string life.
- North Dakota Bakken Expansion:Underpenetrated refracturing activity in older Bakken wells offers service companies a secondary market beyond primary Permian exposure.
- IRA Carbon Capture Incentives:Federal tax credits for CO2 injection wells drive demand for corrosion-resistant coiled tubing in Class VI disposal and enhanced oil recovery operations.
Industry Challenges
- Weld Inspector Certification Gap:API 5ST mandates ultrasonic and electromagnetic inspection protocols that exceed current NDT technician supply in Gulf Coast service hubs.
- Fleet Modernization Capex:Reel trailer upgrades to accommodate 2-3/8 inch and larger diameter strings require $2-4 million per unit, straining regional service company balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Coiled Tubing Market |
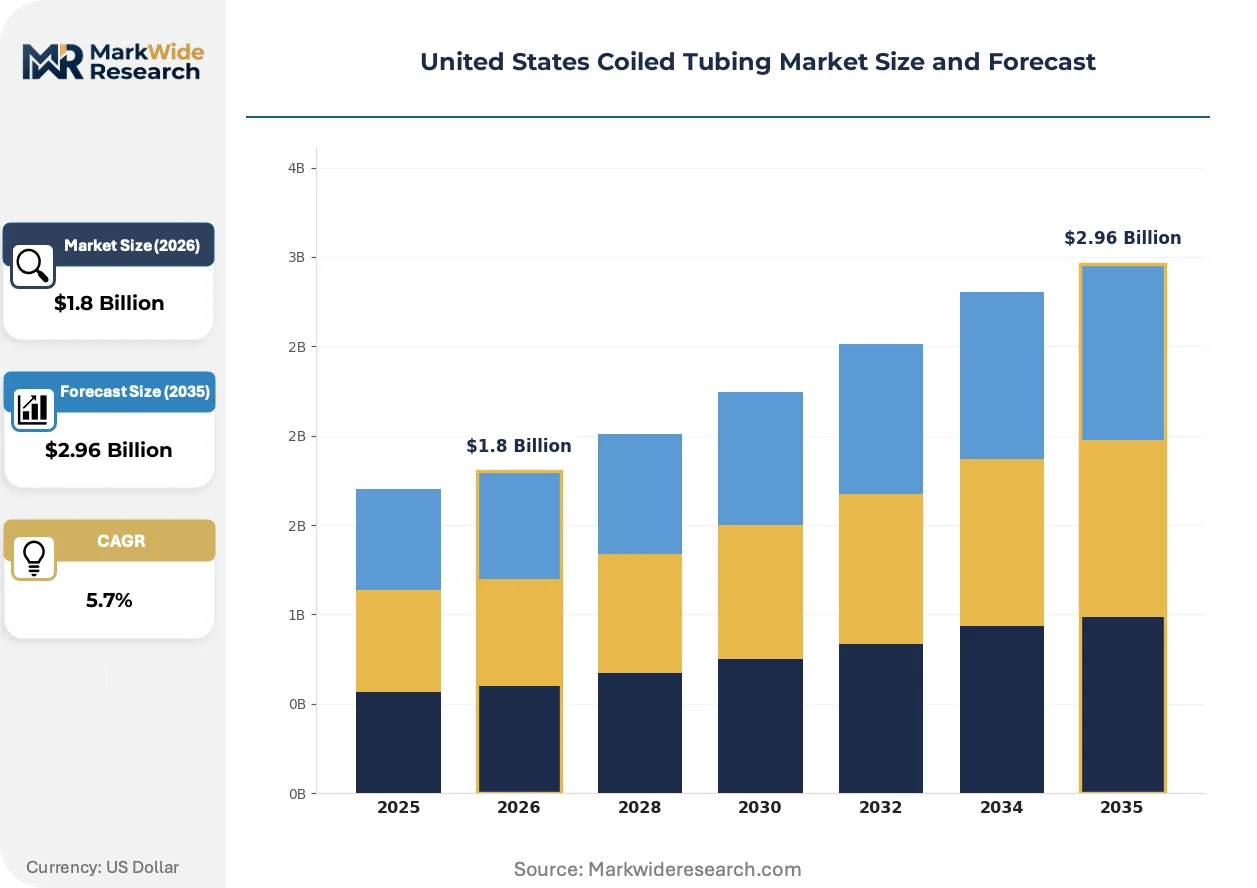
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Coiled Tubing, Special Grade Coiled Tubing, Composite Coiled Tubing, Heavy Wall Coiled Tubing Application: Well Intervention, Drilling, Completion, Production Operations End User: Oil & Gas Producers, Service Companies, Offshore Operators, Onshore Operators Deployment: Onshore Deployment, Offshore Deployment, Inland Waters Deployment, Remote Deployment |
| Companies Covered | Baker Hughes Company, Halliburton Company, Schlumberger Limited, Weatherford International plc, Calfrac Well Services Ltd, NOV Inc, STEP Energy Services, Superior Energy Services, Key Energy Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Coiled Tubing Market Evolving Landscape
Digital instrumentation and advanced metallurgy are converging to transform coiled tubing from a commoditized consumable into a data-generating asset. Service companies now compete on predictive analytics capabilities rather than fleet size alone.
Composite-reinforced coiled tubing is converging with sour-service alloy cores to create hybrid strings that withstand both corrosive reservoir fluids and high-cycle fatigue. Permian operators with high-H2S acreage positions are piloting these configurations for 10,000-psi interventions. The structural result is a bifurcation in fleet strategy, with premium hybrid strings commanding day-rate premiums over standard carbon-steel alternatives.
DOT pipeline safety standards now mandate material traceability from melt source through final spooling, enforced by PHMSA audits of coiled tubing used in gas-lift and velocity-string applications. Manufacturers must maintain lot-level documentation for 10-year retention periods. Gulf Coast distributors have responded by integrating blockchain-based tracking systems that automate compliance documentation for operator audits.
Operator procurement patterns now favor integrated service packages combining coiled tubing, nitrogen pumping, and real-time downhole telemetry under single-source contracts. Independent service companies in Oklahoma are losing share to bundled providers. This consolidation is most pronounced among supermajors operating Delaware Basin assets, where procurement teams have reduced approved vendor lists by 40 percent since 2022.
United States Coiled Tubing Market Segmentation
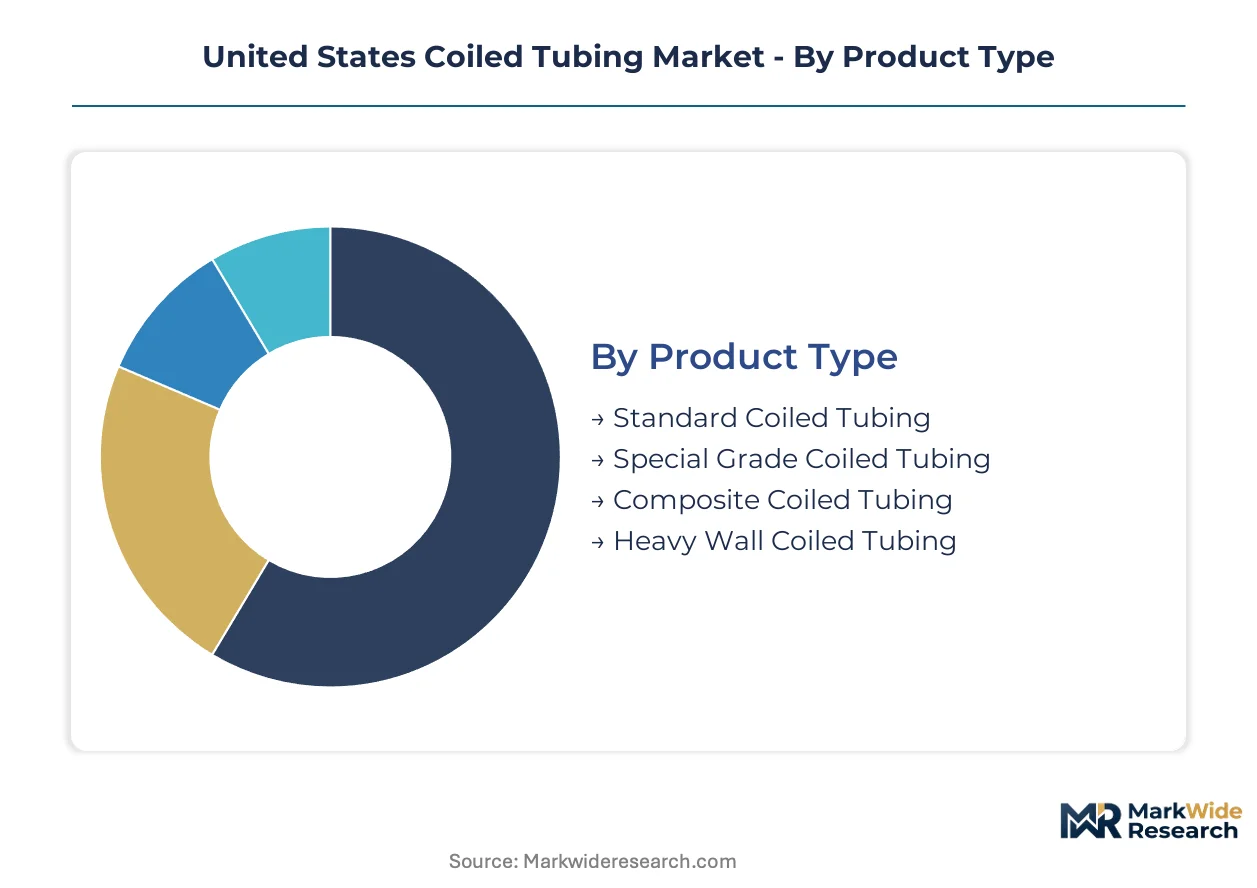
Segmentation reveals how equipment replacement cycles and intervention intensity vary across product grades, applications, and deployment settings. Understanding these divisions clarifies where capital concentrates and which pockets offer service providers the steepest margin expansion.
Product Type:
Upgrade cycles diverge sharply between commodity-grade strings and engineered alloys, with replacement frequency driven by fatigue limits and corrosion exposure rather than calendar age.
- Standard Coiled Tubing:Carbon-steel construction meeting API 5ST baseline specifications dominates the installed fleet by unit count. Permian Basin operators consume the highest volumes for routine nitrogen lifts and basic wellbore cleanouts, though day-rate compression limits margin capture.
- Special Grade Coiled Tubing:Chromium-molybdenum and nickel-alloy formulations resist hydrogen sulfide cracking in sour-service environments. Bakken and Delaware Basin operators with high-H2S acreage are accelerating procurement of these grades, accepting 40-60% day-rate premiums for extended string life.
- Composite Coiled Tubing:Fiber-reinforced thermoplastic construction offers weight reduction for offshore crane-limited platforms.
- Heavy Wall Coiled Tubing:Thicker-walled variants withstand higher internal pressures for deep-set plug milling in extended-reach laterals.
Volume placements concentrate in Standard Coiled Tubing; the faster expansion belongs to Special Grade Coiled Tubing.
Application:
Intervention frequency and technical complexity determine equipment utilization rates and the premium achievable for specialized strings.
- Well Intervention:Live-well operations including matrix acidizing, nitrogen lifting, and scale removal generate the highest deployment cycles per string. Texas and North Dakota service companies run these programs continuously, compressing equipment amortization periods.
- Completion:Plug-and-perf operations in multi-stage horizontal wells demand continuous coiled tubing reach that jointed pipe cannot match. Oklahoma operators pushing 3-mile laterals are expanding this segment fastest.
- Drilling:Underbalanced and slim-hole drilling applications utilize coiled tubing for continuous circulation.
- Production Operations:Velocity strings and gas-lift mandrel installations provide artificial lift support.
Well Intervention generates the most frequent equipment turns; Completion work is climbing the fastest as lateral lengths extend.
End User:
Procurement scale and technical specification authority vary dramatically between integrated majors and independent service providers.
- Oil & Gas Producers:Supermajors and large independents in the Delaware Basin have consolidated vendor lists by 40% since 2022, favoring bundled service packages over standalone coiled tubing procurement.
- Service Companies:Regional operators in Oklahoma and the Texas Panhandle compete on fleet availability and spooling logistics rather than metallurgical differentiation.
- Offshore Operators:Gulf of Mexico platform managers prioritize weight reduction and corrosion resistance for salt-spray environments.
- Onshore Operators:Permian and Bakken focused accounts drive the bulk of domestic demand volume.
Onshore Operators command the largest equipment allocation; Offshore Operators are gaining share fastest as shelf redevelopment accelerates.
Deployment:
Logistics infrastructure and mobilization constraints shape fleet positioning and capital allocation across terrain types.
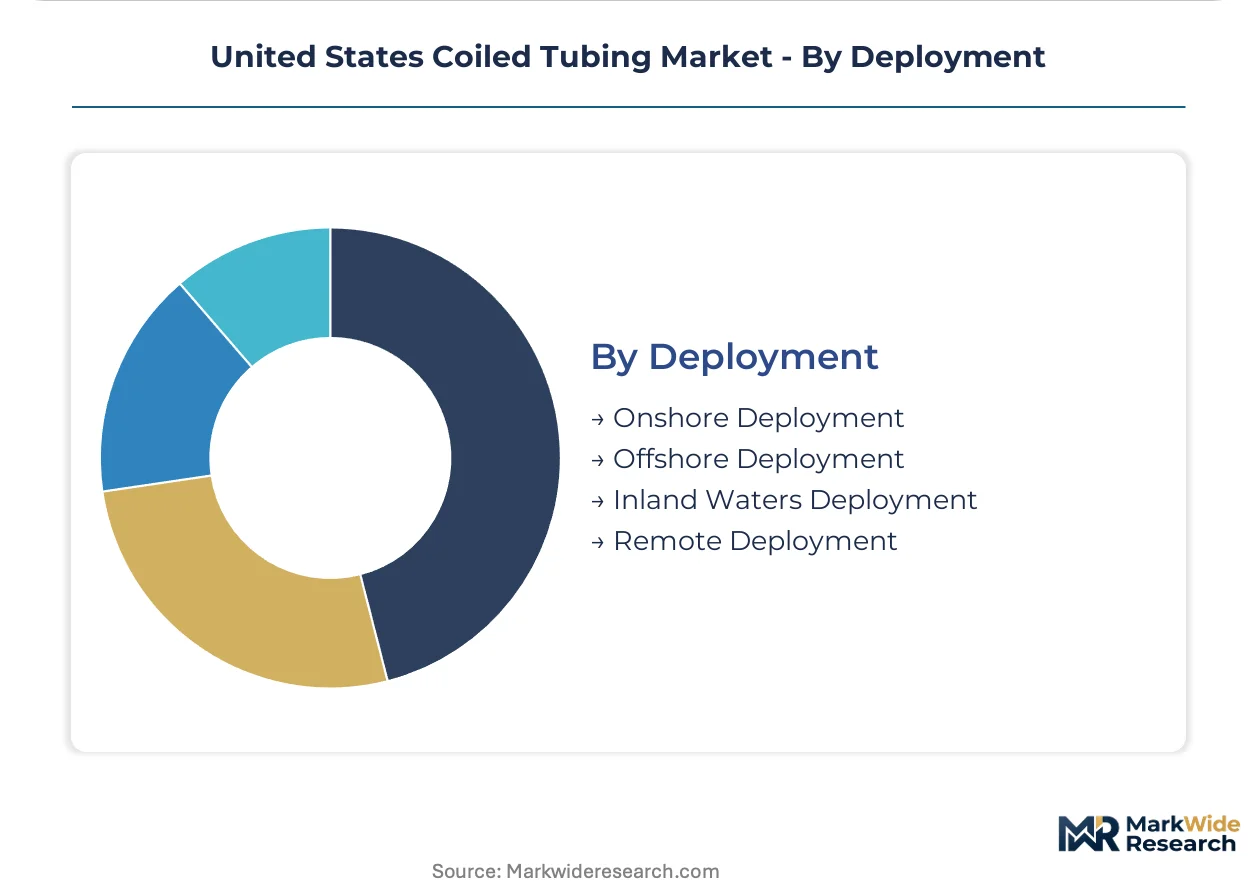
- Onshore Deployment:Road-mobile reel trailers serve the Permian, Bakken, and Anadarko basins through owned yards in Houston, Midland, and Williston. This terrain absorbs over 80% of domestic coiled tubing utilization.
- Offshore Deployment:Platform-based spooling systems and marine-rated pressure control equipment command specialized certification under DOT and BSEE protocols.
- Inland Waters Deployment:Barge-mounted units serve Louisiana marsh and coastal restoration projects.
- Remote Deployment:Helicopter-transportable reel systems access Alaska North Slope and other infrastructure-constrained regions.
Onshore Deployment absorbs the dominant equipment hours; Remote Deployment is expanding most quickly as frontier basins open.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium-molybdenum feedstock production clusters in the Ohio River Valley anchor domestic supply chains for coiled tubing manufacturers. This concentration shapes regional equipment deployment patterns and service company logistics strategies across the Lower 48.
Texas
Permian Basin operators drive the highest coiled tubing utilization intensity through extended-reach laterals exceeding 15,000 feet. EPA methane emission monitoring rules accelerate well intervention frequency as operators seal leaking completions to avoid penalties. Houston and Corpus Christi host the densest concentration of spooling yards and pressure-control equipment staging facilities.
North Dakota
Bakken shale producers are expanding refracturing activity in older wells, creating secondary demand beyond primary Permian exposure. OSHA rig-floor handling standards enforce equipment specification requirements that influence regional fleet composition. Williston serves as the logistics hub for road-mobile reel trailers accessing McKenzie and Williams counties.
Oklahoma
Anadarko Basin operators pushing 3-mile laterals are expanding completion work fastest among domestic sub-regions. FAA regulations govern air transport of coiled tubing reels across state lines from Oklahoma City distribution centers. Independent service companies in the Texas Panhandle compete on fleet availability rather than metallurgical differentiation.
Louisiana
Emerging hydrogen injection pilots in the Gulf Coast corridor require corrosion-resistant coiled tubing alloys for blended-fuel well maintenance. DOT pipeline safety standards mandate material traceability enforced by PHMSA audits of gas-lift applications. Barge-mounted units serve marsh restoration projects through inland waters deployment configurations.
Alaska
North Slope frontier development drives remote deployment expansion through helicopter-transportable reel systems. BSEE protocols govern platform-based spooling systems for offshore-rated pressure control equipment. Infrastructure constraints limit conventional road-mobile access, favoring specialized logistics providers.
United States Coiled Tubing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite-reinforced and sour-service alloy specializations. The vendor base stratifies across three tiers: integrated oilfield service conglomerates with captive metallurgy capabilities, regional operators competing on fleet availability and spooling logistics, and niche specialists developing hybrid composite-steel configurations. Consolidation pressure intensifies as supermajors reduce approved vendor lists by 40 percent since 2022. Dominant competitive moves include bundled service packaging combining coiled tubing with nitrogen pumping and real-time telemetry, alongside predictive maintenance contracts enabled by embedded fatigue-monitoring systems.
Within the integrated service tier, Baker Hughes Company, Halliburton Company, and Schlumberger Limited exemplify divergent strategic positioning. Baker Hughes leverages integrated metallurgy labs for proprietary grade development. Halliburton anchors Gulf Coast distribution through owned spooling and logistics yards. Schlumberger differentiates via real-time fatigue-monitoring systems embedded in fleet equipment. These three represent the archetype of technology-forward, vertically integrated providers capturing premium day-rates through predictive analytics capabilities rather than fleet scale alone.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton Company |
| Schlumberger Limited |
| Weatherford International plc |
| Calfrac Well Services Ltd |
| NOV Inc |
| STEP Energy Services |
| Superior Energy Services |
| Key Energy Services |
| Others |
Value Network & Pricing Analysis
NDT technician concentrations in Gulf Coast service hubs compress labor-cost differentials between premium inspection-grade strings and standard carbon-steel alternatives, widening pricing-tier spreads as API 5ST certification requirements tighten.
Pricing Analysis
Warranty bundling separates predictive maintenance contracts with embedded fatigue-monitoring sensors from unbundled equipment-only procurement. Three-tier pricing structure across premium sour-service alloys, standard API 5ST grades, and economy carbon-steel alternatives dominates transactional patterns. Cost compression in standard-grade segments intensifies because composite pipe substitution displaces steel in low-pressure gas-well applications. Independent service companies in Oklahoma exhibit highest price sensitivity, while Delaware Basin supermajors accept 40-60% premiums for corrosion-resistant chromium-molybdenum formulations.
Supply Chain Analysis
Freight costs from Ohio River Valley specialty steel mills to Permian Basin deployment yards represent a material share of landed equipment costs for domestic OEMs. Raw material supply draws from domestic chromium-molybdenum feedstock producers, Gulf Coast petrochemical complexes for composite resins, and Canadian nickel alloy suppliers. Single-region weather vulnerability in the Ohio River Valley creates supply chain risk during winter logistics disruptions. Distribution runs through owned spooling yards in Houston, Corpus Christi, and Williston serving road-mobile reel trailer fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over metallurgy labs and captive fatigue-testing capacity determines who captures sour-service grade premiums.
For Market Incumbents: Anchor Gulf Coast distribution density through owned logistics yards to defend against bundled service packaging from integrated competitors. Secure backward integration into Ohio River Valley specialty steel feedstock to mitigate single-source regional exposure. API 5ST certification timelines and NDT technician shortages represent persistent margin pressure points requiring workforce development investment. For New Entrants and Emerging Players: Capture refracturing activity in older Bakken wells where incumbent coverage remains thin relative to Permian saturation. Deploy helicopter-transportable reel systems for Alaska North Slope remote deployment as the most penetrable geography outside Lower 48 infrastructure density. Differentiate through hybrid composite-steel configurations piloted in high-H2S Permian acreage rather than competing on standard-grade fleet scale. For Investors and Strategic Acquirers: Re-rating potential sits with regional service companies possessing Williston Basin logistics infrastructure given Bakken refracturing acceleration. Long-term viability over the coming decade hinges on corrosion-resistant alloy capabilities as hydrogen-blended natural gas pilots expand. Watch EPA methane rule enforcement stringency as the signal indicating well intervention frequency and equipment utilization intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Feedstock | Captive chromium-molybdenum supply from Ohio River Valley mills insulates against weather-driven logistics disruptions. |
| Predictive Maintenance Contract Rollout | Embedded fatigue-monitoring sensors transform equipment from consumable to data-generating recurring revenue asset. |
| Bakken Refracturing Market Entry | Williston Basin logistics infrastructure accesses underpenetrated secondary demand beyond Permian saturation. |
| Hybrid Composite-Steel Development | Sour-service alloy cores with fiber-reinforced thermoplastic construction command day-rate premiums in high-H2S environments. |
| Blockchain Traceability Implementation | DOT-mandated material documentation for 10-year retention periods automates compliance for PHMSA audits. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coiled tubing service company operations directors, Permian Basin procurement managers, Ohio River Valley steel mill technical sales leads, and NDT certification program administrators combined with secondary validation. API 5ST specification documents, DOT PHMSA audit records, EPA methane monitoring compliance data, and OSHA rig-floor incident reports supplied triangulation points. Bottom-up equipment fleet counts and top-down energy service company revenue segmentation were reconciled.
Data-stream reconciliation across installation base surveys, day-rate pricing panels, and raw material procurement databases shaped the analytical framework. Segmentation dimensions modeled include product grade tier, application intensity, deployment terrain, and end-user procurement scale across the projection horizon. CAGRs were derived from equipment replacement cycle compression rates and intervention frequency elasticities. Forecast inputs incorporated lateral length extension trajectories and hydrogen injection pilot expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA methane rule enforcement variability and composite pipe substitution rates in low-pressure applications. Forecasts reflect documented assumptions regarding Permian Basin drilling activity and specialty steel feedstock capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Downhole Drilling Tools Market