
 East Africa Oil and Gas Market | 2026-2036
East Africa Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Oil and Gas Market Foresight
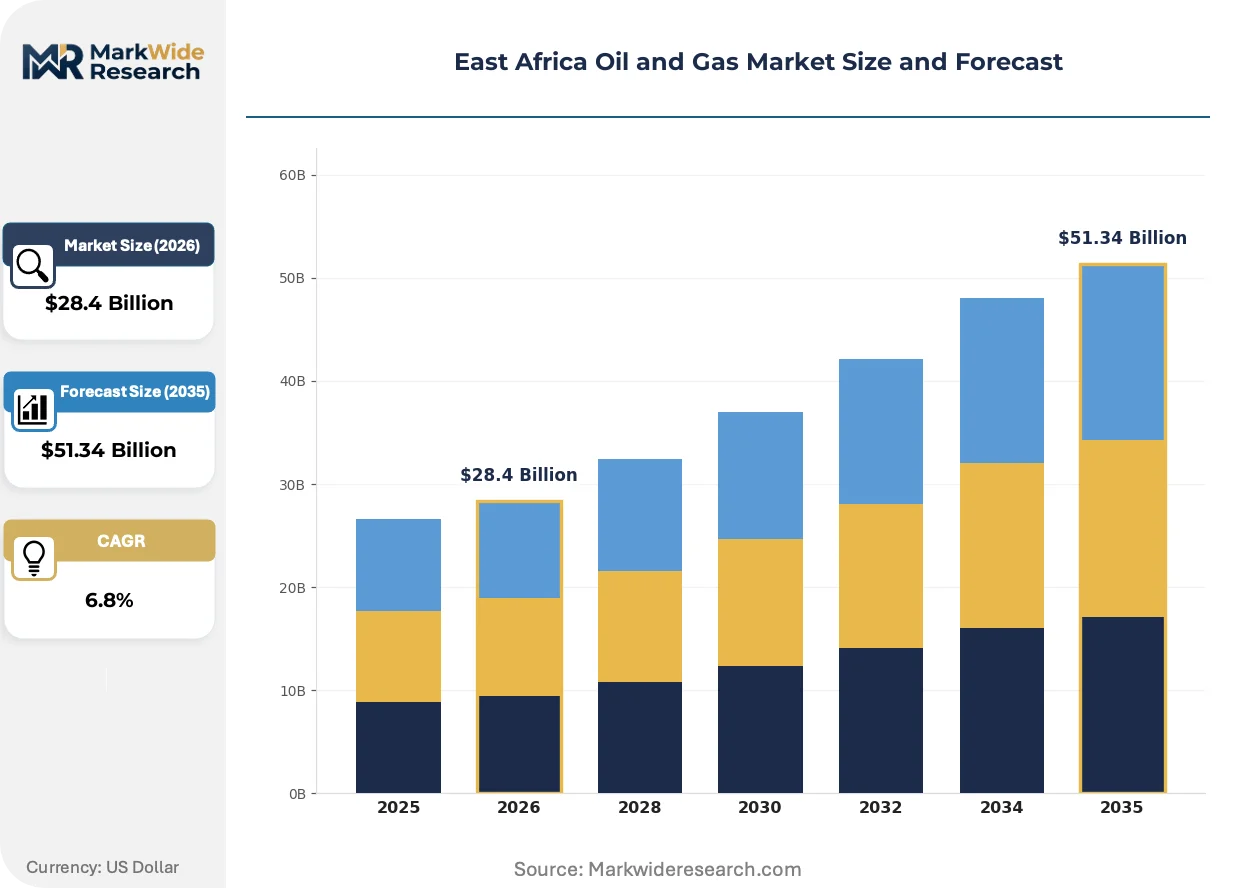
Specialized subsea engineering talent is collapsing across East African project corridors, tightening execution timelines for offshore developments. TotalEnergies leverages its pre-FID equity position in Mozambique's Area 1 to sustain long-cycle capital allocation. Tullow Oil anchors Ugandan upstream activity through its Tilenga project operations. China National Petroleum Corporation dominates South Sudanese production infrastructure through its Dar Petroleum Operating Company consortium.
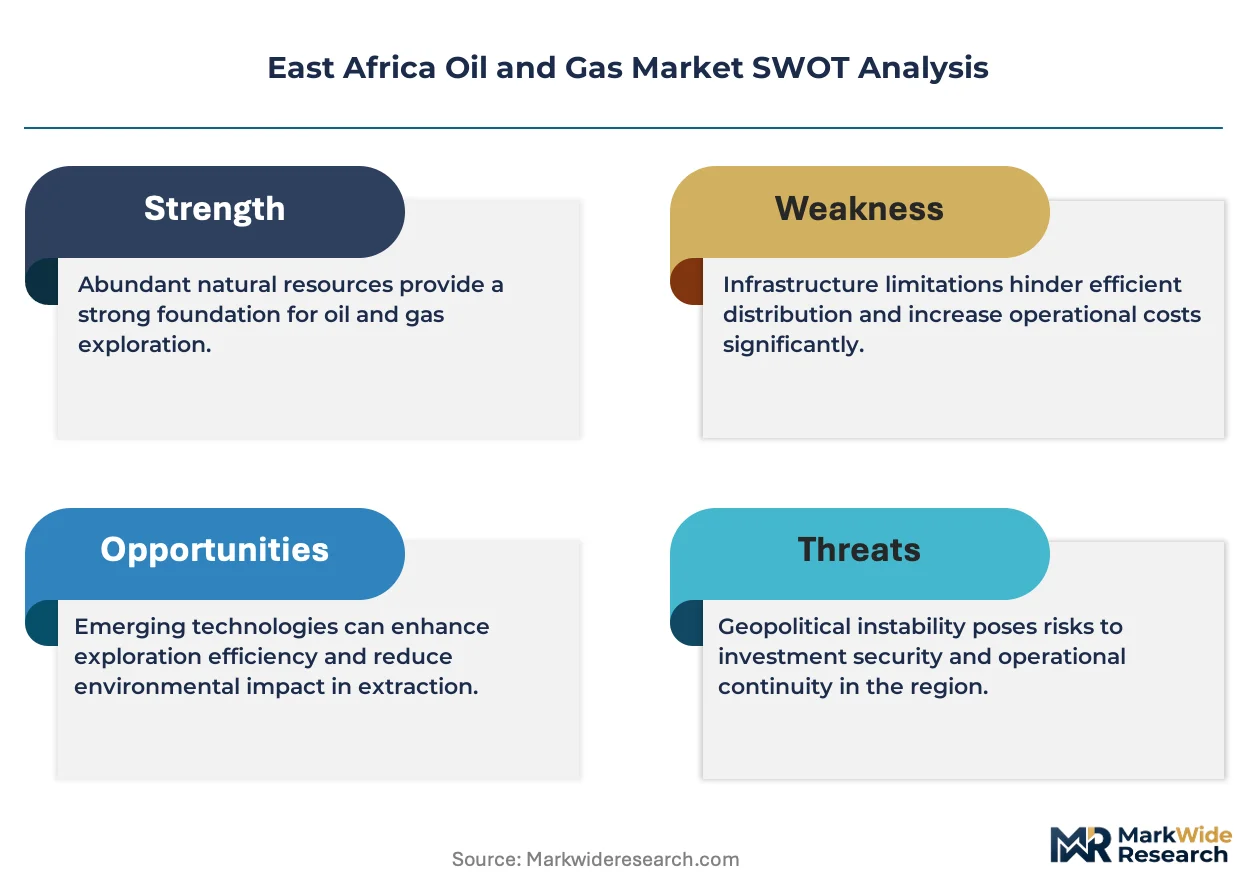
East Africa oil and gas encompasses hydrocarbon exploration, production, transportation, refining, and distribution systems operating across the East African Rift system and adjacent offshore basins, characterized by waxy crude compositions requiring heated pipeline infrastructure and gas reserves with high CO2 content demanding specialized processing. The primary purpose spans electricity generation feedstock, petrochemical manufacturing inputs, and transport fuel supply for import-dependent economies. Upstream activity captures the dominant value pool given frontier basin status, while midstream logistics represents the fastest-expanding segment as LNG export terminals and regional pipelines advance. Downstream refining remains structurally constrained by single-plant national dependence and import parity pricing mechanisms.
Tanzania's Petroleum Act and Uganda's Petroleum Authority framework shape fiscal terms and local content obligations, while Kenya's Energy and Petroleum Regulatory Authority governs downstream pricing and infrastructure access. These regulatory architectures determine project economics, operator selection criteria, and domestic market obligation enforcement. Stakeholders must monitor final investment decision timelines against fiscal regime stability and regional pipeline interconnectivity negotiations.
Market Dynamics
Final investment decision delays on Tanzania's offshore LNG projects are compressing contractor cash cycles and redirecting engineering capacity toward East African pipeline corridors. This capital deployment hesitation is reshaping operator-contractor relationships across the Rift system.
Growth Catalysts
- Gas-to-power conversion mandates:Kenya's Energy and Petroleum Regulatory Authority prioritizes grid-connected natural gas generation, displacing diesel baseload plants and opening midstream infrastructure slots.
- Tanzania Petroleum Act local content floors:Domestic workforce quotas and supplier registration requirements are channeling capital toward indigenous service company formation.
- Subsea tieback engineering:Standardized modular wellhead designs are reducing offshore development breakevens for Rovuma Basin operators.
Market Restraints
- Specialized vessel scarcity:East Africa lacks heavy-lift marine assets, forcing reliance on Singapore and Gulf of Mexico-based contractors with 18-month booking backlogs.
- Waxy crude transport costs:Uganda's heated pipeline infrastructure requires continuous thermal input, inflating per-barrel logistics expenditure versus global light crude benchmarks.
- Fiscal regime uncertainty:Tanzania's production sharing agreement renegotiation timeline deters long-cycle capital commitment from international operators.
Strategic Opportunities
- South Sudan pipeline rehabilitation:Dormant northern export routes present brownfield infrastructure leverage for regional crude marketing diversification.
- Carbon capture integration:Rovuma Basin gas processing facilities can retrofit amine-based CO2 separation for LNG certification premiums.
- Regional refinery feedstock swaps:Kenya's Mombasa facility could process Ugandan waxy crude through viscosity blending with imported light streams.
Industry Challenges
- Reservoir engineer recruitment:Frontier basin experience pools concentrate in Aberdeen and Houston, requiring expatriate premium packages for East African rotations.
- Legacy land-rights reconciliation:Uganda's Tilenga project corridor faces ongoing customary tenure disputes requiring parallel legal and community engagement tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Oil and Gas Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Support Services Technology: Seismic Exploration, Drilling Technology, Refining Processes, Storage Solutions End User: Power Generation, Petrochemical Industry, Transportation, Industrial Service Type: Exploration Services, Production Services, Logistics, Consultancy |
| Companies Covered | Shell, China National Petroleum Corporation, TotalEnergies, Uganda National Oil Company, Sudan National Petroleum Corporation, China National Offshore Oil Corporation, Equinor, Tanzania Petroleum Development Corporation, Tullow Oil, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Oil and Gas Market Shifts & Advancements
Digital reservoir characterization and modular processing architectures are shortening project development cycles across East African frontier basins. These shifts are compressing traditional engineering phases and altering operator contracting strategies.
Advanced 4D seismic acquisition is fragmenting conventional exploration timelines. Operators deploy ocean-bottom node arrays to reduce survey duration from months to weeks. This compression enables faster drill-or-drop decisions on Rovuma Basin blocks, reallocating capital toward appraisal drilling rather than prolonged data interpretation.
Uganda's Petroleum Authority local content certification requirements are mandating supplier pre-qualification through national registration portals. Domestic fabrication yards must demonstrate welding procedure specifications to international pipeline standards. This regulatory architecture is filtering contractor eligibility and extending procurement lead times for international service providers.
Power utility offtake agreements are displacing oil-indexed pricing in Tanzanian gas sales negotiations. TANESCO and independent power producers seek Henry Hub-linked formulas to align electricity tariffs with generation cost volatility. This contractual evolution is visible in Dar es Salaam industrial zone negotiations, where cement and fertilizer manufacturers negotiate direct pipeline connections bypassing traditional distribution intermediaries.
East Africa Oil and Gas Market Segmentation
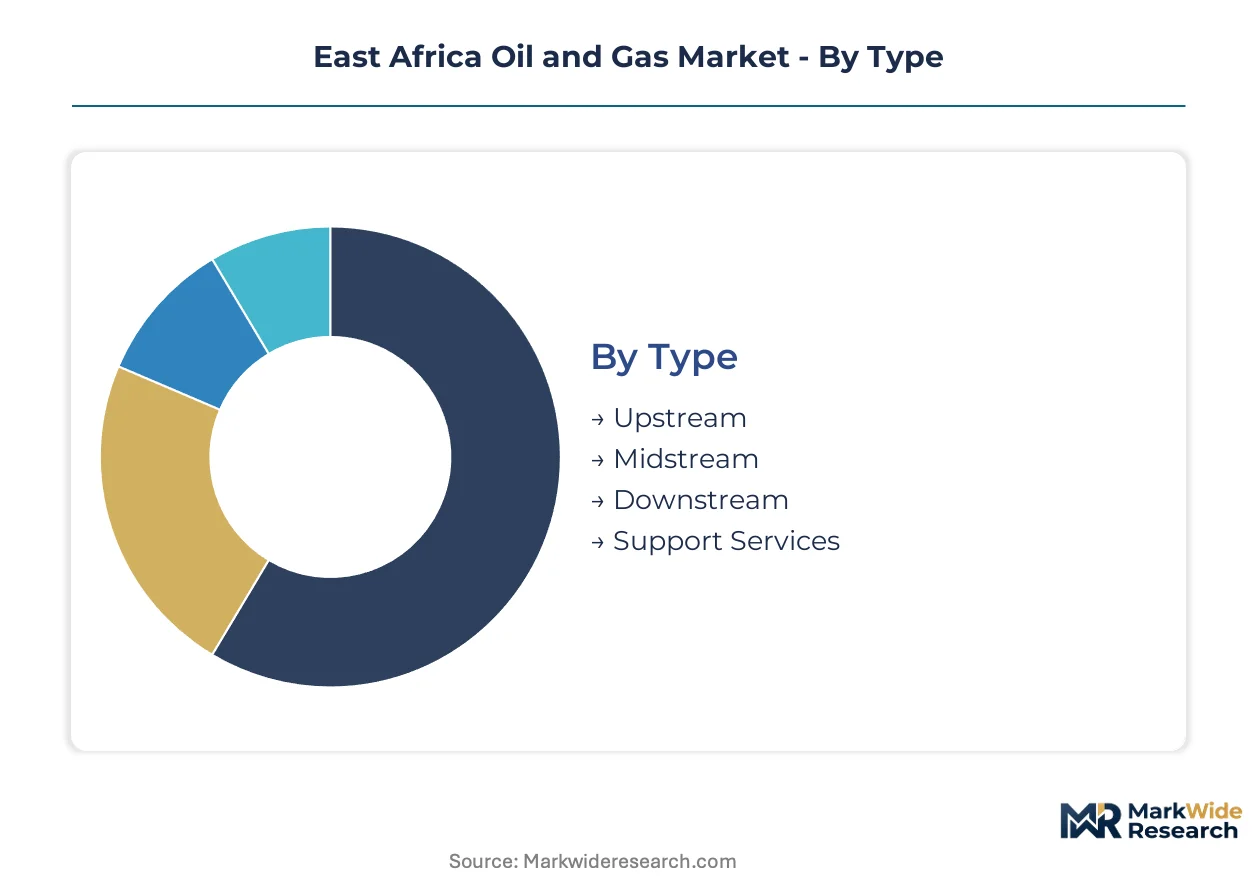
East Africa's oil and gas segmentation reveals how capital flows through distinct technical layers, from frontier basin exploration through waxy crude logistics to gas-fired power offtake. Understanding these segment boundaries clarifies where project delays, local content mandates, and infrastructure gaps concentrate risk.
Type:
Upstream activities channel through international operator consortiums and national oil company partnerships, while midstream and downstream segments flow via infrastructure joint ventures and state-backed distribution networks.
- Upstream:Hydrocarbon exploration and production operations across the Rovuma Basin, Lake Albert rift, and South Sudanese oilfields. Tanzania's offshore gas discoveries and Uganda's Tilenga project anchor regional drilling activity, though fiscal regime uncertainty in Dar es Salaam delays final investment decisions.
- Midstream:Pipeline transport, LNG terminal development, and storage infrastructure connecting production zones to coastal export points. The East African Crude Oil Pipeline and Tanzania LNG export facilities dominate capital allocation, with heated pipeline technology addressing Uganda's waxy crude viscosity challenges.
- Downstream:Refining operations and product distribution networks serving import-dependent economies. Kenya's Mombasa refinery remains the sole significant processing asset, constrained by single-plant national dependence and import parity pricing mechanisms.
- Support Services:Technical consulting, equipment supply, and maintenance operations enabling field development. Local content certification requirements under Tanzania's Petroleum Act and Uganda's Petroleum Authority framework reshape contractor eligibility and procurement channels.
By volume, Upstream leads. By growth pace, Midstream is ahead.
Technology:
Cost tiers separate frontier exploration technologies requiring premium capital deployment from standardized refining and storage solutions with established supply chains.
- Seismic Exploration:Advanced 4D seismic acquisition using ocean-bottom node arrays compresses survey timelines from months to weeks across Rovuma Basin blocks. This acceleration enables faster drill-or-drop decisions, reallocating capital toward appraisal drilling rather than prolonged data interpretation phases.
- Drilling Technology:Extended-reach horizontal drilling and managed pressure systems addressing high-pressure, high-temperature formations in deepwater Tanzanian gas fields. Equipment scarcity and 18-month booking backlogs for specialized marine assets constrain deployment schedules.
- Refining Processes:Viscosity blending and thermal cracking technologies processing waxy Ugandan crude alongside imported light streams. Kenya's Mombasa facility explores feedstock swap arrangements to optimize yield profiles.
- Storage Solutions:Floating storage and regasification units alongside onshore tank farms supporting LNG import and product distribution networks. Dar es Salaam industrial zone expansions drive demand for pressurized storage and direct pipeline connectivity.
Seismic Exploration commands the premium tier. Drilling Technology shows the steepest expansion trajectory as offshore projects advance.
End User:
Application diversity spans grid-connected electricity generation, industrial manufacturing feedstock, and transport fuel substitution, each with distinct offtake contract structures.
- Power Generation:Gas-to-power conversion displacing diesel baseload plants across Kenya and Tanzania. TANESCO and independent power producers negotiate Henry Hub-linked pricing formulas to align electricity tariffs with generation cost volatility, bypassing traditional oil-indexed structures.
- Petrochemical Industry:Fertilizer and cement manufacturing facilities in Dar es Salaam's industrial zone seeking direct pipeline connections. Natural gas feedstock offers cost advantages over imported naphtha and coal alternatives.
- Transportation:Compressed natural gas and liquefied petroleum gas distribution for commercial vehicle fleets. Infrastructure gaps limit penetration outside major urban corridors.
- Industrial:Process heat and captive power applications across manufacturing, mining, and agricultural processing. Grid reliability concerns drive dual-fuel backup system installations.
Power Generation absorbs the largest volume share. Petrochemical Industry is climbing fastest as industrial zone gasification accelerates.
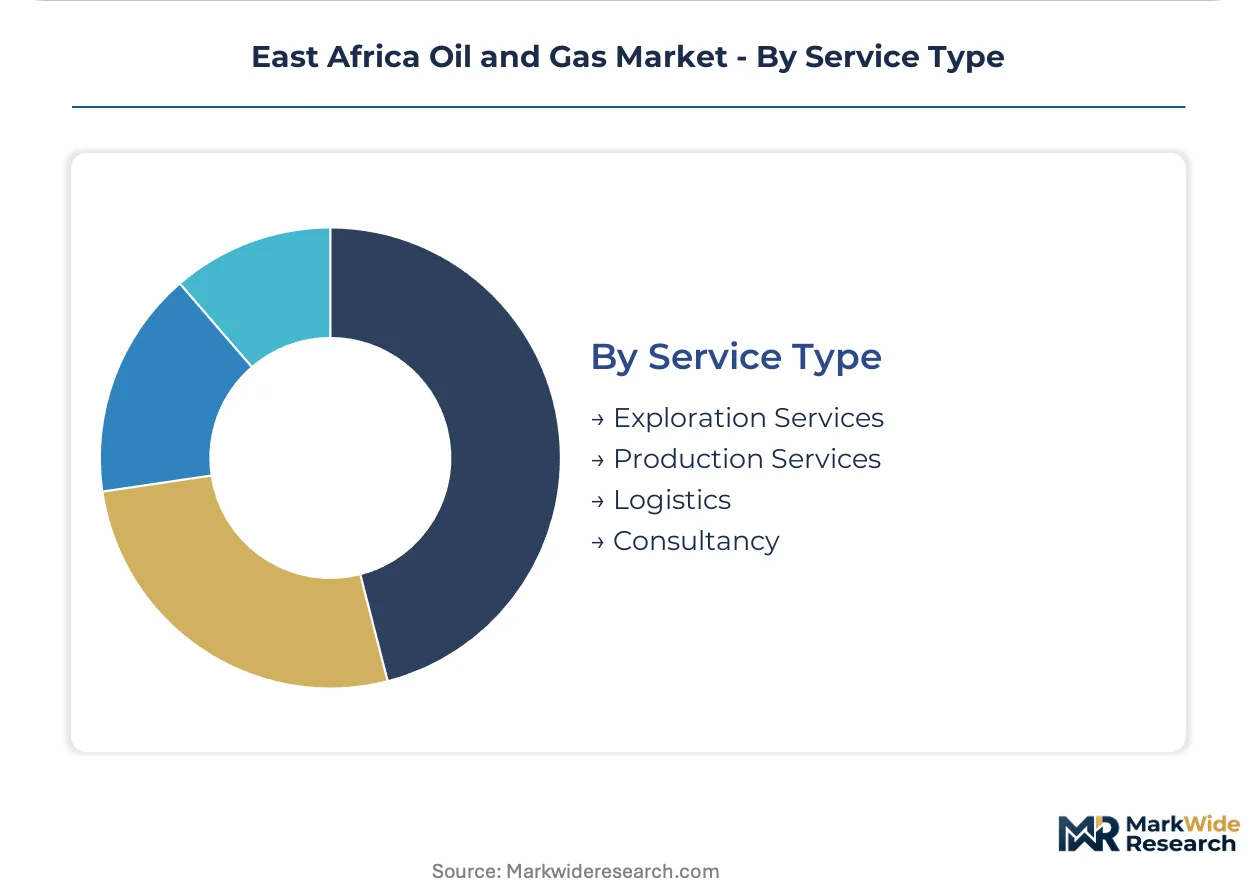
Service Type:
Customer type stratification separates capital-intensive production services for international operators from consultancy and logistics functions serving diverse market participants.
- Exploration Services:Geophysical surveying, well logging, and reservoir characterization supporting frontier basin appraisal. Digital reservoir characterization tools compress traditional engineering phases and alter operator contracting strategies.
- Production Services:Subsea tieback engineering, well completion, and artificial lift systems for offshore gas developments. Standardized modular wellhead designs reduce development breakevens for Rovuma Basin operators facing specialized vessel scarcity.
- Logistics:Marine freight, pipeline construction, and supply base operations connecting production zones to market. Heavy-lift marine asset dependence on Singapore and Gulf of Mexico contractors creates 18-month procurement backlogs.
- Consultancy:Regulatory compliance, local content strategy, and project management advisory navigating Tanzania's Petroleum Act and Uganda's Petroleum Authority frameworks. Domestic workforce quotas channel capital toward indigenous service company formation.
Production Services dominates by revenue concentration. Exploration Services is gaining share fastest as 4D seismic deployment accelerates appraisal timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tanzania commands LNG export pricing leverage against Uganda's landlocked crude logistics, creating a regional asymmetry that shapes capital allocation across the Rift system. This divergence concentrates investment in offshore gas infrastructure while constraining pipeline-dependent developments.
Tanzania
Offshore Rovuma Basin gas discoveries anchor regional LNG export capacity expansion. Tanzania's Petroleum Act mandates local content floors and domestic workforce quotas. Dar es Salaam industrial zone cement and fertilizer manufacturers negotiate direct pipeline connections, bypassing traditional distribution intermediaries.
Uganda
Lake Albert rift oilfields drive heated pipeline infrastructure requirements for waxy crude transport. Uganda's Petroleum Authority streamlined licensing timelines under revised upstream regulations. Tilenga project corridor operations face customary tenure disputes requiring parallel legal and community engagement tracks.
Kenya
Gas-to-power conversion mandates displace diesel baseload plants across the national grid. Kenya's Energy and Petroleum Regulatory Authority governs downstream pricing and infrastructure access. Mombasa refinery explores viscosity blending arrangements to process Ugandan waxy crude alongside imported light streams.
South Sudan
Dormant northern export routes present brownfield infrastructure leverage for crude marketing diversification. The country's national petroleum corporation manages production infrastructure through consortium arrangements. Juba coordinates with regional partners on pipeline rehabilitation and export route security.
Mozambique
Deepwater Area 1 gas developments sustain long-cycle capital allocation from pre-FID equity positions. Offshore licensing frameworks shape fiscal terms and operator selection criteria. Maputo corridor logistics support marine freight and supply base operations connecting production zones to coastal export points.
East Africa Oil and Gas Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across East African project corridors. International majors dominate frontier basin exploration through consortium structures, while national oil companies anchor domestic market obligations and infrastructure control. Two strategic archetypes define competitive positioning: integrated operators leveraging pre-FID equity for long-cycle capital allocation, and state-backed entities capturing local content mandates and pipeline access rights. Competitive moves concentrate on strategic partnerships for LNG offtake and portfolio diversification into carbon capture integration.
Among European-based integrated majors, TotalEnergies and Equinor occupy positions exemplifying long-cycle frontier basin commitment. Tullow Oil represents the independent upstream specialist archetype focused on rift system developments. China National Petroleum Corporation anchors the state-backed infrastructure control position through its Dar Petroleum Operating Company consortium presence.
| Leading Market Players |
|---|
| Shell |
| China National Petroleum Corporation |
| TotalEnergies |
| Uganda National Oil Company |
| Sudan National Petroleum Corporation |
| China National Offshore Oil Corporation |
| Equinor |
| Tanzania Petroleum Development Corporation |
| Tullow Oil |
| Others |
Supply & Pricing Matrix
Henry Hub-linked gas pricing displacing oil-indexed contracts simultaneously redraws supply geography toward pipeline-connected industrial zones and compresses margins for traditional distribution intermediaries. This substitution dynamic concentrates buyer power among cement and fertilizer manufacturers in Tanzania's Dar es Salaam corridor while fragmenting offtake negotiations across Kenya's grid-connected utilities.
Pricing Analysis
The customization-premium spread separates configured-to-order LNG supply arrangements from standardized pipeline gas contracts. Contract-based long-term offtake dominates, with price differentiation driven by volume scale and geographic delivery cost to landlocked versus coastal buyers. Pricing pressure stems from TANESCO's Henry Hub-linked formula demands, eroding oil-indexed premiums. Industrial offtakers show lowest price sensitivity given captive power economics, while independent power producers face acute margin compression.
Supply Chain Analysis
Just-in-time inventory preferences clash with strategic stockpile requirements for heated pipeline infrastructure components and specialized marine assets. Supply concentrates in Singapore, South Korea, and the US Gulf of Mexico for heavy-lift vessels and subsea equipment. Raw material dependencies include high-grade steel for waxy crude pipelines, amine-based solvents for CO2 separation, and modular wellhead assemblies. Single-source vulnerability permeates the vessel charter market. Distribution runs through Mombasa and Dar es Salaam supply bases connecting to Rovuma Basin offshore installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's oil and gas market fragments across regulatory jurisdictions and local content mandates, creating niches for specialized service providers as international operators defer final investment decisions. Gas-to-power conversion mandates and industrial zone gasification generate discrete demand pockets underserved by integrated majors.
For Market Incumbents: Shield equity positions in pre-FID developments by accelerating local content certification for domestic fabrication yards and welding procedure specifications. Secure pipeline access rights through joint ventures with Tanzania Petroleum Development Corporation and Uganda National Oil Company before regulatory thresholds tighten. Vertical integration into carbon capture retrofit engineering offers margin defense against LNG certification premiums.
For New Entrants and Emerging Players: Lead with subsea tieback engineering specialization targeting Rovuma Basin operators facing 18-month vessel booking backlogs. The most penetrable white-space sits in consultancy functions navigating Tanzania's Petroleum Act local content floors and Uganda's Petroleum Authority supplier registration portals. A go-to-market angle anchored in digital reservoir characterization tools compresses traditional engineering phases and differentiates against legacy seismic interpretation providers.
For Investors and Strategic Acquirers: The market sits at a pre-FID capital commitment phase that favors infrastructure-control archetypes over pure exploration exposure. Long-term viability hinges on pipeline interconnectivity negotiations and regional grid gasification timelines. Acquisition targets should demonstrate welding procedure certifications to international pipeline standards and established relationships with national oil companies. The signal to watch is final investment decision announcements on Tanzania LNG export facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Engineering | Positions Rovuma Basin gas for LNG certification premiums through amine-based CO2 separation. |
| Local Content Certification Investment | Unlocks procurement channels under Tanzania's Petroleum Act and Uganda's Petroleum Authority frameworks. |
| Pipeline Interconnectivity Joint Venture | Secures infrastructure access rights across Kenya, Tanzania, and Uganda corridor developments. |
| Modular Wellhead Standardization | Reduces offshore development breakevens for Rovuma Basin operators facing vessel scarcity. |
| Power Purchase Agreement Restructuring | Aligns TANESCO and independent producer tariffs with Henry Hub-linked generation cost volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with upstream project developers, EPC contractors, national oil company planning officers, and power utility procurement leads; and secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up field development economics triangulated against top-down regional demand forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning upstream-midstream-downstream value chain position, fuel source type, project scale tier, regulatory framework cluster, and regional grid interconnection status. CAGRs derived from weighted average development timelines and offtake contract maturation curves. Forecast inputs incorporated final investment decision probability assessments and local content compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained fiscal regime stability or resolved pipeline land-rights disputes would require recalibration. Forecasts reflect assumptions regarding vessel availability and reservoir engineer recruitment feasibility. Revision becomes warranted when Tanzania's production sharing agreement renegotiation timeline crosses commitment thresholds or when regional pipeline security conditions deteriorate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market