
 India Oil and Gas Market | 2026-2036
India Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
India Oil and Gas Market Foresight
Aftermarket service revenue is rewriting profit dynamics across India's hydrocarbon value chain. Reliance Industries leverages its Jamnagar refining complex to dominate petrochemical integration and captive power. ONGC anchors upstream production across the Mumbai High and Krishna-Godavari basins with steady field development. Indian Oil Corporation controls the country's largest pipeline network and retail distribution footprint, sustaining margin capture from crude intake to pump delivery.
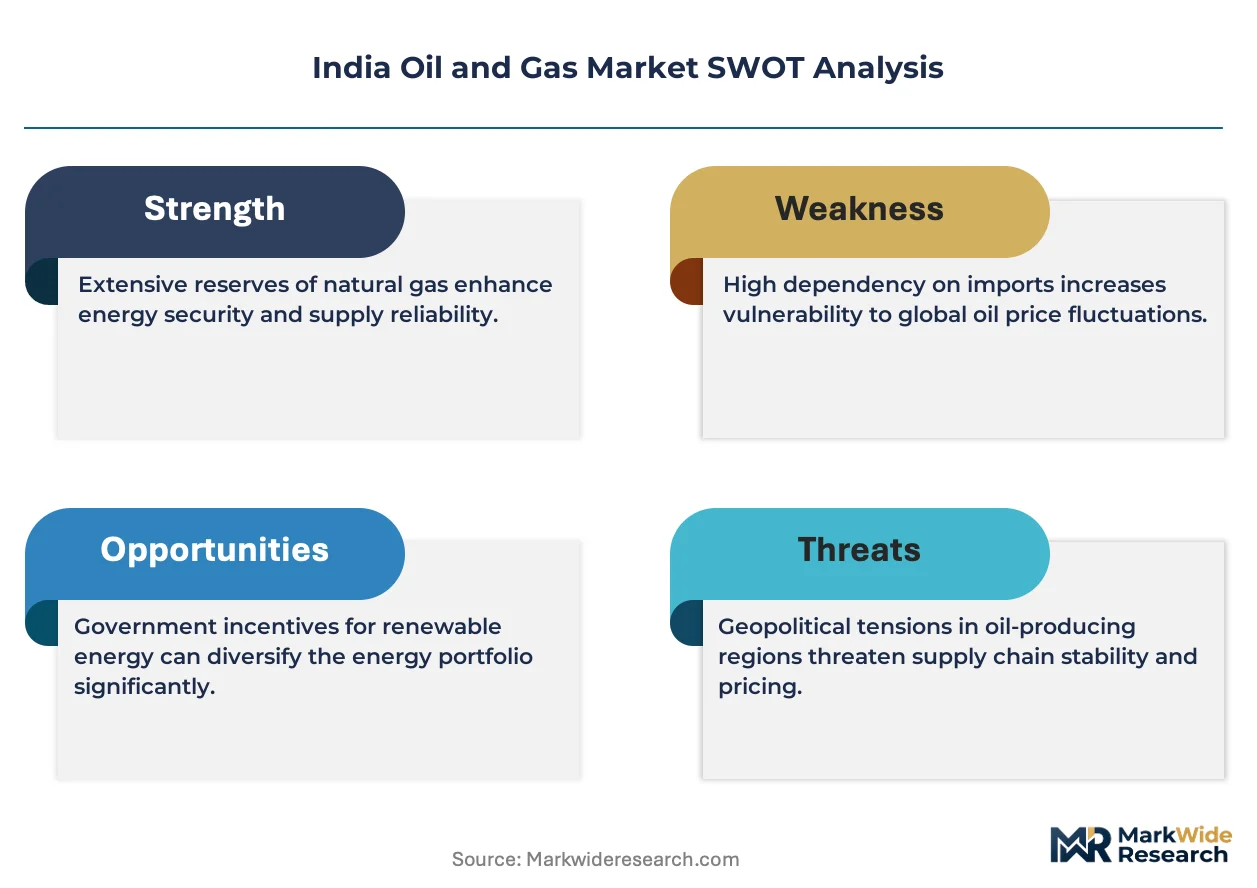
Oil and gas encompasses the exploration, extraction, refining, transportation, and marketing of crude oil, natural gas, and derived products such as gasoline, diesel, LPG, and petrochemical feedstocks, with crude oil characterized by API gravity ranging from light (above 31.1°) to heavy (below 22.3°) and natural gas processed to pipeline specifications of 95%+ methane content. Natural gas and LNG within the Type segment are attracting capital as city gas distribution networks expand under PNGRB licensing rounds, while the Power Generation end user category faces structural competition from solar and wind installations that are altering dispatch priority for gas-fired plants. The Downstream technology segment remains the most mature margin pool, though Renewable integration into refinery operations is emerging as a capital allocation focus for integrated operators.
The Petroleum and Natural Gas Regulatory Board governs pipeline tariffs and city gas licensing, while the Directorate General of Hydrocarbons monitors production sharing contracts and field recovery benchmarks; the Bureau of Indian Standards prescribes fuel quality specifications that refiners must meet for market access. Environmental clearances under the Ministry of Environment, Forest and Climate Change are lengthening project timelines for coastal refinery expansions and deepwater exploration blocks. Stakeholders must weigh the pace of electrification in transport against sustained industrial demand for feedstock and process heat when committing capital to new molecules capacity.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's open access mandate for natural gas pipelines is fragmenting supply monopolies and forcing incumbents to compete on tariff transparency rather than captive infrastructure control.
Growth Catalysts
- PNGRB city gas licensing rounds:The 11th and 12th CGD bidding tranches are extending pipeline networks into 100+ new districts, creating anchor demand for compressed natural gas in transport and piped natural gas in residential clusters.
- Industrial corridor expansion:The Mumbai-Vadodara manufacturing belt is absorbing record volumes of naphtha and natural gas as petrochemical capacity scales to serve textile and packaging export demand.
- Refinery integration upgrades:Complex hydrocracking and delayed coker installations at Gujarat facilities are improving distillate yields from heavier domestic crude slates, tightening the diesel import dependency gap.
Market Restraints
- Upstream production decline:Mumbai High basin mature fields require enhanced oil recovery investments that struggle to clear hurdle rates against volatile Brent-linked realizations, constraining reserve replacement ratios.
- Environmental clearance timelines:Ministry of Environment, Forest and Climate Change coastal regulation zone approvals for deepwater exploration and refinery expansions now stretch 24-36 months, deferring project commissioning.
- Renewable substitution in power:Solar-wind hybrid installations under Solar Energy Corporation tenders are displacing gas-fired combined cycle plants from merit order dispatch, eroding baseload offtake contracts.
Strategic Opportunities
- North-eastern CGD penetration:Assam and Tripura remain underserved by pipeline infrastructure despite proximity to Oil India Limited production fields, presenting first-mover licensing advantages for city gas distribution.
- Hydrogen blending pilots:NTPC's green hydrogen injection trials into existing natural gas networks could establish India as an early mover in hydrogen-ready pipeline standards, supported by Ministry of New and Renewable Energy production-linked incentives.
- Marine LNG bunkering:Jawaharlal Nehru Port and Mundra Port are developing liquefied natural gas refueling infrastructure to capture International Maritime Organization sulfur cap compliance demand from container traffic.
Industry Challenges
- Subsurface engineering talent scarcity:Deepwater exploration and unconventional reservoir characterization require geoscience capabilities concentrated with a handful of public sector training institutes, creating recruitment bottlenecks for private operators.
- Legacy pipeline integrity management:Indian Oil Corporation and GAIL operate 15,000+ kilometers of steel infrastructure commissioned in the 1990s, requiring phased smart pigging and corrosion monitoring investments to maintain PNGRB safety compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Oil and Gas Market |
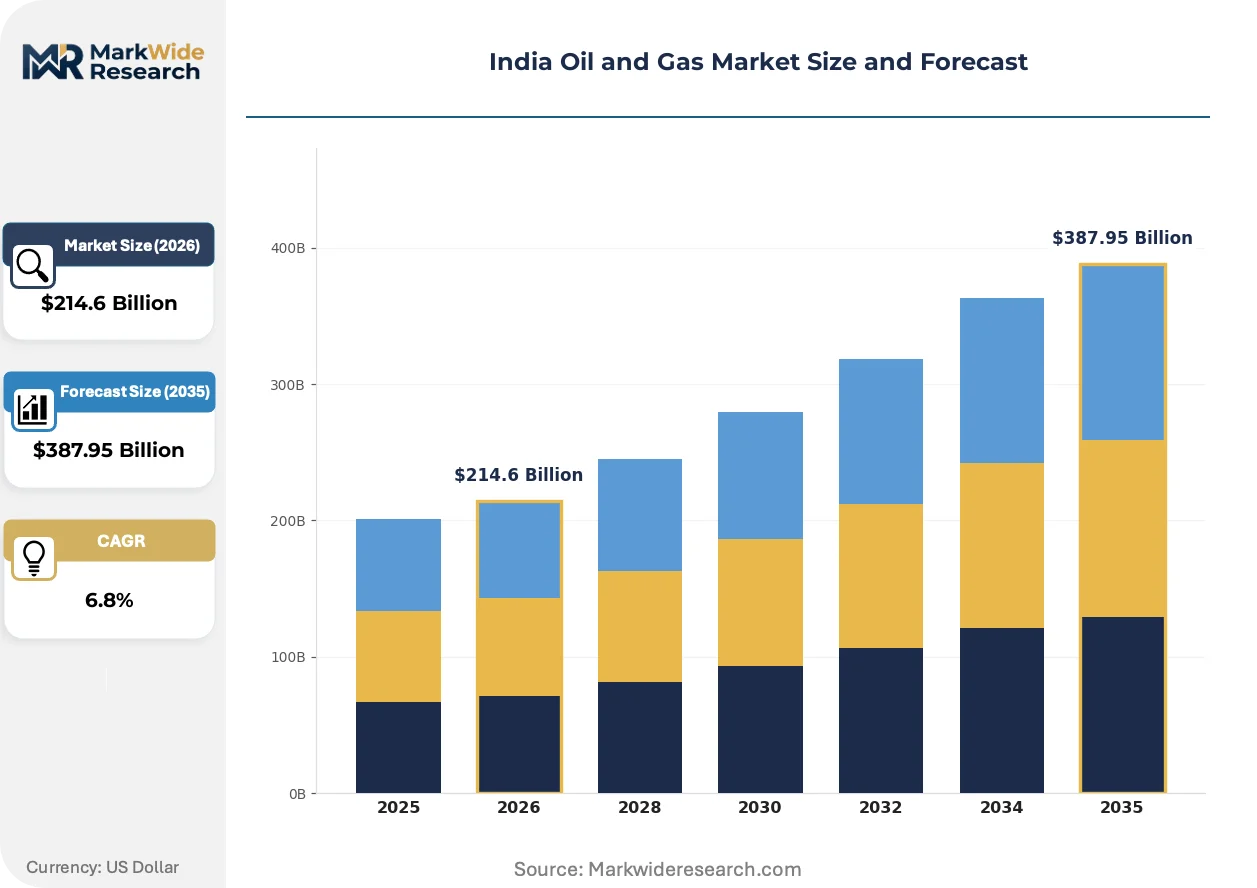
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Natural Gas, Refined Products, LNG Service Type: Exploration, Production, Refining, Distribution End User: Power Generation, Transportation, Industrial, Residential Technology: Upstream, Midstream, Downstream, Renewable |
| Companies Covered | Bharat Petroleum Corporation (BPCL), GAIL (India) Limited, Reliance Industries, Oil India Limited, Petronet LNG, Oil and Natural Gas Corporation (ONGC), Hindustan Petroleum Corporation (HPCL), Indraprastha Gas Limited (IGL), Indian Oil Corporation (IOC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Oil and Gas Market Shifts & Advancements
Digital reservoir characterization and modular refinery upgrades are compressing capital cycles across India's hydrocarbon value chain, while regulatory pressure on carbon intensity is redirecting R&D spending toward emissions abatement technologies.
Artificial lift optimization systems using real-time downhole sensor telemetry are rendering obsolete conventional beam pump maintenance schedules that relied on surface observation and periodic well intervention. ONGC and Oil India Limited field engineers now deploy predictive algorithms to schedule rod replacements, cutting workover rig utilization by 30-40% in marginal wells. This operational shift is compressing upstream opex structures and extending economic field life beyond original reserve estimates.
Bureau of Indian Standards BS-VI emission specifications for gasoline and diesel have forced refiners to install catalytic reforming and hydrotreater capacity to meet 10 ppm sulfur limits. The compliance burden falls heaviest on smaller public sector marketing companies lacking integrated refining assets, driving tolling arrangements with Reliance Industries and Nayara Energy. Coastal refiners with hydrocracker depth now capture premium product spreads against inland competitors processing heavier feedstocks.
Industrial buyers in fertilizers and steel are consolidating procurement through long-term take-or-pay contracts with GAIL and Petronet LNG, abandoning spot cargo dependence that exposed margins to JKM price spikes. This contract concentration is shifting volume risk onto suppliers while locking in pipeline utilization commitments. The pivot is most visible in the phosphatic fertilizer belt of Gujarat and Odisha, where urea manufacturers anchor LNG terminal offtake.
India Oil and Gas Market Segmentation
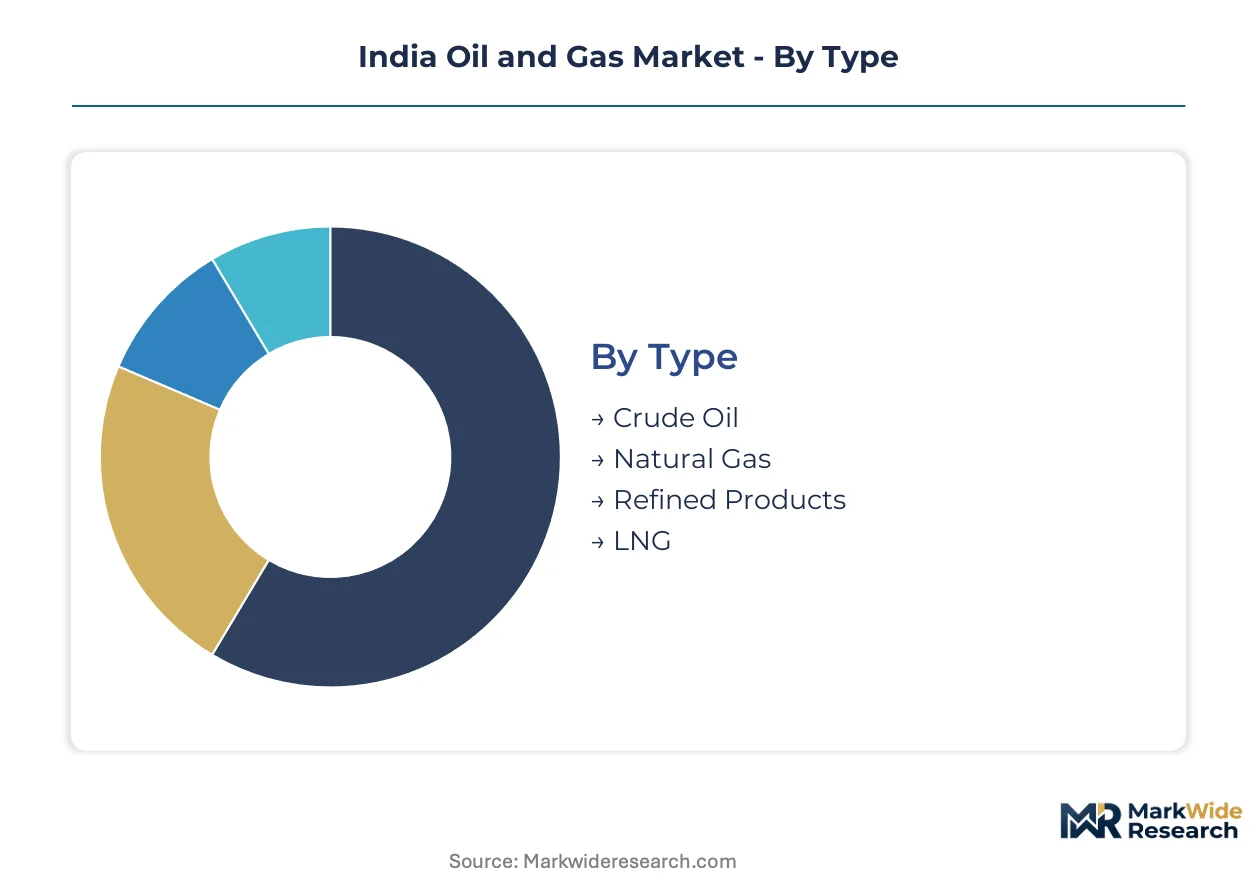
Segmentation across India's hydrocarbon value chain reveals how capital allocation priorities diverge between molecules and infrastructure, with each category mapping to distinct regulatory touchpoints and margin structures. The four-dimensional framework below captures where volume concentrates versus where growth is accelerating.
Type:
Use-case spectrum spans combustion fuels for transport, feedstock for petrochemicals, and pipeline gas for industrial heat, with each molecule type commanding different tariff regimes under PNGRB and Ministry of Petroleum and Natural Gas oversight.
- Crude Oil:Sourced primarily from Mumbai High and Krishna-Godavari basins domestically, with imports arriving at Gujarat and Maharashtra ports. Refinery intake in Jamnagar and Vadodara clusters absorbs the heaviest volumes, though import dependency for heavier grades remains structural.
- Natural Gas:Pipeline specifications require 95%+ methane content after processing at ONGC and Oil India Limited facilities. City gas distribution licensing under PNGRB rounds 11 and 12 is extending network coverage into 100+ new districts, anchoring residential and transport demand.
- Refined Products:Gasoline, diesel, LPG, and naphtha output from Gujarat refineries serve the Mumbai-Vadodara industrial corridor. BS-VI sulfur limits of 10 ppm have forced catalytic reforming investments that smaller marketers cannot self-finance.
- LNG:Regasification terminals at Dahej, Hazira, and Kochi supply fertilizer and steel manufacturers under long-term take-or-pay contracts. Spot cargo exposure has diminished as industrial buyers consolidate procurement through GAIL and Petronet LNG.
Established volume favors Crude Oil; emerging adoption favors Natural Gas.
Service Type:
Cost tier stratification separates capital-intensive upstream development from asset-light distribution operations, with margin capture shifting toward downstream integration as open access regulations commoditize pipeline tariffs.
- Exploration:Seismic surveys and drilling campaigns in deepwater blocks require enhanced oil recovery techniques at Mumbai High mature fields. Environmental clearance timelines under Ministry of Environment, Forest and Climate Change now stretch 24-36 months, deferring project commissioning.
- Production:Artificial lift optimization using real-time downhole telemetry is cutting workover rig utilization by 30-40% at ONGC marginal wells. Geoscience talent scarcity concentrated at public sector training institutes creates recruitment bottlenecks for private operators.
- Refining:Hydrocracking and delayed coker installations at Gujarat facilities improve distillate yields from heavier domestic crude slates. Coastal refiners with hydrocracker depth capture premium spreads against inland competitors processing inferior feedstocks.
- Distribution:Indian Oil Corporation controls the largest pipeline network and retail footprint, sustaining margin capture from crude intake to pump delivery. Smart pigging and corrosion monitoring investments are required for 15,000+ kilometers of 1990s-vintage steel infrastructure.
Refining commands the widest margins; Distribution is gaining share fastest from regulatory-mandated infrastructure access.
End User:
Customer type concentration varies sharply, with industrial buyers locking in long-term contracts while residential and transport segments respond to city gas network expansion.
- Power Generation:Gas-fired combined cycle plants face structural displacement from solar-wind hybrid installations under Solar Energy Corporation tenders. Merit order dispatch priority is eroding baseload offtake contracts for LNG-dependent generators.
- Transportation:Compressed natural gas demand is climbing fastest as CGD networks extend into new districts. Reliance Industries leverages its Jamnagar refining complex to dominate transportation fuel supply alongside petrochemical integration.
- Industrial:Fertilizer and steel manufacturers in Gujarat and Odisha anchor LNG terminal offtake through consolidated procurement. The phosphatic fertilizer belt represents the most contract-concentrated demand pool.
- Residential:Piped natural gas penetration remains limited to licensed CGD areas, with Assam and Tripura presenting first-mover opportunities despite proximity to Oil India Limited production fields.
Industrial offtake dominates contract value; Transportation is climbing the fastest on CNG infrastructure rollout.
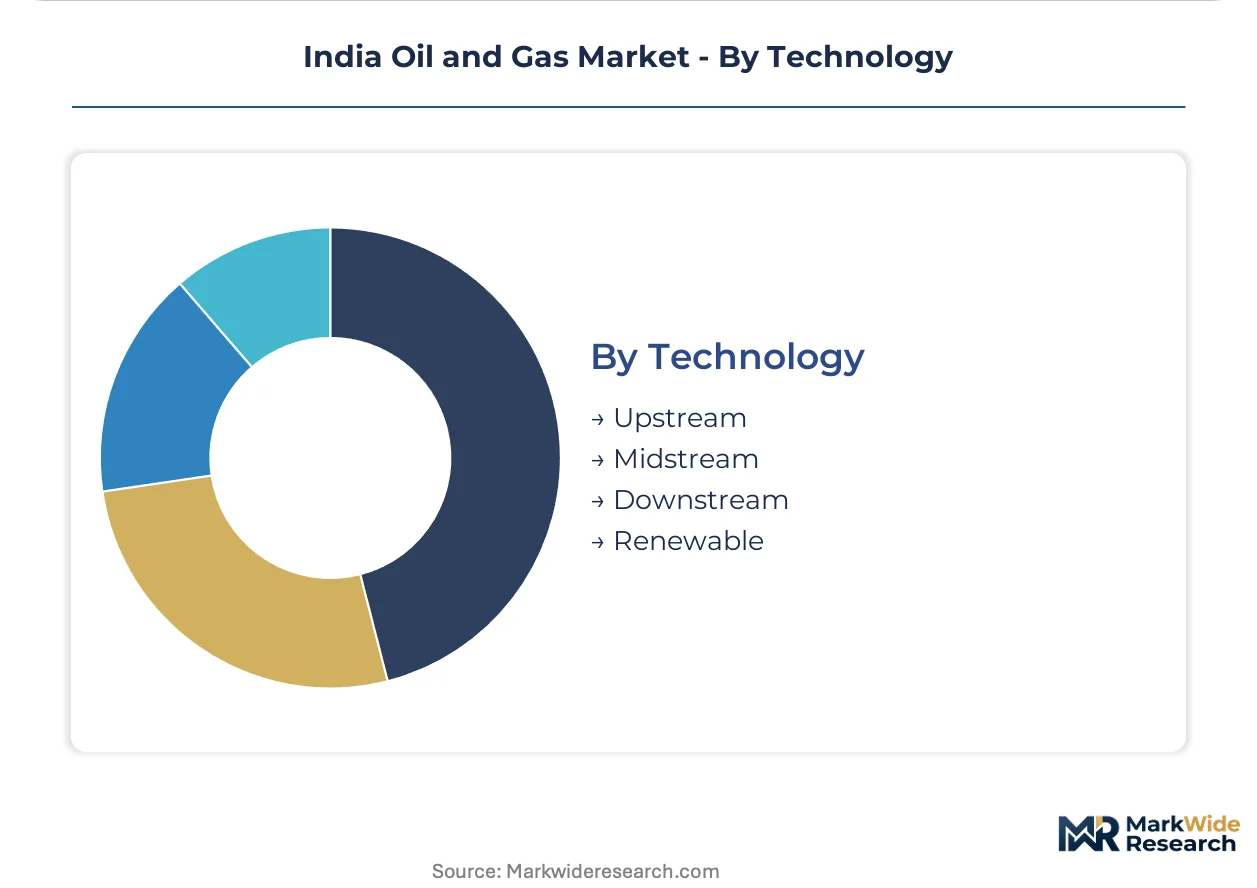
Technology:
Maturity gradient runs from established downstream processing to nascent renewable integration, with capital allocation increasingly bifurcated between hydrocarbon optimization and emissions abatement.
- Upstream:Digital reservoir characterization and predictive algorithms are compressing capital cycles at mature fields. Subsurface engineering capabilities remain scarce outside public sector training infrastructure.
- Midstream:Open access regulations are fragmenting supply monopolies and forcing tariff transparency competition. Legacy pipeline integrity management requires phased investment to maintain PNGRB safety compliance.
- Downstream:The most mature margin pool, though renewable integration into refinery operations is emerging as a capital allocation focus for integrated operators. BS-VI compliance has driven tolling arrangements between smaller marketers and complex refiners.
- Renewable:NTPC's green hydrogen injection trials into existing natural gas networks could establish India as an early mover in hydrogen-ready pipeline standards. Ministry of New and Renewable Energy production-linked incentives support pilot scaling.
Downstream retains margin depth; Renewable integration represents the steepest expansion trajectory for new capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat and Maharashtra absorb heavier refinery throughput than other states, while Assam and the north-east depend more on domestic crude extraction than imported molecules. This consumption-mix differential shapes infrastructure investment patterns across the federation.
Gujarat
Jamnagar and Vadodara host India's densest refining cluster, processing imported Middle Eastern crude alongside domestic Mumbai High barrels. The Petroleum and Natural Gas Regulatory Board's open access tariffs for natural gas pipelines are forcing incumbent operators to compete on transparency rather than captive infrastructure control. Dahej anchors LNG regasification capacity serving the phosphatic fertilizer belt.
Maharashtra
Mumbai High basin mature fields require enhanced oil recovery investments that struggle to clear hurdle rates against volatile Brent-linked realizations. Environmental clearances under the Ministry of Environment, Forest and Climate Change for coastal refinery expansions now stretch 24-36 months. The Mumbai-Vadodara manufacturing corridor absorbs record naphtha volumes as petrochemical capacity scales for textile export demand.
Assam
Proximity to Oil India Limited production fields has not translated into dense city gas distribution coverage, leaving first-mover licensing advantages for PNGRB bidding rounds. The Brahmaputra valley's isolated pipeline geography forces reliance on liquid fuel logistics that inflate delivered costs. Digboi and Duliajan anchor upstream production infrastructure dating to colonial-era field development.
Tamil Nadu
Manali and Ennore host petrochemical complexes importing naphtha and LNG for synthetic fiber and plasticizer output. Solar-wind hybrid installations under Solar Energy Corporation tenders are displacing gas-fired combined cycle plants from merit order dispatch, eroding baseload offtake for LNG-dependent generators. The Cauvery basin holds modest onshore production that supplements coastal refinery intake.
Andhra Pradesh
The Krishna-Godavari basin deepwater blocks anchor ONGC's reserve replacement strategy despite subsurface engineering talent scarcity concentrated at public sector training institutes. Kakinada serves as the eastern LNG import pivot with regasification capacity supplying fertilizer manufacturers in Odisha and Telangana. Coastal regulation zone approvals for offshore exploration have lengthened project timelines under Ministry of Environment oversight.
India Oil and Gas Market Competitive Landscape
Capability concentration sits with integrated refiners commanding hydrocracker depth; scale advantage sits with pipeline operators controlling 15,000-plus kilometers of midstream infrastructure. The market structures around three archetypes: upstream field developers anchored at mature basins, downstream integrators capturing margin from crude intake to pump delivery, and gas utilities licensing city gas distribution networks. Dominant competitive moves include refinery integration upgrades to process heavier domestic slates and long-term take-or-pay contracts consolidating industrial procurement.
Within the integrated downstream tier, Reliance Industries and Indian Oil Corporation occupy positions that exemplify scale-driven margin capture across refining and retail distribution. GAIL (India) Limited anchors the gas utility archetype, representing pipeline infrastructure control that PNGRB open access regulations are now fragmenting. ONGC exemplifies the upstream field developer position, though its reserve replacement economics face pressure from volatile crude realizations at mature Mumbai High properties.
| Leading Market Players |
|---|
| Bharat Petroleum Corporation (BPCL) |
| GAIL (India) Limited |
| Reliance Industries |
| Oil India Limited |
| Petronet LNG |
| Oil and Natural Gas Corporation (ONGC) |
| Hindustan Petroleum Corporation (HPCL) |
| Indraprastha Gas Limited (IGL) |
| Indian Oil Corporation (IOC) |
| Others |
Supply & Pricing Matrix
Commodity volatility in Brent-linked crude realizations determines both margin compression at domestic refineries and the geographic sourcing patterns of Indian importers. Tariff exposure at Gujarat and Maharashtra ports feeds into pricing tier spreads between coastal hydrocracker-equipped facilities and inland processors dependent on heavier domestic slates.
Pricing Analysis
Long-term take-or-pay contracts dominate industrial procurement as fertilizer and steel manufacturers abandon spot cargo dependence. Price differentiation rests on sulfur content grades and hydrocracker depth, with BS-VI-compliant coastal refiners capturing premium spreads against inland competitors. Pricing pressure stems from renewable substitution eroding gas-fired power dispatch economics. Small public sector marketers exhibit highest price sensitivity, lacking integrated refining assets to absorb catalytic reforming investments.
Supply Chain Analysis
Export-control restrictions on advanced subsurface imaging technology limit deepwater exploration equipment flows into Indian basins. Supply concentration draws from Saudi Arabia, Iraq, and the United Arab Emirates for crude intake, while LNG cargoes source from Qatar, Australia, and the United States. Raw material dependencies center on catalytic reforming catalysts, hydrocracker hydrogen supply, and specialized corrosion-resistant alloys. Single-source vulnerability runs through geoscience talent concentrated at public sector training institutes. Distribution runs through Indian Oil Corporation's 15,000-kilometer pipeline network and GAIL's trunk line infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's oil and gas sector sits at a regulatory inflection where PNGRB open access mandates fragment pipeline monopolies and city gas licensing rounds accelerate network penetration. This disruption creates asymmetric opportunity across incumbent defense, entrant white-space capture, and investor cycle positioning.
For Market Incumbents: Build regulatory compliance moats through accelerated smart pigging investments on 1990s-vintage steel infrastructure ahead of PNGRB safety enforcement. Defensive consolidation should prioritize hydrocracker depth upgrades at Gujarat facilities to process heavier domestic crudes, tightening diesel import dependency gaps against renewable substitution threats in transport fuel demand. For New Entrants and Emerging Players: Assam and Tripura's sparse city gas distribution coverage presents first-mover licensing advantages despite proximity to Oil India Limited production fields. White-space targets include hydrogen-ready pipeline pilots and marine LNG bunkering infrastructure at Jawaharlal Nehru Port. Go-to-market positioning should anchor on long-term industrial offtake contracts with phosphatic fertilizer manufacturers in underserved north-eastern districts. For Investors and Strategic Acquirers: The market sits at a mid-cycle consolidation phase that favors integrated downstream operators with hydrocracker depth and captive petrochemical integration. Long-term viability over the coming decade hinges on emissions abatement technology deployment and renewable-hydrogen blending capabilities. Acquisition targets should screen for pipeline integrity management compliance records and CGD license portfolios in tier-two districts. The signal to watch is Ministry of Environment clearance timeline compression for coastal refinery expansions.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Integration Upgrade | Hydrocracker and delayed coker installations at Gujarat facilities improve distillate yields from heavier domestic crude slates. |
| City Gas Distribution Licensing | PNGRB bidding rounds 11 and 12 extend pipeline networks into 100+ new districts, anchoring CNG transport demand. |
| Pipeline Integrity Management | Smart pigging investments on 15,000 kilometers of 1990s-vintage infrastructure maintain PNGRB safety compliance. |
| Green Hydrogen Pilot Scaling | NTPC's injection trials into natural gas networks establish India as an early mover in hydrogen-ready pipeline standards. |
| Long-term Industrial Procurement | Take-or-pay contracts with GAIL and Petronet LNG shift volume risk onto suppliers while locking in terminal offtake. |
Research Methodology
Desk research of Petroleum and Natural Gas Regulatory Board licensing records, Ministry of Petroleum and Natural Gas policy circulars, and Bureau of Indian Standards emission specifications preceded structured interviews with refinery operations managers, city gas distribution license holders, pipeline integrity engineers, and fertilizer procurement directors. Secondary validation drew from Directorate General of Hydrocarbons production sharing contract disclosures, environmental clearance tracking databases, and LNG terminal throughput reports. Bottom-up field-level capacity assessments combined with top-down macroeconomic energy demand projections through iterative triangulation.
Assumptions held fixed include PNGRB regulatory enforcement timelines, BS-VI emission specification continuity, and existing solar-wind hybrid installation dispatch priority over gas-fired generation. The analytical framework modeled volume and value across the projection horizon through four segmentation dimensions: molecule type, service tier, end-use category, and technology maturity gradient. CAGRs derived from regression analysis against crude import dependency ratios, refinery utilization rates, and city gas network penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by complex coastal refiners or accelerated green hydrogen deployment by NTPC would shift outcomes. Material shifts in Ministry of Environment clearance timelines or international LNG cargo pricing volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Gold Mining Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Coal Mining Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Mining and Oil & Gas Fasteners Market