
 CO2 EOR Market | 2026-2036
CO2 EOR Market Size, Share, and Industry Trends Forecast 2026-2036
CO2 EOR Market Intelligence
A shift from single-source, operator-owned CO2 supply to a multi-source procurement model is expanding across the industry. Occidental Petroleum leverages its extensive CO2 pipeline infrastructure and captive sources to lead in the Permian Basin. Service providers like Halliburton and Schlumberger specialize in the subsurface engineering and injection technology required for EOR projects. Denbury operates a vast CO2 pipeline network, acting as a crucial third-party supplier.
CO2 enhanced oil recovery (EOR) is a tertiary recovery process that injects carbon dioxide into an oil reservoir. Typically using supercritical CO2, the method reduces oil viscosity and pressure, allowing more crude to be swept toward production wells. Onshore reservoirs and mature fields constitute the primary application areas due to established infrastructure and declining primary production rates. Miscible injection techniques represent the most effective deployment method, achieving higher recovery factors compared to other injection types.
Regulatory frameworks are pivotal, with the US EPA's Underground Injection Control program governing well safety and the IRA's 45Q tax credits incentivizing projects. China's dual carbon goals and the EU Green Deal create similarly supportive policy environments for carbon capture and utilization technologies. Stakeholders must navigate the dual objectives of maximizing hydrocarbon recovery while demonstrating verifiable and permanent carbon sequestration.
Market Dynamics
The CO2 EOR market is defined by the dual objectives of maximizing hydrocarbon output from mature fields and achieving verifiable carbon sequestration. This dynamic is heavily influenced by powerful economic incentives, such as the 45Q tax credits within the United States' Inflation Reduction Act.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act provides substantial tax credits for carbon capture and reuse, directly improving the economic viability of CO2 EOR projects and spurring investment in related infrastructure.
- Mature Field Economics:In established oil regions like the US Permian Basin, operators use CO2 injection as a tertiary recovery method to extend the productive lifespan of aging wells and boost extraction rates.
- Injection Technology Refinements:Advances in miscible injection techniques, which enable CO2 to mix more effectively with crude oil, are improving recovery efficiency and making more reservoirs suitable for EOR application.
Market Restraints
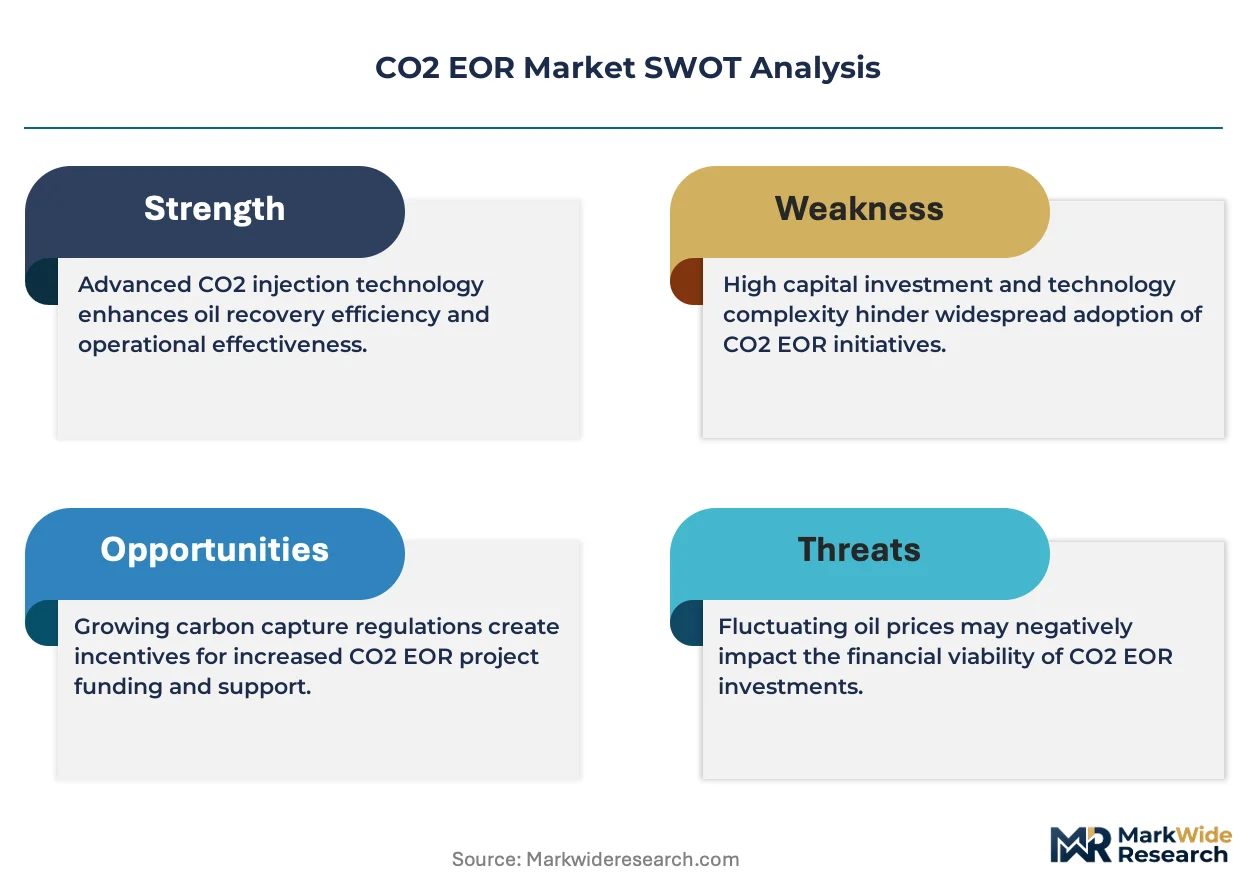
- CO2 Supply Constraints:A primary bottleneck is the limited availability of large-volume, low-cost CO2, with dedicated pipeline infrastructure heavily concentrated in specific North American geographies.
- High Capital Expenditure:The significant upfront investment required for CO2 capture plants, pipelines, and injection well conversions presents a substantial financial barrier for many operators.
- Geological Suitability:Many oil reservoirs lack the specific depth, pressure, and permeability characteristics required for effective and economical miscible or immiscible CO2 flooding.
Strategic Opportunities
- Industrial CO2 Sourcing:Capturing CO2 from industrial emitters like cement and steel plants offers a significant opportunity to expand and diversify the supply chain beyond naturally occurring sources.
- Unconventional Reservoir Application:Developing and applying modified CO2 injection methods to tight oil and shale formations could unlock vast, previously unrecoverable resources from these low-permeability plays.
- International Policy Adoption:The replication of supportive policy frameworks, similar to the US 45Q credit, in other oil-producing nations like Canada or in the Middle East could open major new markets for development.
Industry Challenges
- Specialized Talent Scarcity:A shortage of reservoir engineers and geoscientists with expertise in CO2 flood modeling, simulation, and project management creates operational execution risks for complex EOR projects.
- Complex Monitoring and Verification:Meeting regulatory mandates for permanent carbon storage, such as those under the EPA's Underground Injection Control program, requires sophisticated and costly long-term monitoring technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2 EOR Market |
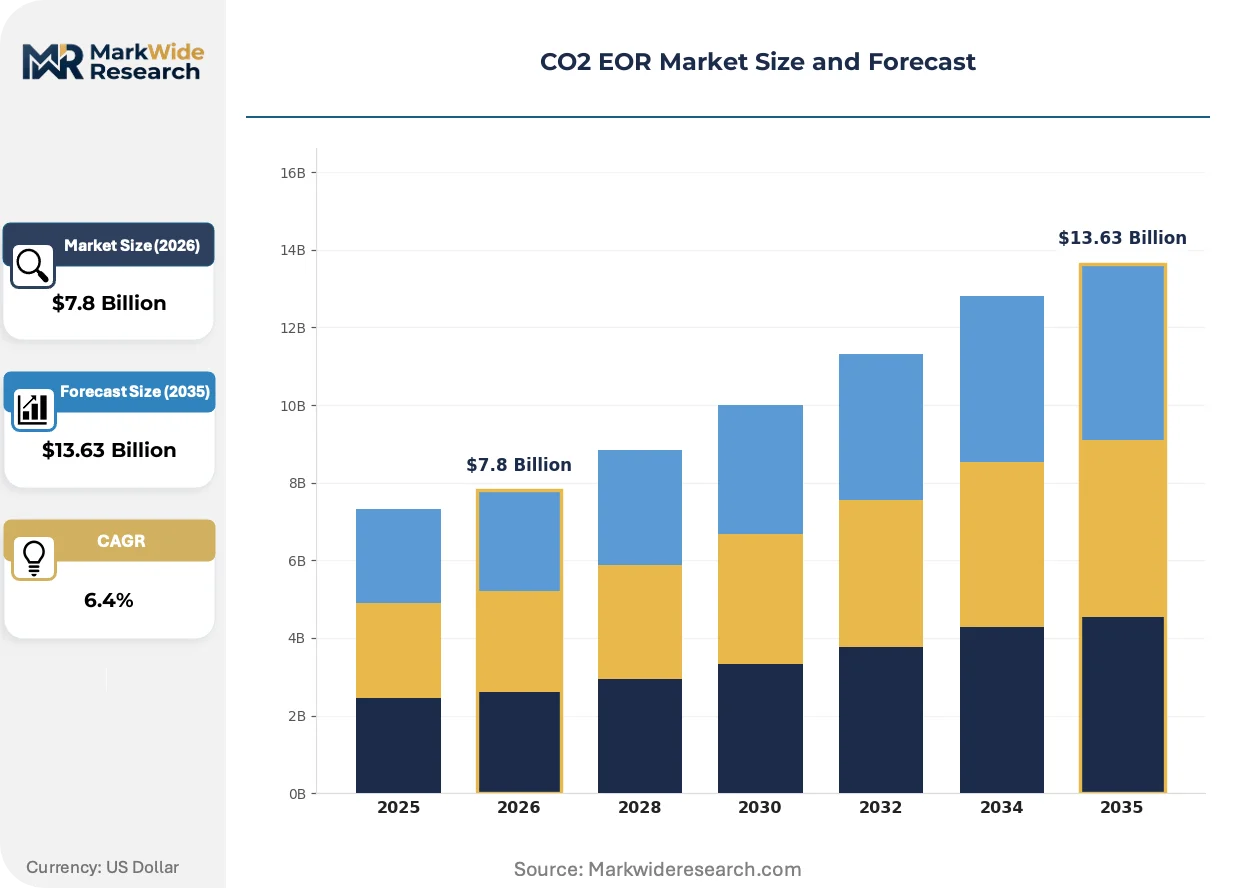
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Continuous Injection, Cyclic Injection, WAG Injection, Miscible Injection Application: Offshore Reservoirs, Onshore Reservoirs, Mature Fields, Unconventional Oilfields Deployment: Enhanced Recovery, Carbon Sequestration, Emissions Reduction, Well Stimulation End User: Independent Operators, National Oil Companies, Service Providers, Independent Contractors |
| Companies Covered | Occidental Petroleum, Halliburton, Chevron, Denbury, Baker Hughes, ExxonMobil, Schlumberger, Kinder Morgan, ConocoPhillips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2 EOR Market Strategic Shifts & Innovations
The market's trajectory is being redefined by the integration of digital subsurface analytics with more flexible CO2 sourcing models. This combination is shifting project designs from a singular focus on oil recovery toward a more holistic carbon management and utilization business case.
Digital twin technology for reservoirs creates a dynamic, real-time virtual model of the subsurface environment. Major oil and gas operators are increasingly adopting this for optimizing CO2 injection patterns and accurately predicting reservoir response. This technology is unifying previously siloed disciplines like reservoir engineering, seismic analysis, and production operations into a single, predictive management framework, thereby improving project efficiency.
China's national "dual carbon" policy framework creates a strong impetus for large-scale carbon capture, utilization, and storage (CCUS) deployment. The policy drives state-level investment in integrated projects where CO2 EOR is a key component for achieving industrial decarbonization goals. Consequently, state-owned energy firms in basins like the Ordos and Junggar are pioneering integrated CCUS-EOR hubs to reduce the carbon intensity of both energy production and heavy industry.
A notable behavioral shift involves operators moving from single-source CO2 contracts to a more resilient, multi-source supply portfolio. This change disrupts the dependence on one captive or third-party source, replacing it with a flexible network model managed by CO2 pipeline operators and aggregators. The trend is most advanced in the US Permian Basin, where dense pipeline infrastructure allows EOR operators to secure supply from a mix of natural and industrial sources.
CO2 EOR Market Segmentation
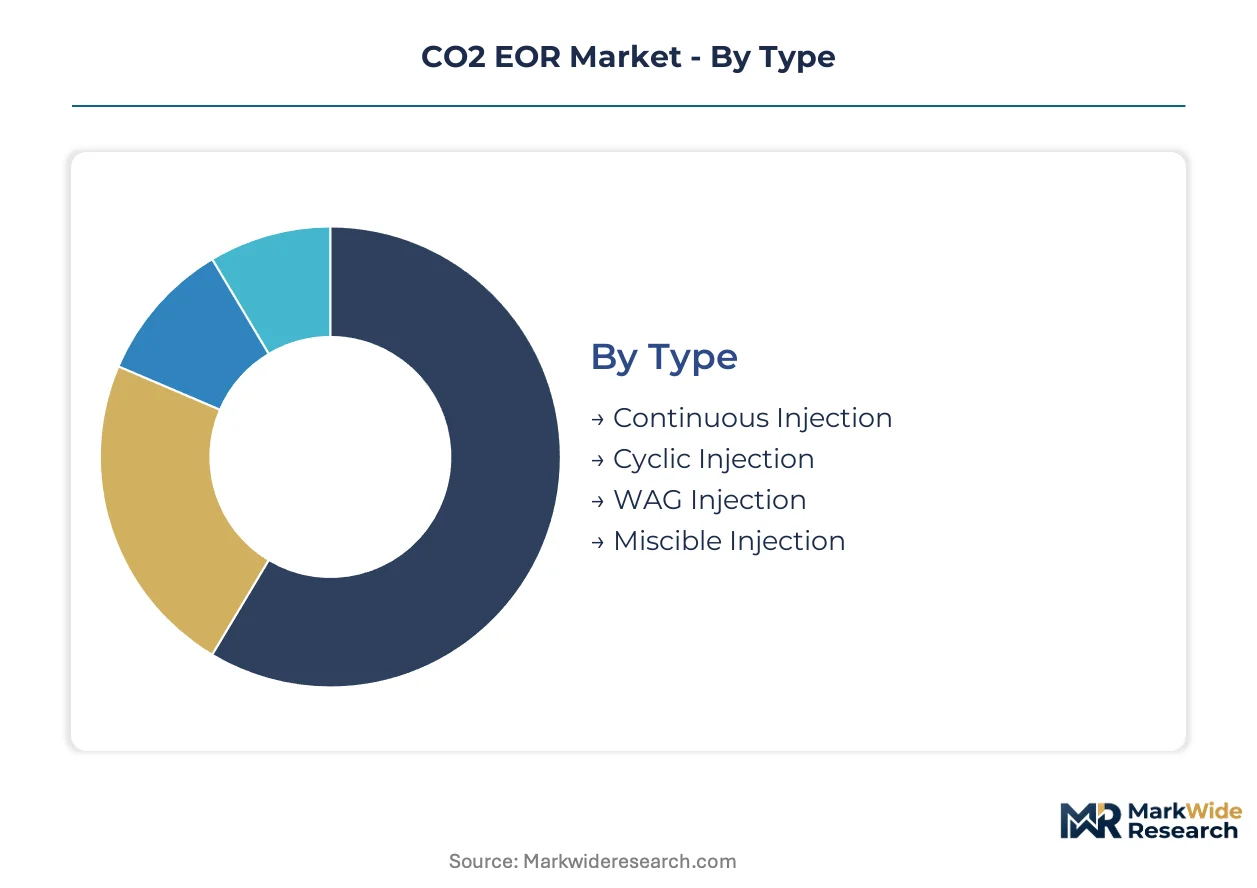
The CO2 EOR market exhibits distinct segmentation across various operational and strategic dimensions. Understanding these segments clarifies the diverse approaches to maximizing hydrocarbon output and achieving carbon management goals. This granular view reveals where investment and technological advancements are most concentrated.
Type:
The choice of CO2 injection technique often reflects a balance between reservoir-specific customization and standardized operational procedures.
- Miscible Injection:Miscible injection involves CO2 mixing completely with crude oil, significantly reducing its viscosity and swelling the oil. This method achieves the highest recovery factors, particularly in formations suited for such interaction. Operators in the Permian Basin widely adopt this technique due to favorable reservoir conditions and economic incentives from the US IRA.
- WAG Injection:Water Alternating Gas (WAG) injection cycles slugs of CO2 with water to improve sweep efficiency and reduce CO2 mobility. This approach mitigates early CO2 breakthrough and optimizes reservoir contact. Projects in the North Sea and Canadian heavy oil fields utilize WAG to enhance recovery while managing costs.
- Continuous Injection:Continuous injection involves a steady flow of CO2 into the reservoir, suitable for specific reservoir characteristics.
- Cyclic Injection:Cyclic injection, or huff-and-puff, injects CO2 for a period, allows it to soak, then produces from the same well.
Leading the category by volume: Miscible Injection. Growing fastest: WAG Injection.
Application:
Application areas for CO2 EOR are often differentiated by the inherent cost structures and logistical complexities associated with each reservoir type.
- Mature Fields:Mature fields represent the primary application for CO2 EOR, leveraging existing infrastructure and declining production rates. These assets benefit from tertiary recovery to extend their economic life and maximize remaining oil. The US Permian Basin and other established onshore plays are key regions for this application.
- Onshore Reservoirs:Onshore reservoirs provide accessible and relatively less expensive environments for CO2 EOR deployment, benefiting from established pipeline networks. The ability to easily monitor and manage injection processes makes these ideal candidates. China's Ordos Basin and Canada's Western Sedimentary Basin are significant onshore EOR hubs.
- Unconventional Oilfields:Unconventional oilfields are exploring modified CO2 injection techniques to improve recovery from tight formations.
- Offshore Reservoirs:Offshore reservoirs face higher capital and operational costs, limiting CO2 EOR to specific, larger-scale projects.
Mature Fields dominate the application segment, while Unconventional Oilfields represent the fastest-growing trajectory.
Deployment:
The deployment of CO2 EOR technologies is driven by a dual focus on hydrocarbon production enhancement and environmental stewardship objectives.
- Enhanced Recovery:Enhanced Recovery focuses directly on increasing oil production from existing wells by injecting CO2 to improve oil mobility. This remains the primary commercial driver for most CO2 EOR projects, extending the productive life of oil assets. Operators in the US Permian Basin prioritize this deployment for economic returns.
- Carbon Sequestration:Carbon Sequestration emphasizes the permanent storage of CO2 within geological formations, often co-located with EOR operations. This deployment aligns with global decarbonization efforts and leverages regulatory incentives like the US IRA 45Q tax credits. Projects in Australia and the Middle East are exploring large-scale sequestration.
- Emissions Reduction:Emissions Reduction, through CO2 utilization, contributes to lowering the carbon footprint of industrial processes.
- Well Stimulation:Well Stimulation uses CO2 injection to improve permeability and flow in certain reservoir types, distinct from full-scale EOR.
Enhanced Recovery holds the largest share in deployment, with Carbon Sequestration gaining share quickly.
End User:
End-users of CO2 EOR solutions are segmented by their operational scale, strategic objectives, and integration within the energy value chain.
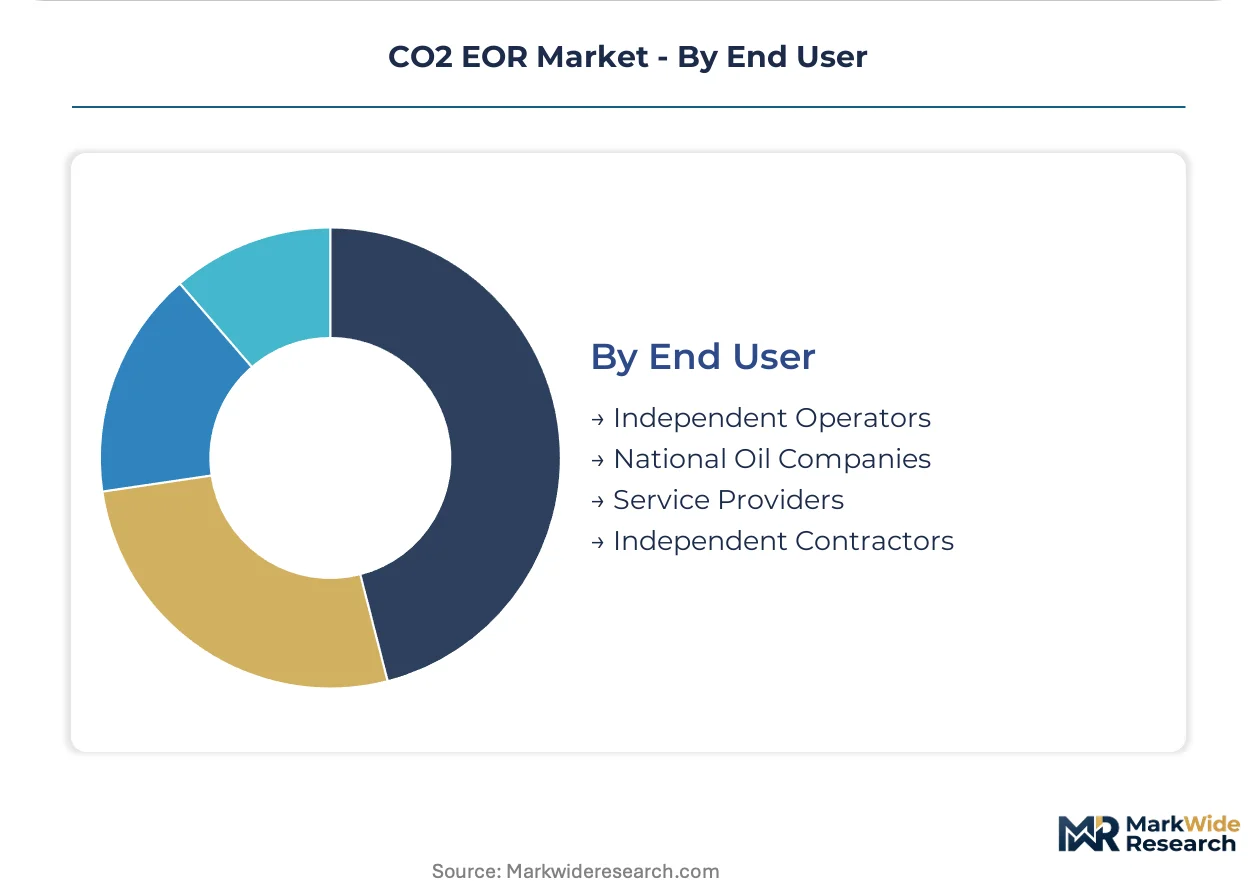
- National Oil Companies:National Oil Companies (NOCs) frequently engage in CO2 EOR to manage national hydrocarbon reserves and align with state-mandated carbon reduction goals. These entities often operate large, mature fields and possess significant capital for infrastructure development. Saudi Aramco and China National Petroleum Corporation (CNPC) are prominent NOCs in this segment.
- Service Providers:Service Providers offer specialized technical expertise, equipment, and project management for CO2 EOR operations. Companies like Halliburton and Schlumberger deliver subsurface engineering, injection technology, and monitoring solutions. They support both independent operators and NOCs in complex EOR projects globally.
- Independent Operators:Independent Operators, typically smaller firms, focus on optimizing recovery from specific assets, often leveraging third-party CO2 supply.
- Independent Contractors:Independent Contractors provide niche services, such as well intervention or specialized equipment, to support EOR initiatives.
National Oil Companies command significant project volumes, while Service Providers are expanding their market penetration through technological offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' extensive CO2 pipeline infrastructure anchors the global CO2 EOR market. Deployment in mature fields is accelerating to maximize oil recovery from aging assets, extending their productive life. Powerful economic incentives, such as the 45Q tax credits within the Inflation Reduction Act, heavily influence this dynamic.
United States
The United States drives significant CO2 EOR demand from its vast mature oil fields, particularly in Texas and New Mexico. The Inflation Reduction Act (IRA) provides substantial 45Q tax credits, directly improving the economic viability of CO2 EOR projects. Project development heavily concentrates in the Permian Basin, a hub for EOR activity and CO2 infrastructure.
China
China's dual carbon goals create a strong impetus for large-scale carbon capture, utilization, and storage deployment. The national policy drives state-level investment in integrated projects where CO2 EOR is a key component. State-owned energy firms in basins like the Ordos and Junggar are pioneering integrated CCUS-EOR hubs.
Canada
Canadian heavy oil fields represent a growing application area for CO2 EOR to enhance recovery. Federal carbon pricing mechanisms and provincial support programs incentivize carbon capture and utilization projects. Operators in the Western Sedimentary Basin utilize WAG injection to improve recovery from complex reservoirs.
Saudi Arabia
Saudi Arabia utilizes CO2 EOR to manage its national hydrocarbon reserves and align with state-mandated carbon reduction goals. The Saudi Green Initiative encourages sustainable practices across the energy sector. Saudi Aramco, a prominent National Oil Company, explores large-scale CO2 injection projects in its vast oil fields.
Australia
Australian projects emphasize large-scale carbon sequestration alongside enhanced oil recovery. The Carbon Capture and Storage Flagships program supports innovative CCUS initiatives. The Gorgon Carbon Dioxide Injection Project in Western Australia showcases significant CO2 storage capabilities.
CO2 EOR Market Key Industry Players
Infrastructure development dominates the current landscape, driven by the imperative for extensive CO2 pipeline networks that efficiently transport carbon dioxide from source to reservoir. The market exhibits a tiered structure, with large integrated oil companies, specialized service providers, and dedicated midstream CO2 suppliers. Strategic partnerships and technology licensing between these distinct archetypes are common, facilitating complex EOR projects and enabling broader geographic expansion into new oil-producing regions.
Integrated operators like Occidental Petroleum exemplify the strategy of leveraging captive CO2 sources and extensive infrastructure to lead in key basins, optimizing both recovery and carbon management. Service providers such as Halliburton specialize in subsurface engineering and injection technology, offering crucial technical expertise for complex EOR project design and execution. Denbury, a dedicated midstream company, occupies a position as a crucial third-party CO2 supplier, managing a vast pipeline network that aggregates and distributes CO2 across multiple projects. These companies collectively shape the operational dynamics across the CO2 EOR value chain by providing essential capabilities.
| Leading Market Players |
|---|
| Occidental Petroleum |
| Halliburton |
| Chevron |
| Denbury |
| Baker Hughes |
| ExxonMobil |
| Schlumberger |
| Kinder Morgan |
| ConocoPhillips |
| Others |
Cost & Logistics Intelligence
National Oil Companies and large integrated operators, driven by long-term project viability, primarily engage in contract-based pricing for CO2 supply and EOR services. Their significant capital investment influences the market's cost structure.
Pricing Analysis
Service providers often bundle subsurface engineering, injection technology, and monitoring solutions with CO2 supply contracts. Project-based and long-term contract-based offtake agreements dominate CO2 EOR pricing, with differentiation based on CO2 purity, delivery logistics, and reservoir engineering complexity. Pricing softness reflects the high capital expenditure for new CO2 capture infrastructure and long payback periods. Independent Operators exhibit higher price sensitivity compared to National Oil Companies.
Supply Chain Analysis
Carbon sequestration mandates create a reverse logistics flow for CO2, where captured emissions are permanently stored rather than released. CO2 supply concentrates in the US Permian Basin, China, and Canada, drawing from natural sources and industrial emitters. The supply chain relies on CO2 capture technology, extensive pipeline networks, and injection well equipment. Single-source vulnerability for CO2 supply remains a structural risk, despite the shift towards multi-source procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CO2 EOR market is evolving into a consolidation play, driven by the immense capital expenditure required for CO2 capture and transport infrastructure. This financial barrier forces smaller, less capitalized operators to exit or partner.
For Market Incumbents: Anticipate increasing regulatory scrutiny on verifiable carbon sequestration, necessitating investment in advanced monitoring technologies. Consolidate CO2 supply networks through strategic acquisitions of midstream pipeline assets to secure long-term access. Invest in R&D for advanced miscible injection techniques to improve recovery factors and expand application to new reservoir types. The threat of alternative carbon capture utilization technologies could displace some EOR applications.
For New Entrants and Emerging Players: Capture opportunities in specialized subsurface engineering services for unconventional reservoirs, leveraging expertise in complex geology. Target niche markets in regions with nascent CO2 infrastructure but strong policy incentives, like emerging EOR projects in Canada or Australia. Partner with industrial emitters to develop localized CO2 capture and utilization hubs, reducing reliance on extensive pipeline networks.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term infrastructure assets with predictable revenue streams from CO2 transport and storage. Long-term viability depends on sustained policy support and carbon capture efficiency advancements. Acquire mid-sized technology providers specializing in advanced reservoir monitoring or novel CO2 injection methods. Monitor the replication of US 45Q tax credit-like incentives in other major oil-producing nations as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expanding CO2 capture and pipeline infrastructure supports wider EOR project deployment. |
| Technology Licensing | Securing rights to advanced injection methods enhances recovery efficiency and project viability. |
| Joint Venture | Forming partnerships with industrial CO2 emitters diversifies supply and reduces procurement costs. |
| Vertical Integration into Storage | Controlling carbon sequestration projects ensures compliance and maximizes environmental benefits. |
| Green Certification Program | Achieving verifiable carbon reduction credentials attracts ESG-focused investment and stakeholder trust. |
Research Approach
Multi-period observation of EOR project deployment rates and CO2 supply infrastructure development anchored the trend analysis, supplemented by interviews. Reservoir engineers, EOR project managers, and CO2 midstream executives provided primary insights. Secondary validation drew from government energy agency reports, corporate sustainability disclosures, and academic research. A bottom-up and top-down triangulation approach ensured data consistency.
An input-output matrix modeled market dynamics, integrating supply-side capacities with demand drivers across the analysis window. Segmentation dimensions included injection type, application area, deployment strategy, and end-user archetype. Compound annual growth rates derived from historical trends, technology adoption, and policy impact assessments. Key inputs included crude oil price forecasts and carbon credit values.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to policy shifts and crude oil price volatility. Forecasts reflect assumptions regarding technological breakthroughs. Practitioners should monitor global carbon pricing mechanisms for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Natural Gas Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Desalter Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
North America Shale Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market