
 Natural Gas Liquid Market | 2026-2036
Natural Gas Liquid Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Liquid Market Analysis
Multi-source feedstock procurement is pivoting toward integrated supply chains as midstream operators consolidate gathering and fractionation assets. ExxonMobil Corporation leverages its Permian Basin position to capture ethane and propane at the wellhead. Shell plc anchors European demand through its Rotterdam chemicals complex. Enterprise Products Partners LP dominates Gulf Coast fractionation with extensive pipeline networks linking Mont Belvieu to downstream consumers.
Natural gas liquids comprise hydrocarbons extracted from natural gas streams, including ethane, propane, butane, and natural gasoline with carbon chains ranging from two to five atoms, primarily serving as petrochemical feedstocks and residential or industrial fuels. These components require cryogenic separation or absorption processes to isolate individual fractions from raw gas before further processing or distribution. Ethane and propane within the Product Type dimension lead absolute volume consumption, while natural gasoline commands premium margins tied to motor fuel blending specifications. The End User segment shows Petrochemical Industry demand outpacing Residential Heating growth, reflecting Asia-Pacific cracker investments and North American export terminal expansions.
The US EPA regulates volatile organic compound emissions from storage and transfer operations, while OSHA governs worker exposure limits during fractionation and handling activities. Texas Railroad Commission and Louisiana Department of Natural Resources administer state-level production quotas and pipeline safety protocols that directly affect supply availability. Stakeholders must monitor regulatory shifts in methane intensity standards and carbon border adjustment mechanisms that could reconfigure competitive economics between domestic consumption and export-oriented production.
Market Dynamics
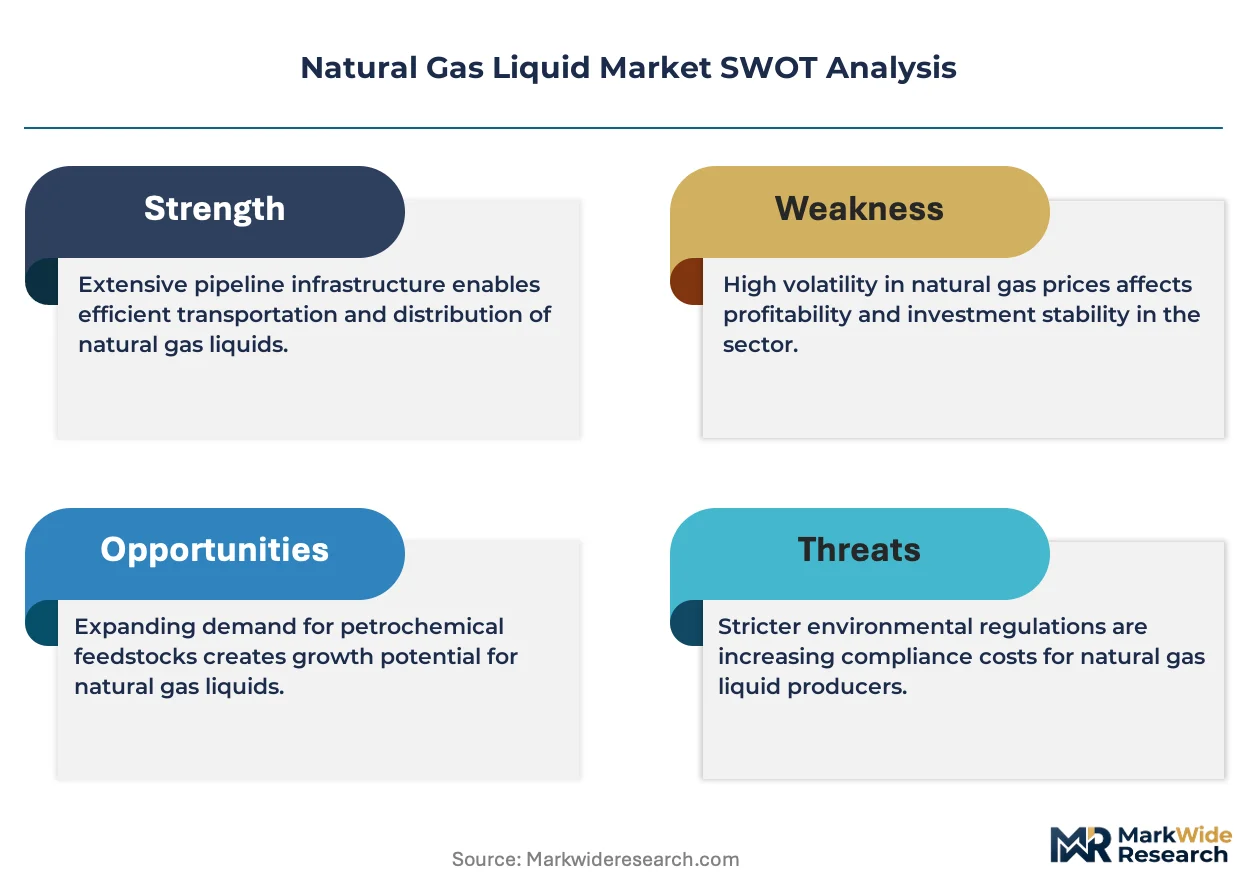
Feedstock flexibility is the dominant structural force reshaping natural gas liquid economics, as cracker operators across Asia-Pacific and the US Gulf Coast reconfigure units to process lighter ethane-propane blends rather than naphtha. This shift is compressing traditional refining margins while elevating demand for dedicated fractionation infrastructure.
Growth Catalysts
- US EPA methane intensity standards:Stricter flaring regulations are accelerating investment in vapor recovery units and closed-loop gathering systems, improving NGL capture rates at the wellhead.
- Ethane cracking expansion:Petrochemical complexes in China and South Korea are adding ethane-only crackers, creating dedicated demand pull for US-sourced ethane exports via refrigerated vessels.
- Mont Belvieu pricing hub:Concentrated storage and fractionation infrastructure along the Texas Gulf Coast anchors global NGL price discovery, attracting hedging liquidity and long-term offtake contracts.
Market Restraints
- Henry Hub price volatility:Natural gas price swings directly compress NGL extraction economics, making cryogenic processing margins unpredictable for midstream operators.
- Gulf Coast concentration risk:Over 60% of US fractionation capacity sits within hurricane exposure zones, creating single-point supply vulnerability during storm seasons.
- Renewable naphtha substitution:Bio-based feedstocks and recycled plastic pyrolysis oils are capturing sustainability premiums in European petrochemical procurement.
Strategic Opportunities
- India petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding crackers in Gujarat and Odisha, creating new demand anchors for imported ethane and propane.
- Propane dehydrogenation (PDH) technology:On-purpose propylene production via PDH units is displacing naphtha crackers in China, requiring dedicated propane supply chains.
- US Department of Energy export authorizations:Streamlined permitting for new liquefaction and marine terminal capacity is unlocking stranded Permian Basin NGL production for Asian markets.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in sub-zero fractionation and refrigeration system design is concentrated among retiring professionals, constraining new project execution.
- Legacy pipeline metallurgy:Existing gathering infrastructure in the Permian and Appalachia requires costly retrofitting to handle higher-pressure rich-gas streams and corrosive sour gas components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Liquid Market |
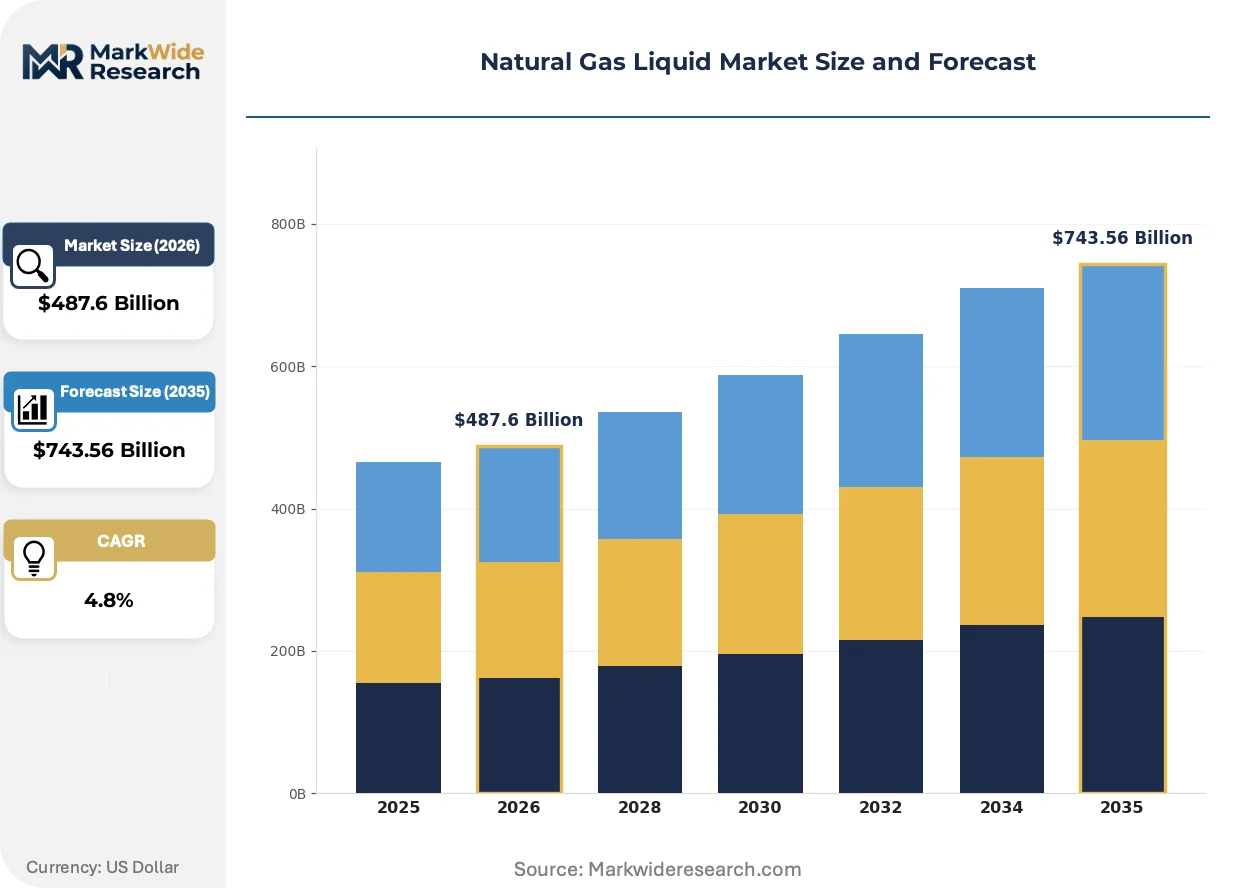
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethane, Propane, Butane, Natural Gasoline End User: Petrochemical Industry, Power Generation, Residential Heating, Transportation Application: Chemical Feedstock, Fuel Source, Solvent Production, Refining Distribution Channel: Pipelines, Tankers, Rail, Storage Facilities |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell plc, BP plc, ConocoPhillips, TotalEnergies SE, Enterprise Products Partners LP, Occidental Petroleum Corporation, Saudi Aramco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Liquid Market Emerging Trajectories
Digital twin technology and modular fractionation units are compressing project development cycles while enabling real-time optimization of NGL recovery rates. These advances are reducing the minimum economic scale for greenfield investments.
Modular cryogenic fractionation skids are rewriting deployment economics for marginal gas fields. Small-scale operators in the Permian Basin are adopting containerized units that slash installation timelines from years to months. This technology is compressing the capital barrier between exploration and full NGL commercialization.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in NGL fractionation cooling cycles. European operators face retrofit deadlines that accelerate adoption of ammonia-based and absorption refrigeration alternatives. German and Dutch chemical complexes are leading this transition, with compliance costs reshaping regional processing competitiveness.
Long-term tolling agreements are displacing spot market procurement among Asian petrochemical buyers. Japanese and South Korean crackers now prefer 10-15 year ethane supply contracts with fixed differentials to Mont Belvieu. This behavior shift is locking in US export volumes while compressing trading liquidity in short-term markets.
Natural Gas Liquid Market Segmentation
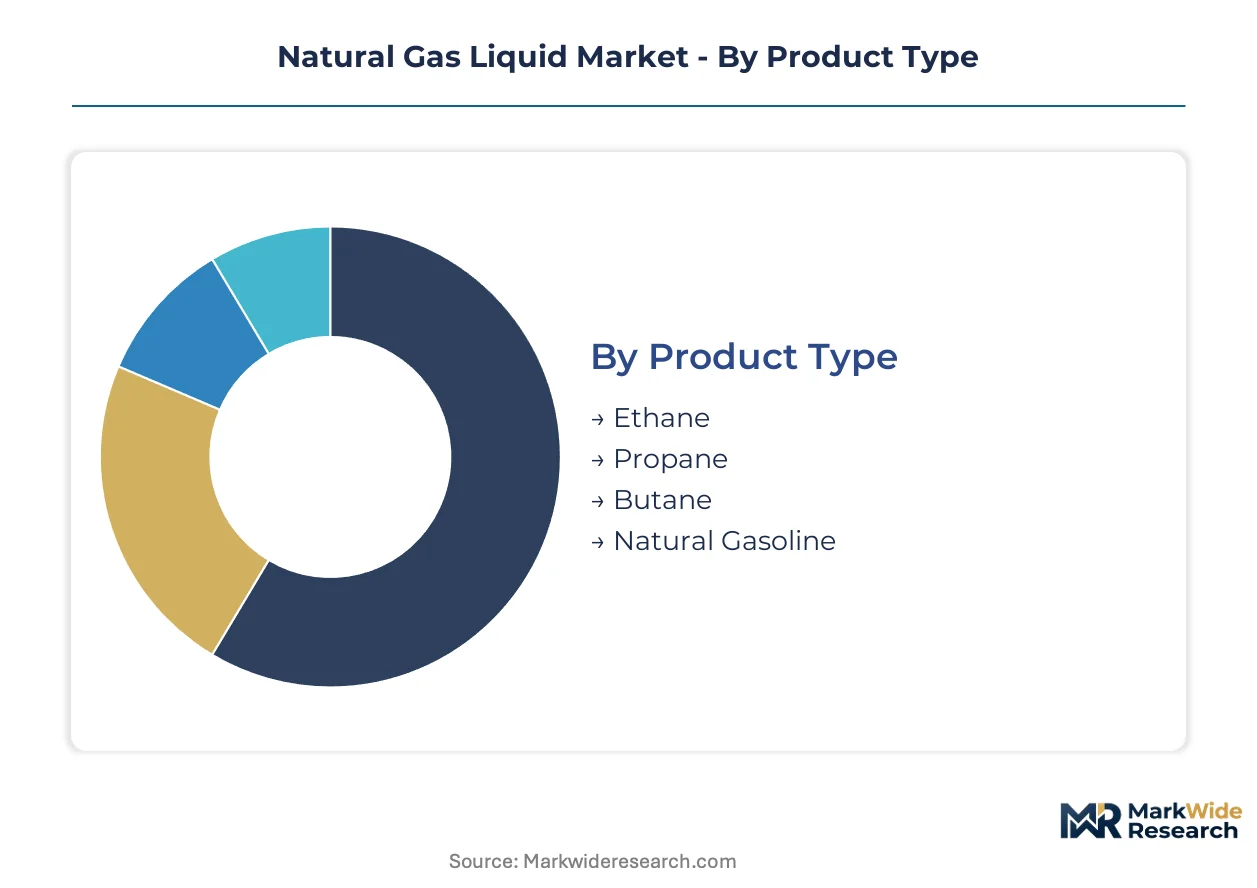
Segmentation in natural gas liquids separates molecules by carbon chain length and vapor pressure, determining which regulatory frameworks govern storage, transport, and end-use qualification. Each category carries distinct certification burdens that shape procurement economics and infrastructure investment priorities.
Product Type:
Ethane and propane face the most stringent EPA New Source Performance Standards for storage tank emissions, while butane and natural gasoline trigger additional DOT hazardous materials routing requirements for overland transport.
- Ethane:A two-carbon paraffin with the lowest boiling point among NGL components, requiring cryogenic handling at minus 127 degrees Fahrenheit. Demand concentrates along the US Gulf Coast petrochemical corridor, where ethane-only crackers at ExxonMobil Baytown and Shell Deer Park consume dedicated supply streams. The EPA methane intensity standards are accelerating closed-loop vapor recovery investments at extraction points.
- Propane:Three-carbon liquefied petroleum gas serving dual markets as residential heating fuel and petrochemical feedstock for on-purpose propylene production. Chinese PDH operators in Zhejiang and Shandong provinces are locking in long-term offtake agreements with US exporters, displacing naphtha in propylene supply chains. OSHA exposure limits during transfer operations add compliance costs to terminal operations.
- Butane:Four-carbon blendstock for gasoline vapor pressure adjustment and base feed for synthetic rubber production. The Texas Railroad Commission administers production quotas that directly affect supply availability.
- Natural Gasoline:Pentane-plus liquid with the highest carbon content, refined into motor fuel or light naphtha for chemical synthesis. Louisiana Department of Natural Resources pipeline safety protocols govern its transport to Gulf Coast refiners.
Leading the category by volume: Ethane. Growing fastest: Propane.
End User:
Cost tiers separate these segments, with petrochemical buyers commanding volume discounts through 10-15 year tolling agreements while residential heating markets absorb seasonal price volatility.
- Petrochemical Industry:Integrated crackers and fractionators consuming ethane and propane as olefin precursors. Reliance Industries Gujarat complex and Indian Oil Corporation Odisha facility anchor emerging Asian demand, requiring dedicated import terminal infrastructure for refrigerated vessel receipt.
- Power Generation:Peaking plants and distributed generation units burning propane or natural gasoline for grid reliability. The segment contracts during renewable penetration but expands in Texas and California during extreme weather events.
- Residential Heating:Seasonal demand concentrated in rural US Midwest and Northeast markets lacking natural gas distribution. FERC interstate pipeline regulations shape supply security during winter drawdowns.
- Transportation:Autogas conversions and fleet vehicle propane dispensing, constrained by EPA vehicle emission certification requirements and infrastructure scarcity outside established corridors.
Dominating procurement scale: Petrochemical Industry. Expanding most quickly: Power Generation.
Application:
Application maturity varies, with chemical feedstock representing the established baseline while solvent production captures premium margins in specialty chemical synthesis.
- Chemical Feedstock:The foundational use case, supplying ethylene crackers and propylene dehydrogenation units with standardized purity specifications. Mont Belvieu pricing hub liquidity enables transparent cost benchmarking for Asian contract negotiations.
- Fuel Source:Direct combustion in industrial boilers, agricultural equipment, and residential appliances, competing with natural gas and heating oil on delivered energy cost.
- Solvent Production:High-purity butane and natural gasoline fractions for pharmaceutical and electronics cleaning applications, commanding quality premiums tied to moisture and sulfur specifications.
- Refining:Alkylation feedstock and gasoline blendstock, with demand fluctuating according to seasonal Reid Vapor Pressure regulations administered by EPA regional offices.
Highest volume application: Chemical Feedstock. Steepest expansion trajectory: Solvent Production.
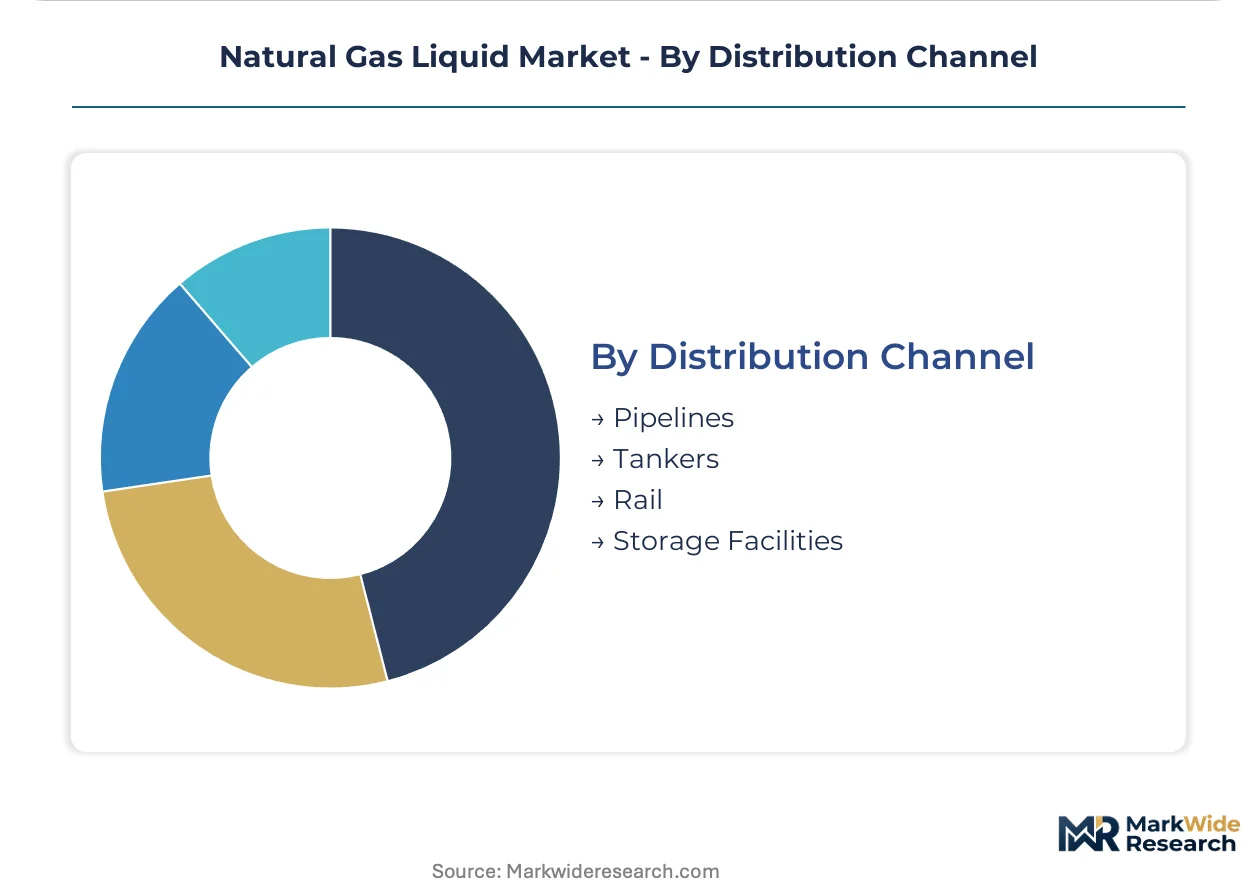
Distribution Channel:
Supply concentration defines competitive positioning, with pipeline networks offering lowest unit cost while tankers and rail provide flexibility for disaggregated demand.
- Pipelines:High-capacity gathering systems and interstate transmission lines linking Permian Basin production to Gulf Coast fractionation. Enterprise Products Partners operates the dominant network connecting Mont Belvieu to downstream consumers.
- Tankers:Refrigerated and pressurized marine vessels enabling US ethane exports to Asian crackers. US Department of Energy export authorizations determine terminal expansion pace.
- Rail:Unit trains serving inland petrochemical complexes and propane distributors beyond pipeline reach, subject to DOT hazmat routing and tank car specifications.
- Storage Facilities:Salt dome caverns and above-ground tanks providing price arbitrage and supply security, concentrated in Texas and Louisiana hurricane exposure zones.
Handling greatest throughput: Pipelines. Gaining infrastructure investment fastest: Tankers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin in Texas anchors upstream NGL production, while Mont Belvieu serves as the pricing and storage hub that connects US supply to Asian petrochemical demand.
United States
Gulf Coast petrochemical complexes at Baytown and Deer Park consume dedicated ethane streams from Permian gathering systems. EPA methane intensity standards accelerate vapor recovery investments at extraction points. Enterprise Products Partners operates fractionation infrastructure linking Mont Belvieu to downstream consumers.
China
Zhejiang and Shandong provinces host propane dehydrogenation units displacing naphtha in propylene supply chains. The Ministry of Ecology and Environment enforces dual carbon goals tightening industrial emissions benchmarks. Sinopec and private operators expand crackers in Yangtze River Delta chemical clusters.
Saudi Arabia
Saudi Aramco leverages domestic gas reserves to supply captive petrochemical complexes at Jubail and Yanbu. The Saudi Standards, Metrology and Quality Organization administers product specifications for NGL derivatives. Eastern Province industrial cities concentrate ethane cracker capacity serving Asian export markets.
India
Reliance Industries Gujarat complex and Indian Oil Corporation Odisha facility anchor emerging demand for imported ethane and propane. Petroleum and Natural Gas Regulatory Board oversees pipeline safety and terminal access protocols. Gujarat Maritime Board facilitates refrigerated vessel receipt at Dahej and Hazira ports.
South Korea
Yeosu and Ulsan industrial complexes operate ethane-only crackers locking in long-term US supply contracts. Ministry of Trade, Industry and Energy coordinates strategic stockpiling and import diversification. Korean petrochemical buyers prefer 10-15 year tolling agreements with Mont Belvieu-linked pricing.
Natural Gas Liquid Market Vendor Landscape
Global majors compete with regional champions across integrated value chains, with asset-heavy upstream operators facing specialized midstream fractionators for margin capture. The structure tiers between supermajor oil companies holding Permian acreage and independent midstream partnerships controlling Gulf Coast infrastructure. Strategic archetypes include upstream-integrated producers, pure-play midstream operators, and downstream petrochemical consumers securing captive feedstock. Dominant competitive moves encompass gathering system consolidation and long-term tolling contract origination.
Within the upstream-integrated tier, ExxonMobil Corporation and Chevron Corporation exemplify acreage-holding producers capturing NGL volumes at the wellhead. Shell plc anchors European demand through Rotterdam chemicals complex positioning. Enterprise Products Partners LP occupies the midstream specialist position with fractionation and pipeline network concentration.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| BP plc |
| ConocoPhillips |
| TotalEnergies SE |
| Enterprise Products Partners LP |
| Occidental Petroleum Corporation |
| Saudi Aramco |
| Others |
Supply Flow & Price Mechanics
Mont Belvieu pricing hub liquidity cascades through natural gas liquid supply chains, compressing spot market premiums while elevating long-term tolling contract differentials for Asian petrochemical buyers. Henry Hub volatility feeds directly into extraction economics, forcing midstream operators to hedge cryogenic processing margins through integrated storage positions.
Pricing Analysis
Long-term tolling agreements bundle marine freight and terminal handling into fixed differentials, while spot cargoes expose buyers to unbundled demurrage and refrigeration costs. Contract-based long-term offtake dominates ethane procurement, with volume scale and Mont Belvieu linkage serving as the primary price differentiation drivers. Cost compression in spot propane runs through hurricane-season supply vulnerability, making residential heating buyers most price-sensitive while integrated crackers absorb volatility through captive storage.
Supply Chain Analysis
Domestic-content mandates in India's Petroleum and Natural Gas Regulatory Board framework are reshaping terminal infrastructure sourcing toward local fabrication partners. Supply concentrates in the United States, Saudi Arabia, and China, with ethane and propane feedstock flows anchored in Permian Basin gathering systems. Logistics chokepoint risk clusters around Gulf Coast salt dome caverns within hurricane exposure zones. Distribution runs through pipeline networks to Mont Belvieu, then refrigerated tankers to Asian crackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural gas liquid markets are becoming a vertical-integration race, with upstream acreage holders building captive fractionation capacity and midstream operators acquiring wellhead gathering systems to secure supply.
For Market Incumbents: Acquire cryogenic fractionation assets in the Permian Basin to capture margin between wellhead extraction and Gulf Coast delivery. Secure long-term tolling agreements with Reliance Industries and Korean petrochemical buyers before new export terminal capacity floods the market. Backward integration into rich-gas gathering systems defends against pure-play midstream competitors. For New Entrants and Emerging Players: Enter via modular cryogenic skids serving marginal Permian fields abandoned by majors chasing scale economies. Target propane dehydrogenation feedstock supply to Chinese operators in Zhejiang province, where naphtha displacement creates white-space demand. License containerized fractionation technology from specialized engineering firms to compress deployment timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor midstream partnerships with underutilized Mont Belvieu storage capacity during Henry Hub price spikes that crush extraction economics. Long-term viability hinges on Asian cracker demand sustaining ethane import growth over the next decade. Watch EPA methane intensity standard enforcement as the inflection signal for vapor recovery equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gathering Systems | ExxonMobil's Permian wellhead capture secures ethane supply before midstream markup. |
| Long-term Supply Agreement | Enterprise Products Partners locks Korean crackers into Mont Belvieu-linked tolling contracts. |
| Capacity Expansion | Indian Oil Corporation's Odisha terminal builds refrigerated vessel receipt infrastructure. |
| Joint Venture | Shell's Rotterdam complex anchors European propane demand through integrated processing. |
| Green Certification Program | EU F-Gas Regulation compliance reshapes refrigeration system investments at Dutch fractionators. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this natural gas liquid market analysis. Primary interviews with midstream infrastructure planners, petrochemical procurement leads, cryogenic engineering specialists, and terminal operations managers combined with EIA production statistics, FERC pipeline capacity reports, and EPA emissions disclosures. Bottom-up field-level production estimates triangulated against top-down regional consumption benchmarks.
Segment-level granularity modeled ethane, propane, butane, and natural gasoline volumes separately across petrochemical, residential heating, power generation, and transportation end uses. Regional production hub clustering captured Permian, Appalachia, and international supply dynamics. CAGRs derived from capacity expansion timelines and cracker investment cycles, with Henry Hub price scenarios and marine freight rate assumptions feeding margin sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hurricane disruption and methane regulation acceleration scenarios. Assumptions include sustained Asian ethane import growth and no breakthrough in renewable naphtha cost parity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Oil Shale Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Pale Oil Market