
 Europe Completion Equipment and Services Market | 2026-2036
Europe Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Completion Equipment and Services Market Foresight
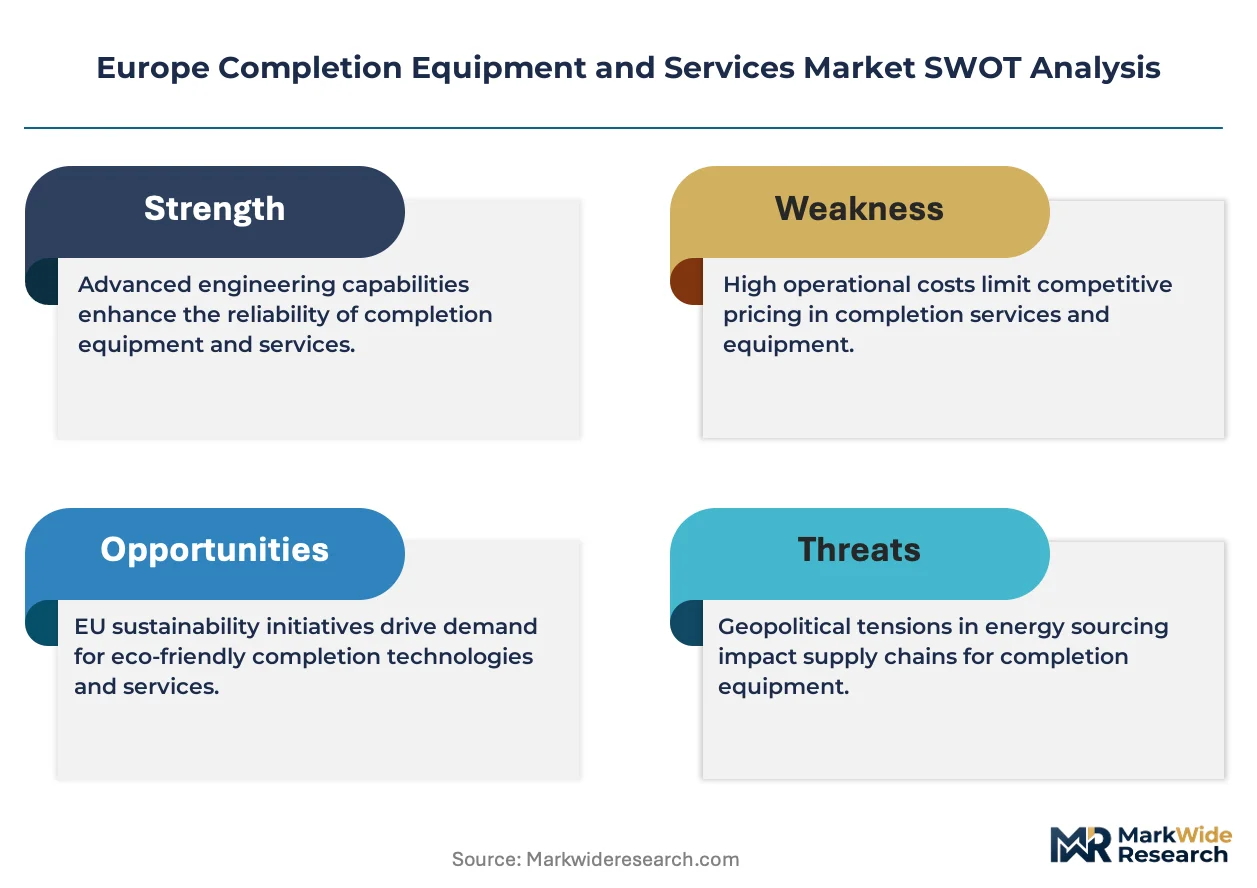
Offshore gas producers are reorganizing capital allocation toward intelligent completion systems as North Sea reservoir depletion intensifies. Schlumberger Ltd leverages deepwater technology leadership to anchor premium service contracts across Norwegian and UK continental shelf projects. Halliburton Company sustains its stimulation services footprint through integrated well testing and cementing packages tailored to high-pressure high-temperature formations. Baker Hughes Company differentiates via permanent monitoring hardware that reduces intervention frequency in subsea tiebacks.
Europe completion equipment and services encompasses the hardware, downhole tools, and technical services required to prepare a drilled well for hydrocarbon production, including packers, sand control systems, and wellbore cleanout equipment rated for pressures exceeding 15,000 psi and temperatures above 350°F. Completion tools constitute the largest product segment by installed base, though sand control systems represent the fastest-growing category as operators target unconsolidated formations in mature North Sea fields. Well testing services command the highest margin pool within service types due to real-time data requirements and specialized personnel, while stimulation services face structural pressure from carbon intensity disclosures under EU sustainability frameworks.
REACH and the EU Green Deal shape material selection and emission thresholds for completion chemicals and offshore logistics, while Norway's Petroleum Safety Authority enforces well integrity standards that dictate packer certification and barrier verification protocols. The F-Gas Regulation restricts fluorinated compound use in downhole monitoring equipment, compelling manufacturers to redesign sensor housings and sealing systems. Stakeholders must monitor regulatory divergence between EU-wide climate mandates and UK North Sea licensing reforms as investment timelines extend beyond current policy cycles.
Market Dynamics
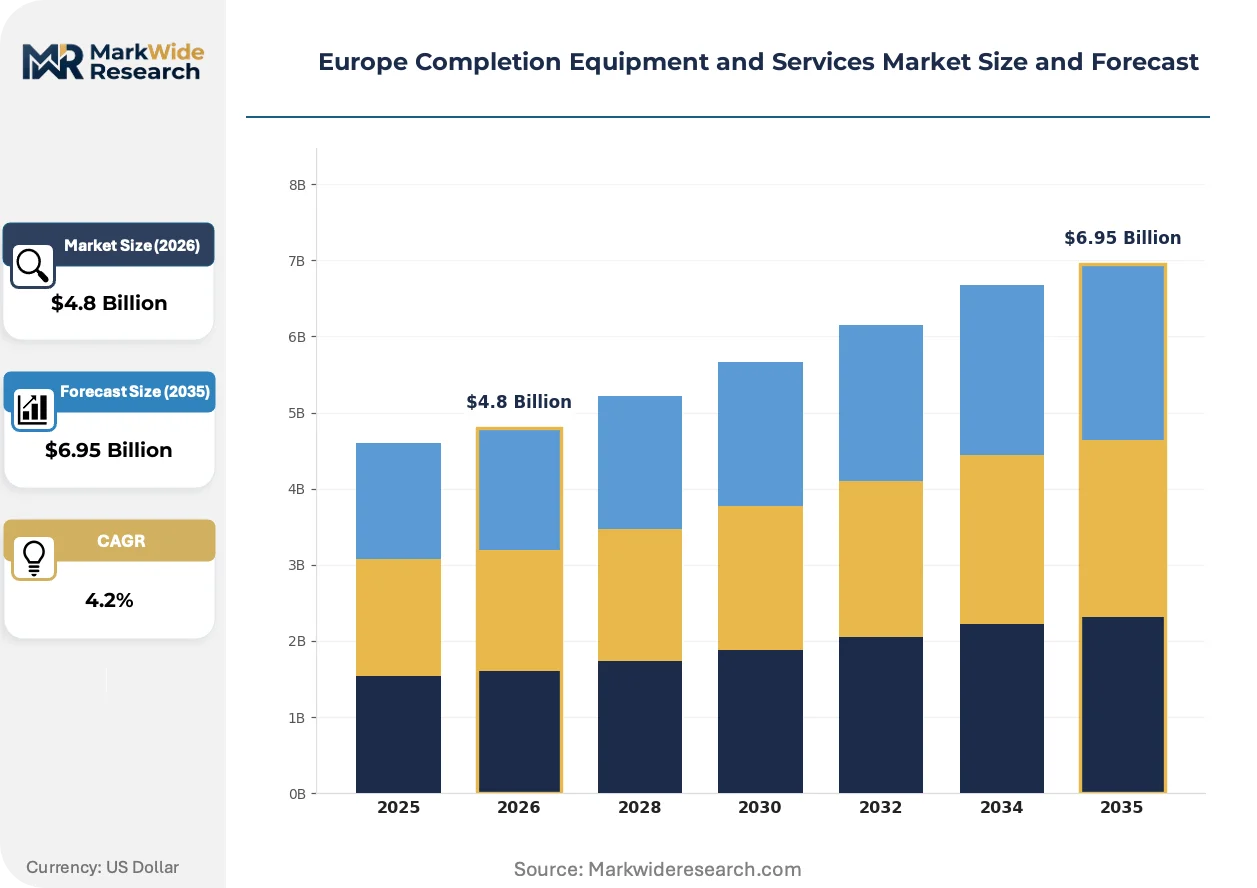
North Sea reservoir depletion is forcing operators toward intelligent completion systems that deliver real-time downhole data, compressing the economic life of conventional mechanical completions while elevating service contract values for digitally integrated packages.
Growth Catalysts
- EU Green Deal methane mandates:Operators must deploy lower-emission completion technologies, accelerating demand for electric actuation systems and sealed wellbore designs that eliminate venting during interventions.
- Norwegian continental shelf redevelopment:Equinor-led projects require advanced intelligent completions to manage commingled production from depleted reservoirs, concentrating equipment demand in the North Sea.
- Hydraulic fracturing in unconsolidated formations:Sand control systems are expanding rapidly as operators target high-permeability zones previously bypassed in mature fields.
Market Restraints
- Specialized alloy supply concentration:Premium completion metallurgy for high-pressure high-temperature service depends on a limited supplier base in Germany and Austria, creating input cost volatility.
- F-Gas Regulation technical barriers:Fluorinated compound restrictions under EU law force redesign of downhole sensor housings, extending product development timelines for monitoring equipment.
- Carbon accounting disclosure requirements:REACH compliance and EU sustainability frameworks add documentation burden that disadvantages smaller service providers lacking dedicated regulatory teams.
Strategic Opportunities
- Polish Baltic Sea offshore expansion:Emerging gas development programs outside traditional North Sea hubs offer first-mover positioning for completion service providers with modular rigless deployment capability.
- Geothermal repurposing of oilfield expertise:Drilling and completion knowledge from hydrocarbon operations transfers directly to deep geothermal projects, opening adjacent revenue streams as EU renewable targets harden.
- Integrated well testing and digital twin convergence:Real-time data analytics layered onto conventional well testing services creates outcome-based pricing models that operators in Norway and UK waters increasingly prefer.
Industry Challenges
- Downhole electronics reliability certification:Permanent monitoring hardware must demonstrate 25-year service life in corrosive environments, stretching validation protocols beyond conventional timelines.
- Cross-border regulatory divergence:UK North Sea licensing reforms post-Brexit create compliance fragmentation for service providers operating across Norwegian, UK, and EU jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Completion Equipment and Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Completion Tools, Wellbore Cleanout Equipment, Packers, Sand Control Systems Service Type: Well Testing, Stimulation Services, Cementing Services, Logging Services End User: Exploration Companies, Oil Producers, Gas Producers, Service Providers Installation Type: Onshore, Offshore, Modular, Permanent |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, Trican Well Service Ltd, Welltec AS, Schoeller-Bleckmann Oilfield Equipment AG, Weir Group plc, NOV Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Completion Equipment and Services Market Shifts & Advancements
Digital integration is compressing the traditional separation between hardware installation and production optimization, with real-time telemetry now embedded as standard in premium completion contracts rather than offered as aftermarket upgrade.
Downhole fiber-optic sensing is miniaturizing from large-diameter intervention-dependent systems to slimline permanent installations that fit within standard tubing specifications. North Sea operators are adopting these systems at accelerating pace for reservoir surveillance in subsea tiebacks. This miniaturization is collapsing the distinction between monitoring and production tubing, enabling commingled zone management without mechanical intervention.
REACH and the EU Green Deal are reshaping material selection protocols for completion chemicals and offshore logistics, with ECHA substance restrictions now governing everything from packer elastomers to wellbore cleanout surfactants. Manufacturers must reformulate product lines to meet emission thresholds and biodegradability standards. Sand control chemical systems face the steepest compliance burden, driving substitution toward bio-based polymer alternatives.
Buyer concentration among Norwegian and UK supermajors is consolidating procurement authority into centralized technical committees that unbundle traditional service packages. Discrete contracting for well testing, stimulation, and intelligent completion hardware replaces integrated field development awards. This pattern is most pronounced in Equinor's supplier rationalization program, which separates equipment purchase from installation and commissioning services.
Europe Completion Equipment and Services Market Segmentation
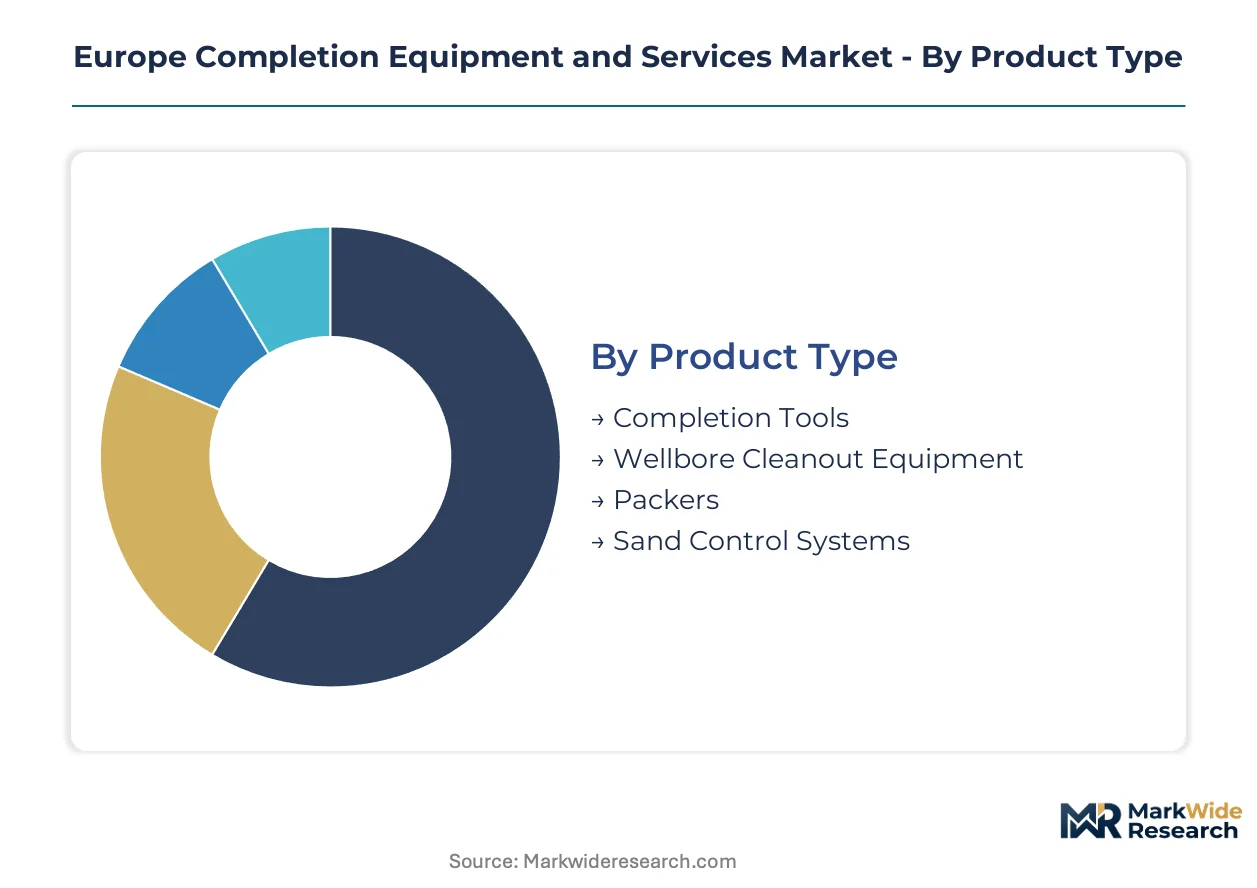
Completion equipment and services segmentation reveals how North Sea operators allocate capital across hardware, services, and deployment modes. Category boundaries are blurring as intelligent systems integrate formerly discrete product and service lines.
Product Type:
Domestic manufacturing concentrates in Germany and Austria for premium metallurgy, while sand control system assembly increasingly sources from UK fabrication hubs serving Norwegian projects.
- Completion Tools:Downhole hardware including sliding sleeves, safety valves, and landing nipples rated for pressures exceeding 15,000 psi. Norwegian supermajors anchor demand through Equinor-led field redevelopment programs requiring intelligent completion configurations.
- Sand Control Systems:Gravel pack tools, screens, and chemical consolidation systems targeting unconsolidated formations in mature North Sea reservoirs. UK and Dutch operators drive fastest category expansion as high-permeability zones previously bypassed now become economic targets.
- Packers:Mechanical and hydraulic sealing devices manufactured to Norway Petroleum Safety Authority well integrity standards. German specialty alloy suppliers constrain input availability for high-temperature variants.
- Wellbore Cleanout Equipment:Circulation tools and debris removal systems deployed during completion phase. North Sea offshore logistics favor modular designs compatible with platform crane capacity limits.
Completion tools hold the largest share; momentum sits with sand control systems.
Service Type:
Margin structures diverge sharply between data-intensive well testing and carbon-exposed stimulation services facing EU disclosure pressure.
- Well Testing:Real-time reservoir evaluation and flow assurance verification commanding premium pricing due to specialized personnel requirements and continuous data acquisition. Norwegian operators prioritize integrated digital twin convergence for subsea tieback validation.
- Stimulation Services:Hydraulic fracturing and acidizing treatments constrained by REACH chemical restrictions and methane emission accounting under EU Green Deal frameworks. UK North Sea licensing reforms add compliance fragmentation for cross-border service providers.
- Cementing Services:Zonal isolation and casing support operations tailored to high-pressure high-temperature North Sea formations. Barrier verification protocols follow Norway Petroleum Safety Authority specifications.
- Logging Services:Formation evaluation and completion diagnostics using wireline and logging-while-drilling technologies. Electric line deployment expands as operators reduce intervention frequency.
Well testing commands the highest margin pool; stimulation services face structural pressure from sustainability frameworks.
End User:
Buyer concentration among Norwegian and UK supermajors consolidates procurement authority into centralized technical committees.
- Oil Producers:North Sea operators managing mature field decline through infill drilling and intelligent completion retrofits. Capital allocation prioritizes real-time downhole monitoring over conventional mechanical systems.
- Gas Producers:Offshore developers in Norwegian and UK continental shelf waters expanding completion program spending as reservoir complexity rises. EU methane regulations accelerate demand for sealed wellbore designs.
- Exploration Companies:Early-stage field developers requiring modular completion packages compatible with appraisal well conversion. Polish Baltic Sea expansion creates first-mover positioning opportunities.
- Service Providers:Integrated oilfield service contractors unbundling traditional packages into discrete equipment purchase and installation contracts. Equinor supplier rationalization program drives this segmentation.
Oil producers represent the largest installed base; gas producers are expanding most quickly.
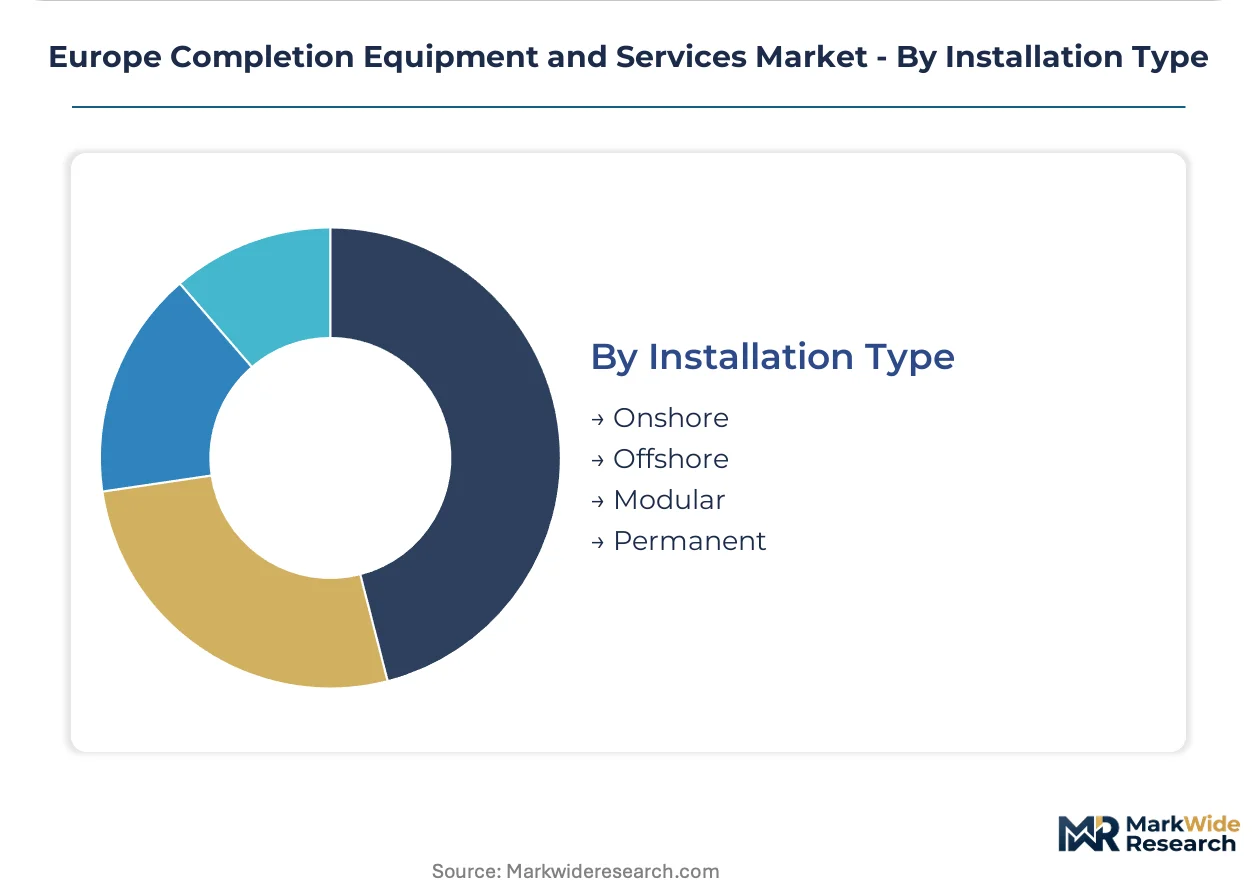
Installation Type:
Deployment economics favor permanent installations in Norwegian deepwater while UK operators retain modular flexibility for shorter field life cycles.
- Offshore:Subsea and platform-based completions dominating North Sea expenditure. Fiber-optic miniaturization enables permanent monitoring within standard tubing specifications.
- Permanent:Long-duration installations with 25-year service life certification requirements. Downhole electronics reliability validation stretches conventional timelines.
- Onshore:Limited European presence concentrated in Romanian and Polish conventional developments. Geothermal repurposing opens adjacent revenue streams.
- Modular:Rigless deployment configurations suited to marginal field economics and intervention-heavy mature assets. Polish Baltic Sea programs favor this approach.
Offshore installations dominate value; permanent systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian equipment exports supply UK and Dutch offshore projects through North Sea logistics corridors, while German metallurgical suppliers feed completion hardware fabrication across the continent.
Norway
Equinor-led field redevelopment programs anchor demand for intelligent completion systems rated to 15,000 psi. The Petroleum Safety Authority enforces well integrity standards that dictate packer certification and barrier verification protocols. Stavanger and Bergen host engineering clusters where subsea tieback projects concentrate procurement authority.
United Kingdom
UK continental shelf operators expand completion spending on mature field infill drilling and sand control retrofits. Post-Brexit licensing reforms create regulatory divergence from EU methane mandates, fragmenting compliance for cross-border service providers. Aberdeen maintains its position as the primary North Sea service hub.
Germany
Premium alloy suppliers in Germany and Austria constrain input availability for high-temperature completion metallurgy, creating supply bottlenecks. REACH chemical restrictions govern packer elastomer formulation and wellbore cleanout surfactant selection. Industrial clusters in North Rhine-Westphalia and Bavaria fabricate pressure-rated downhole hardware.
Netherlands
Dutch operators target unconsolidated formations in mature Groningen and offshore fields, accelerating sand control system deployment. EU Green Deal methane regulations push adoption of sealed wellbore designs and electric actuation systems. Rotterdam logistics hubs coordinate offshore equipment staging for North Sea campaigns.
Poland
Emerging Baltic Sea gas development programs create first-mover positioning opportunities for modular rigless completion deployment. ECHA substance restrictions under REACH compliance frameworks govern offshore logistics and chemical selection. Gdańsk and Szczecin port infrastructure supports offshore supply chain expansion.
Europe Completion Equipment and Services Market Competitive Landscape
Listed leaders compete with private specialists across technology integration and regional coverage dimensions. The vendor base separates into three tiers: integrated service conglomerates with full hardware-service portfolios, regional equipment fabricators with metallurgical specialization, and digital-focused specialists in intelligent completion telemetry. Consolidation pressure concentrates in the mid-tier as procurement unbundling favors discrete contracting over integrated awards. Dominant competitive moves include backward integration into alloy supply and technology licensing partnerships for downhole monitoring systems.
Within the integrated service tier, Schlumberger Ltd, Halliburton Company, and Baker Hughes Company occupy positions as archetypal full-line providers. These entities represent the scale-driven end of competitive positioning, anchoring premium contract awards through combined equipment-service offerings. Their geographic footprints span Norwegian, UK, and continental European markets, exemplifying the cross-border operational capability that procurement centralization now demands.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| Trican Well Service Ltd |
| Welltec AS |
| Schoeller-Bleckmann Oilfield Equipment AG |
| Weir Group plc |
| NOV Inc |
| Others |
Supply & Pricing Matrix
Norway's Petroleum Safety Authority well integrity standards gate both supplier qualification and price stratification simultaneously, mandating 25-year service life certification for downhole electronics that only premium-tier manufacturers can achieve. This regulatory threshold splits the vendor base into certified incumbents commanding contract premiums and uncertified challengers competing on modular rigless deployment economics.
Pricing Analysis
Next-generation intelligent completion systems with embedded fiber-optic telemetry command 40-60% contract premiums over conventional mechanical configurations, while prior-generation packer and sand control hardware faces margin compression from procurement unbundling. Three-tier pricing structure across premium intelligent systems, standard mechanical completions, and economy modular packages reflects certification grade and real-time data capability. Pricing pressure stems from Equinor-led supplier rationalization programs that separate equipment purchase from installation services. Exploration companies in Polish Baltic Sea developments exhibit highest price sensitivity, while Norwegian supermajors prioritize outcome-based digital twin convergence over unit cost.
Supply Chain Analysis
Rotterdam port congestion and North Sea container availability constraints inflate inbound logistics costs for UK and Dutch offshore staging operations, compressing delivery windows during campaign-intensive summer months. Premium completion metallurgy concentrates in Germany and Austria, with gravel pack screen fabrication increasingly shifting to UK hubs serving Norwegian projects. Supply chains draw from specialty alloy feedstock, high-temperature elastomer compounds, and miniaturized fiber-optic sensor arrays. Single-source vulnerability sits with German superalloy suppliers for HPHT-rated packer components. Distribution runs through Stavanger and Bergen engineering clusters coordinating subsea tieback procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Norwegian and UK supermajors through centralized technical committees, fragmenting traditional integrated service awards into discrete equipment and installation contracts that disadvantage mid-tier vendors.
For Market Incumbents: Consolidate backward integration into German and Austrian specialty alloy supply to secure input availability for HPHT packer certification. Anchor premium positioning through captive manufacturing of permanent monitoring hardware that meets Norway Petroleum Safety Authority 25-year validation protocols. Defend against procurement unbundling by bundling digital twin analytics with well testing services under outcome-based pricing structures. For New Entrants and Emerging Players: Norway Petroleum Safety Authority certification fast-tracks for intelligent completion electronics offer entry pathways without incumbents' legacy mechanical installed base. Polish Baltic Sea modular rigless deployment programs present the most penetrable geography, with exploration companies prioritizing capital flexibility over integrated service packages. Go-to-market positioning should emphasize rapid deployment velocity and lower-carbon electric actuation systems aligned with EU Green Deal methane mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across permanent monitoring hardware sub-segments as 25-year reliability validation stretches R&D timelines and working capital requirements. Long-term viability favors vendors with demonstrated Norway Petroleum Safety Authority certification track records and established subsea tieback reference projects. Acquisition target archetype: digital-focused specialists in downhole fiber-optic telemetry with validated North Sea deployments. Signal to watch: Equinor supplier rationalization program expansion into cementing and logging services unbundling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive access to German and Austrian HPHT metallurgy secures packer certification and input cost stability. |
| Digital Twin Convergence with Well Testing | Outcome-based pricing models align vendor incentives with Norwegian operator production optimization targets. |
| Modular Rigless Deployment Capability | Polish Baltic Sea expansion favors capital-light configurations compatible with marginal field economics. |
| Permanent Monitoring Hardware Miniaturization | Fiber-optic slimline integration collapses distinction between monitoring and production tubing in subsea tiebacks. |
| EU Green Deal Compliance Repositioning | Electric actuation and sealed wellbore designs eliminate venting during interventions under methane regulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, incorporating completion engineering directors at Norwegian supermajors, procurement leads at UK continental shelf operators, technical R&D heads at German metallurgical suppliers, and aftermarket service managers at Aberdeen-based contractors. Secondary validation drew from Norway Petroleum Safety Authority certification databases, ECHA REACH substance restriction filings, EU Green Deal methane emission disclosure frameworks, and North Sea project development announcements. Bottom-up equipment unit economics were triangulated against top-down operator capital expenditure patterns.
Across the projection horizon, the analytical framework modeled completion tools, sand control systems, packers, and wellbore cleanout equipment by service type, installation mode, and end-user category. CAGRs were derived from segment-level demand build-ups incorporating field redevelopment timelines, regulatory compliance cost pass-through, and technology substitution curves for intelligent versus mechanical completions. Industry-specific inputs included Equinor supplier rationalization program scope, F-Gas Regulation redesign timelines for downhole sensors, and Polish Baltic Sea licensing round progress.
Decision-makers should treat outputs as directional under assumptions of sustained Norway Petroleum Safety Authority certification stringency and stable EU methane regulatory frameworks; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions regarding North Sea reservoir depletion rates and intelligent completion adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Tricone Bits Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Egypt Natural Gas Market