
 Deepwater Hydrocarbons Exploration Market | 2026-2036
Deepwater Hydrocarbons Exploration Market Size, Share, and Industry Trends Forecast 2026-2036
Deepwater Hydrocarbons Exploration Market Outlook
Buyer concentration among oilfield operators is consolidating as national oil companies and supermajors internalize more exploration capabilities and reduce reliance on independent service contractors. ExxonMobil leverages its integrated project delivery model to control deepwater development timelines from prospect evaluation through production startup. Shell sustains technology leadership through proprietary seismic imaging and subsea processing systems deployed across its Atlantic Margin portfolio. Petrobras anchors Latin American deepwater activity through its dominant position in Brazil's pre-salt province.
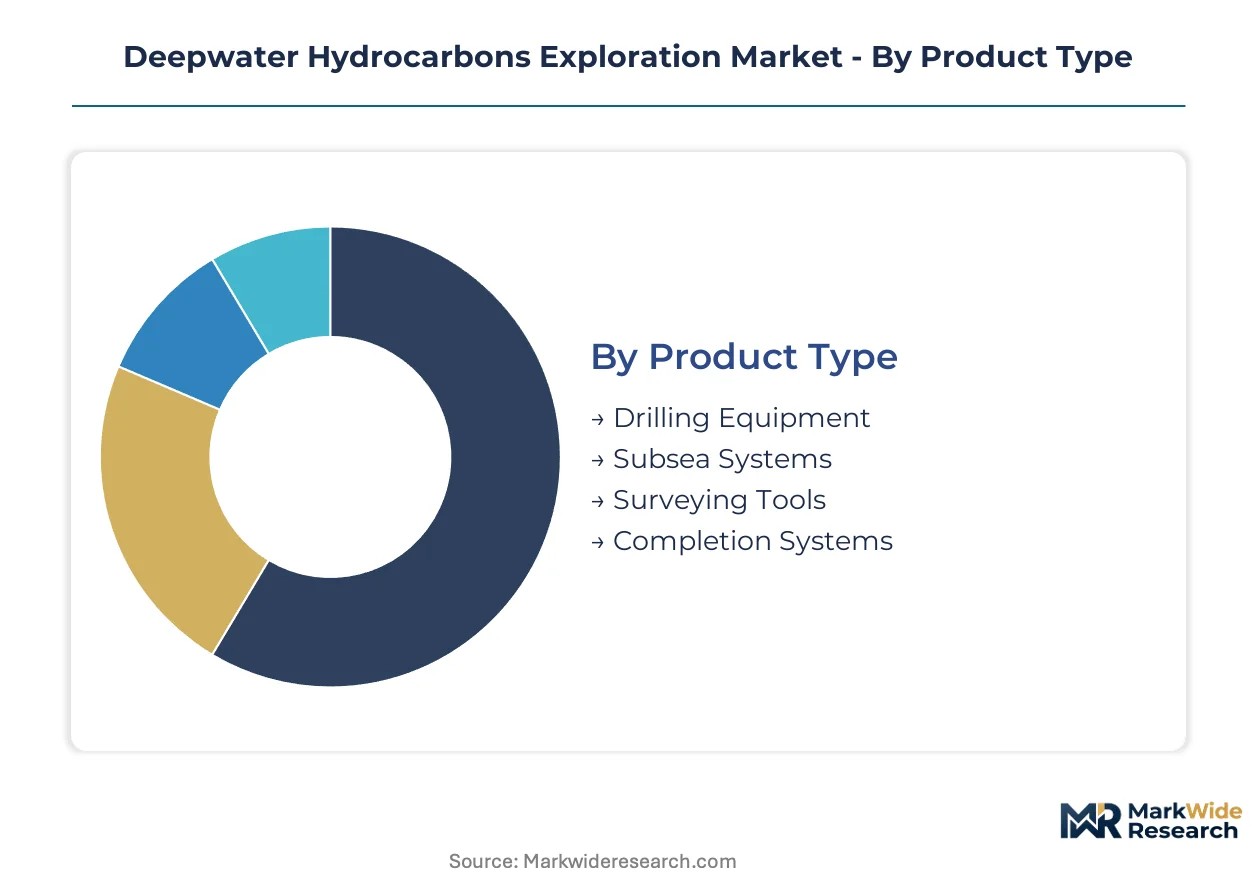
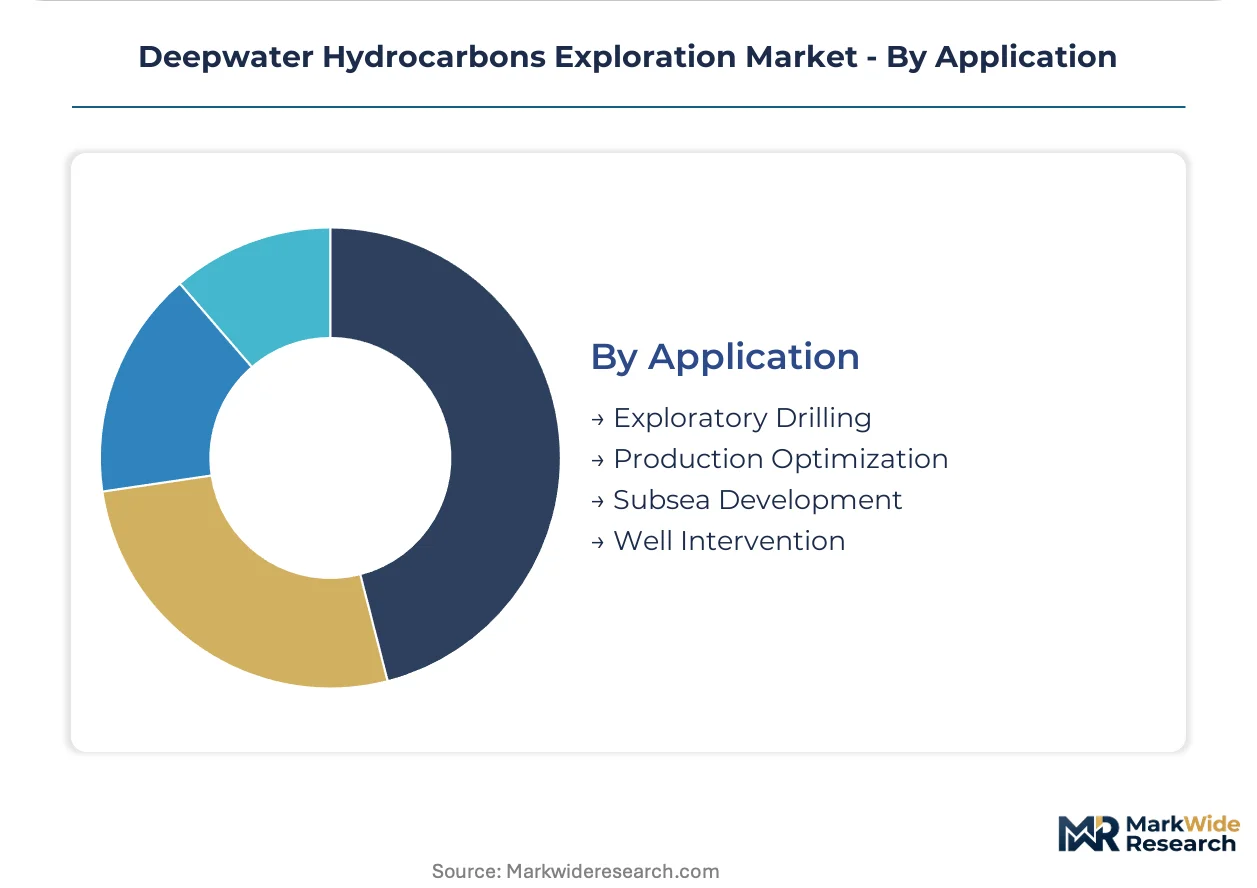
Deepwater hydrocarbons exploration encompasses the search for and appraisal of oil and natural gas deposits in water depths exceeding 400 meters, employing dynamically positioned drillships, subsea blowout preventers, and remotely operated vehicles capable of operating at pressures exceeding 15,000 psi. The primary commercial purpose is to identify recoverable reserves sufficient to justify capital-intensive field development with production facilities designed for decades-long operational life. Drilling equipment commands the largest capital allocation within product type segments due to rig dayrate exposure and consumables intensity. ROV technology represents the fastest-expanding technology segment as autonomous underwater vehicles displace tethered systems for routine inspection tasks. Exploratory drilling generates the highest value per barrel among applications, though subsea development delivers superior margins through repeatable engineering templates.
The US Bureau of Safety and Environmental Enforcement enforces blowout preventer testing protocols that shape equipment procurement standards for Gulf of Mexico operations. Brazil's National Petroleum Agency imposes local content requirements that structure supply chain participation for pre-salt block awards. Norway's Petroleum Safety Authority mandates integrated operations planning that influences contractor selection and risk allocation frameworks. Stakeholders must monitor regulatory divergence between prescriptive equipment standards and performance-based safety regimes as this tension determines competitive positioning across Atlantic Basin deepwater provinces.
Market Dynamics
Subsea tieback technology is compressing development timelines for marginal deepwater fields, enabling operators to commercialize reservoirs that previously required standalone production facilities and billion-dollar capital commitments.
Growth Catalysts
- Brazil's local content mandates:ANP requirements for pre-salt block awards are structuring supply chain participation and driving domestic fabrication capacity expansion for subsea equipment.
- Autonomous underwater vehicle proliferation:AUVs are displacing tethered ROV systems for routine inspection tasks, reducing operational costs and extending subsea intervention reach.
- Pre-salt basin appraisal:Petrobras and partner operators are accelerating exploration drilling across Brazil's Santos Basin, generating sustained demand for high-specification drillships.
Market Restraints
- Ultra-deepwater rig supply concentration:The global fleet of drillships capable of operating beyond 3,000 meters water depth remains concentrated among a limited contractor base, creating rate volatility exposure.
- High-pressure high-temperature technical barriers:Reservoir conditions exceeding 15,000 psi and 200°C in the Gulf of Mexico's Lower Tertiary trend constrain completion equipment reliability.
- Blowout preventer certification friction:US BSEE testing protocols extend procurement cycles and elevate capital requirements for Gulf of Mexico drilling programs.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater provinces offshore Mauritania, Senegal, and Côte d'Ivoire offer untapped resource potential as seismic imaging improves.
- Subsea processing integration:Convergence of subsea compression and boosting technologies with all-electric control systems enables longer tieback distances and lower facility footprints.
- Norwegian integrated operations mandates:PSA requirements for remote operations planning are accelerating digital twin adoption and creating vendor opportunities in real-time monitoring systems.
Industry Challenges
- Deepwater geoscience talent scarcity:Specialized expertise in pre-salt carbonate reservoir characterization and subsalt imaging remains concentrated among a shrinking cohort of experienced interpreters.
- Subsea equipment qualification timelines:Extended factory acceptance testing and offshore commissioning protocols for HPHT wellheads compress project schedules and strain contractor working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deepwater Hydrocarbons Exploration Market |
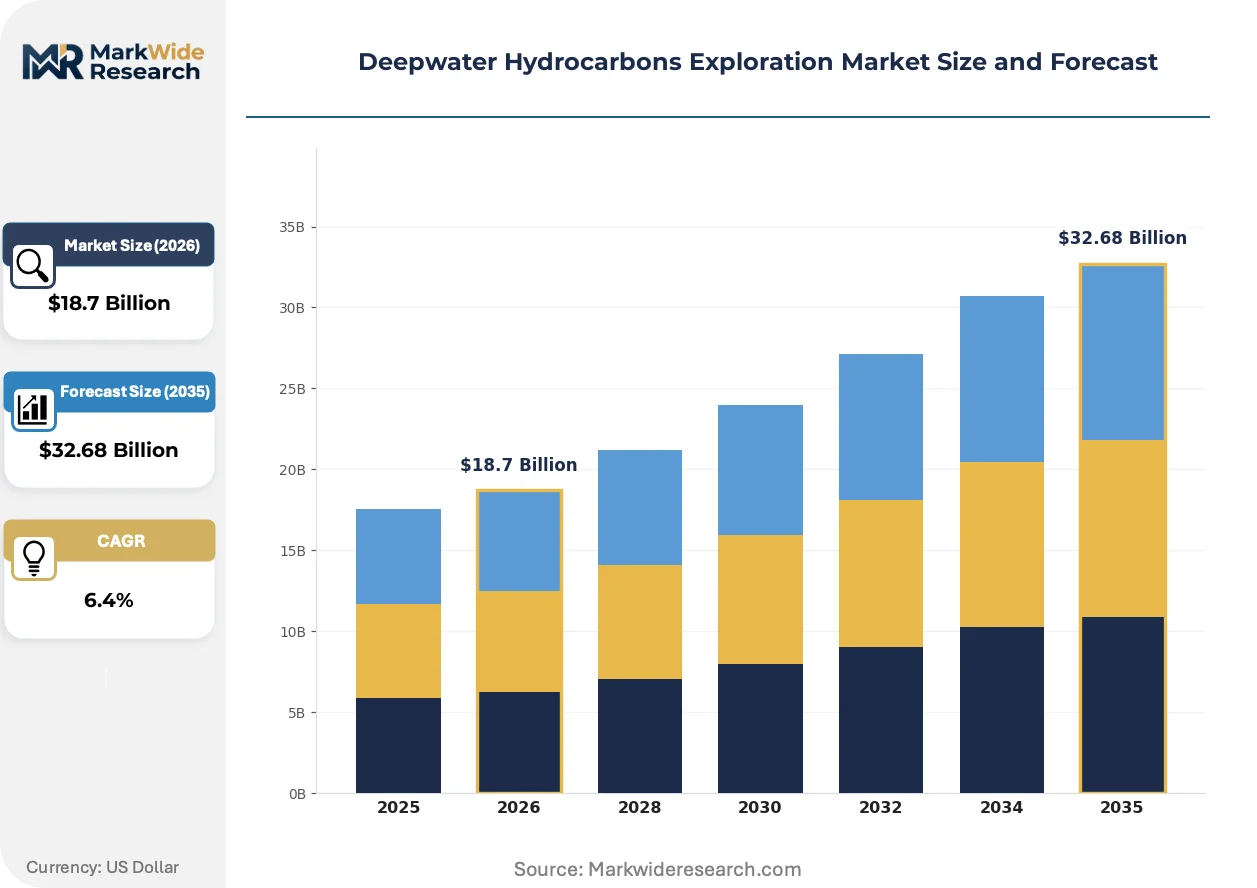
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Equipment, Subsea Systems, Surveying Tools, Completion Systems Technology: Remote Sensing, Geophysical Imaging, Blowout Preventers, ROV Technology End User: Oilfield Operators, Exploration Companies, Service Providers, Government Agencies Application: Exploratory Drilling, Production Optimization, Subsea Development, Well Intervention |
| Companies Covered | ExxonMobil, Shell, Chevron, TotalEnergies, BP, Petrobras, Equinor, ConocoPhillips, Eni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deepwater Hydrocarbons Exploration Market Strategic Shifts
Digitalization is restructuring how deepwater operators manage reservoir uncertainty, compressing the cycle from seismic acquisition to drilling decision and enabling real-time adjustments to exploration programs based on streaming well data.
All-electric subsea production systems are electrifying control architecture across new field developments, replacing hydraulic umbilicals with power and data transmission through single-cable infrastructure. Operators in Norway's Johan Sverdrup and Brazil's Mero fields are deploying these systems at scale. This technology is electrifying subsea field architecture by eliminating hydraulic fluid volumes and enabling longer step-out distances from host platforms.
The US Bureau of Safety and Environmental Enforcement has tightened well control equipment verification requirements following incident investigations, mandating third-party witness of BSEE blowout preventer function tests. This policy is extending procurement lead times for subsea stacks and elevating documentation burdens on equipment suppliers. Gulf of Mexico deepwater drillers are responding by pre-positioning certified BOP stacks and accelerating maintenance scheduling to avoid regulatory downtime.
Exploration procurement is consolidating toward integrated drilling services contracts that bundle rig, logistics, and subsea equipment under single-vendor accountability. National oil companies in Brazil and West Africa are displacing fragmented tendering with multi-well program awards to reduce interface risk. This pattern is most visible in Petrobras's pre-salt drilling campaigns, where five-year rig commitments with integrated service provision are becoming standard.
Deepwater Hydrocarbons Exploration Market Segmentation
Deepwater exploration procurement divides across equipment categories, technology platforms, and operational phases, each carrying distinct certification requirements from regulators like the US BSEE and Brazil's ANP. Understanding these segment boundaries clarifies where capital concentrates and where vendor specialization creates competitive moats.
Product Type:
BSEE blowout preventer testing protocols and ANP local content mandates apply differentially across equipment categories, shaping procurement lead times and supplier qualification burdens.
- Drilling Equipment:Drillships, dynamically positioned semisubmersibles, and subsea blowout preventer stacks rated for 15,000 psi operating pressure. Demand concentrates in Brazil's Santos Basin pre-salt campaigns and the Gulf of Mexico's Lower Tertiary trend, where Petrobras and supermajors commission multi-year rig programs.
- Subsea Systems:Tieback infrastructure including manifolds, flowlines, and riser systems enabling marginal field development without standalone platforms. Norway's Johan Sverdrup and Brazil's Mero fields are deploying all-electric architectures at scale, compressing development timelines for satellite reservoirs.
- Surveying Tools:Seismic acquisition equipment and seabed logging systems for pre-drill prospect evaluation.
- Completion Systems:Subsea wellheads, trees, and intervention interfaces for HPHT reservoir conditions.
Leading the category by volume: Drilling Equipment. Growing fastest: Subsea Systems.
Technology:
Technology segments stratify by capital intensity and operational risk, with autonomous systems commanding premium pricing against conventional tethered alternatives.
- Remote Sensing:Satellite-based ocean surface monitoring and synthetic aperture radar for seep detection. West African frontier basins offshore Mauritania and Senegal are deploying these systems to prioritize seismic acquisition budgets.
- Geophysical Imaging:Wide-azimuth seismic and full-waveform inversion for subsalt and pre-salt carbonate reservoir definition. Brazil's pre-salt province and the Gulf of Mexico's Lower Tertiary depend on proprietary algorithms from service contractors.
- Blowout Preventers:Subsea stacks with shear ram redundancy and acoustic backup control systems.
- ROV Technology:Tethered work-class vehicles and autonomous underwater vehicles for subsea inspection and intervention.
Drilling Equipment absorbs the largest capital share. ROV Technology is expanding most quickly as AUVs displace tethered systems.
End User:
Customer concentration patterns reveal where procurement authority is consolidating versus fragmenting across the value chain.
- Oilfield Operators:Integrated supermajors and national oil companies with in-house exploration capabilities. Petrobras anchors Latin American demand through dominant pre-salt position; ExxonMobil and Shell control Atlantic Margin programs through proprietary project delivery models.
- Exploration Companies:Independents and venture-backed operators targeting frontier basins with farm-in structures.
- Service Providers:Drilling contractors and integrated service companies executing exploration programs under long-term agreements.
- Government Agencies:Regulators and state-backed entities holding equity participation in strategic blocks.
National oil companies and supermajors dominate procurement volume. Service Providers are gaining share fastest through integrated drilling contracts.
Application:
Application segments align with the exploration-to-production value chain, with upstream phases commanding higher margins but lower repeatability.
- Exploratory Drilling:Wildcat and appraisal wells to confirm reservoir presence and delineate recoverable volumes. Brazil's pre-salt appraisal campaigns and West African frontier testing generate sustained demand for high-specification drillships.
- Subsea Development:Tieback engineering and installation for marginal field commercialization. Gulf of Mexico operators deploy repeatable templates to reduce engineering cycles.
- Production Optimization:Reservoir monitoring and artificial lift for mature deepwater assets.
- Well Intervention:Subsea workovers and recompletions to sustain field productivity.
Exploratory Drilling leads by capital deployed per barrel. Subsea Development follows the steepest expansion trajectory as tieback technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater exploration investment clusters in five Atlantic Basin jurisdictions where pre-salt geology, Lower Tertiary plays, and frontier basins concentrate capital deployment. National oil companies and supermajors direct procurement toward Brazil, the United States, Norway, Angola, and Guyana based on resource endowment and regulatory stability.
Brazil
Petrobras dominates pre-salt drilling campaigns in the Santos Basin, commissioning high-specification drillships for multi-year programs. Brazil's National Petroleum Agency imposes local content requirements that structure supply chain participation for block awards. Rio de Janeiro anchors Latin American deepwater activity through dominant fabrication yards and subsea equipment clusters serving pre-salt development.
United States
Supermajors target the Gulf of Mexico's Lower Tertiary trend where HPHT reservoir conditions exceed 15,000 psi and 200°C. The US Bureau of Safety and Environmental Enforcement enforces blowout preventer testing protocols that shape equipment procurement standards. Houston concentrates drilling contractor headquarters and subsea engineering centers supporting Atlantic Margin programs.
Norway
Equinor and partner operators deploy all-electric subsea systems at Johan Sverdrup and adjacent North Sea fields. Norway's Petroleum Safety Authority mandates integrated operations planning that influences contractor selection and risk allocation frameworks. Stavanger hosts the primary cluster of subsea technology vendors and digital twin service providers.
Angola
TotalEnergies and Eni advance deepwater appraisal in underexplored Lower Congo Basin blocks following seismic imaging improvements. The country's national petroleum regulator structures production sharing contracts that determine fiscal terms for frontier drilling. Luanda serves as the logistical hub for West African offshore operations with supply base infrastructure supporting ultra-deepwater campaigns.
Guyana
ExxonMobil's Stabroek Block development anchors South Atlantic frontier exploration with successive FPSO installations. The Guyanese government negotiates production sharing agreements that govern cost recovery and profit oil splits. Georgetown emerges as a coordination center for drilling logistics and crew rotations serving the prolific offshore province.
Deepwater Hydrocarbons Exploration Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated service contracts and digital monitoring capabilities. The vendor base stratifies between supermajors with proprietary project delivery models, national oil companies controlling domestic resource access, and specialized drilling contractors executing exploration programs. Three archetypes dominate: integrated operators internalizing exploration capabilities, rig owners commanding ultra-deepwater fleet capacity, and technology licensors monetizing seismic imaging and subsea processing IP. Competitive positioning hinges on multi-year rig commitments and strategic partnerships with national oil companies.
Among US-based integrated operators, ExxonMobil and Chevron exemplify project delivery consolidation through control of deepwater development timelines from prospect evaluation through production startup. Shell anchors European supermajor positioning through proprietary seismic imaging deployment across Atlantic Margin portfolios. Petrobras represents the national oil company archetype, anchoring Latin American demand through dominant pre-salt province control and local content-structured supply chain participation.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| Chevron |
| TotalEnergies |
| BP |
| Petrobras |
| Equinor |
| ConocoPhillips |
| Eni |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BSEE-compliant Gulf of Mexico stacks and standard-specification Atlantic Margin equipment manifests in both dayrate premiums and supplier qualification burdens. ANP local content mandates in Brazil impose parallel cost structures that reshape fabrication geography and contractor selection.
Pricing Analysis
Volume-vs-margin split separates high-utilization drillship contracts from subsea equipment spot procurement. Project-based rig charters with integrated service bundles dominate Brazil's pre-salt campaigns, while transactional BOP stack rentals prevail in the Gulf of Mexico spot market. Price differentiation hinges on HPHT certification tier and ANP local content compliance, with non-certified contractors facing accelerating cost compression. Least price-sensitive buyers are Petrobras and supermajors locking multi-year programs; most sensitive are independents in West African frontier basins.
Supply Chain Analysis
Single-source vulnerability sits with South Korean shipyards for ultra-deepwater drillship construction and Norwegian subsea technology clusters for all-electric production systems. Raw material dependencies include high-strength steel alloys, subsea umbilical thermoplastics, and blowout preventer elastomer seals. Supply chain risk centers on tariff exposure for fabricated equipment crossing into Brazilian local content zones. Distribution runs through integrated drilling contractors bundling rig, logistics, and subsea stack provision.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ANP local content mandates and BSEE certification friction force capital-constrained independents toward asset sales or farm-in structures.
For Market Incumbents: Hedge against rig oversupply cycles by securing five-year integrated service contracts with Petrobras and West African national oil companies. Anchor fabrication capacity in Rio de Janeiro to satisfy ANP local content thresholds. Defensive priority: pre-position certified BOP stacks to avoid BSEE-mandated downtime exposure. For New Entrants and Emerging Players: The premium-to-economy gap in subsea inspection services offers entry latitude for AUV operators displacing tethered ROV incumbents. Target Norwegian integrated operations mandates accelerating digital twin adoption. Penetrable segment: real-time monitoring systems for remote platform operations. Go-to-market angle: partner with Stavanger-based engineering consultancies for PSA compliance credibility. For Investors and Strategic Acquirers: Re-rating potential sits with specialized AUV technology licensors given autonomous system proliferation displacing conventional ROV fleets. Long-term viability frames around decade-long pre-salt development timelines and Lower Tertiary appraisal cycles. Acquisition target archetype: digital twin service providers with Norwegian PSA track records. Signal to watch: Petrobras rig commitment announcements indicating demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Reduces interface risk for Petrobras pre-salt multi-well programs through single-vendor accountability. |
| All-Electric Subsea Deployment | Enables longer step-out distances at Johan Sverdrup and Mero fields via power-over-cable architecture. |
| AUV Fleet Proliferation | Displaces tethered ROV systems for routine inspection tasks across Atlantic Margin portfolios. |
| Local Content Fabrication Expansion | Satisfies ANP requirements for pre-salt block awards through Rio de Janeiro yard capacity. |
| Digital Twin Platform Development | Supports Norwegian PSA integrated operations mandates with real-time reservoir monitoring capabilities. |
Study Parameters
Document review covered regulatory filings from BSEE and ANP, complemented by interviews with drilling contractors, subsea equipment procurement leads, and offshore project engineers. Secondary sources included EIA production data, IEA offshore investment trackers, and customs records for subsea stack imports. Bottom-up rig demand modeling triangulated against top-down capex disclosures from supermajors and national oil companies.
Cross-reference approach matched historical utilization patterns against panel input from fleet managers and chartering executives. Segmentation dimensions spanned equipment category, technology platform, water depth tier, and regional regulatory cluster. CAGRs derived from rig dayrate trajectories and subsea equipment order backlogs, with HPHT wellhead demand and AUV deployment rates as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; exploratory drilling equipment carries tighter precision than frontier basin surveying tools. Forecasts reflect assumptions about Petrobras capital allocation continuity and BSEE regulatory stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Frac Tree Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Wellhead System Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
Wireline Logging Services Market