
 Floating Liquefied Natural Gas (FLNG) Terminals Market | 2026-2036
Floating Liquefied Natural Gas (FLNG) Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Liquefied Natural Gas (FLNG) Terminals Market Foresight
American Bureau of Shipping (ABS) classification for FLNG hull structures and cryogenic containment systems is unwinding the competitive field, elevating capital requirements for new entrants. Shell plc leverages its integrated project delivery model across multiple FLNG developments. Golar LNG Limited specializes in converting existing LNG carriers into floating liquefaction assets. MODEC, Inc. anchors its position through proprietary hull designs and long-term charter arrangements with resource holders.
Floating Liquefied Natural Gas terminals are marine facilities that produce, store, and transfer LNG at sea, typically employing membrane or Moss-type containment systems rated for temperatures below minus 162 degrees Celsius, enabling extraction of gas reserves without shore-based infrastructure. FLNG Production Units dominate capital deployment due to their integrated liquefaction trains and substantial engineering complexity. Membrane Containment technology leads installation counts for newbuild vessels given its efficient volumetric utilization. Jetty Mooring Systems remain concentrated in brownfield expansions where fixed infrastructure already exists.
The International Maritime Organization enforces emissions and safety standards that govern FLNG vessel construction and operation, while classification societies including ABS and DNV set structural and cryogenic containment benchmarks that determine market access. National regulators in Australia and Malaysia impose additional environmental and maritime security conditions on offshore gas developments. Stakeholders must track evolving carbon intensity benchmarks for floating liquefaction against competing onshore alternatives.
Market Dynamics
The FLNG market is reconfiguring around the International Maritime Organization's carbon intensity benchmarks, which are forcing offshore operators to recalculate project economics against onshore liquefaction alternatives. This regulatory pressure is compressing the competitive set and elevating capital barriers for new facility deployments.
Growth Catalysts
- Stranded Reserve Monetization:Offshore gas discoveries in remote basins lack pipeline economics, making shipboard liquefaction the only viable extraction path for resource holders.
- Membrane Containment Scale-Up:GTT's NO96 and Mark III systems now dominate newbuild FLNG hulls due to superior volumetric efficiency versus Moss-type spheres.
- Australian Regulatory Clarity:The National Offshore Petroleum Safety and Environmental Management Authority provides streamlined approval pathways for floating production facilities.
Market Restraints
- Specialized Hull Fabrication Bottlenecks:Only South Korean and Singaporean yards possess the cryogenic welding certifications required for FLNG construction, concentrating supply risk.
- Liquefaction Train Cost Escalation:APCI and Shell's double-mixed refrigerant process technology commands premium licensing fees that inflate project breakeven thresholds.
- Onshore LNG Competition:QatarEnergy's North Field expansion and US Gulf Coast brownfield projects offer lower per-tonne liquefaction costs than greenfield FLNG developments.
Strategic Opportunities
- African Frontier Basins:Mozambique's Coral South development proves deepwater FLNG viability, opening adjacent Tanzanian and Mauritanian prospects for similar deployment.
- Conversion Arbitrage:Existing LNG carriers reaching regulatory retirement age offer hull candidates for redeployment as floating liquefaction units at reduced capital intensity.
- Carbon Capture Integration:Pre-combustion capture on FLNG power generation systems aligns with the EU Carbon Border Adjustment Mechanism, preserving European offtake access.
Industry Challenges
- Cryogenic Welding Certification Scarcity:ABS and DNV qualified welders for nine-percent nickel steel command premium wages and extended mobilization timelines.
- Regulatory Duality:Operators must satisfy both flag-state maritime rules and host-nation petroleum licensing, creating compliance coordination complexity.
- Subsea Integration Risk:Turret mooring and riser systems for harsh-environment FLNG sites require extended commissioning periods that delay first cargo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Liquefied Natural Gas (FLNG) Terminals Market |
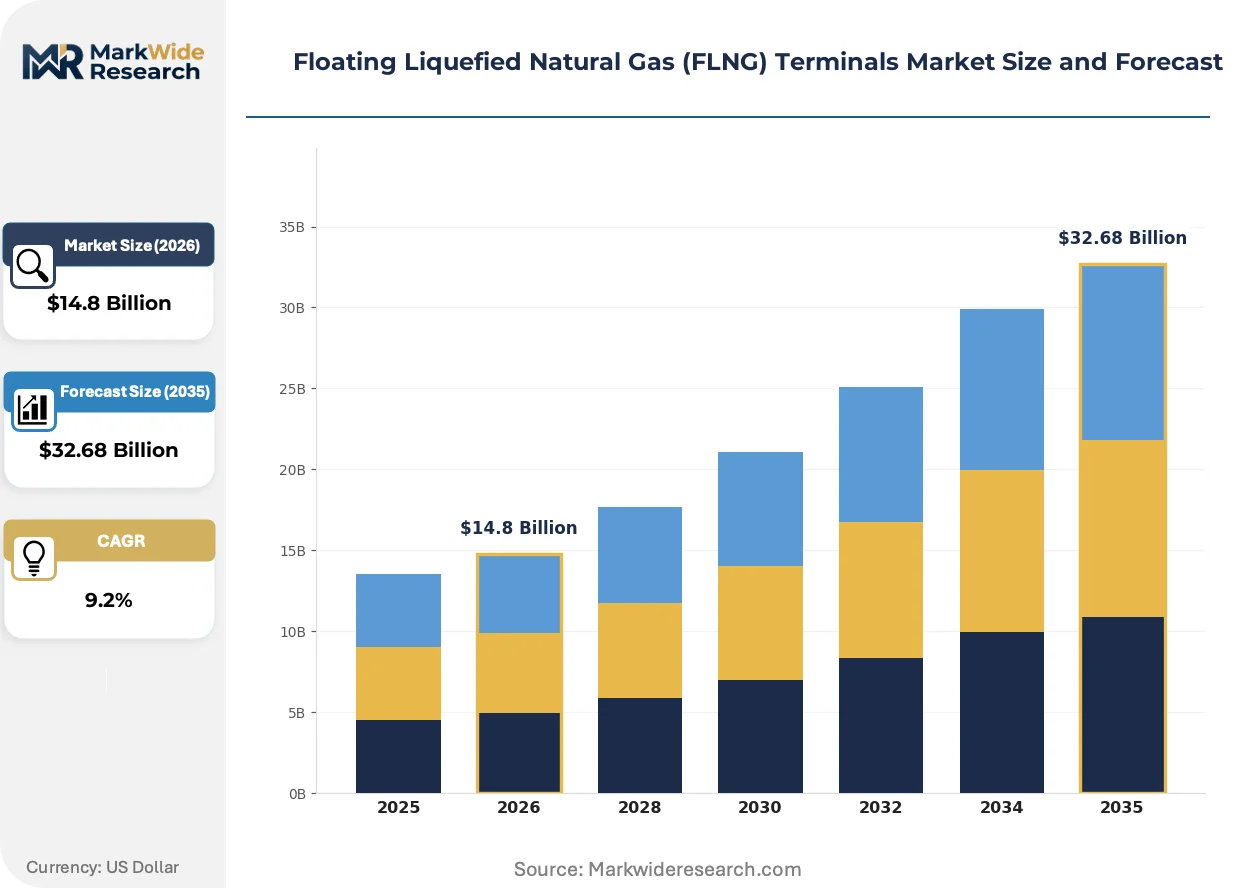
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: FLNG Production Units, FLNG Storage Units, FLNG Offloading Units, FLNG Regasification Units Technology: Membrane Containment, Moss-Type Containment, Gravity-Based Storage, Jetty Mooring Systems Application: Liquefaction, Storage, Transportation, Export, Re-gasification End User: Exploration Companies, Energy Trading Firms, Marine Contractors, Offshore Operators |
| Companies Covered | ExxonMobil Corporation, Woodside Energy Group Ltd, Shell plc, BW Offshore Ltd, MODEC, Inc., PETRONAS, Chevron Corporation, Hyundai Heavy Industries, Golar LNG Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Liquefied Natural Gas (FLNG) Terminals Market Shifts & Advancements
Technological trajectories in floating liquefaction are diverging between megaproject scale and modular replication, with regulatory pressure and buyer risk appetite determining which path dominates deployment decisions.
Membrane containment systems are bifurcating the FLNG fleet into two distinct classes: large-scale newbuilds exceeding three million tonnes annual capacity and mid-scale converted carriers below one million tonnes. European utilities with stringent carbon accounting requirements favor the newbuild pathway for its integrated power efficiency, while Asian traders accepting higher carbon intensity per cargo are absorbing the converted tonnage. This technology split is compressing the middle of the FLNG market, eliminating intermediate-scale projects from development pipelines.
The International Maritime Organization's 2023 revised GHG strategy mandates forty percent carbon intensity reduction by 2030 for international shipping, directly affecting FLNG vessel propulsion and power generation specifications. Dual-fuel diesel-electric systems burning LNG as primary fuel are becoming baseline requirements for newbuild orders. Australian and Malaysian projects are responding earliest, with Prelude and PFLNG Dua already incorporating carbon capture readiness in their original engineering.
Buyer contracting patterns are consolidating around tolling structures that separate gas ownership from liquefaction services, reducing offtake risk for FLNG operators. Trading houses in Singapore and commodity desks at Japanese utilities are driving this shift, preferring fee-based arrangements over traditional SPA-linked project finance. This restructuring is most visible in the Atlantic basin, where BP and Eni's cross-border gas trades now routinely utilize third-party FLNG tolling rather than dedicated equity liquefaction.
Floating Liquefied Natural Gas (FLNG) Terminals Market Segmentation
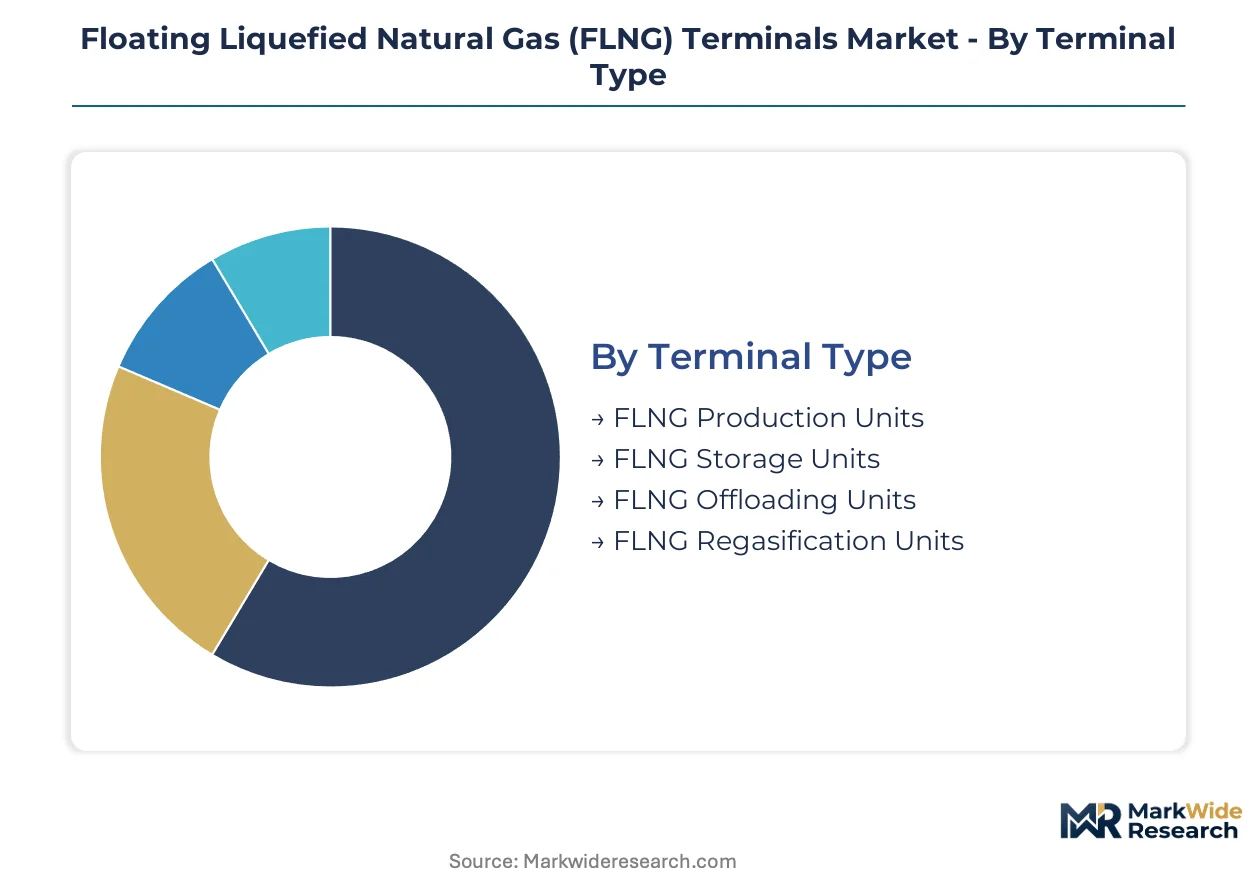
Segmentation in FLNG terminals reveals how regulatory pressure and capital intensity stratify deployment strategies across vessel configurations and operational models. Each category exposes distinct compliance burdens and buyer risk appetites that determine project viability in remote offshore basins.
Terminal Type:
Regulatory differentiation across terminal classifications stems from the International Maritime Organization's emissions benchmarks, which impose stricter carbon intensity calculations on integrated production-storage vessels than on standalone storage or offloading units.
- FLNG Production Units:These integrated facilities combine subsea gas reception, liquefaction trains, and cargo storage in a single hull. Australian offshore operators favor this configuration for Prelude-scale developments where shore-based infrastructure is economically prohibitive.
- FLNG Storage Units:Dedicated storage hulls receive LNG from production platforms or shuttle carriers for buffer inventory management. Malaysian developments deploy these as satellite buffers to manage cargo scheduling flexibility against long-haul offtake commitments.
- FLNG Offloading Units:Transfer stations enable side-by-side or tandem LNG carrier loading without fixed jetty infrastructure. These units concentrate in African frontier basins where seasonal weather windows constrain direct production vessel loading.
- FLNG Regasification Units:Floating import terminals vaporize LNG for pipeline injection or power generation. Energy-deficient island economies in Southeast Asia deploy these to bypass onshore terminal construction timelines.
Established volume favors FLNG Production Units; emerging adoption favors FLNG Regasification Units.
Technology:
Cost tier stratification in containment systems separates premium newbuild membrane installations from converted Moss-type hulls and lower-capital gravity-based alternatives.
- Membrane Containment:GTT-licensed NO96 and Mark III systems maximize volumetric efficiency through prismatic cargo tanks integrated into hull structure. South Korean shipyards dominate fabrication of these systems for Australian megaprojects where cargo volume directly determines project economics.
- Moss-Type Containment:Spherical aluminum tanks suspended in hull cavities offer structural simplicity and reduced insulation complexity. Converted LNG carriers reaching regulatory retirement age frequently retain these tanks for redeployment as mid-scale floating liquefaction units.
- Gravity-Based Storage:Concrete caisson structures anchored to seabed eliminate dynamic positioning requirements. These installations concentrate in benign-environment locations where construction cost savings offset operational inflexibility.
- Jetty Mooring Systems:Fixed or articulated loading arms connect vessels to shoreside infrastructure. Brownfield expansions in established LNG export corridors favor this approach where existing marine terminals reduce incremental capital requirements.
Membrane Containment captures premium-tier deployments; conversion arbitrage favors Moss-Type Containment for mid-scale projects.
Application:
Customer type determines application focus, with integrated oil companies prioritizing liquefaction control while trading houses emphasize storage and transportation flexibility.
- Liquefaction:The core value-adding process converts feed gas to cryogenic liquid through refrigeration cycles. Shell's double-mixed refrigerant process dominates Australian and Malaysian developments where resource holders demand maximum liquids recovery.
- Storage:Buffer inventory management bridges production continuity against cargo scheduling constraints. Floating storage demand concentrates in Singapore trading hubs where arbitrage windows require rapid cargo repositioning.
- Transportation:Shuttle vessel coordination links remote production to main export lanes. Atlantic basin operators deploy dedicated LNG carriers for FLNG-to-FLNG transfers where pipeline infrastructure is absent.
- Export:Cargo loading and customs documentation for international offtake. Nigerian and Mozambican projects structure export operations around tolling arrangements that separate resource ownership from liquefaction services.
- Re-gasification:Vaporization and odorization for pipeline injection or power generation. Bangladesh and Pakistan utilities favor floating import terminals to accelerate energy security timelines without onshore construction delays.
Liquefaction commands capital deployment; re-gasification offers the steepest expansion trajectory in import-dependent economies.
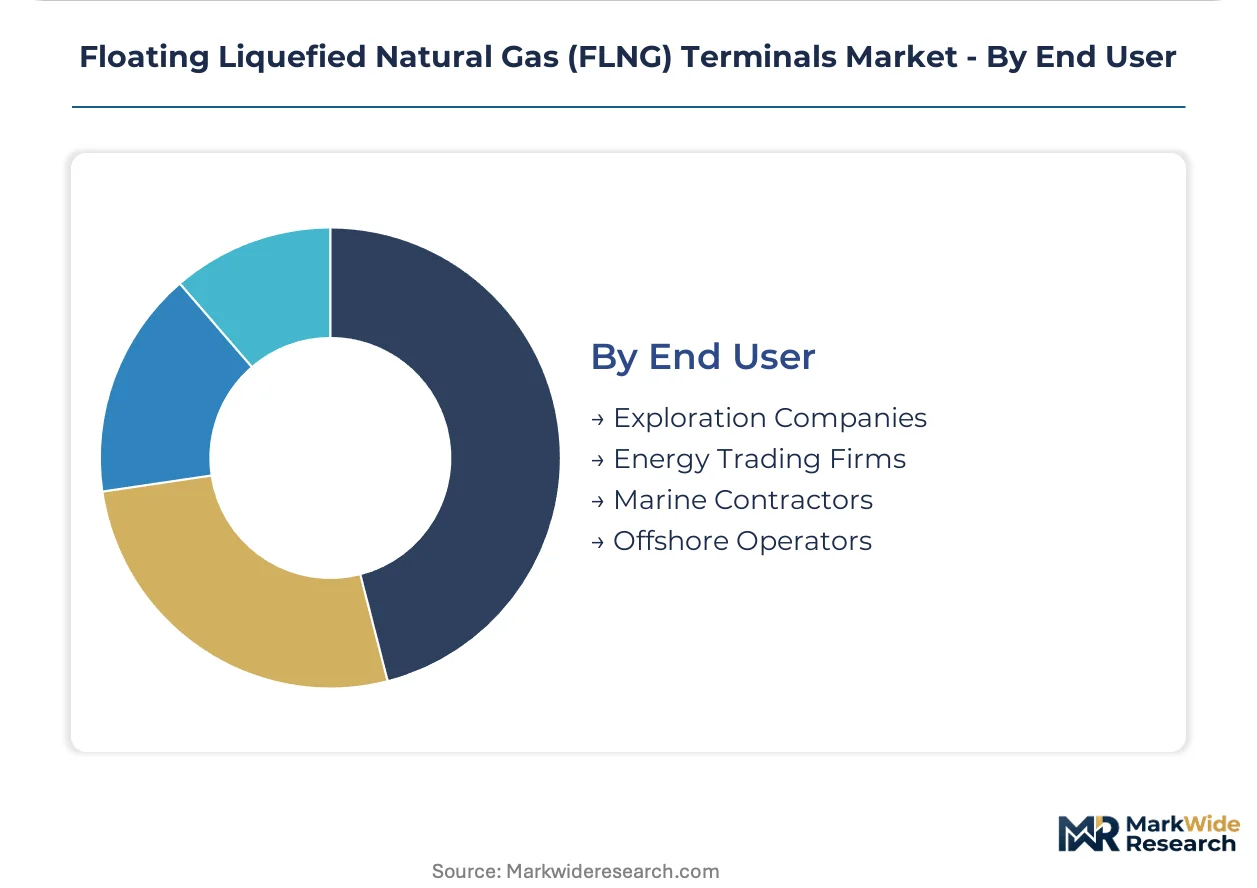
End User:
Supply concentration among qualified marine contractors and specialized offshore operators creates bottlenecks that exploration companies and trading firms must navigate through long-term charter structures.
- Exploration Companies:Resource holders developing stranded gas discoveries without pipeline access. Woodside Energy and Santos anchor Australian FLNG demand through equity participation in integrated production-liquefaction projects.
- Energy Trading Firms:Commodity merchants seeking tolling capacity without upstream resource exposure. Trafigura and Gunvor structure fee-based arrangements with FLNG operators to capture arbitrage without project finance burden.
- Marine Contractors:Specialized vessel operators providing construction, installation, and maintenance services. Technip Energies and Subsea 7 concentrate in turret mooring and riser system integration for harsh-environment FLNG sites.
- Offshore Operators:Integrated service providers managing production, liquefaction, and cargo operations under long-term charter. MODEC and Golar LNG anchor this segment through proprietary hull designs and operational expertise.
Offshore Operators control operational deployment; Energy Trading Firms are expanding most quickly as tolling structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oil companies and energy trading houses concentrate procurement authority in Australia, Malaysia, and Mozambique, with shipyard capacity in South Korea and Singapore determining deployment feasibility for frontier basin developments.
Australia
Woodside Energy and Santos drive FLNG demand through equity participation in offshore gas developments. The National Offshore Petroleum Safety and Environmental Management Authority streamlines approval pathways for floating production facilities. The Browse Basin and Carnarvon Basin anchor project concentration, with Prelude-scale developments validating megaproject economics without shore-based infrastructure.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries hold exclusive cryogenic welding certifications for FLNG hull fabrication. The Korean Register of Shipping enforces structural and cryogenic containment benchmarks that determine yard qualification. The Geoje shipyard cluster concentrates newbuild membrane containment fabrication, with GTT-licensed NO96 systems dominating Australian-bound orders.
Mozambique
Eni and ExxonMobil validate deepwater FLNG viability through the Coral South development in the Rovuma Basin. The national petroleum regulator imposes local content requirements on offshore gas licensing rounds. The Afungi Peninsula serves as logistics hub, with turret mooring systems requiring extended commissioning periods before first cargo.
Malaysia
PETRONAS deploys PFLNG Dua and satellite storage units to manage cargo scheduling flexibility against long-haul offtake commitments. The national maritime regulator coordinates flag-state rules with petroleum licensing conditions. The Bintulu LNG complex anchors regional expertise, with conversion arbitrage opportunities emerging from retiring LNG carrier hulls.
Singapore
Trafigura and Gunvor structure tolling arrangements that separate gas ownership from liquefaction services, reducing offtake risk for FLNG operators. The Maritime and Port Authority enforces emissions standards aligned with International Maritime Organization benchmarks. The Jurong shipyard cluster specializes in LNG carrier conversion, offering mid-scale floating liquefaction units at reduced capital intensity.
Floating Liquefied Natural Gas (FLNG) Terminals Market Competitive Landscape
Player mix skews toward integrated oil companies with captive resource positions, specialized offshore vessel operators, and marine contractors with proprietary hull designs. The competitive set compresses around liquefaction train technology licensing and long-term charter arrangements with resource holders. Three archetypes dominate: integrated majors controlling project equity, conversion specialists redeploying retiring LNG carriers, and fabrication yards with cryogenic certification scarcity. Capacity expansion at qualified South Korean yards and strategic partnerships between operators and classification societies constitute the primary competitive moves.
Within the integrated major tier, Shell plc and ExxonMobil Corporation exemplify project equity control through multiple FLNG developments. Among specialized offshore operators, Golar LNG Limited and MODEC, Inc. occupy positions anchored by proprietary hull designs and long-term charter expertise. These three companies represent the archetype spectrum from resource-holder integration through conversion arbitrage to fabrication-integrated service provision.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Woodside Energy Group Ltd |
| Shell plc |
| BW Offshore Ltd |
| MODEC, Inc. |
| PETRONAS |
| Chevron Corporation |
| Hyundai Heavy Industries |
| Golar LNG Limited |
| Others |
Supply & Pricing Matrix
Three-million-tonne annual liquefaction capacity at South Korean yards anchors price floors through scale economies in membrane containment fabrication, compressing mid-scale competitors while elevating entry barriers for newbuild FLNG projects. This concentration of cryogenic welding certification at Hyundai Heavy Industries and Samsung Heavy Industries directly shapes contract structures and procurement timelines for Australian and African frontier developments.
Pricing Analysis
Cost-plus contracts with Henry Hub or JKM indexation dominate FLNG tolling arrangements, separating gas ownership from liquefaction fees to reduce offtake risk. Price differentiation rests on containment system certification tier—ABS-classified membrane hulls command premiums over converted Moss-type carriers—and on volume scale, with megaprojects securing lower per-tonne rates. Pricing pressure stems from QatarEnergy's North Field expansion offering lower liquefaction costs than greenfield FLNG. National oil companies show least price sensitivity due to captive resource positions; trading houses exhibit highest sensitivity as tolling margin compresses.
Supply Chain Analysis
Inventory lead times for nine-percent nickel steel and GTT-licensed containment systems extend eighteen to twenty-four months, tethering project schedules to South Korean and Singaporean yard slots. Raw material dependencies center on cryogenic-grade aluminum alloys, specialized welding consumables, and APCI or Shell double-mixed refrigerant process technology. Single-source vulnerability concentrates in ABS and DNV qualified welder pools, where certification scarcity commands premium wages. Distribution runs through long-term charter arrangements with resource holders rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FLNG deployment sits in early-cycle expansion as stranded reserve monetization accelerates adoption across African and Southeast Asian frontier basins where pipeline economics fail.
For Market Incumbents: Secure exclusive cryogenic welding certification pipelines through South Korean yard partnerships to defend against fabrication bottlenecks. Anchor charter coverage with Australian and Malaysian resource holders before African projects absorb available capacity. Vertical integration into turret mooring and riser systems mitigates subsea integration risk that delays first cargo. For New Entrants and Emerging Players: Anchor in conversion arbitrage opportunities at Singapore's Jurong shipyard cluster, where retiring LNG carriers offer hull candidates for mid-scale floating liquefaction at reduced capital intensity. Target African frontier basins—Tanzanian and Mauritanian prospects adjacent to Mozambique's Coral South—for first-mover positioning before integrated majors consolidate licensing rounds. Structure tolling arrangements with Trafigura or Gunvor to access offtake without project finance burden. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among offshore operators with long-term charter coverage and proprietary hull designs. Five-to-ten-year viability favors acquisition targets with MODEC-style integrated service models over pure-play fabrication exposure. Watch International Maritime Organization carbon intensity benchmark enforcement as inflection indicator for newbuild versus conversion investment preference.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout at Qualified Yards | Hyundai and Samsung yard expansion preserves fabrication access for Australian megaprojects. |
| Long-term Charter Arrangement | MODEC-style contracts with PETRONAS reduce offtake risk through tolling structures. |
| Technology Licensing Agreement | Shell's double-mixed refrigerant process access determines liquefaction train economics. |
| Conversion Arbitrage Program | Jurong shipyard LNG carrier redeployment cuts capital intensity for mid-scale projects. |
| Carbon Capture Readiness Integration | Pre-combustion capture on FLNG power systems preserves European offtake under EU Carbon Border Adjustment Mechanism. |
Research Methodology
Desk research of International Maritime Organization regulatory filings, classification society standards from ABS and DNV, and national petroleum licensing databases preceded structured interviews with FLNG project developers, shipyard procurement directors, and offshore vessel chartering executives. Secondary validation drew from customs trade data on cryogenic steel imports, EPC contractor project disclosures, and energy trading house tolling agreement structures. Bottom-up vessel deployment counts triangulated against top-down capital expenditure estimates across the analysis window.
Variance decomposition across terminal type, containment technology, and application segments shaped the analytical framework, with CAGRs derived from capacity-weighted deployment schedules and liquefaction train cost escalation trajectories. Modeled dimensions included production versus storage versus regasification configuration, membrane versus Moss-type versus gravity-based containment, and integrated oil company versus trading house versus marine contractor end-user archetype. Forecast inputs incorporated South Korean yard capacity utilization rates and International Maritime Organization carbon intensity benchmark compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained stranded gas reserve discovery rates and stable South Korean-Singaporean yard capacity; material deviation in either would warrant model refresh. Specific risk factors include liquefaction train cost escalation beyond historical trends and regulatory acceleration of carbon intensity benchmarks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Upstream Services Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Gold Mining Market