
 Norway Oil and Gas Upstream Market | 2026-2036
Norway Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oil and Gas Upstream Market Analytics
NORSOK S-001 safety standard certification is rotating the competitive landscape by mandating rigorous technical competence for suppliers seeking offshore platform contracts. Equinor ASA leverages its integrated operator-service provider model across the Norwegian Continental Shelf. Aker BP ASA anchors its portfolio through focused ownership of high-margin producing assets in the North Sea. Vår Energi competes aggressively for exploration licenses in frontier areas of the Barents Sea.
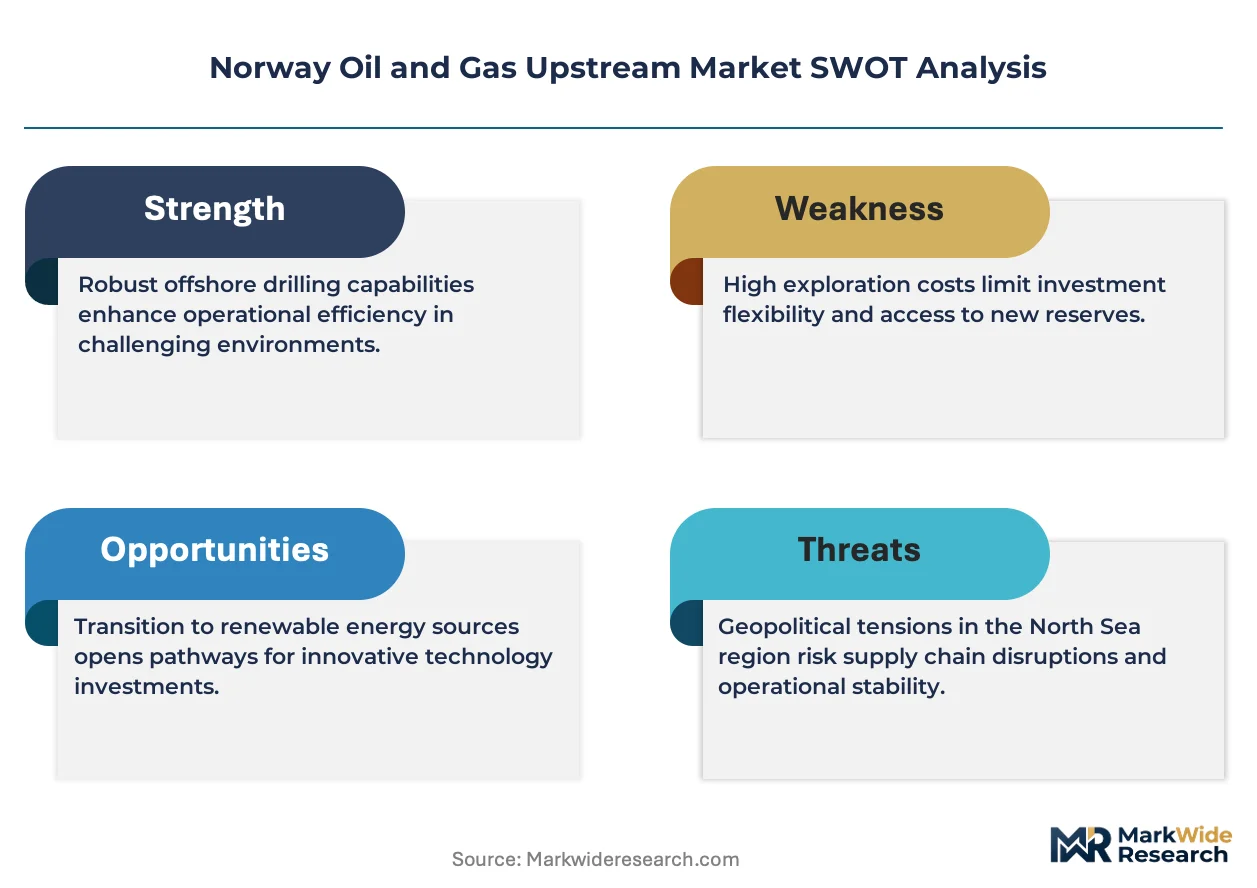
Norway Oil and Gas Upstream encompasses the exploration, drilling, and production of crude oil and natural gas from subsea reservoirs beneath the Norwegian Continental Shelf, typically operating at water depths ranging from 100 to 2,000 meters using steel-jacket fixed platforms or floating production systems. The primary purpose centers on extracting hydrocarbons for pipeline delivery to European markets and liquefaction export terminals. Seismic technology dominates capital allocation as operators prioritize 4D reservoir monitoring to maximize recovery rates from mature fields. Subsea equipment represents the fastest-growing product category as tieback developments replace costly platform installations. Production firms absorb the largest share of service spending as they outsource well intervention and facility maintenance to specialized contractors.
The Norwegian Petroleum Directorate coordinates resource management with the Ministry of Petroleum and Energy, while Petroleum Safety Authority Norway enforces offshore facility integrity standards that directly shape equipment procurement specifications and contractor qualification requirements. NORSOK standards further constrain market access by requiring documented quality systems for all critical suppliers. Stakeholders must track how the EU Green Deal's methane emission benchmarks and Norway's own carbon intensity thresholds for new field approvals will reshape investment priorities and technology selection criteria.
Market Dynamics
4D seismic reservoir monitoring is decomposing traditional field development economics by enabling operators to extract incremental barrels from mature North Sea formations without new platform investments. This technology shift compresses breakeven thresholds and redirects capital toward subsea tieback architectures.
Growth Catalysts
- Johan Sverdrup cluster expansion:The second development phase adds processing capacity that pulls subsea installation demand across the Utsira High formation. Tieback projects multiply as infrastructure availability lowers marginal field development hurdles.
- EU Green Deal methane benchmarks:Emission intensity thresholds for pipeline gas imports accelerate Norwegian operators' deployment of electrified platform power and closed-flare systems. Compliance creates equipment replacement cycles across the Norwegian Continental Shelf.
- Electrification of offshore facilities:Shore-based power feed to the Johan Castberg and Snøhvit fields demonstrates technical viability, triggering specification changes for topside electrical systems and subsea cable infrastructure.
Market Restraints
- Steel and alloy input volatility:Subsea manifold fabrication depends on specialized corrosion-resistant alloys subject to nickel and molybdenum price swings. Cost uncertainty compresses engineering-procurement-construction contractor margins on fixed-price contracts.
- Barents Sea ice window constraints:Seasonal operational access limits drilling and installation activity to July-October periods. Infrastructure utilization rates suffer versus North Sea counterparts with year-round marine access.
- Carbon intensity thresholds for new field approvals:Norway's Ministry of Petroleum and Energy applies emission performance standards that disqualify development concepts below specified efficiency floors. Marginal projects face sanctioning delays or scope reductions.
Strategic Opportunities
- Arctic subsea technology export:Barents Sea operating experience positions Norwegian engineering houses for Russian Far East and Canadian Beaufort Sea projects. Harsh-environment competence transfers to ice-prone frontier markets.
- Decommissioning service bundling:North Sea platform removal obligations concentrate in the 2030-2040 window. Integrated plug-and-abandonment contractors capture multi-field contracts spanning well intervention, topside dismantling, and seabed clearance.
- Power-from-shore infrastructure reuse:Electrification cable corridors to offshore platforms create stranded asset potential for offshore wind interconnection. Joint development models merge oil and gas facility power demand with renewable export capacity.
Industry Challenges
- Subsea robotics technician scarcity:Remote-operated vehicle piloting and autonomous underwater system maintenance require specialized training pipelines that Norwegian technical institutes have not scaled to match fleet expansion.
- NORSOK S-001 certification timelines:Safety-critical equipment qualification demands documented quality systems and third-party verification that extends supplier onboarding to 18-24 months. Procurement cycles compress available delivery windows.
- Legacy platform integration complexity:Digital twin deployment on 1980s-vintage steel jackets requires sensor retrofit and data architecture reconciliation that strains operator IT capabilities and vendor interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oil and Gas Upstream Market |
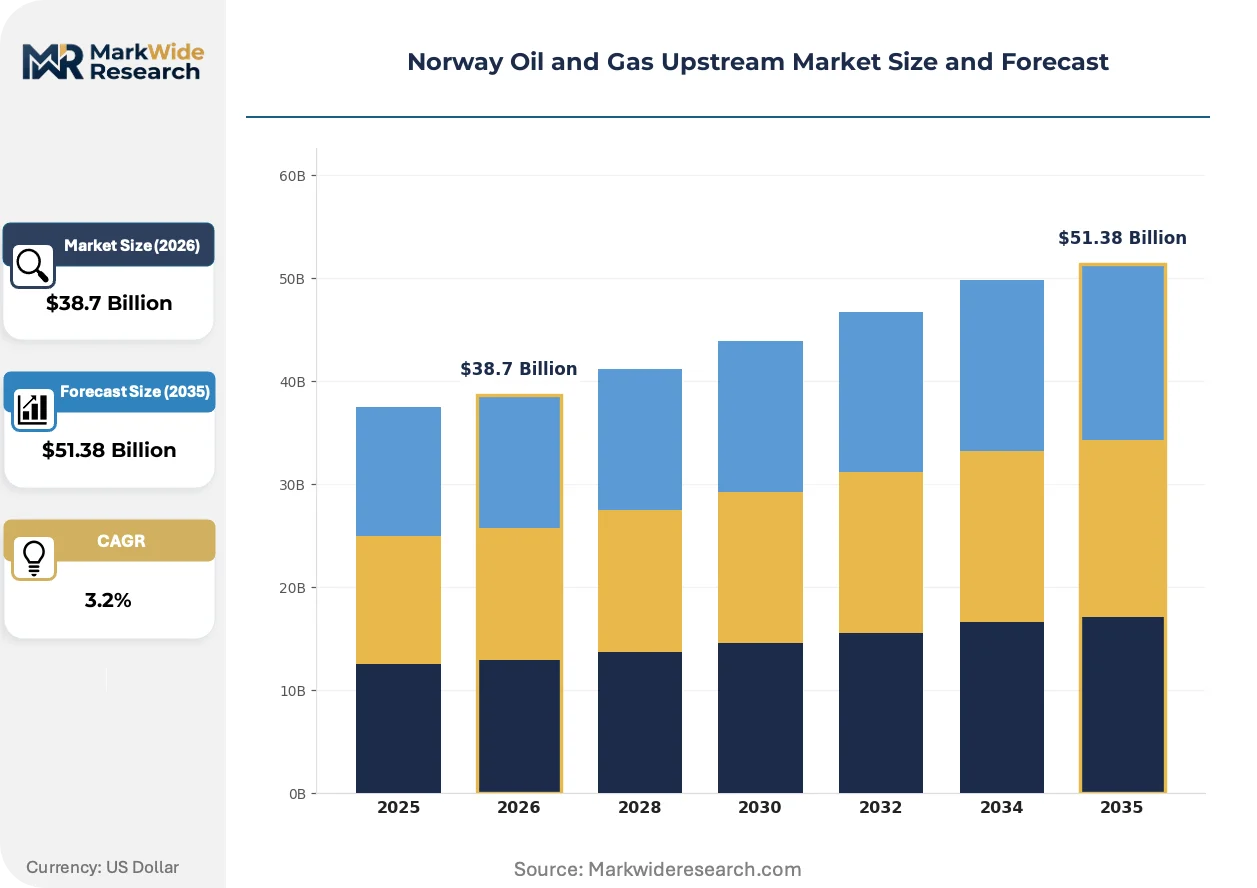
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $51.38 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Seismic, Drilling, Production, Reservoir Management End User: Exploration Companies, Production Firms, Service Providers, EPC Contractors Service Type: Drilling Services, Maintenance, Engineering, Environmental Consulting Product Type: Platform, Rigs, Subsea Equipment, Flare Systems |
| Companies Covered | Equinor ASA, Aker BP ASA, ConocoPhillips Norway, TotalEnergies SE, Shell Norge, Vår Energi, ExxonMobil Norway, Repsol Norge, OMV Norge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oil and Gas Upstream Market Evolving Landscape
Subsea processing technology and reservoir digitalization are converging to transform how Norwegian operators extract value from maturing basins. These developments compress development timelines while raising technical performance thresholds for equipment suppliers.
Subsea gas compression is decomposing the economic rationale for new fixed-platform investments in mid-sized gas fields. Equinor's Åsgard subsea compression facility demonstrated sustained operation at 300-meter depths, validating wet-gas compressor reliability for tieback developments. Operators now specify subsea boosting for fields previously requiring platform-based processing, redirecting capital toward seabed infrastructure and away from topside fabrication yards.
Norway's carbon intensity thresholds for new field approvals are forcing development concept selection toward electrified or low-emission power solutions. The Petroleum Safety Authority Norway coordinates with the Ministry of Petroleum and Energy to enforce emission performance standards that disqualify conventional gas-turbine power generation for new projects. Floating offshore wind-to-platform power and shore-based cable feed now dominate concept screening for pre-sanction fields across the Norwegian Continental Shelf.
European petrochemical refiners are consolidating offtake contracting around emission-certified crude and natural gas liquids. Buyers now require documented methane intensity and flaring performance data that Norwegian operators must provide through standardized certification protocols. This specification shift concentrates demand on Norwegian barrels versus competing supply from jurisdictions without equivalent measurement infrastructure, reinforcing the Norwegian Continental Shelf's position in northwest European refining slates.
Norway Oil and Gas Upstream Market Segmentation
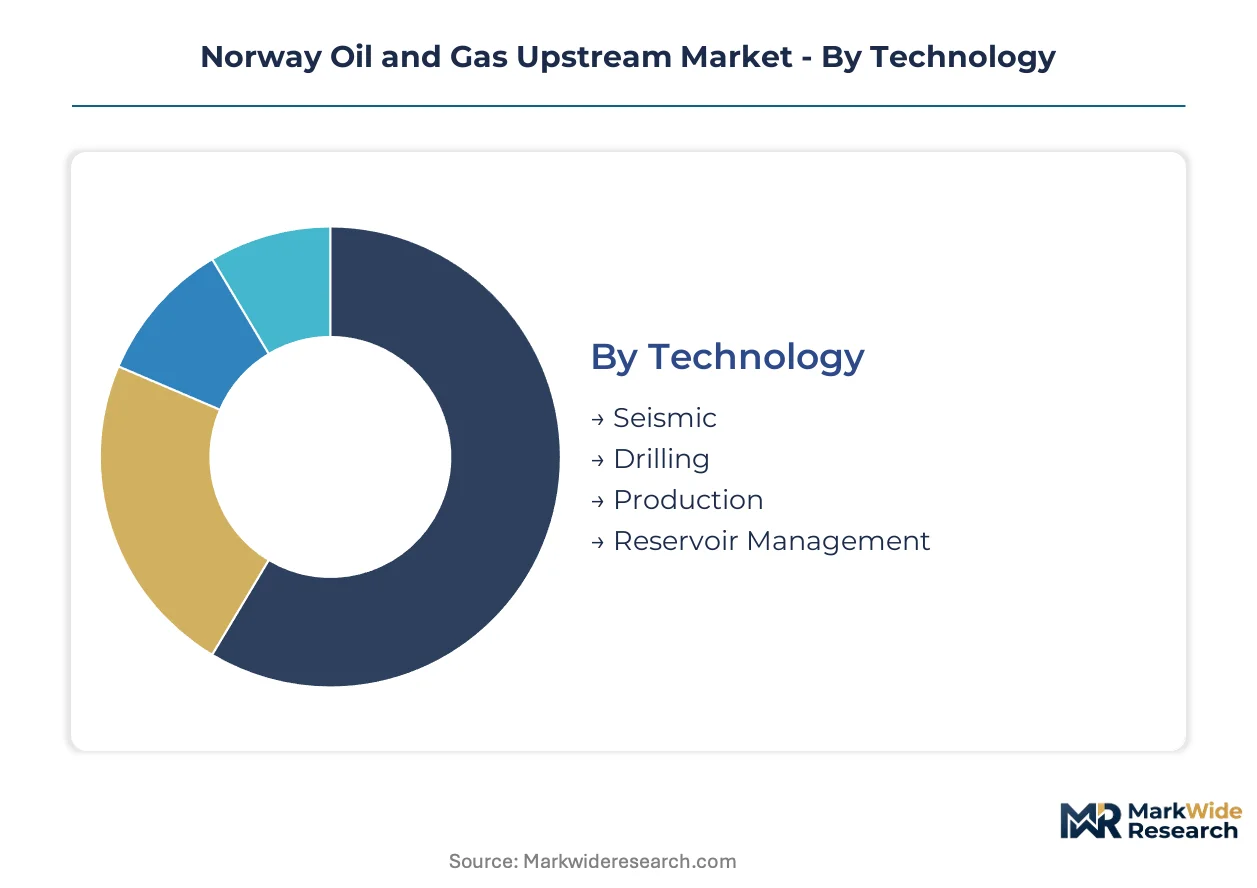
Upstream segmentation in Norway reflects how capital allocation priorities differ across the field lifecycle, from frontier exploration through mature basin redevelopment. Technology and service procurement specifications vary sharply between electrified new developments and legacy platform retrofits, creating distinct supplier qualification pathways.
Technology:
Seismic and reservoir management segments face intensifying substitution pressure from digital twin and AI-driven analytics platforms that compress traditional geoscience workflows.
- Seismic:4D time-lapse acquisition systems monitor fluid movement in producing reservoirs, enabling infill drilling optimization without new platform investments. Demand concentrates around the Johan Sverdrup cluster and mature North Sea fields where incremental recovery justifies repeated survey expenditure.
- Reservoir Management:Integrated production optimization software combines real-time well data with physics-based simulation models. Norwegian operators deploy these systems to maximize recovery factors from aging chalk formations in the Ekofisk area, where even fractional percentage gains translate to substantial reserve additions.
- Drilling:Extended-reach horizontal drilling from existing platforms reduces subsea infrastructure requirements for satellite field tiebacks.
- Production:Subsea boosting and gas compression systems enable standalone development of mid-sized discoveries without fixed-platform capital.
Seismic anchors the volume base while reservoir management gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive field operators from outsourced service contractors with diverging procurement authority and technical specification influence.
- Production Firms:Asset-owning operators control long-term service agreements and facility upgrade budgets across the Norwegian Continental Shelf. Equinor and Aker BP concentrate spending on electrification retrofits and subsea tieback infrastructure, prioritizing vendors with NORSOK certification and documented North Sea execution records.
- Service Providers:Specialized well intervention and subsea installation contractors absorb expanding scope as operators outsource operational activities. These firms procure consumables, rental equipment, and marine support services, creating tiered supply relationships distinct from operator-direct purchasing.
- Exploration Companies:License-focused entities concentrate spending on seismic acquisition and exploration drilling campaigns.
- EPC Contractors:Engineering-procurement-construction firms execute lump-sum field development projects with embedded equipment supply responsibilities.
Production firms anchor the volume base while service providers expand most quickly through outsourcing scope transfer.
Service Type:
Application-driven procurement separates discrete project-based engineering from recurring maintenance contracts with diverging margin structures and vendor loyalty patterns.
- Drilling Services:Rig contracting, directional drilling, and completion services constitute the largest discrete expenditure category. Demand fluctuates with licensing round timing and field sanctioning decisions coordinated by the Norwegian Petroleum Directorate.
- Maintenance:Facility integrity management and preventive maintenance programs generate recurring revenue streams tied to platform operating life. The North Sea decommissioning wave approaching in the 2030s concentrates maintenance spending on life-extension engineering rather than greenfield installation support.
- Engineering:Front-end design and project management services precede final investment decisions on new developments.
- Environmental Consulting:Emissions measurement, carbon accounting, and regulatory compliance support respond to EU Green Deal methane benchmarks and Norway's carbon intensity thresholds.
Drilling services anchor the volume base while environmental consulting climbs the fastest on regulatory compliance expansion.
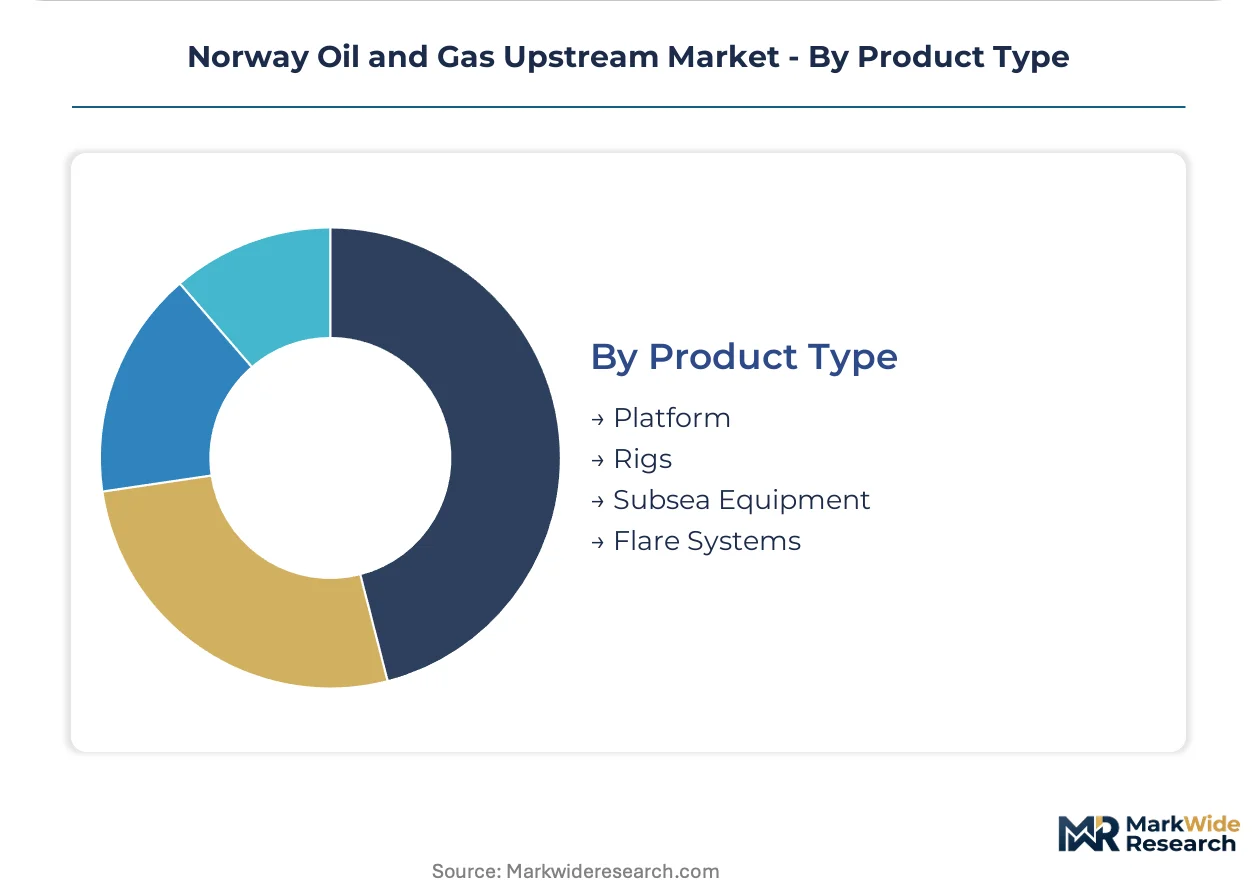
Product Type:
Supply concentration in specialized subsea fabrication yards creates procurement bottlenecks that favor integrated suppliers with captive manufacturing capacity over pure design houses.
- Subsea Equipment:Manifolds, jumpers, and umbilical systems constitute the fastest-expanding product category as tieback architectures displace platform-based processing. Norwegian fabrication yards in Stavanger and Bergen cluster execute these orders, with NORSOK material specifications constraining qualified supplier pools.
- Platform:Steel-jacket fixed structures and floating production systems represent capital-intensive, long-delivery items with concentrated domestic fabrication capability. New platform orders have slowed as electrification retrofits and subsea solutions dominate development concepts.
- Rigs:Jack-up and semi-submersible drilling units operate under Norwegian Maritime Authority jurisdiction with stringent safety equipment requirements.
- Flare Systems:Closed-flare and recovery units respond to emission intensity thresholds enforced by the Petroleum Safety Authority Norway.
Platform anchors the volume base while subsea equipment gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European petrochemical refiners in Germany, the Netherlands, and Belgium anchor offtake demand for Norwegian crude and natural gas liquids. Pipeline infrastructure concentrates delivery through the Draupner and Sleipner hubs into continental processing centers.
United Kingdom
North Sea interconnectors link Norwegian gas fields to UK terminals at St Fergus and Easington. The North Sea Transition Authority coordinates decommissioning standards that align with Norwegian Petroleum Directorate protocols. Aberdeen clusters host engineering contractors executing subsea tieback projects for Utsira High developments.
Germany
Ruhr Valley refiners and BASF Ludwigshafen petrochemical complexes absorb condensate and NGL volumes via Norpipe and Europipe systems. The Federal Network Agency enforces methane emission benchmarks under EU Green Deal implementation. Hamburg and Wilhelmshaven terminals process direct Norwegian crude deliveries for northern European distribution.
Netherlands
Rotterdam refining hub demand concentrates around low-sulfur crude grades suitable for complex conversion units. The Human Environment and Transport Inspectorate enforces maritime emission standards affecting tanker routing from Norwegian load ports. Amsterdam-Rotterdam-Antwerp corridor terminals blend Norwegian barrels into European product specifications.
Belgium
Antwerp refining cluster purchases Norwegian crude for hydrocracker and coker feedstock optimization. The Federal Public Service Health, Food Chain Safety and Environment applies EU methane intensity thresholds to import certification. Port of Antwerp-Bruges infrastructure handles NGL fractionation for petrochemical derivative production.
France
Normandy and Provence refiners source Norwegian grades for FCC and reformer unit compatibility. The Directorate General for Energy and Climate implements carbon border adjustment mechanisms affecting upstream emission accounting. Le Havre and Fos-sur-Mer terminals receive direct shuttle tanker deliveries from North Sea production corridors.
Norway Oil and Gas Upstream Market Competitive Landscape
Player mix skews toward integrated national champions with state-linked ownership structures and specialized North Sea operators with focused asset portfolios. Market structure concentrates around three to four dominant license holders controlling infrastructure-accessible production corridors. Strategic archetypes separate into integrated operators with service-provider capabilities, pure-play production specialists, and frontier exploration-focused entities. Competitive moves center on portfolio high-grading through divestment of non-core assets and electrification retrofit partnerships for emission compliance.
Within the integrated operator tier, Equinor ASA exemplifies the state-linked national champion model combining upstream ownership with infrastructure control. Aker BP ASA and Vår Energi occupy positions as specialized production-focused entities with concentrated North Sea and Barents Sea portfolios respectively. These three structures represent the dominant competitive configurations shaping capital deployment and partnership formation across the Norwegian Continental Shelf.
| Leading Market Players |
|---|
| Equinor ASA |
| Aker BP ASA |
| ConocoPhillips Norway |
| TotalEnergies SE |
| Shell Norge |
| Vår Energi |
| ExxonMobil Norway |
| Repsol Norge |
| OMV Norge |
| Others |
Value Network & Pricing Analysis
NORSOK S-001 safety standard certification gates supplier qualification while simultaneously stratifying price tiers across offshore equipment procurement. Equipment vendors holding documented quality systems command 15-25% premiums over uncertified competitors, yet buyers absorb these premiums to avoid 18-24 month onboarding delays that threaten project schedules. This certification-price coupling concentrates purchasing power among integrated operators with volume leverage to negotiate master service agreements.
Pricing Analysis
Cost-plus contracts indexed to nickel and molybdenum commodity benchmarks dominate subsea manifold fabrication agreements, protecting engineering-procurement-construction contractors from alloy price volatility. Price differentiation separates NORSOK-certified suppliers from standard-tier vendors, with certification grade and documented North Sea execution records driving tier placement. Cost compression in standard-tier equipment is intensifying because European petrochemical refiners are consolidating offtake around emission-certified crudes, pressuring upstream operators to redirect capital toward electrification retrofits. Exploration companies exhibit highest price sensitivity due to discretionary drilling budgets, while production firms with sanctioned field developments demonstrate lowest sensitivity given committed capital timelines.
Supply Chain Analysis
Inventory lead times for subsea umbilical systems extend 14-18 months due to specialized polymer extrusion capacity constraints at Norwegian fabrication yards in Stavanger and Bergen. Geographic supply concentration centers on Norway, with secondary fabrication capability in Scotland and the Netherlands supporting North Sea demand. Raw material dependencies rest on corrosion-resistant alloy feedstocks, high-voltage subsea cables, and specialized hydraulic fluids subject to Petroleum Safety Authority Norway import specifications. Single-source vulnerability characterizes qualified umbilical manufacturers with NORSOK material certification. Distribution runs through operator-direct procurement for capital equipment and tiered contractor purchasing for consumables and rental services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norwegian Continental Shelf is approaching a platform-economics inflection where subsea tieback infrastructure creates shared-access production corridors. Interoperability standards for electrification cable corridors now enable joint oil-and-gas and offshore-wind development models, restructuring how operators monetize seabed infrastructure.
For Market Incumbents: Consolidate control over Utsira High corridor infrastructure through acquisition of non-operated interests in satellite fields, securing tieback optionality as marginal discoveries seek processing capacity. Deepen backward integration into subsea cable manufacturing to capture electrification retrofit margins and defend against specialist contractors expanding into integrated project delivery. For New Entrants and Emerging Players: Anchor in Barents Sea exploration support services where seasonal ice-window constraints limit incumbent capacity utilization and create entry windows for specialized Arctic logistics providers. Target environmental consulting and methane measurement certification as the most penetrable segment, leveraging EU Green Deal compliance deadlines to displace incumbent service relationships through faster certification turnaround. For Investors and Strategic Acquirers: Carve-out targets emerge from international oil majors divesting non-core Norwegian assets to meet portfolio carbon intensity targets. Long-term viability favors production firms with low-breakeven reserves and electrified platform power already deployed. Watch Johan Sverdrup cluster production plateau rates as the inflection signal indicating tieback infrastructure availability for third-party field developments.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Infrastructure Sharing Agreements | Equinor's Utsira High corridor processing capacity lowers marginal field development hurdles for satellite discoveries. |
| Electrification Retrofit Partnerships | Shore-based power feed to Johan Castberg demonstrates technical viability for emission compliance without platform replacement. |
| Arctic Logistics Capability Buildout | Barents Sea ice-window operating experience transfers to Russian Far East and Canadian Beaufort Sea frontier markets. |
| Decommissioning Service Bundling | Integrated plug-and-abandonment contractors capture multi-field contracts spanning well intervention and topside dismantling. |
| Closed-Flare System Deployment | Petroleum Safety Authority Norway emission thresholds trigger equipment replacement cycles across legacy platform fleets. |
Research Methodology
Initial hypotheses were tested against primary input from offshore platform engineers, subsea equipment procurement managers, Petroleum Safety Authority Norway compliance officers, and European refinery crude buyers, then refined through secondary validation against Norwegian Petroleum Directorate field development consents, EU Green Deal methane benchmark documentation, NORSOK standard revision records, and operator annual sustainability disclosures. Bottom-up project sanctioning timelines were triangulated against top-down European petrochemical demand forecasts.
Variance decomposition across technology, end-user, service type, and product type segments structured the analytical framework over the projection horizon. Modeled dimensions included water depth architecture, field maturity stage, emission intensity tier, and infrastructure access proximity. CAGRs were derived from field-by-field production profiles and capital expenditure schedules, with electrification retrofit pacing and Barents Sea licensing round timing as key forecast inputs.
Material uncertainties — carbon intensity threshold revisions, EU methane benchmark enforcement timing, and nickel-molybdenum alloy price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Johan Sverdrup cluster expansion phasing and subsea robotics technician training pipeline scaling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Shale Shakers Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Coiled Tubing Services Market