
 North America Shale Market | 2026-2036
North America Shale Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shale Market Analytics
The EPA's updated methane emissions standards for new and modified oil and gas sources is shifting capital allocation toward leak detection and repair infrastructure across the Permian and Appalachian basins. Exxon Mobil Corporation leverages its integrated midstream footprint to capture and market associated gas rather than vent or flare. Chevron Corporation sustains lower-carbon intensity production through continuous investment in electrified drilling and completions. Pioneer Natural Resources anchors its position in the Midland Basin with dense well spacing and optimized proppant loading.
Shale refers to fine-grained sedimentary rock formations containing organic matter that, through thermal maturation, generates hydrocarbons trapped within low-permeability matrix; hydraulic fracturing combined with horizontal drilling creates conductive pathways to release oil and natural gas at commercial flow rates. Horizontal drilling dominates capital deployment due to its superior reservoir contact per wellbore relative to vertical alternatives. Among end users, oil and gas companies concentrate spending on production optimization services as legacy wells mature and decline curves steepen across older Bakken and Eagle Ford developments.
The EPA enforces Clean Air Act standards for volatile organic compounds and methane from upstream operations, while state regulators in Texas and New Mexico impose site-specific flaring limits that shape drilling permit economics. OSHA maintains worker exposure thresholds for silica dust generated during hydraulic fracturing sand handling, affecting proppant logistics and onsite handling protocols. Stakeholders must monitor how evolving federal methane fees and state groundwater protection rules alter the cost structure of multi-well pad development in water-stressed basins.
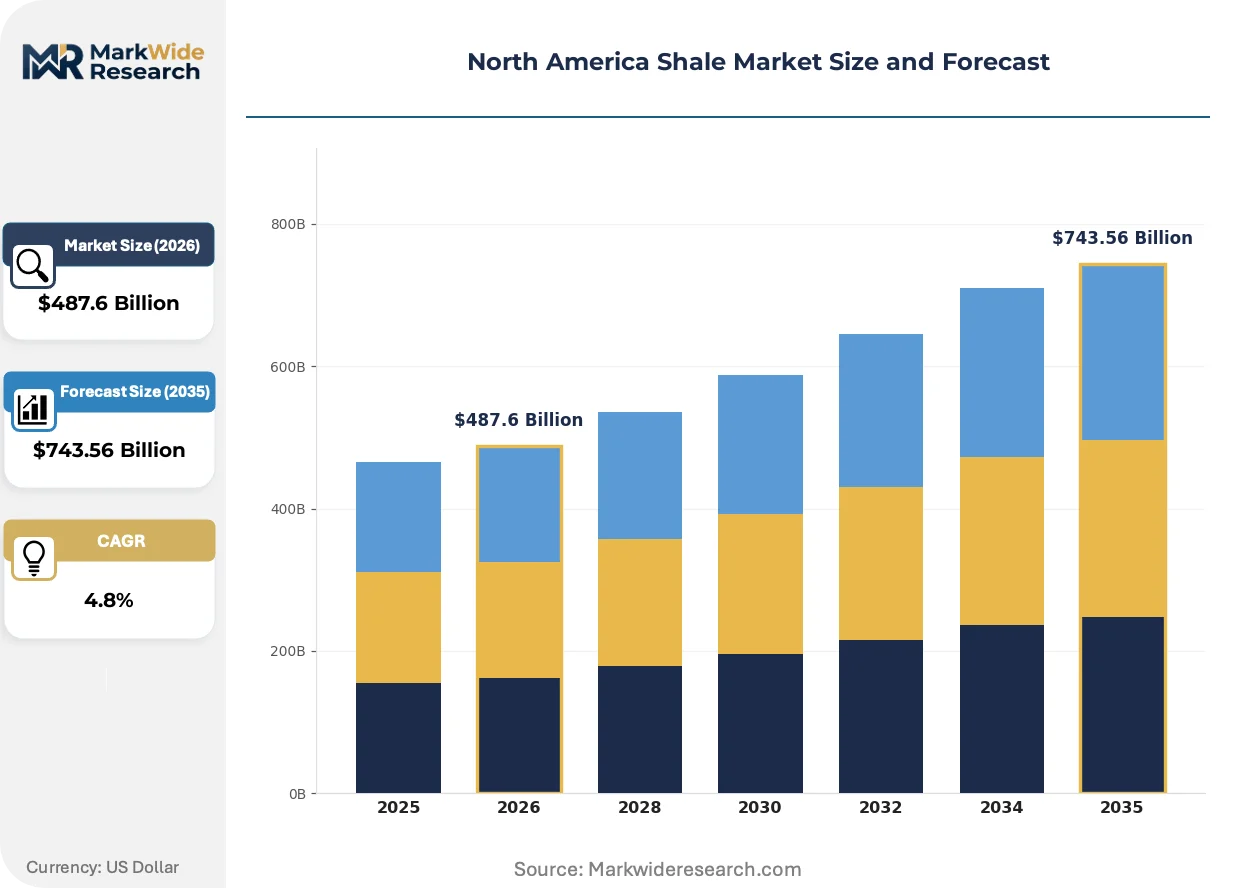
Market Dynamics
EPA methane emissions standards and state-level flaring restrictions are compressing operational margins across marginal Permian and Appalachian producers while capital concentrates with large-scale operators possessing integrated midstream infrastructure.
Growth Catalysts
- Petrochemical demand expansion:Appalachian and Permian basins supply feedstock to Gulf Coast ethylene crackers. Chemical manufacturers anchor long-term offtake agreements.
- Pipeline takeaway capacity:Texas operators access export terminals through Permian Highway and Whistler pipelines. Infrastructure completion unlocks stranded production.
- Leak detection technology:Continuous monitoring systems satisfy EPA reporting requirements. Optical gas imaging reduces compliance costs versus manual inspection protocols.
Market Restraints
- Proppant cost volatility:Northern White sand from Wisconsin and Minnesota faces rail logistics constraints. Silica dust handling adds OSHA compliance overhead.
- Water sourcing limitations:Permian operators compete with agricultural and municipal users in drought-stressed West Texas aquifers. Recycling infrastructure requires substantial capex deployment.
- Basin maturity divergence:Bakken and Eagle Ford legacy wells exhibit steepening decline curves. Refracturing economics struggle against greenfield Permian returns.
Strategic Opportunities
- Carbon capture integration:Class VI well injection permits enable CO2 sequestration alongside hydrocarbon production. 45Q tax credits improve project economics.
- Power purchase agreements:Electrified drilling rigs connect to Texas ERCOT grid. Renewable energy contracts reduce Scope 2 emissions intensity.
- Associated gas monetization:Small-scale LNG and CNG facilities serve off-grid industrial demand. Mexico border manufacturing clusters present proximate markets.
Industry Challenges
- Specialized fracturing crew availability:High-pressure pumping equipment demands experienced technicians. Labor competition from renewable construction projects tightens hiring pools.
- Multi-well pad complexity:Simultaneous operations on dense spacing require precise timing coordination. Parent-child well interference degrades child well productivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shale Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Drilling, Hydraulic Fracturing, Recompletion, Enhanced Oil Recovery End User: Utilities, Independent Producers, Oil and Gas Companies, EPC Contractors Service Type: Drilling Services, Fracturing Services, Well Completion, Production Optimization Application: Oil Extraction, Natural Gas Production, Biogas Capture, Resource Recovery |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, ConocoPhillips, Occidental Petroleum Corporation, Shell PLC, EQT Corporation, Antero Resources Corporation, Pioneer Natural Resources, BP PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shale Market Evolving Landscape
Digital automation and emissions monitoring technologies are reshaping capital deployment patterns across North American shale basins. Operators prioritize measurable carbon intensity reductions alongside production optimization.
Simul-frac and zipper-frac techniques are consolidating well completion efficiency across Permian multi-well pads. Large independents deploy dual-fleet configurations to fracture two wells simultaneously. The technology is consolidating drilling schedules from 45 days to 28 days per pad, compressing capital cycle times and improving leasehold economics.
EPA's updated methane performance standards for new and modified sources impose quarterly leak surveys and repair timelines. Operators must install vapor recovery units on storage tanks and pneumatic controllers. Appalachian Basin dry gas producers face disproportionate compliance burdens relative to Permian liquids-rich streams.
Buyers now unbundle drilling contracts from integrated service packages. Operating companies separately procure directional drilling, mud logging, and completion services through digital procurement platforms. This fragmentation is most visible in Texas, where vendor density enables competitive bidding and real-time performance benchmarking.
North America Shale Market Segmentation
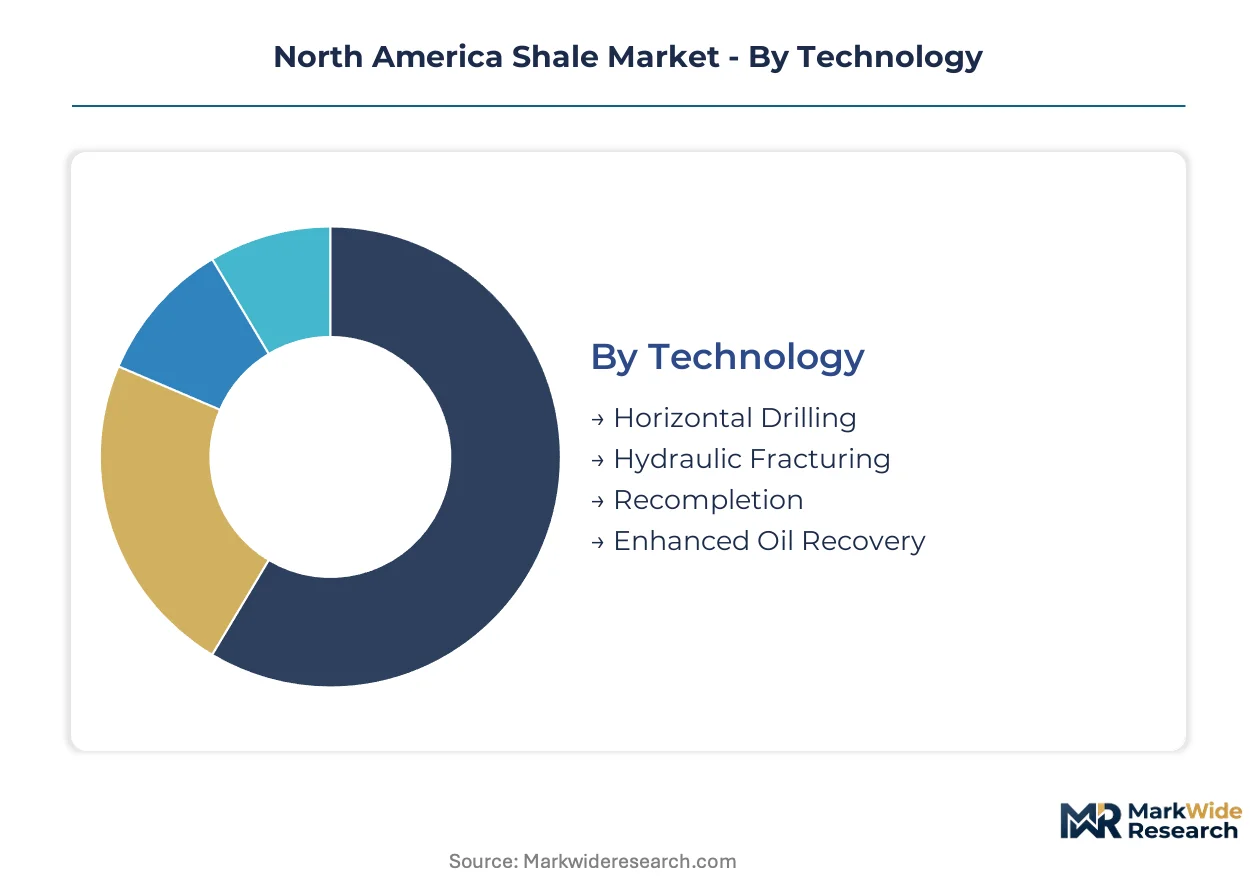
Technology choice determines capital intensity and recovery factors across North American shale plays. Service procurement patterns and end-user economics vary sharply by basin maturity and hydrocarbon mix.
Technology:
Horizontal drilling dominates standalone deployment while recompletion and enhanced oil recovery function as embedded add-ons to existing wellbores.
- Horizontal Drilling:Laterals extending 10,000+ feet through low-permeability matrix maximize reservoir contact per wellbore. Texas Permian operators deploy this as the primary extraction architecture, with rig mobility and pad drilling compressing cycle times.
- Hydraulic Fracturing:High-pressure fluid injection creates conductive fracture networks in tight formations. Proppant loading intensity varies by formation—Permian Wolfcamp demands higher sand concentrations than Appalachian Marcellus dry gas targets.
- Recompletion:Refracturing of legacy horizontal wells extends productive life in maturing Bakken and Eagle Ford assets.
- Enhanced Oil Recovery:CO2 flooding and huff-and-puff gas injection target residual oil saturation in depleted zones.
Horizontal drilling leads volumes today; recompletion is gaining share fastest as legacy well inventories expand.
End User:
Customer scale determines service bundling preferences and contracting tenure, with integrated majors favoring long-term partnerships and independents pursuing spot market flexibility.
- Oil and Gas Companies:Integrated operators with captive midstream assets internalize production optimization and control methane capture infrastructure. Their capital allocation spans full well lifecycle from drilling through abandonment.
- Independent Producers:Pure-play upstream operators concentrate in single-basin positions, outsourcing fracturing and completion services to pressure pumping specialists. Their procurement emphasizes per-well cost control over integrated solutions.
- Utilities:Power generators and gas distribution utilities source long-term supply contracts for baseload fuel.
- EPC Contractors:Engineering-procurement-construction firms deliver turnkey field development for external capital providers.
Oil and gas companies lead volumes today; independent producers are expanding fastest through private equity-backed drilling programs.
Service Type:
Margin concentration follows technical specialization, with fracturing services commanding premium pricing versus commoditized drilling rig dayrates.
- Fracturing Services:Pressure pumping fleets execute multi-stage completions with engineered fluid and proppant designs. Simul-frac configurations now fracture two wells simultaneously, compressing pad timelines and improving crew utilization in Permian multi-well developments.
- Production Optimization:Artificial lift installation, wellbore diagnostics, and decline curve management extend economic life of producing assets. Demand concentrates in maturing Bakken and Eagle Ford fields where artificial lift conversion from rod pumps to ESPs improves recovery.
- Drilling Services:Directional drilling and mud logging support wellbore construction.
- Well Completion:Casing, cementing, and perforating bridge drilling and production phases.
Fracturing services lead volumes today; production optimization is climbing fastest as legacy well populations mature.
Application:
Hydrocarbon type shapes regulatory exposure and pricing dynamics, with associated gas handling creating compliance burdens distinct from dry gas or oil-focused developments.
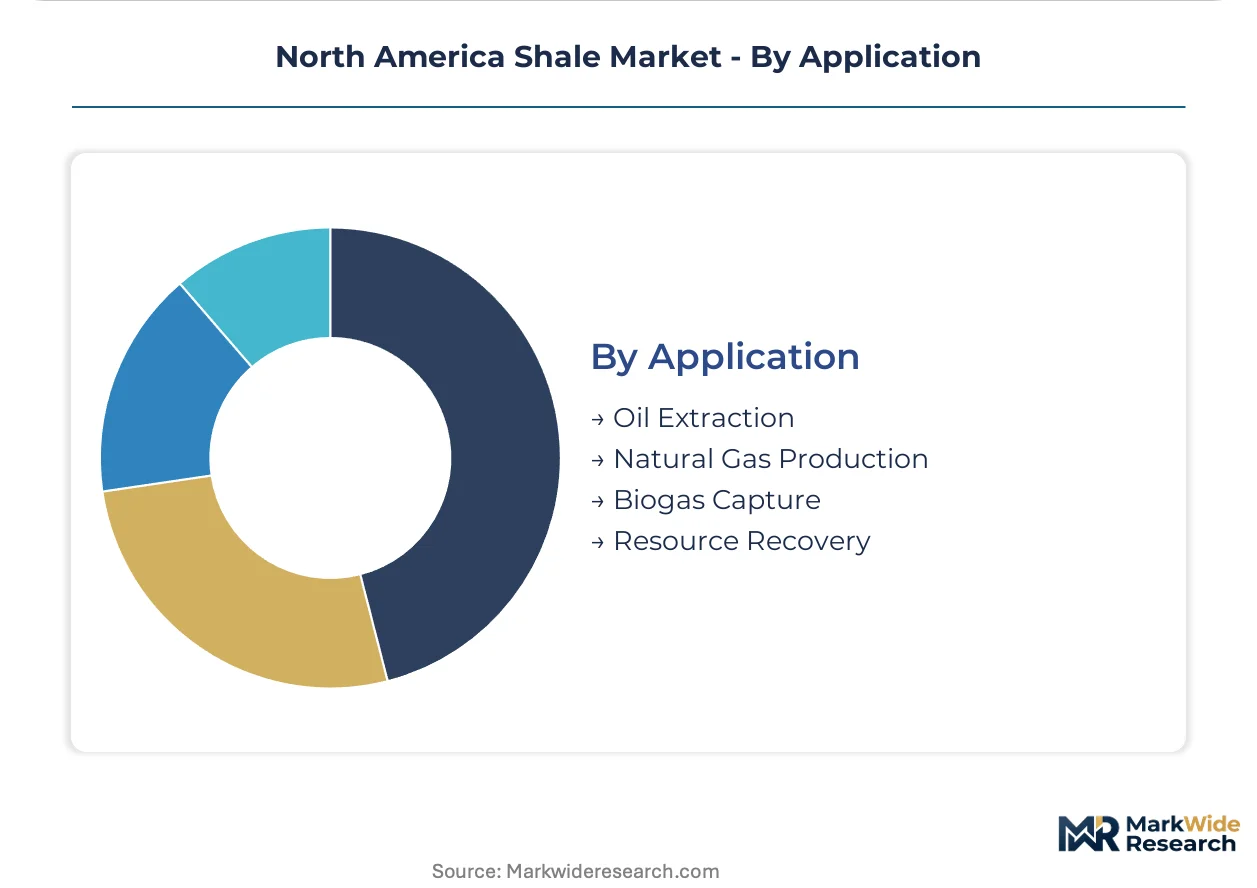
- Oil Extraction:Light tight oil production from Permian Delaware and Midland basins generates associated gas requiring vapor recovery and pipeline offtake. West Texas operators face EPA methane performance standards and Texas Railroad Commission flaring limits that shape well economics.
- Natural Gas Production:Dry gas from Appalachian Marcellus and Utica formations supplies Gulf Coast LNG export terminals and Northeast heating demand. Pipeline takeaway constraints have eased with Mountain Valley Pipeline completion, improving netbacks for Pennsylvania and West Virginia producers.
- Biogas Capture:Landfill and agricultural methane recovery qualifies for renewable fuel credits.
- Resource Recovery:Helium, lithium, and rare earth extraction from produced brines represents emerging value streams.
Oil extraction leads volumes today; natural gas production is expanding most quickly with LNG export capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American shale industry traces its commercial origins to the Barnett Shale near Dallas-Fort Worth, where Mitchell Energy pioneered hydraulic fracturing economics in the late 1990s. This breakthrough established the Permian Basin and Appalachian formations as the continent's dominant production centers.
United States
Permian Basin operators in West Texas and southeastern New Mexico leverage pipeline interconnects to Gulf Coast export terminals. EPA methane performance standards and Texas Railroad Commission flaring limits shape well economics. The Midland-Odessa metropolitan area anchors pressure pumping fleet deployment and sand transloading infrastructure.
Canada
Montney and Duvernay formation operators in Alberta and British Columbia supply liquefied natural gas feedstock to Pacific export projects. The country's national energy regulator oversees pipeline approvals while provincial authorities manage water allocation for fracturing operations. Calgary headquarters major independent producers active in both Canadian and U.S. basins.
Mexico
Burgos Basin dry gas production in Nuevo León and Tamaulipas serves industrial demand in Monterrey's manufacturing corridor. State hydrocarbon regulator CNH administers exploration contracts while PEMEX maintains legacy field positions. Pipeline capacity constraints to Texas border interconnects limit netback realizations for northern producers.
North America Shale Market Competitive Landscape
Capital-heavy integrated majors compete with asset-light independent producers across North American shale basins. The market structure concentrates upstream spending among ten to fifteen operators controlling Permian and Appalachian acreage positions. Three archetypes dominate: integrated majors with captive midstream assets, large independents with basin-specialized technical teams, and private equity-backed drillers pursuing short-cycle returns. Competitive dynamics center on acreage consolidation through asset acquisitions and operational differentiation via drilling efficiency metrics.
Among U.S.-based integrated operators, Exxon Mobil Corporation and Chevron Corporation exemplify the capital-heavy archetype with internalized completion services and pipeline ownership. Pioneer Natural Resources, referenced in the raw data, occupies a position within the large independent tier focused on Midland Basin density optimization. These company names serve as anchors for understanding how scale advantages concentrate with operators possessing integrated gas processing and export terminal access.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| Occidental Petroleum Corporation |
| Shell PLC |
| EQT Corporation |
| Antero Resources Corporation |
| Pioneer Natural Resources |
| BP PLC |
| Others |
Value Network & Pricing Analysis
Integrated majors with captive midstream infrastructure command contract-based long-term offtake pricing that insulates against spot volatility, while independent producers without pipeline access absorb basis differentials that erode wellhead realizations. This bifurcation concentrates pricing power among operators with Texas Gulf Coast export terminal access, forcing asset-light competitors into disadvantageous spot market exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated majors with firm transportation contracts from large independents with pipeline commitments and marginal producers exposed to spot Henry Hub differentials. Price differentiation hinges on methane intensity certification and flaring compliance history, with EPA audit scores increasingly influencing buyer willingness to pay. Cost compression in the economy tier is intensifying because Appalachian dry gas producers face disproportionate methane compliance burdens without liquids revenue offsets. Marginal Permian operators exhibit highest price sensitivity, while majors with integrated gas processing demonstrate lowest sensitivity due to capture economics.
Supply Chain Analysis
Regional distribution centers in Midland-Odessa and Pecos anchor sand transloading infrastructure, with hub-and-spoke patterns radiating toward multi-well pad clusters across the Delaware and Midland basins. Proppant supply draws from Wisconsin Northern White sand mines, Permian regional sand mines, and Mexican ceramic proppant imports. Single-source vulnerability concentrates in high-pressure pumping equipment, where fracturing fleet availability constrains completion schedules. Distribution runs through pipeline gathering systems to Gulf Coast processing and LNG export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American shale has entered a late-cycle quality phase where capital allocation favors operators with verified low-methane production profiles. Chemical manufacturers and LNG offtakers now require emissions disclosure as a contract precondition, elevating certified low-carbon gas to premium pricing tiers.
For Market Incumbents: To counter margin compression from EPA methane fees and state flaring restrictions, Exxon Mobil and Chevron should deepen backward integration into carbon capture infrastructure and expand firm pipeline capacity holdings. Capturing Class VI well permits and 45Q tax credit eligibility creates regulatory arbitrage against independents lacking sequestration geology.
For New Entrants and Emerging Players: Capture stranded gas monetization opportunities in Mexico border manufacturing corridors and small-scale LNG serving off-grid industrial demand. The most penetrable segment lies in associated gas processing for Permian operators lacking midstream access, with power purchase agreements offering the clearest go-to-market path through ERCOT grid interconnection.
For Investors and Strategic Acquirers: Private equity-backed upstream consolidators are the most active acquirer in this space, targeting Midland Basin acreage positions with dense well spacing potential and remaining drilling inventory. Acquisition candidates with contiguous leasehold and water recycling infrastructure offer superior capital efficiency over greenfield development. Watch EPA enforcement variance across regional offices as the signal indicating regulatory cost trajectory divergence between Permian and Appalachian assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Class VI well permits enable CO2 sequestration alongside Permian production, capturing 45Q tax credits. |
| Power Purchase Agreement | ERCOT grid interconnection for electrified drilling reduces Scope 2 emissions intensity for Texas operators. |
| Pipeline Takeaway Expansion | Permian Highway and Whistler pipeline access unlocks stranded production for Gulf Coast LNG export. |
| Leak Detection Technology Deployment | Continuous monitoring systems satisfy EPA quarterly survey requirements at lower cost than manual protocols. |
| Simul-Frac Configuration | Dual-fleet completions compress pad timelines from 45 days to 28 days, improving capital cycle velocity. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with pressure pumping fleet managers, EPC contractors, utility fuel procurement officers, and chemical plant supply chain directors with secondary validation through EIA production data, FERC pipeline filings, EPA emissions inventories, and state regulatory flaring reports. Triangulation across these sources ensures volume estimates align with infrastructure capacity constraints and regulatory enforcement patterns.
Historical trendline analysis of basin-level production, completion counts, and proppant loadings informs the projection framework across the analysis window, with segmentation by technology type, hydrocarbon mix, operator scale, and regional regulatory cluster. CAGRs derive from elasticity modeling against petrochemical demand curves and LNG export capacity additions, incorporating EPA methane fee schedules and state water allocation policies as scenario variables.
Regulatory enforcement variance, proppant logistics disruptions, and basin maturity divergence are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Indonesia Oil and Gas Midstream Market