
 Global LNG Liquefaction Equipment Market | 2026-2036
Global LNG Liquefaction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global LNG Liquefaction Equipment Market Foresight
Qatari megatrain expansions is broadening the addressable base for large-frame refrigeration compressors and cryogenic heat exchangers. Linde Group anchors European technology supply through its mixed refrigerant cycle expertise, while Air Products and Chemicals dominates cryogenic process design for land-based megaprojects. Chart Energy and Chemicals specializes in brazed aluminum heat exchangers, a component category where fabrication lead times now stretch eighteen months or longer.
LNG liquefaction equipment encompasses the cryogenic machinery, compression trains, and thermal exchange systems that cool natural gas to minus 162 degrees Celsius for volumetric reduction and maritime transport. Mixed refrigerant cycles achieve thermodynamic efficiency through staged propane, ethylene, and methane refrigeration loops, while cascade systems remain prevalent in legacy Atlantic Basin facilities. Heat exchangers capture the largest equipment capital share in greenfield trains, whereas floating LNG facilities drive demand for compact, skid-mounted compressor packages that minimize topside weight.
FERC in the United States governs siting and environmental review for export terminals, while EU methane emissions regulations under the EU Green Deal tighten leakage standards for equipment seals and flanged connections. Japan's METI influences technology selection through its financing support for pre-FID projects that adopt advanced nitrogen rejection or dual mixed refrigerant configurations. Stakeholders must weigh refrigerant cycle selection against evolving carbon border adjustments and offtake contract duration before committing to twenty-five-year asset lives.
Market Dynamics
Mixed refrigerant cycle optimization is compressing energy intensity benchmarks across new liquefaction trains, forcing equipment suppliers to recalibrate compressor and heat exchanger specifications for Qatar's megatrain expansions and US Gulf Coast brownfield additions.
Growth Catalysts
- Qatari North Field expansion:The state-led megatrain program is pulling large-frame refrigeration compressors and cryogenic heat exchangers into long-lead procurement cycles, extending fabrication backlogs to twenty-four months.
- FERC export authorization:Accelerated permitting timelines for US Gulf Coast terminals are unlocking final investment decisions on liquefaction capacity, directly stimulating modular compression package orders.
- Mixed refrigerant advances:Staged propane-ethylene-methane loops are achieving thermodynamic efficiencies that cascade systems cannot match, displacing legacy Atlantic Basin infrastructure specifications.
Market Restraints
- Aluminum alloy supply concentration:Brazed heat exchanger cores depend on specialized aluminum-lithium alloys concentrated in Chinese and Russian smelter networks, exposing fabrication schedules to geopolitical supply shocks.
- Specialized welding labor scarcity:Cryogenic vessel certification requires ASME Section VIII-qualified welders whose training cycles extend thirty-six months, capping global fabrication throughput regardless of capital availability.
- EU methane leakage standards:The EU Green Deal's tightening seal and flange emission thresholds are disqualifying legacy equipment designs from European-linked offtake contracts, fragmenting addressable demand pools.
Strategic Opportunities
- West African stranded gas:Mauritania-Senegal cross-border fields are driving feasibility studies for mid-scale floating LNG trains requiring compact, skid-mounted compression packages that minimize topside weight.
- Carbon border adjustment alignment:The EU CBAM is creating procurement preference for liquefaction trains with certified low-carbon intensity, rewarding suppliers with integrated carbon capture-ready process designs.
- Dual mixed refrigerant configurations:Japanese METI financing support for pre-FID projects adopting advanced nitrogen rejection loops is opening specification windows for specialized cryogenic separation equipment.
Industry Challenges
- Cryogenic instrumentation calibration:Minus 162 degrees Celsius operating conditions demand sensor accuracy within 0.1 Kelvin, yet qualified calibration facilities concentrate in Germany, Japan, and the United States, creating logistics bottlenecks for distributed project sites.
- Modular integration complexity:Floating LNG facilities require compressor packages that fit within shipyard lifting constraints while maintaining onshore-equivalent efficiency, forcing redesign cycles that compress engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LNG Liquefaction Equipment Market |
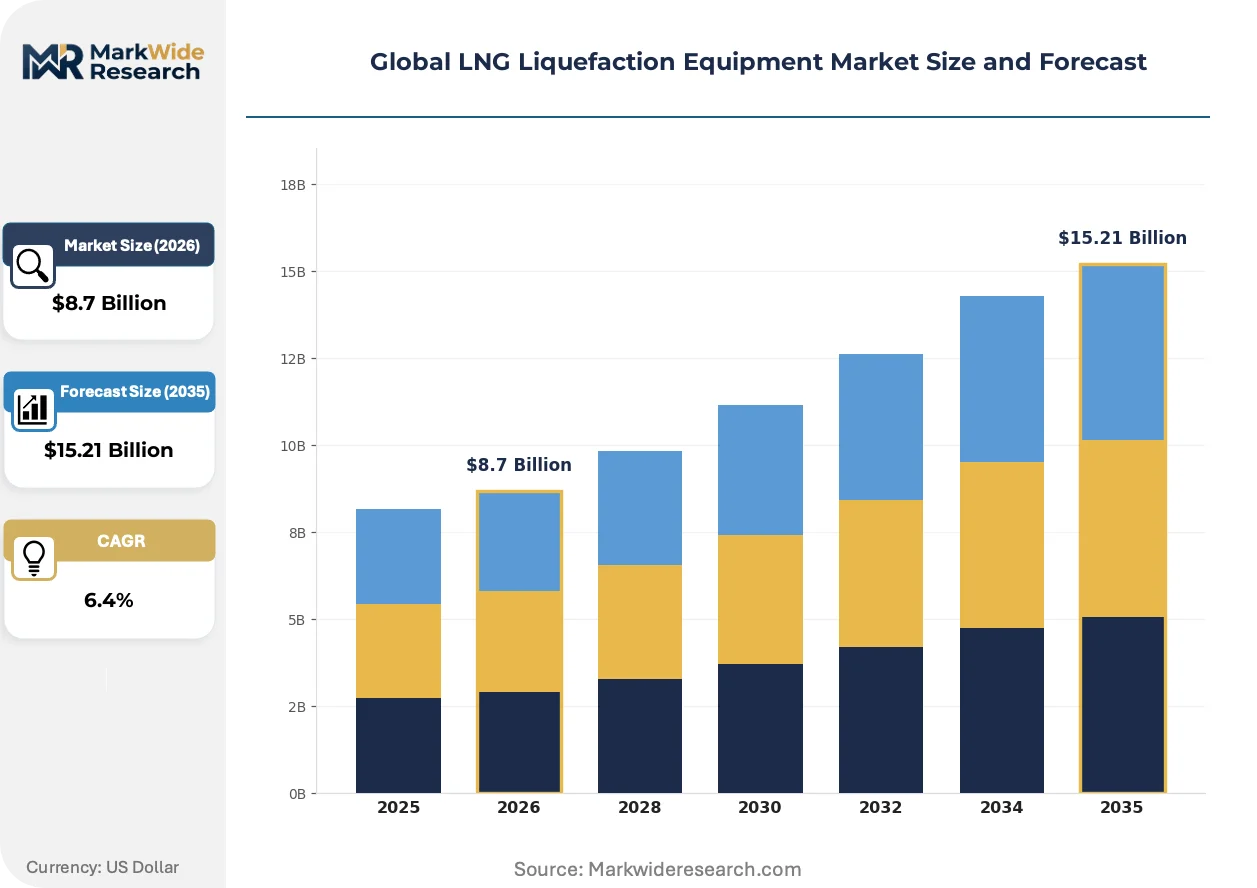
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigeration Compressors, Cryogenic Pumps, Heat Exchangers, Expansion Turbines, Control Valves Technology: Mixed Refrigerant Cycles, Cascade Cycles, Expander Cycles, Dual Mixed Refrigerant, Nitrogen Rejection Application: Floating LNG Facilities, Land-Based Plants, Peak Shaving Units, Small-Scale LNG, Modular Liquefaction End User Industry: Liquefaction Licensing Firms, Gas Producers, Energy Infrastructure Operators, Marine Terminal Operators |
| Companies Covered | Air Products and Chemicals, Linde Group, ConocoPhillips Company, Atlas Copco, Ingersoll Rand, General Electric, Chart Energy and Chemicals, Kobelco Compressors, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LNG Liquefaction Equipment Market Shifts & Advancements
Equipment specification standards are bifurcating between maximum-efficiency land-based megatrains and weight-optimized floating systems, compressing the viable design space for universal product platforms.
Magnetic bearing centrifugal compressors are eliminating lubrication systems from refrigeration loops, reducing methane leakage pathways and maintenance intervals. Offshore project developers in Mozambique and Tanzania are specifying these units for floating LNG hulls where crane access is constrained. The technology is absorbing engineering talent from oil-free turbomachinery sectors, tightening recruitment pipelines for conventional compressor OEMs.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerant availability, forcing liquefaction designers to evaluate ammonia and hydrocarbon alternatives for auxiliary cooling circuits. Industrial gas majors are retrofitting existing propane storage and handling systems to accommodate wider refrigerant portfolios. Asian engineering contractors face the steepest compliance curve, as their standard specifications rely heavily on phased-out HFC blends.
Buyers are unbundling long-term service contracts from initial equipment procurement, compressing vendor margins on aftermarket parts and specialist technician deployment. QatarEnergy and US Gulf Coast terminal operators are establishing in-house maintenance capabilities for refrigeration compressors, displacing OEM service revenue streams. This pattern is most visible in Australia, where Chevron and Shell have built captive technician workforces for Gorgon and Prelude facilities.
Global LNG Liquefaction Equipment Market Segmentation
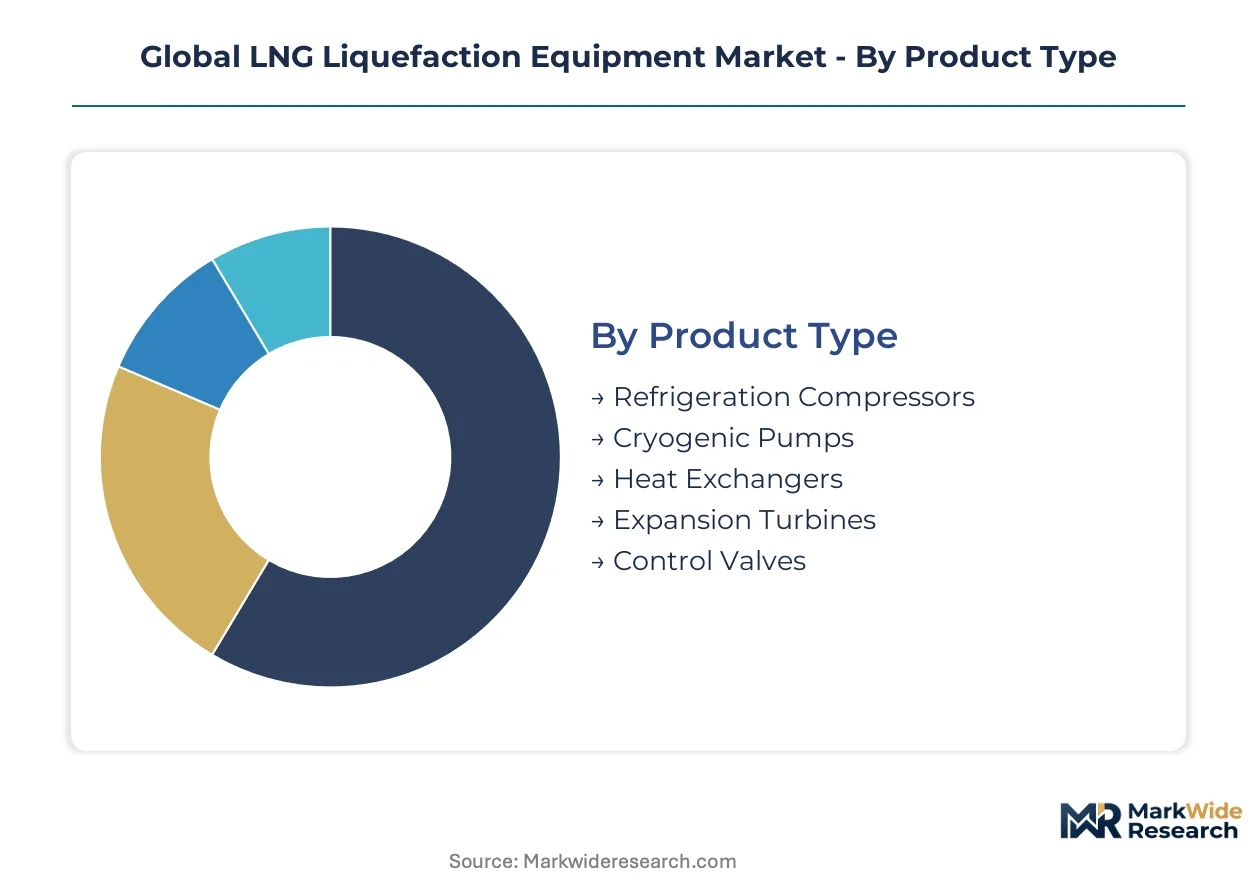
Equipment segmentation in LNG liquefaction determines procurement timelines, certification pathways, and vendor qualification requirements. Each product category and technology configuration carries distinct regulatory burdens that shape project economics and supplier selection criteria.
Product Type:
ASME Section VIII certification governs pressure vessel fabrication for cryogenic pumps and heat exchangers, while API 617 standards apply to centrifugal refrigeration compressors deployed in Qatar's megatrains and US Gulf Coast terminals.
- Refrigeration Compressors:Large-frame centrifugal units with magnetic bearing options eliminate lubrication systems and reduce methane leakage pathways. QatarEnergy's North Field expansion is pulling these into twenty-four-month fabrication backlogs, forcing vendors to prioritize capacity for state-led megaprojects over smaller orders.
- Heat Exchangers:Brazed aluminum plate-fin designs capture the largest capital share in greenfield trains but depend on aluminum-lithium alloys concentrated in Chinese and Russian smelter networks. Fabrication lead times now stretch eighteen months or longer, exposing project schedules to geopolitical supply shocks.
- Cryogenic Pumps:Submerged motor designs for LNG transfer and storage applications require NEMA or IEC explosion-proof certifications.
- Expansion Turbines:Cryogenic turboexpanders for refrigerant recovery loops demand precision balancing within ISO 1940 G2.5 standards.
- Control Valves:Low-temperature trim packages rated for minus 196 degrees Celsius service face extended factory acceptance testing protocols.
Leading the category by volume: Heat Exchangers. Growing fastest: Refrigeration Compressors.
Technology:
Cycle selection determines equipment count, energy intensity, and carbon border adjustment exposure for long-term offtake contracts.
- Mixed Refrigerant Cycles:Staged propane-ethylene-methane loops achieve thermodynamic efficiencies that cascade systems cannot match. US Gulf Coast brownfield additions and Qatari megatrains are standardizing on this configuration, displacing legacy Atlantic Basin infrastructure specifications.
- Dual Mixed Refrigerant:Advanced nitrogen rejection capabilities qualify projects for Japanese METI financing support, opening specification windows for specialized cryogenic separation equipment in pre-FID developments.
- Cascade Cycles:Legacy propane-ethylene-methane sequential cooling remains prevalent in older Atlantic Basin facilities facing retrofit decisions.
- Expander Cycles:Nitrogen-based refrigeration suits small-scale and peak shaving applications with lower throughput requirements.
- Nitrogen Rejection:Integrated cryogenic separation units address high-nitrogen feed gas compositions in select stranded gas developments.
Highest deployment share: Mixed Refrigerant Cycles. Steepest expansion trajectory: Dual Mixed Refrigerant.
Application:
Facility type dictates weight constraints, modularization requirements, and crane access assumptions that compress engineering timelines.
- Land-Based Plants:Maximum-efficiency megatrains with unlimited topside weight allowance enable full-scale compression trains and largest-diameter heat exchangers. Qatar and Australia anchor demand for this configuration.
- Floating LNG Facilities:Compact, skid-mounted packages must fit within shipyard lifting constraints while maintaining onshore-equivalent efficiency. Offshore developers in Mozambique and Tanzania are specifying magnetic bearing compressors to eliminate maintenance access requirements.
- Modular Liquefaction:Factory-fabricated, truck-shippable trains reduce field construction labor but limit individual unit capacity.
- Small-Scale LNG:Containerized or barge-mounted systems serve remote power generation and marine bunkering markets.
- Peak Shaving Units:Seasonal liquefaction and regasification facilities balance pipeline network demand fluctuations.
Dominant by installed capacity: Land-Based Plants. Climbing the fastest: Floating LNG Facilities.
End User Industry:
Procurement authority concentration varies by project structure, with integrated gas producers retaining equipment selection control in Qatar while US terminal developers delegate to EPC contractors.
- Gas Producers:State-led entities in Qatar and integrated majors in Australia specify equipment directly, establishing in-house maintenance capabilities that displace OEM service revenue. QatarEnergy's megatrain program is the single largest demand concentration.
- Liquefaction Licensing Firms:Technology licensors like Air Products and Linde bundle process design with equipment supply, capturing margin through proprietary refrigerant cycle configurations.
- Energy Infrastructure Operators:US Gulf Coast terminal developers rely on EPC contractors for equipment procurement, compressing vendor direct relationships.
- Marine Terminal Operators:Port authorities and floating storage operators specify transfer and custody transfer systems for import facilities.
Largest procurement volume: Gas Producers. Gaining share fastest: Liquefaction Licensing Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas reserves in Qatar's North Field and Australia's offshore basins anchor liquefaction capacity expansion, while US shale formations feed Gulf Coast export corridors. Equipment procurement concentrates where state-led megaprograms or FERC-permitted terminals drive final investment decisions.
United States
FERC export authorizations for Gulf Coast terminals in Texas and Louisiana are accelerating modular compression package orders. The Inflation Reduction Act's methane emissions provisions tighten equipment seal standards for projects seeking offtake contracts with European buyers. Corpus Christi and Sabine Pass anchor brownfield expansion clusters where EPC contractors delegate procurement to specialized vendors.
Qatar
QatarEnergy's North Field megatrain program represents the single largest demand concentration for large-frame refrigeration compressors. The state-led procurement structure retains direct equipment selection control, establishing in-house maintenance capabilities that displace OEM service revenue. Ras Laffan Industrial City hosts fabrication yards where cryogenic heat exchanger lead times now stretch twenty-four months.
Australia
Integrated majors Chevron and Shell have built captive technician workforces for Gorgon and Prelude facilities, displacing vendor aftermarket contracts. The country's national energy regulator enforces safety standards for cryogenic pressure vessels that exceed ASME Section VIII baselines. Karratha and Gladstone anchor liquefaction clusters where brownfield debottlenecking sustains equipment replacement cycles.
Japan
METI financing support for pre-FID projects adopting advanced nitrogen rejection or dual mixed refrigerant configurations shapes technology selection across Asian developments. The Ministry of Economy, Trade and Industry channels capital toward liquefaction trains with certified low-carbon intensity. Yokohama and Chiba host engineering centers where Japanese contractors specify equipment for Southeast Asian floating LNG projects.
Germany
The EU Green Deal's methane leakage standards under REACH and F-Gas Regulation frameworks disqualify legacy equipment designs from European-linked offtake contracts. ECHA oversight of refrigerant phase-downs forces liquefaction designers to evaluate ammonia alternatives for auxiliary cooling circuits. Hamburg and Munich anchor industrial gas engineering clusters where Linde Group maintains mixed refrigerant cycle expertise.
Global LNG Liquefaction Equipment Market Competitive Landscape
Global majors compete with regional champions across technology licensing and fabrication capacity. The supplier base consolidates around process licensors who bundle refrigerant cycle design with equipment supply, while specialized fabricators capture margin on long-lead components. Three archetypes dominate: integrated industrial gas majors with proprietary cycle configurations, compressor OEMs with magnetic bearing technology portfolios, and heat exchanger specialists with captive aluminum alloy supply relationships. Competitive moves center on backward integration into alloy smelting networks and strategic partnerships with EPC contractors for floating LNG hull integration.
Within the industrial gas licensor tier, Air Products and Chemicals and Linde Group exemplify the process-integrated model that captures margin through bundled technology and equipment supply. Chart Energy and Chemicals represents the component-specialist archetype, occupying a position where brazed aluminum heat exchanger fabrication expertise creates procurement leverage. Among Japanese precision engineering houses, IHI Corporation and Kobelco Compressors anchor the regional champion segment, with their geographic proximity to METI-financed projects in Southeast Asia creating specification advantages for nitrogen rejection and compact compression systems.
| Leading Market Players |
|---|
| Air Products and Chemicals |
| Linde Group |
| ConocoPhillips Company |
| Atlas Copco |
| Ingersoll Rand |
| General Electric |
| Chart Energy and Chemicals |
| Kobelco Compressors |
| IHI Corporation |
| Others |
Supply & Pricing Matrix
Buyers unbundling long-term service contracts from initial equipment procurement are compressing vendor margins and forcing suppliers to recalibrate revenue models toward pure equipment sales. This shift concentrates pricing power with state-led megaproject operators in Qatar and integrated majors in Australia, while tier-2 EPC contractors in the US Gulf Coast face squeezed terms.
Pricing Analysis
Warranty and aftermarket service bundling now separates premium-tier suppliers from standard-tier competitors, with magnetic bearing compressor packages commanding higher upfront pricing due to eliminated lubrication maintenance requirements. Price differentiation rests on ASME Section VIII certification grade and magnetic bearing technology inclusion, with pressure intensifying on conventional oil-lubricated systems as methane leakage standards tighten. European-linked offtake contracts show least price sensitivity due to EU Green Deal compliance premiums, while modular floating LNG developers in West Africa exhibit highest sensitivity due to capital constraints.
Supply Chain Analysis
Regional distribution for cryogenic heat exchanger cores flows through hub-and-spoke patterns anchored in German and Japanese engineering centers, with final assembly concentrating in Chinese and Russian aluminum-lithium alloy networks. Fabrication draws from specialized aluminum-lithium smelters, precision welding labor pools, and cryogenic instrumentation calibration facilities. Single-source vulnerability in aluminum alloy supply creates structural exposure to geopolitical disruption. Distribution runs through EPC contractor procurement channels for land-based projects and shipyard-integrated logistics for floating LNG hulls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global LNG Liquefaction Equipment Market functions as a cost-of-compliance arena where EU Green Deal methane standards and FERC permitting requirements erect barrier-to-entry moats favoring incumbent licensors with established certification pathways and regulatory relationships.
For Market Incumbents: Deepen backward integration into aluminum-lithium alloy supply networks to secure fabrication capacity against geopolitical shocks, while expanding captive technician training programs to offset buyer unbundling of aftermarket services. Magnetic bearing technology portfolios and integrated carbon capture-ready process designs represent critical defensive levers against emerging compact liquefaction specialists. For New Entrants and Emerging Players: EU Green Deal methane leakage standards in Germany open a window for specialized seal and flange manufacturers capable of certifying sub-ppm emission thresholds. West African floating LNG feasibility studies and Japanese METI-financed nitrogen rejection projects represent the most penetrable white-space targets. Go-to-market positioning should emphasize weight-optimized skid packages for shipyard lifting constraints. For Investors and Strategic Acquirers: The window for entry favors heat exchanger fabricators with captive aluminum alloy relationships or magnetic bearing compressor technology holders. Long-term viability centers on twenty-five-year asset life alignment with carbon border adjustment trajectories. Watch Qatari megatrain procurement cadence as the primary inflection signal for large-frame refrigeration compressor demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive aluminum-lithium sourcing insulates fabrication schedules from Chinese and Russian smelter disruptions. |
| Magnetic Bearing Technology Licensing | Elimination of lubrication systems reduces methane leakage pathways and satisfies EU Green Deal seal standards. |
| Carbon Capture-Ready Process Design | Integrated configurations qualify projects for EU CBAM procurement preference and long-term offtake contracts. |
| Captive Technician Workforce Development | In-house maintenance capabilities displace OEM service revenue and strengthen buyer negotiating position. |
| Floating LNG Hull Integration Partnership | Shipyard collaboration compresses engineering timelines for weight-optimized skid-mounted compression packages. |
Research Methodology
Document review covered FERC export authorization filings, EU ECHA regulatory frameworks, and Japanese METI financing guidelines, complemented by interviews with liquefaction licensing firm technology directors, EPC contractor procurement leads, and cryogenic equipment fabrication managers. Secondary validation drew from customs trade data, ASME certification registries, and project development databases. Bottom-up equipment shipment tallies and top-down capacity installation estimates were triangulated to anchor market sizing.
Historical capacity deployment patterns were cross-referenced against panel input from utility planning officers and integrated gas producer engineering directors. The analytical framework modeled segmentation across product type, refrigerant cycle technology, facility application, and end-user procurement authority throughout the projection horizon. CAGRs were derived from equipment lead time trajectories, final investment decision pipelines, and regulatory compliance cost curves specific to methane emissions standards and carbon border adjustment mechanisms.
The model assumes a particular technology adoption path favoring mixed refrigerant cycles and magnetic bearing compressors; alternative pathways for expander-based or cascade system retrofits would alter the outlook for heat exchanger and conventional compressor demand. Forecasts reflect documented assumptions around FERC permitting timelines, EU methane phase-down schedules, and Qatari megatrain procurement cadence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Smart Oilfield Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Middle East and Africa Digital Oilfield Market