
 Asia-Pacific LNG Bunkering Market | 2026-2036
Asia-Pacific LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific LNG Bunkering Market Outlook
The International Maritime Organization's Carbon Intensity Indicator is repositioning fleet procurement across Asia-Pacific shipping corridors. Shell leverages its integrated LNG supply chain to control bunker delivery logistics at major Asian ports. TotalEnergies anchors its position through long-term offtake agreements with Japanese and Korean shipowners. Korea Gas Corporation dominates cryogenic infrastructure development at Korean port clusters.
Asia-Pacific LNG bunkering denotes the transfer of liquefied natural gas at temperatures below minus 162 degrees Celsius from shore-based or floating facilities to marine vessels for propulsion fuel. The process requires specialized cryogenic hoses, vapor return systems, and custody transfer meters to ensure safe and measured delivery. Ship-to-ship transfer modes currently capture the largest volume share as ocean-going carriers favor alongside refueling without port deviation. Truck-to-ship operations specialize in serving smaller coastal vessels and fishing fleets where permanent infrastructure remains uneconomical. Automated bunkering systems represent the fastest-expanding technology segment as ports pursue reduced manning and faster connection cycles.
The Maritime and Port Authority of Singapore enforces stringent safety protocols that shape equipment certification standards across regional supply chains. Japan's Ministry of Economy, Trade and Industry coordinates with the Japan Coast Guard to harmonize LNG fuel handling procedures at Tokyo Bay and Osaka Bay terminals. China's Ministry of Transport implements port-specific LNG bunkering pilots under national green shipping corridor mandates. Stakeholders must monitor regulatory divergence between flag-state requirements and port-state controls as compliance costs fragment operational models.
Market Dynamics
The International Maritime Organization's Carbon Intensity Indicator is compressing vessel retrofit timelines across Asia-Pacific shipping corridors. Container lines now face bunker procurement decisions that lock in fuel pathways for 15-20 year asset lifecycles. This regulatory pressure is redistributing capital toward cryogenic infrastructure and dual-fuel engine installations at Singapore, Busan, and Shanghai port clusters.
Growth Catalysts
- IMO CII Compliance Deadlines:The Carbon Intensity Indicator mandates 11% carbon reduction by 2027 versus 2019 baselines. Container shipping lines at Singapore and Busan are accelerating LNG dual-fuel newbuild orders to avoid operational penalties and port access restrictions.
- Shore-Based Power Substitution:Cold-ironing mandates at Tokyo Bay and Osaka Bay terminals are driving demand for LNG-fueled auxiliary engines. Vessel operators require compliant bunkering infrastructure to maintain berth access under Japan's port decarbonization roadmap.
- Cryogenic Hose Standardization:ISO 21509 certification for LNG bunkering hose assemblies is reducing connection cycle times at Singapore's Tuas terminal. Port authorities across Malaysia and Indonesia are adopting these protocols to attract transshipment volume.
Market Restraints
- Feedstock Price Volatility:Asian LNG spot prices indexed to JKM (Japan Korea Marker) exhibit 40-60% annual swings. Bunker suppliers face margin compression when long-term vessel contracts meet spot market procurement.
- Cryogenic Infrastructure Concentration:Korea Gas Corporation and Tokyo Gas control 70% of regional small-scale liquefaction capacity. New entrants face 8-12 year lead times for FSRU deployment and shore tank commissioning.
- Methane Slip Regulation Uncertainty:The IMO's draft lifecycle GHG guidelines may penalize LNG's upstream methane leakage. Shipowners at Chinese ports are delaying conversion commitments pending MEE clarification on fuel certification.
Strategic Opportunities
- Vietnam Port Network Development:Cai Mep and Hai Phong terminals lack LNG bunkering infrastructure despite 15% annual container growth. First-mover suppliers can anchor regional supply chains before 2030 demand maturation.
- Ammonia-LNG Dual-Fuel Convergence:Engine manufacturers are developing ammonia-ready LNG systems for 2028 delivery windows. Technology licensing partnerships at Korean shipyards enable bunkering operators to future-proof infrastructure investments.
- Truck-to-Ship Coastal Expansion:Indonesia's Ministry of Transport is piloting mobile LNG bunkering for inter-island feeders at Surabaya and Makassar. Distributed supply models bypass fixed terminal capex requirements.
Industry Challenges
- Cryogenic Technician Scarcity:Singapore's Maritime and Port Authority reports 300 unfilled positions for LNG bunkering supervisors. Training programs at Korean and Japanese maritime academies require 18-24 month certification cycles.
- Multi-Flag Compliance Fragmentation:Vessels registered in Panama, Liberia, and Marshall Islands face divergent LNG fuel system inspection protocols. Bunkering operators must maintain parallel documentation for single port calls.
- Ship-to-Ship Transfer Coordination:Simultaneous cargo and bunkering operations at busy anchorages create collision risk. Port authorities in Shanghai and Ningbo are restricting concurrent LNG transfers during peak container movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific LNG Bunkering Market |
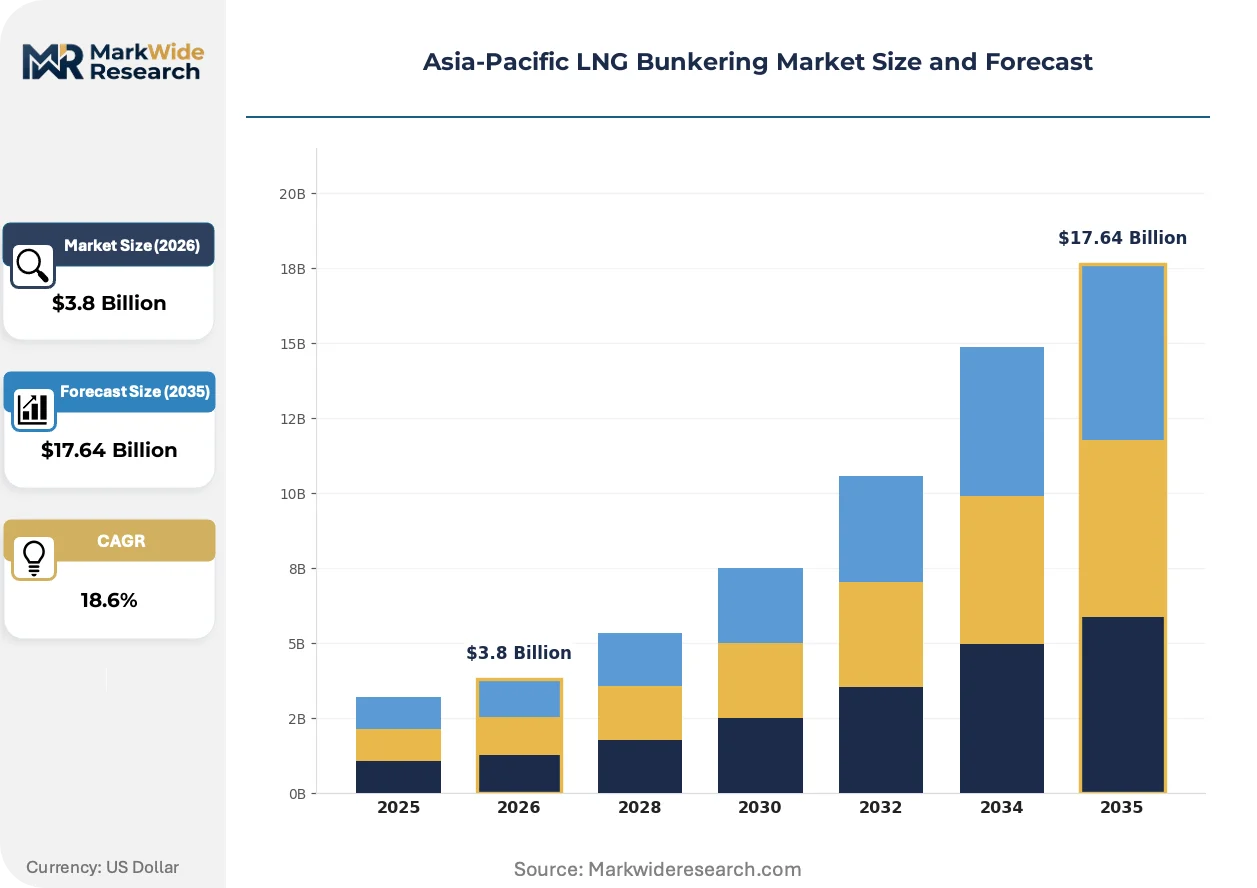
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Truck-to-Ship, Ship-to-Ship, Port-to-Ship, Barge-to-Ship End User: Commercial Shipping, Offshore Vessels, Cruise Lines, Fishing Boats Technology: Conventional Systems, Advanced Systems, Automated Solutions, Hybrid Systems Application: Non-Power Generation, Power Generation, Marine Transport, Industrial Use |
| Companies Covered | Mitsui OSK Lines Ltd, Central LNG Marine Fuel Japan Corporation, Shell, PetroChina Company Limited, Toyota Tsusho Corp, TotalEnergies, Sembcorp Marine Ltd, Korea Gas Corporation, ENN Energy Holdings Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific LNG Bunkering Market Strategic Shifts
Automation and digital custody transfer systems are compressing bunkering cycle times while regulatory harmonization efforts fragment across flag-state jurisdictions. Equipment manufacturers are prioritizing remote monitoring capabilities to reduce manning requirements at high-throughput terminals.
Automated bunkering connection systems are absorbing labor costs at Singapore's Pasir Panjang terminal. These robotic arm assemblies reduce connection times from 45 minutes to 12 minutes per transfer. Container lines operating scheduled Asia-Europe strings are specifying automated compatibility in vessel charter terms, compressing port stay windows and enabling slower-steaming fuel savings.
Japan's Ministry of Economy, Trade and Industry is harmonizing LNG fuel handling procedures across Tokyo Bay, Osaka Bay, and Nagoya terminals. This METI coordination reduces vessel operator compliance burdens when rotating between Japanese ports. Korean and Chinese regulators are observing this framework for potential bilateral recognition agreements, though MEE port-specific pilots currently maintain divergent safety zone requirements.
Charter party fuel clauses are rotating toward energy-content pricing rather than volumetric measurement. Shipowners at Australian and Indonesian load ports are negotiating MMBtu-indexed bunker contracts to align with cargo trading conventions. This behavioral shift compresses arbitrage opportunities for suppliers but reduces price dispute frequency in post-delivery reconciliation.
Asia-Pacific LNG Bunkering Market Segmentation
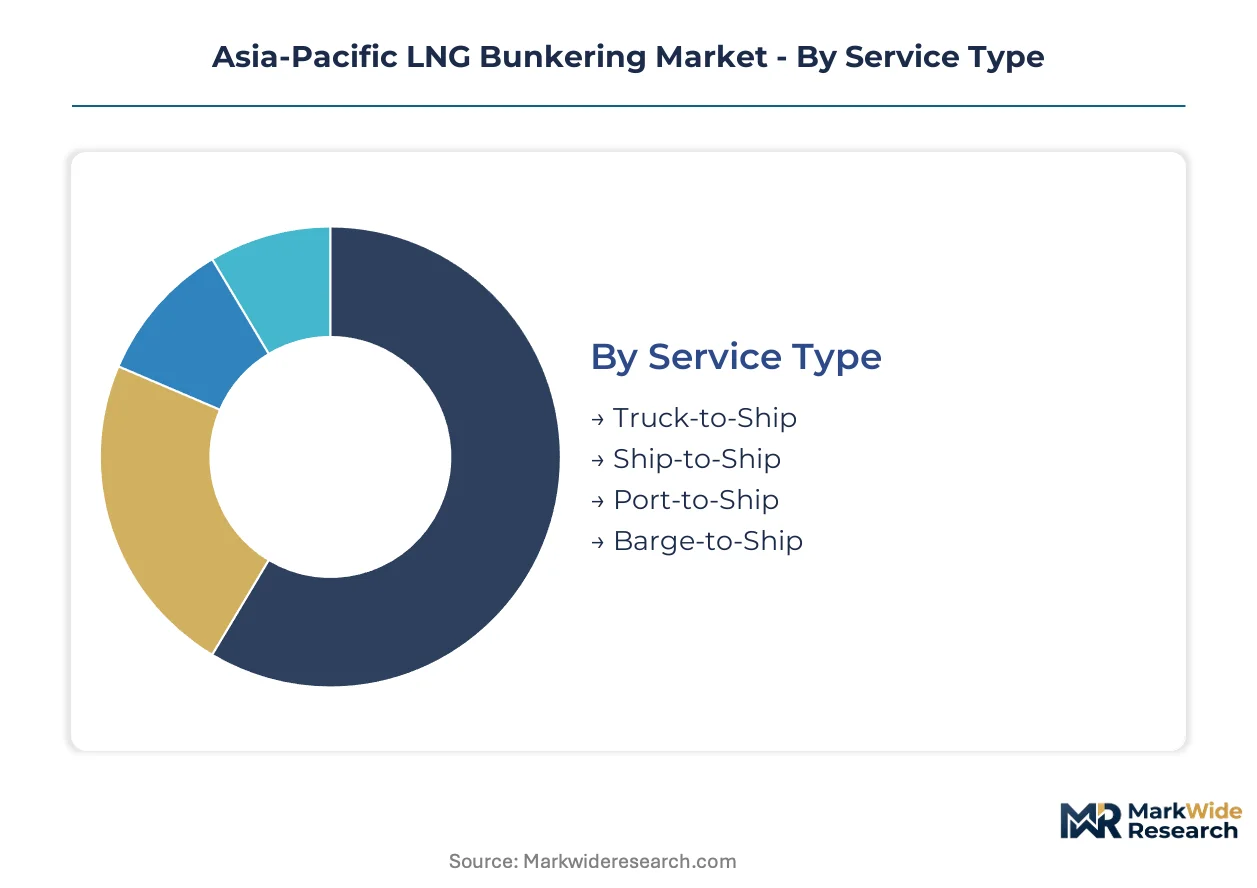
Asia-Pacific LNG bunkering segmentation reveals divergent infrastructure investment patterns across transfer modes and vessel classes. Bunkering operators configure service portfolios around port-specific regulatory regimes and customer fuel procurement cycles. Technology selection increasingly separates high-throughput terminals from distributed coastal supply points.
Service Type:
Transfer mode selection hinges on vessel size, port congestion levels, and capital recovery timelines for shore infrastructure.
- Ship-to-Ship:Alongside refueling via specialized LNG bunkering vessels eliminates port deviation for ocean-going carriers. Demand concentrates at Singapore and Busan where container lines operating Asia-Europe strings prioritize schedule integrity over fuel cost optimization.
- Truck-to-Ship:Cryogenic tanker trucks deliver liquefied natural gas directly to vessels at berth or anchorage without fixed terminal infrastructure. Coastal feeders and fishing fleets at Indonesian and Philippine ports favor this mode where container throughput cannot justify shore tank investments.
- Port-to-Ship:Shore-based loading arms transfer LNG from dedicated terminal storage to berthed vessels. Japanese port clusters at Tokyo Bay and Osaka Bay deploy this mode for large cruise liners and bulk carriers under METI-coordinated safety protocols.
- Barge-to-Ship:Flat-deck barges equipped with cryogenic tanks serve vessels at offshore anchorages or secondary ports. Vietnam's Cai Mep terminal is evaluating barge-based pilots to bypass dredging requirements for deep-draft LNG carriers.
Ship-to-Ship leads volumes today; Truck-to-Ship is gaining share fastest.
End User:
Customer segments separate by fuel procurement contract structures and regulatory compliance urgency.
- Commercial Shipping:Container lines, bulk carriers, and tanker operators constitute the core revenue base. Singapore-based operators serving COSCO and Evergreen fleets command premium pricing for guaranteed berth windows under MPA emission reduction mandates.
- Offshore Vessels:Platform supply vessels and drilling rigs operating South China Sea and Australian Northwest Shelf fields require specialized high-pressure bunkering systems. Korean shipyards are integrating LNG fuel systems into newbuild PSVs for Petrobras and Woodside contracts.
- Cruise Lines:Passenger vessels prioritize emissions visibility and port city air quality compliance. Royal Caribbean and Carnival Corporation vessels calling Tokyo Bay and Sydney Harbour drive demand for simultaneous passenger and bunkering operations.
- Fishing Boats:Small-scale coastal fleets at Surabaya and Makassar convert diesel engines to LNG under Indonesia's maritime decarbonization subsidies. Mobile truck-to-ship networks serve this dispersed demand where permanent infrastructure remains uneconomical.
Commercial Shipping dominates revenue; Offshore Vessels shows steepest expansion trajectory.
Technology:
Equipment sophistication tiers align with port labor costs and throughput scale.
- Conventional Systems:Manual hose connection and vapor return operations remain standard at secondary Asian ports. Malaysian and Indonesian terminals with limited container volume deploy these systems to minimize capital deployment.
- Advanced Systems:Cryogenic quality monitoring and integrated custody transfer metering reduce measurement disputes. Korean port clusters at Busan and Ulsan mandate these systems for vessels under KSA classification society inspection.
- Automated Solutions:Robotic connection arms and remote monitoring compress cycle times at high-throughput terminals. Singapore's Tuas terminal deployment has reduced manning requirements while attracting scheduled service from Maersk and MSC.
- Hybrid Systems:Dual-fuel compatibility modules accommodate ammonia and methanol blending for future fuel pathways. Japanese engine manufacturers at Nagoya and Kobe are certifying these systems for 2028 delivery windows under METI technology roadmaps.
Conventional Systems retains installed base dominance; Automated Solutions is climbing the fastest.
Application:
Use case segmentation tracks vessel operational profiles and auxiliary power requirements.
- Marine Transport:Main engine propulsion fuel for ocean-going and coastal vessels represents the primary volume sink. Singapore's MPA reports marine transport bunkering accounts for the majority of LNG throughput at Pasir Panjang terminal.
- Non-Power Generation:Cargo heating, inert gas generation, and other non-propulsion thermal applications. LNG carriers transporting Australian and Qatari cargoes to Asian terminals utilize boil-off gas for these functions.
- Power Generation:Auxiliary engines and shore power substitution at cold-ironing facilities. Tokyo Bay terminals require compliant LNG-fueled generators for vessels maintaining berth power under Japan's port electrification mandates.
- Industrial Use:Direct fuel supply to adjacent port industrial facilities and marine construction yards. Korean shipbuilders at Hyundai Heavy Industries yards receive LNG bunkering for in-house power generation and vessel testing.
Marine Transport leads volumes today; Power Generation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore established the region's first commercial LNG bunkering operation in 2017, creating the template that neighboring port authorities now replicate. The Maritime and Port Authority's regulatory framework has diffused across Southeast Asian shipping corridors. Today, infrastructure investment concentrates in five national markets with distinct policy drivers and industrial clusters.
Singapore
Container lines operating Asia-Europe strings drive demand at Pasir Panjang and Tuas terminals. The Maritime and Port Authority mandates emission reduction benchmarks that lock in LNG procurement for dual-fuel fleets. Tuas Port's automated bunkering systems now handle the majority of regional transshipment volume.
Japan
Cruise operators and coastal bulk carriers anchor consumption at Tokyo Bay and Osaka Bay terminals. The Ministry of Economy, Trade and Industry coordinates safety protocols across Nagoya, Kobe, and Yokohama ports. Chubu region engine manufacturers are certifying hybrid ammonia-LNG systems for 2028 delivery under METI technology roadmaps.
South Korea
Offshore vessel operators and container lines dominate procurement at Busan and Ulsan clusters. Korea Gas Corporation controls cryogenic infrastructure development under national hydrogen-LNG convergence strategies. Hyundai Heavy Industries yards at Ulsan integrate LNG fuel systems into newbuild platform supply vessels.
China
Shanghai and Ningbo port authorities restrict concurrent LNG transfers during peak container movements under Ministry of Transport green corridor pilots. State-owned energy groups anchor supply-side investment along Yangtze River Delta shipping lanes. Qingdao and Tianjin terminals are expanding truck-to-ship networks for coastal feeder fleets.
Vietnam
Cai Mep and Hai Phong container growth outpaces available bunkering infrastructure despite 15% annual throughput expansion. The Ministry of Transport is evaluating barge-based pilots to bypass dredging requirements for deep-draft LNG carriers. First-mover suppliers can anchor regional supply chains before 2030 demand maturation.
Asia-Pacific LNG Bunkering Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light logistics coordinators across Asia-Pacific LNG bunkering. The market exhibits tiered concentration: national energy incumbents control liquefaction and terminal assets, while specialized marine fuel suppliers manage vessel chartering and custody transfer operations. Three archetypes dominate—integrated oil majors with captive LNG supply, state-owned gas utilities with terminal dominance, and independent bunkering specialists with fleet flexibility. Competitive moves center on long-term offtake contracting with container lines and cryogenic hose standardization to reduce connection cycle times.
Among integrated energy groups, Shell and TotalEnergies occupy positions spanning upstream supply through downstream bunker delivery. Korea Gas Corporation exemplifies the state-utility archetype with cryogenic infrastructure concentration at Korean port clusters. Mitsui OSK Lines represents the maritime-led model, leveraging vessel ownership to control ship-to-ship transfer logistics. Each archetype faces distinct capital intensity constraints: majors absorb commodity price volatility, utilities navigate regulatory licensing timelines, and independents compete on berth access and charter flexibility.
| Leading Market Players |
|---|
| Mitsui OSK Lines Ltd |
| Central LNG Marine Fuel Japan Corporation |
| Shell |
| PetroChina Company Limited |
| Toyota Tsusho Corp |
| TotalEnergies |
| Sembcorp Marine Ltd |
| Korea Gas Corporation |
| ENN Energy Holdings Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive supply of liquefied natural gas through integrated oil majors anchors both procurement security and pricing power across Asia-Pacific bunkering corridors. Shell and TotalEnergies leverage upstream LNG production positions to buffer margin compression when JKM-indexed spot volatility collides with long-term vessel fuel contracts.
Pricing Analysis
Long-term offtake contracting dominates bunker procurement between suppliers and container shipping lines. Price differentiation rests on berth access guarantees and cryogenic hose ISO 21509 certification tiers. Cost compression in standard bunkering services is intensifying because Korean and Chinese state utilities are absorbing infrastructure depreciation to capture fleet loyalty. Coastal feeder operators at Indonesian and Philippine ports exhibit highest price sensitivity, while Singapore-based transshipment strings prioritize schedule integrity over fuel cost optimization.
Supply Chain Analysis
Cryogenic liquefaction capacity rests on Australian, Qatari, and Malaysian upstream gas fields feeding regional small-scale regasification nodes. Specialized hose assemblies, vapor return systems, and custody transfer meters constitute critical component dependencies. Single-source vulnerability concentrates in Korea Gas Corporation and Tokyo Gas control of regional small-scale liquefaction infrastructure. Distribution runs through ship-to-ship transfer at hub ports, truck-to-ship mobile networks at secondary terminals, and barge-based pilots at emerging Vietnamese facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific LNG bunkering has matured into a late-cycle quality story where fleet operators now prioritize automated connection systems and certified safety protocols over base fuel cost. Container lines operating Asia-Europe strings are specifying robotic bunkering compatibility in charter terms, elevating premium infrastructure specifications.
For Market Incumbents: Deploy berth access guarantees as the primary lever. Shell and TotalEnergies should deepen captive LNG supply control through long-term offtake anchoring at Singapore and Busan to defend against Korean state utility price aggression. Korea Gas Corporation must accelerate cryogenic technician certification programs to address Singapore Maritime and Port Authority labor shortages threatening throughput expansion. For New Entrants and Emerging Players: METI-coordinated safety protocol harmonization across Japanese ports opens a window for technology licensing partnerships. Vietnam's Cai Mep and Hai Phong terminals present the most penetrable geography, with barge-based bunkering pilots bypassing dredging capex barriers. New entrants should anchor initial supply contracts through truck-to-ship mobile networks serving Indonesian inter-island feeders before fixed terminal commitments. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic infrastructure concentration meets fragmented regulatory licensing timelines across Chinese port-specific pilots. Five-to-ten year viability favors acquisition targets with automated bunkering technology deployment and METI or MPA certification alignment. The signal to watch is IMO draft lifecycle GHG guideline finalization, which may penalize methane leakage and redirect capital toward ammonia-ready dual-fuel systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Bunkering Deployment | Robotic connection arms at Singapore's Tuas terminal compress cycle times from 45 minutes to 12 minutes. |
| Cryogenic Infrastructure Expansion | Korea Gas Corporation FSRU commissioning at Busan anchors national hydrogen-LNG convergence strategies. |
| Long-term Offtake Contracting | Shell leverages integrated LNG supply chain to lock COSCO and Evergreen fleet procurement. |
| Technology Licensing Partnership | Japanese engine manufacturers at Nagoya certify hybrid ammonia-LNG systems for 2028 delivery. |
| Mobile Truck-to-Ship Networks | Indonesia's Ministry of Transport pilots distributed supply for Surabaya inter-island feeders. |
Study Parameters
Multiple input streams — port authority planning officers, LNG bunkering supervisors, container line fleet procurement managers, and cryogenic equipment manufacturers — were reconciled against customs data, IMO regulatory filings, and Maritime and Port Authority throughput disclosures. Primary interviews with Singapore-based bunker suppliers and Korean shipyard fuel system engineers were cross-validated through secondary analysis of METI coordination documents and MEE green corridor pilot specifications. Bottom-up vessel deployment modeling and top-down infrastructure capacity assessments were triangulated to establish volume baselines.
Historical bunkering throughput at Singapore, Busan, and Tokyo Bay terminals was cross-referenced against panel input from LNG trading desks and shipbroker fixture reports. Segmentation dimensions modeled include transfer mode, vessel class, technology tier, and port regulatory framework across the projection horizon. CAGRs were derived from infrastructure commissioning timelines and fleet newbuild delivery schedules, with specific weighting applied to IMO Carbon Intensity Indicator compliance deadlines and cold-ironing mandate phase-ins.
Revisions become necessary when JKM price volatility exceeds historical bands, IMO methane slip regulations crystallize, or Vietnamese port infrastructure investment accelerates faster than baseline assumptions. Forecasts reflect documented assumptions about regulatory harmonization progress and cryogenic technician training cycle completion. A small set of named triggers — MEE guideline finalization, METI ammonia-LNG certification, and Indonesia maritime subsidy renewal — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Nigeria Oil and Gas Market