
 Subsea Manifolds Market | 2026-2036
Subsea Manifolds Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Manifolds Market Analysis
The gap between fully integrated subsea production systems and standalone commodity manifolds is repositioning how operators evaluate lifecycle costs versus upfront capital. TechnipFMC plc leverages its integrated engineering-to-installation model to anchor complex deepwater projects. Baker Hughes Company competes through modular architectures that reduce offshore hookup duration. SLB differentiates via digital twin integration that extends asset monitoring beyond commissioning.
Subsea manifolds are pressure-rated flow distribution structures fabricated from duplex or super-duplex stainless steels, designed to consolidate production, injection, and monitoring lines at the seabed and direct hydrocarbons toward riser bases or processing facilities. Horizontal manifolds dominate mature basins where template-based field architecture prevails, while compact manifolds represent the fastest-growing configuration as operators prioritize vessel-deck space and simplified installation logistics. The production phase segment commands the largest installed base, though decommissioning phase activity is intensifying as North Sea and Gulf of Mexico assets reach end-of-design life.
API Specification 17D and ISO 13628-4 govern subsea manifold design, materials, and testing protocols, while national regulators such as BSEE in the United States and Norway's Petroleum Safety Authority enforce facility-specific integrity management requirements. Brazil's ANP mandates local content thresholds that reshape supplier qualification and fabrication location decisions for pre-salt developments. Stakeholders must weigh standardization benefits against field-specific customization as project economics tighten and lead-time compression becomes a decisive competitive variable.
Market Dynamics
Subsea manifold procurement is pivoting toward lifecycle contracting models as operators seek to transfer commissioning risk and decommissioning liability to equipment vendors. This structural shift compresses supplier margins while extending accountability windows across decades of subsea asset operation.
Growth Catalysts
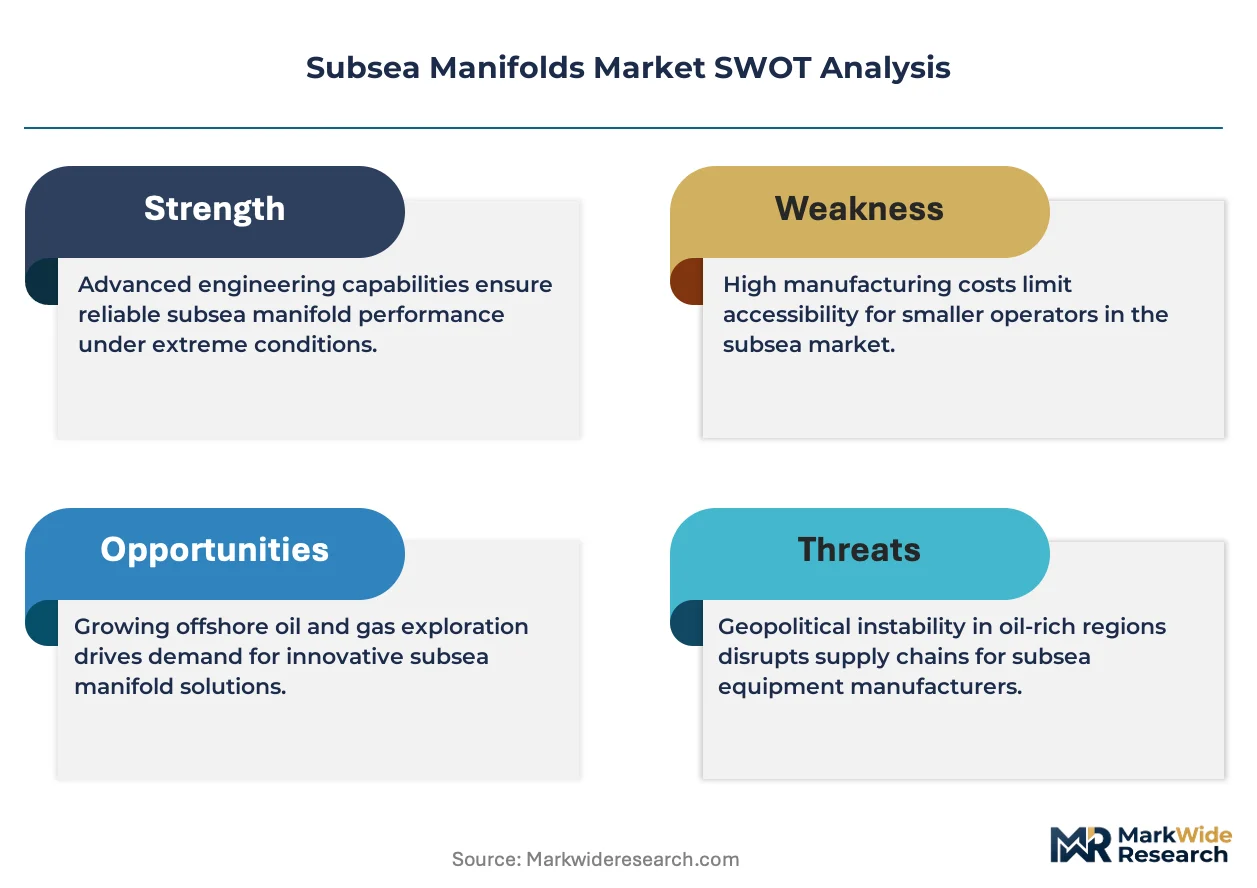
- Brazil's ANP local content mandates:Domestic fabrication requirements for pre-salt developments are redirecting supply chain investment toward South Atlantic manufacturing clusters.
- Digital twin integration:Real-time manifold performance monitoring is reducing unplanned subsea interventions and extending mean time between failures.
- Ultra-deepwater tiebacks:Brownfield operators in the Gulf of Mexico are reusing existing infrastructure through compact manifold architectures.
Market Restraints
- Super-duplex stainless steel price volatility:Nickel and molybdenum input costs swing manifold fabrication economics unpredictably.
- Fabrication concentration in Southeast Asia:Limited qualified vessel yards in Singapore and South Korea create chokepoints for large-diameter manifold delivery.
- API 17D qualification timelines:Extended third-party verification cycles delay project sanctioning and compress installation windows.
Strategic Opportunities
- West African deepwater:Underdeveloped subsea infrastructure in Angola and Nigeria offers first-mover positioning for integrated production system vendors.
- Carbon capture injection manifolds:Offshore CO2 storage projects require adapted manifold architectures for corrosive service conditions.
- Modular standardization:Pre-engineered manifold skids are reducing engineering hours and enabling batch fabrication economies.
Industry Challenges
- Welding inspector certification scarcity:Qualified hyperbaric weld inspectors for duplex steel fabrication command premium rates and extend yard schedules.
- Legacy control system integration:New digital manifolds must interface with 1990s-era subsea distribution units without full umbilical replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Manifolds Market |
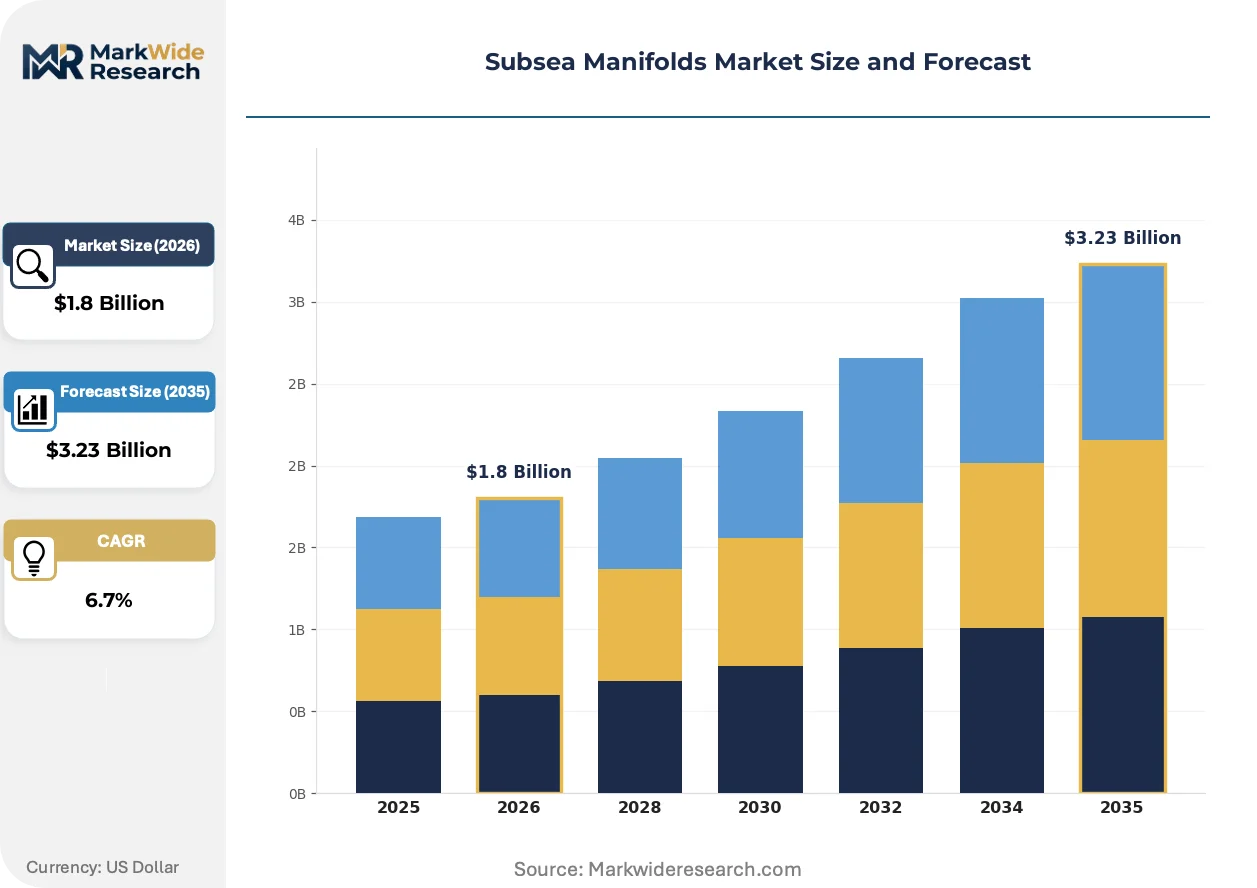
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Manifolds, Vertical Manifolds, Compact Manifolds, Multi-Function Manifolds Installation Type: Shallow Water, Deep Water, Ultra-Deep Water, Subsea Templates End User: Oil & Gas Operators, Service Companies, Engineering Firms, Subsea Equipment Manufacturers Phase: Development Phase, Production Phase, Decommissioning Phase, Maintenance Phase |
| Companies Covered | TechnipFMC plc, Baker Hughes Company, Aker Solutions, SLB, Subsea7, Halliburton Company, Dril-Quip, Inc., Weatherford, NOV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Manifolds Market Emerging Trajectories
Subsea production architecture is compressing toward seabed factory concepts where processing, boosting, and metering migrate from platforms to the ocean floor. This redistribution of functional scope is redefining manifold design specifications and vendor capability requirements.
Compact steel tube flying lead technology is modularizing subsea connection systems, enabling manifold-to-tree hookups without diver intervention. Independent operators in the North Sea are adopting this approach to reduce offshore personnel exposure and compress installation campaigns from weeks to days. The technology is modularizing procurement patterns by separating mechanical connection scope from manifold fabrication contracts.
Norway's Petroleum Safety Authority has tightened barrier integrity documentation requirements for subsea facilities, mandating quantitative risk assessments for manifold pressure-containing components. Operators must now demonstrate failure mode coverage across all conceivable leak paths before installation consent. The Norwegian Continental Shelf is responding through enhanced factory acceptance testing protocols and third-party verification scope expansion.
Integrated service contracts are displacing discrete equipment purchases as majors bundle manifold supply with installation and life-of-field support. This consolidation concentrates vendor selection authority within central engineering teams and marginalizes standalone equipment suppliers. The Gulf of Mexico exhibits this pattern most acutely, where operator procurement functions have merged subsea hardware and subsea construction into single tender packages.
Subsea Manifolds Market Segmentation
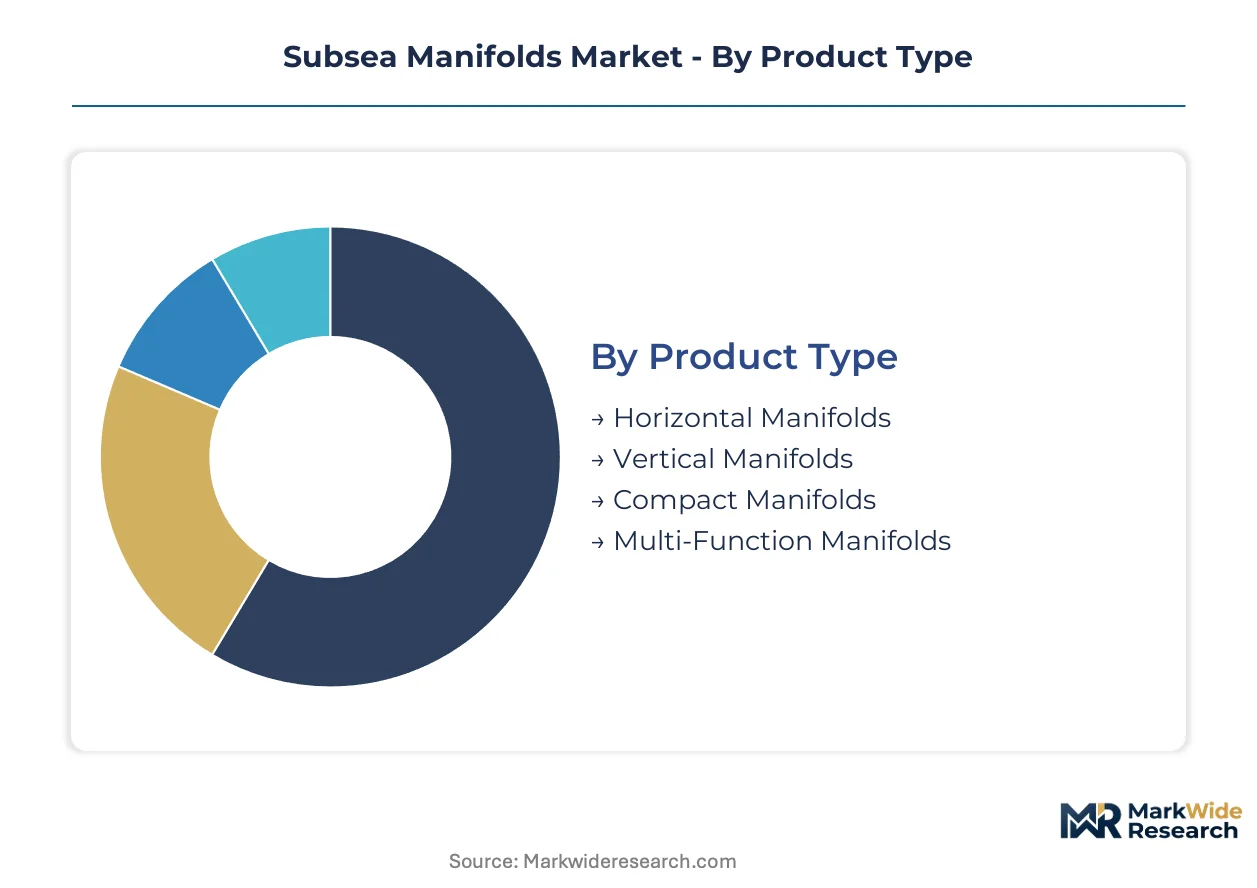
Segmentation in subsea manifolds reveals how capital allocation, water depth, and field lifecycle stage reshape procurement patterns. Operators match manifold architecture to reservoir pressure, installation vessel capability, and tieback economics.
Product Type:
Capital intensity varies sharply across manifold architectures, with integrated processing functions and ultra-deepwater ratings commanding premium engineering investment.
- Horizontal Manifolds:Template-based structures distribute multiple wellbores across a planar seabed footprint. Petrobras deploys these extensively across Brazil's pre-salt Santos Basin where cluster drilling demands high-capacity flow distribution.
- Compact Manifolds:Reduced deck-sphere designs prioritize vessel crane limits and simplified installation logistics. Gulf of Mexico brownfield operators favor these for marginal field tiebacks where infrastructure reuse compresses project breakeven.
- Vertical Manifolds:Stacked valve arrangements suit congested seabed corridors with limited horizontal clearance.
- Multi-Function Manifolds:Integrated processing, boosting, and metering capabilities consolidate subsea factory functions.
Horizontal manifolds absorb the bulk of installed capacity; compact manifolds are expanding most quickly.
Installation Type:
Water depth thresholds determine fabrication standards, metallurgy grades, and installation vessel specifications.
- Deep Water:400-1500 meter ratings dominate current procurement as mature basins exhaust shelf prospects. Angola's Block 17 developments exemplify this tier's engineering complexity and supplier qualification demands.
- Ultra-Deep Water:Beyond 1500 meters requires super-duplex alloys and dynamic positioning installation spreads. Brazil's pre-salt Buzios and Mero fields anchor global demand for this specification tier.
- Shallow Water:Conventional carbon steel designs serve shelf developments with lower pressure ratings.
- Subsea Templates:Integrated structural frames combine manifold functions with drilling and completion support.
Deep water installations carry the largest committed capital; ultra-deep water projects are climbing the fastest.
End User:
Procurement authority concentrates among integrated operators with multi-decade field development horizons.
- Oil & Gas Operators:Majors and national oil companies specify manifold architectures and anchor vendor relationships through lifecycle contracts. ExxonMobil, Shell, and Petrobras exercise disproportionate influence over industry design standards.
- Service Companies:Subsea construction specialists procure manifolds as part of integrated installation packages. TechnipFMC and Subsea 7 bundle fabrication with offshore hookup to compress project schedules.
- Engineering Firms:Design contractors influence manifold selection during front-end engineering phases.
- Subsea Equipment Manufacturers:Tier-two fabricators supply standardized manifold skids for non-critical applications.
Oil and gas operators deploy the dominant share of procurement capital; service companies are gaining share fastest through integrated contracting.
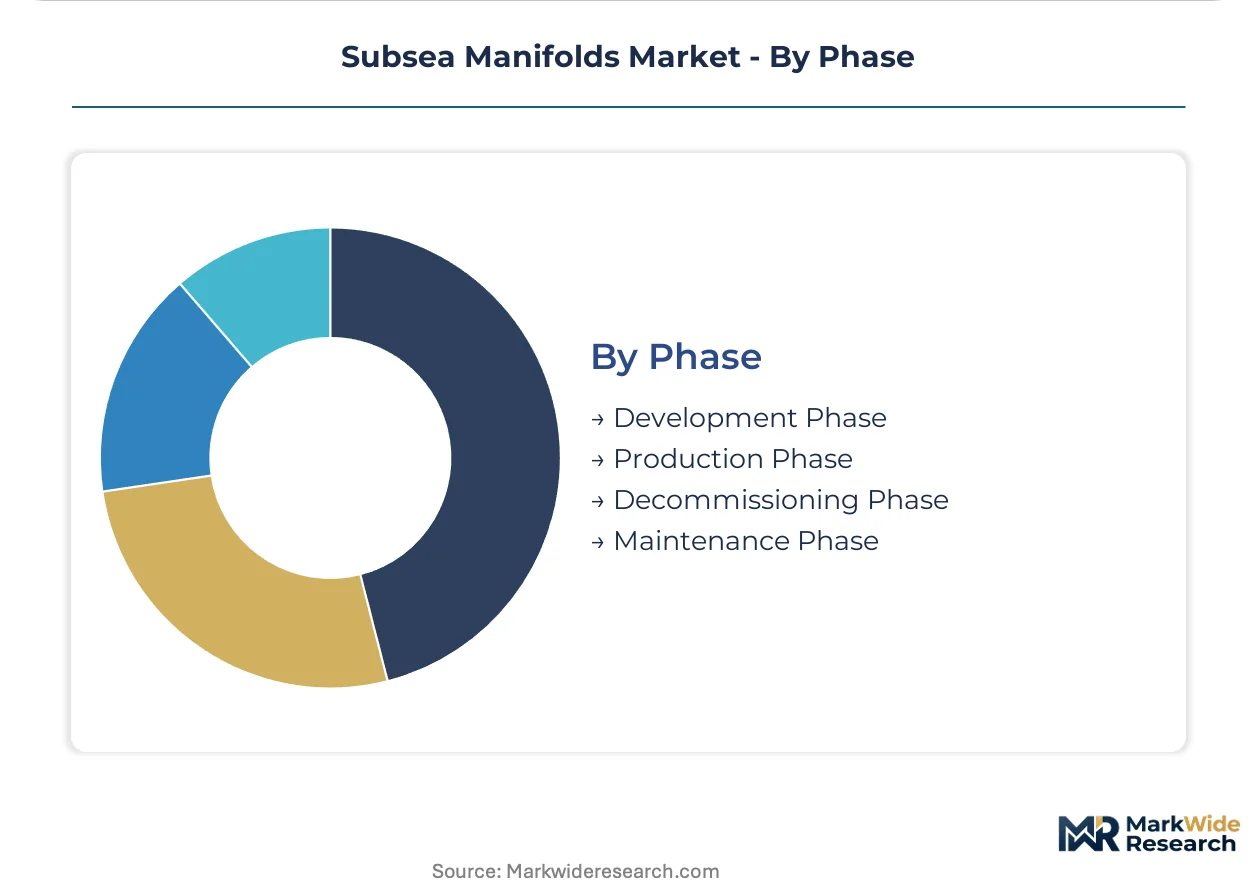
Phase:
Lifecycle stage determines manifold specification urgency, spare parts strategy, and regulatory compliance intensity.
- Production Phase:Sustained intervention demand, corrosion monitoring, and flow assurance challenges characterize this longest-duration segment. North Sea operators face intensifying integrity management as 1990s-era manifolds approach design life.
- Decommissioning Phase:Plug and abandonment campaigns, seabed clearance, and material recovery reshape supplier relationships. UK and Norwegian regulators now mandate detailed manifold removal planning decades ahead of cessation.
- Development Phase:Greenfield sanctioning and brownfield tieback engineering drive newbuild manifold orders.
- Maintenance Phase:Scheduled overhaul, valve replacement, and control system upgrades sustain aftermarket revenue.
Production phase manifolds represent the largest installed base; decommissioning phase activity is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors subsea manifold engineering concentration, with the Gulf Coast corridor hosting fabrication yards and engineering centers that serve ultra-deepwater developments across the Americas and West Africa.
Brazil
Petrobras-led pre-salt developments in the Santos and Campos basins drive demand for ultra-deepwater manifold architectures rated beyond 2000 meters. Brazil's ANP mandates local content thresholds that redirect fabrication toward South Atlantic supply clusters. The Rio de Janeiro metropolitan area hosts engineering centers and qualification facilities serving Buzios, Mero, and Tupi field developments.
United States
Brownfield tieback projects in the Gulf of Mexico reuse existing infrastructure through compact manifold designs that compress project breakeven economics. The Bureau of Safety and Environmental Enforcement enforces facility-specific integrity management requirements for subsea facilities. Houston and New Orleans corridor yards specialize in super-duplex fabrication for high-pressure high-temperature applications.
Norway
North Sea decommissioning activity intensifies as 1990s-era manifolds approach design life, reshaping supplier relationships toward removal and material recovery services. The Petroleum Safety Authority mandates quantitative risk assessments for manifold pressure-containing components before installation consent. Stavanger and Bergen engineering clusters lead barrier integrity documentation and enhanced factory acceptance testing protocols.
United Kingdom
Plug and abandonment campaigns accelerate across mature North Sea assets, requiring detailed manifold removal planning decades ahead of cessation. The North Sea Transition Authority enforces decommissioning liability frameworks that transfer accountability to equipment vendors. Aberdeen engineering centers pivot toward late-life asset management and seabed clearance project management.
Angola
Underdeveloped subsea infrastructure in Block 17 and adjacent deepwater concessions offers first-mover positioning for integrated production system vendors. The national petroleum regulator oversees concession-specific local content requirements that shape supplier qualification. Luanda and Cabinda logistics corridors serve as staging points for ultra-deepwater installation campaigns.
Subsea Manifolds Market Vendor Landscape
Premium-margin players sit above commodity-margin players across engineering complexity and lifecycle contract scope, with integrated production system vendors capturing disproportionate value through risk-transfer arrangements. The vendor base organizes into three tiers: full-system integrators with installation capabilities, modular equipment specialists, and standardized skid fabricators. Market structure rewards M&A-driven capability consolidation and strategic partnerships that bundle fabrication with offshore construction services.
Among integrated engineering-to-installation providers, TechnipFMC plc and Baker Hughes Company exemplify the premium-tier archetype through lifecycle contracting models that extend accountability across decades of subsea operation. SLB occupies a position within the digital integration vector, representing vendors that anchor competitive differentiation through asset monitoring beyond commissioning. These three entities collectively illustrate how procurement authority concentrates within central engineering teams that merge hardware supply with subsea construction scope.
| Leading Market Players |
|---|
| TechnipFMC plc |
| Baker Hughes Company |
| Aker Solutions |
| SLB |
| Subsea7 |
| Halliburton Company |
| Dril-Quip, Inc. |
| Weatherford |
| NOV |
| Others |
Supply Flow & Price Mechanics
Hyperbaric welding inspector concentration in Southeast Asian fabrication yards widens labor-cost differentials between premium-tier super-duplex manifolds and standardized carbon-steel alternatives. API 17D qualification timelines compress installation windows, forcing operators to absorb premium rates for certified capacity or accept extended yard schedules.
Pricing Analysis
Lifecycle uptime guarantees anchor value-based pricing for integrated manifold systems, with vendors contracting against mean-time-between-failure thresholds rather than unit hardware costs. Price differentiation separates API-certified super-duplex architectures from commodity carbon-steel skids, with brand premiums attaching to installation track records in ultra-deepwater basins. Cost compression in shallow-water tiers intensifies as standardized designs commoditize, while least price sensitivity concentrates among pre-salt operators where failure costs dwarf procurement premiums.
Supply Chain Analysis
API 17D and ISO 13628-4 certification gating restricts qualified fabrication to Singapore, South Korea, and Norway, creating capacity chokepoints for large-diameter manifold delivery. Raw material procurement draws from nickel and molybdenum suppliers in Indonesia and the Philippines, with super-duplex alloy production concentrated in European specialty steel mills. Single-source vulnerability runs through Southeast Asian heavy-lift vessel availability, while distribution feeds through integrated service contractors bundling fabrication with offshore installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API Specification 17D compliance costs erect a formidable barrier-to-entry moat, with third-party verification cycles and material traceability requirements filtering out capital-constrained fabricators. This cost-of-compliance structure rewards incumbent investment in qualification infrastructure.
For Market Incumbents: Anticipate margin compression from modular standardization trends by deepening captive control over super-duplex alloy supply and expanding Southeast Asian yard capacity ahead of competitor entry. Defend positioning through accelerated digital twin integration that extends service revenue beyond hardware delivery, countering emerging threats from software-native entrants.
For New Entrants and Emerging Players: Enter via carbon capture injection manifold adaptation for corrosive service conditions, where incumbent qualification lags create white-space opportunity. Target West African deepwater developments in Angola and Nigeria, where underdeveloped subsea infrastructure and local content flexibility enable first-mover positioning without confronting entrenched supplier relationships in Brazil or the Gulf of Mexico.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated production system vendors given lifecycle contracting momentum transferring decades of accountability to equipment suppliers. Long-term viability favors archetypes with installation capabilities anchoring ultra-deepwater pre-salt exposure. Watch Brazil's ANP local content threshold adjustments as the inflection signal determining South Atlantic supply cluster investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Super-Duplex Alloy Supply | Captive nickel and molybdenum sourcing insulates fabrication margins from commodity volatility. |
| Digital Twin Platform Development | Real-time manifold monitoring extends vendor accountability beyond commissioning into operational phases. |
| Carbon Capture Manifold Adaptation | CO2 injection service conditions require corrosion-resistant architectures opening adjacent market entry. |
| Southeast Asian Yard Capacity Expansion | Singapore and South Korea fabrication chokepoints reward preemptive qualified capacity investment. |
| Lifecycle Contracting Model Adoption | Risk-transfer arrangements concentrate procurement authority with vendors accepting decommissioning liability. |
Methodological Framework
Regulatory filings from BSEE and Norway's Petroleum Safety Authority, trade customs data for super-duplex alloy shipments, and API qualification registries formed the secondary backbone for market sizing. Primary interviews with subsea project engineers, procurement directors at integrated oil companies, fabrication yard operations managers, and hyperbaric welding inspectors combined with secondary validation through bottom-up installation database triangulation and top-down capital expenditure reconciliation.
Historical trendline analysis of sanctioned project manifolds by water depth tier and field architecture type anchored the projection framework across the analysis window. Segmentation dimensions modeled include manifold configuration, installation depth rating, lifecycle phase, and regional regulatory cluster. CAGRs derived from facility-by-facility roll-up of disclosed and inferred procurement values, with forecast inputs incorporating Petrobras pre-salt development pacing and North Sea decommissioning liability enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Brazil local content threshold volatility and nickel price shock scenarios. Model assumptions reflect disclosed project sanctioning timelines, yard capacity utilization rates, and regulator enforcement patterns. A model refresh is warranted upon material change in ANP domestic fabrication mandates or BSEE barrier integrity documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Enclosed Flares Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Sucker Rod Market
Oil & Gas
United States Oil and Gas Separation Market