
 Energy Cable Market | 2026-2036
Energy Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Cable Market Analysis
Aftermarket service revenue for cable system maintenance and life-extension is narrowing as manufacturers push bundled long-term service contracts. Prysmian Group leverages its submarine installation fleet to control project delivery from factory to offshore termination. Nexans sustains competitive positioning through backward integration into compound manufacturing and HVDC converter stations. Sumitomo Electric Industries anchors its presence in Asia-Pacific through dominance in superconducting and high-temperature cable R&D.
Energy cables are insulated conductive assemblies, typically comprising copper or aluminum conductors with cross-linked polyethylene or ethylene propylene rubber insulation, engineered to transmit electrical power across generation, transmission, and distribution networks at voltages ranging from sub-1 kV to over 500 kV. Low voltage and medium voltage cables serve mature, replacement-driven demand in building wire and urban distribution, where margin pools have compressed to commodity levels. High voltage and extra high voltage segments carry structural premiums tied to project complexity, qualification timelines, and the limited supplier base capable of delivering submarine and underground installations for intercontinental grid links and offshore renewable connections.
The EU Green Deal and F-Gas Regulation shape European demand by mandating fluorinated gas reductions in cable insulation and accelerating offshore wind grid connections. China's GB standards and MIIT directives enforce localization requirements for ultra-high-voltage transmission components, constraining market access for non-domestic suppliers. In the US, FERC Order 2023 and state-level renewable portfolio standards are restructuring interconnection queues, directly influencing cable procurement timelines and technical specifications. Stakeholders must monitor regulatory divergence across these jurisdictions, as compliance fragmentation threatens to segment supply chains and inflate qualification costs for manufacturers serving multiple markets.
Market Dynamics
Offshore wind developers are consolidating procurement around vertically integrated cable suppliers capable of delivering factory-to-termination project control, compressing margins for pure manufacturing competitors.
Growth Catalysts
- EU F-Gas Regulation:Mandated fluorinated gas phase-downs in cable insulation are accelerating replacement cycles across European grid infrastructure and offshore wind connections.
- Ultra-high-voltage transmission:China's MIIT directives and GB standards enforcement are driving capital deployment into 800 kV and 1000 kV land and submarine corridors.
- Offshore wind farm expansion:Developers in the North Sea and Baltic are procuring high-capacity submarine cables for grid connection, creating sustained demand for qualified installation fleets.
Market Restraints
- Copper price volatility:Raw material cost swings compress margin visibility for manufacturers locked into fixed-price project contracts with 18-36 month delivery horizons.
- Supplier concentration:Qualified high-voltage submarine cable production concentrates among three European and two Asian manufacturers, creating allocation risk during demand surges.
- XLPE technical ceiling:Cross-linked polyethylene insulation faces thermal and voltage limits above 500 kV that constrain underground transmission economics versus overhead alternatives.
Strategic Opportunities
- US interconnection reform:FERC Order 2023 restructuring of transmission queues creates procurement acceleration for high-voltage cables serving renewable portfolio standard compliance.
- Superconducting cable deployment:Convergence of high-temperature superconducting materials with liquid nitrogen cooling systems enables urban retrofit applications with 5-10x capacity density.
- Life-extension services:Aging submarine cable infrastructure in the North Sea creates aftermarket revenue pools for condition monitoring and repair vessel deployment.
Industry Challenges
- Submarine installation vessel scarcity:Qualified cable-laying ships with dynamic positioning and burial capability face 24-36 month booking backlogs, constraining project execution velocity.
- Type certification timelines:IEC 62895 and CIGRE TB 623 qualification protocols for 525 kV HVDC systems require 3-5 year testing cycles, delaying revenue recognition for new product introductions.
- Cross-jurisdictional compliance fragmentation:Divergent insulation compound approvals between EU REACH, US EPA, and China GB standards inflate qualification costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Cable Market |
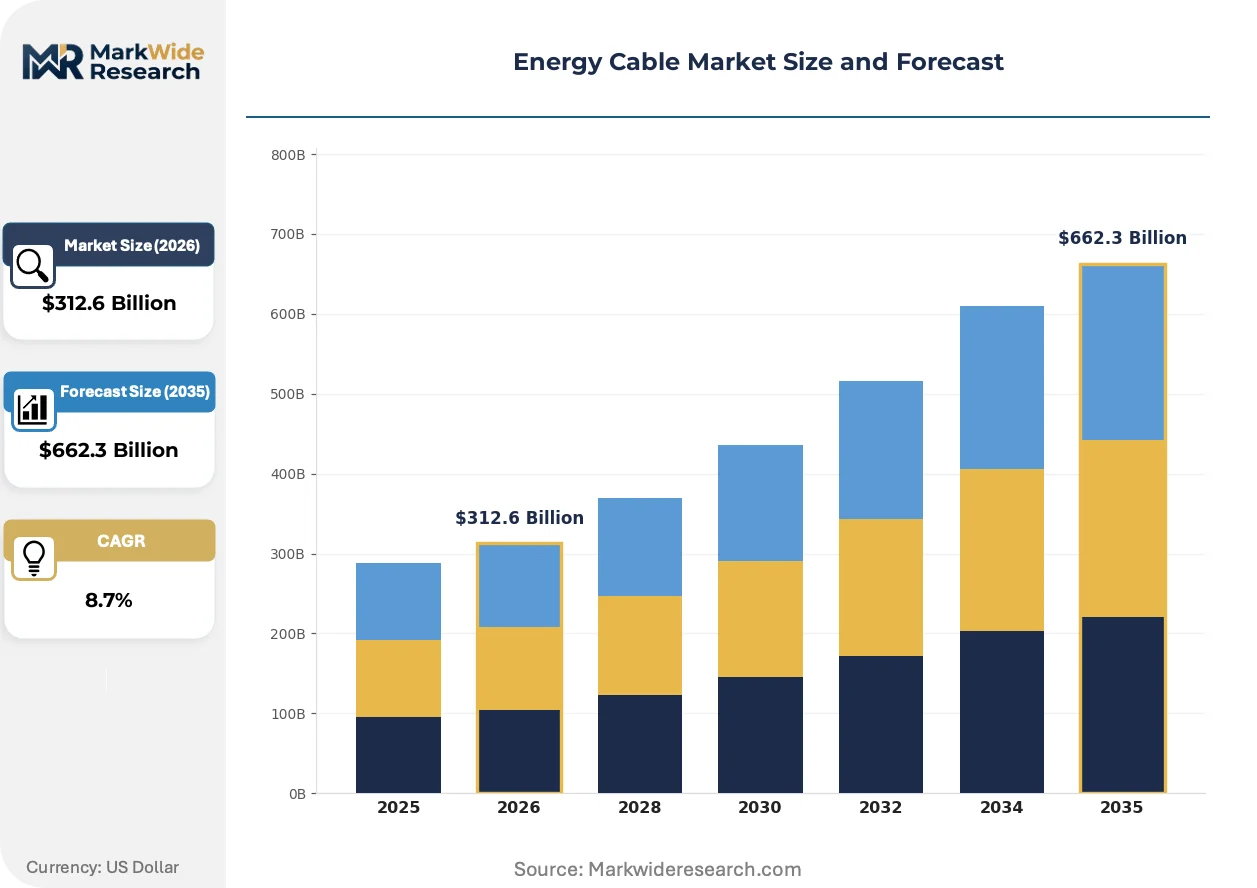
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Material: Copper, Aluminum, Fiber Optic, Polyethylene Installation: Underground, Overhead, Submarine, Aerial End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Sumitomo Electric Industries, LS Cable & System, Furukawa Electric, NKT, Fujikura, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Cable Market Emerging Trajectories
Digitalization of cable system monitoring and predictive maintenance is reshaping competitive differentiation, while regulatory chemistry mandates and procurement consolidation are restructuring supply relationships.
Dynamic temperature rating systems embedded with distributed fiber-optic sensing are digitizing transmission asset management. Grid operators in Germany and the UK are deploying these systems on 400 kV underground circuits to extract 15-30% additional ampacity from existing corridors. Real-time thermal monitoring is digitizing maintenance scheduling and extending cable economic life beyond original design assumptions.
The EU F-Gas Regulation's phased reduction of SF6 and fluorinated insulation gases is forcing compound reformulation across European cable manufacturing. ECHA restrictions on per- and polyfluoroalkyl substances are accelerating R&D into bio-based and mineral-filled insulation alternatives. High-voltage submarine cable suppliers serving North Sea offshore wind are responding with accelerated qualification timelines for gas-free insulation systems.
Utility procurement departments are consolidating vendor relationships around integrated EPC-service bundles that internalize installation risk. European transmission system operators are displacing component-only purchasing with 20-25 year service contracts encompassing cable, installation, and marine maintenance. This concentration is most visible in German and Danish offshore wind auctions where developers pre-qualify only vertically integrated cable system providers.
Energy Cable Market Segmentation
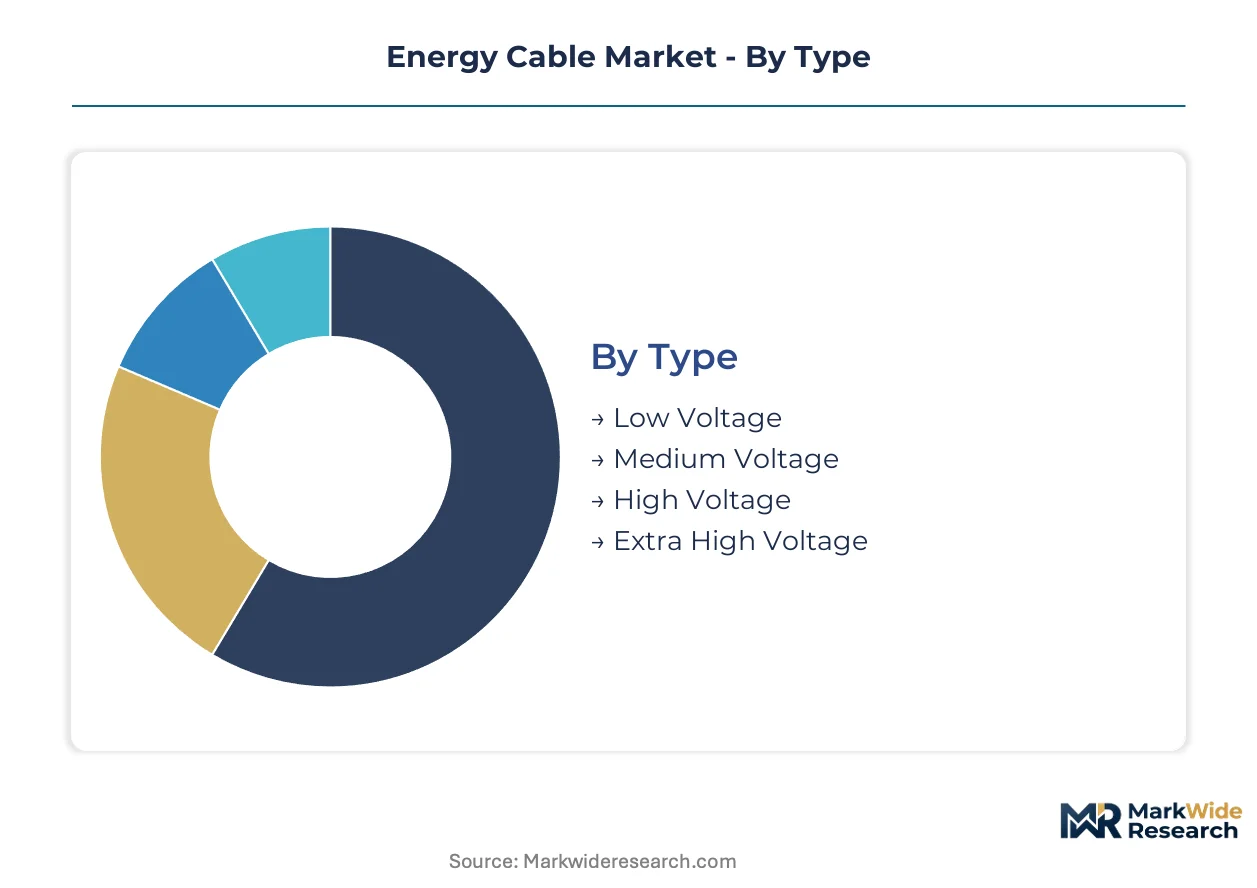
Segmentation in the energy cable market reveals divergent margin structures and replacement cycles. Voltage tier and installation environment determine project qualification requirements, raw material exposure, and supplier competitive position.
Type:
Replacement cycles stretch from 5-7 years for building wire to 40+ years for submarine transmission, creating fundamentally different revenue recognition patterns across voltage tiers.
- Low Voltage:Building wire and distribution cables rated below 1 kV utilize PVC or XLPE insulation over stranded copper conductors. Demand concentrates in residential construction and commercial retrofit across Germany, France, and Italy where building energy codes accelerate replacement of aging installations.
- Medium Voltage:Distribution cables from 1 kV to 35 kV serve urban grid densification and industrial park connections. Chinese state grid procurement and US utility undergrounding programs drive volume concentration, though margin pools have compressed toward commodity levels.
- High Voltage:Transmission cables from 35 kV to 230 kV enable inter-regional power corridors and renewable integration. European TSOs in Germany and Spain are procuring for offshore wind grid connections.
- Extra High Voltage:Land and submarine systems above 230 kV, including 525 kV HVDC, require decade-long qualification cycles and dedicated installation fleets. China's 800 kV and 1000 kV ultra-high-voltage corridors dominate capital deployment.
Low voltage dominates installed base. Extra high voltage is where expansion concentrates.
Material:
Raw material selection determines conductivity performance, weight economics, and regulatory compliance exposure across transmission and distribution applications.
- Copper:Oxygen-free high-conductivity copper dominates submarine and high-voltage underground installations where ampacity density justifies cost premiums. North Sea offshore wind developers specify copper for dynamic export cables.
- Aluminum:Lightweight conductivity solution for overhead transmission and aerial distribution where span length and tower loading drive economics. US utility procurement increasingly specifies aluminum for long-distance renewable interconnection.
- Fiber Optic:Composite power-communication cables integrate optical fibers for grid monitoring and control signaling. German and UK grid operators deploy these on 400 kV circuits for real-time thermal rating.
- Polyethylene:Cross-linked and thermoplastic polyethylene compounds provide moisture resistance and dielectric stability. ECHA restrictions on fluorinated additives are accelerating reformulation toward bio-based fillers.
Copper commands premium pricing in high-performance installations. Aluminum is gaining share fastest in cost-sensitive overhead applications.
Installation:
Installation environment dictates project complexity, equipment requirements, and the supplier base capable of execution.
- Underground:Direct-buried or duct-bank installations in urban corridors where overhead right-of-way is unavailable. German cities including Hamburg and Munich are mandating undergrounding for aesthetic and reliability reasons.
- Overhead:Aerial conductor systems on transmission towers for long-distance bulk power transfer. Rural China and the US Great Plains rely on overhead for cost-efficient renewable evacuation.
- Submarine:Subsea cable systems requiring specialized laying vessels and burial equipment. North Sea and Baltic offshore wind farms are procuring 220 kV and 525 kV export cables with 50+ kilometer lengths.
- Aerial:Self-supporting bundled cables for secondary distribution and rural electrification. India's rural electrification programs and Southeast Asian island connections deploy aerial for terrain accessibility.
Overhead retains the largest installed kilometer base. Submarine is climbing the fastest as offshore wind capacity expands.
End User:
Customer type determines procurement sophistication, contract structure, and service bundling requirements.
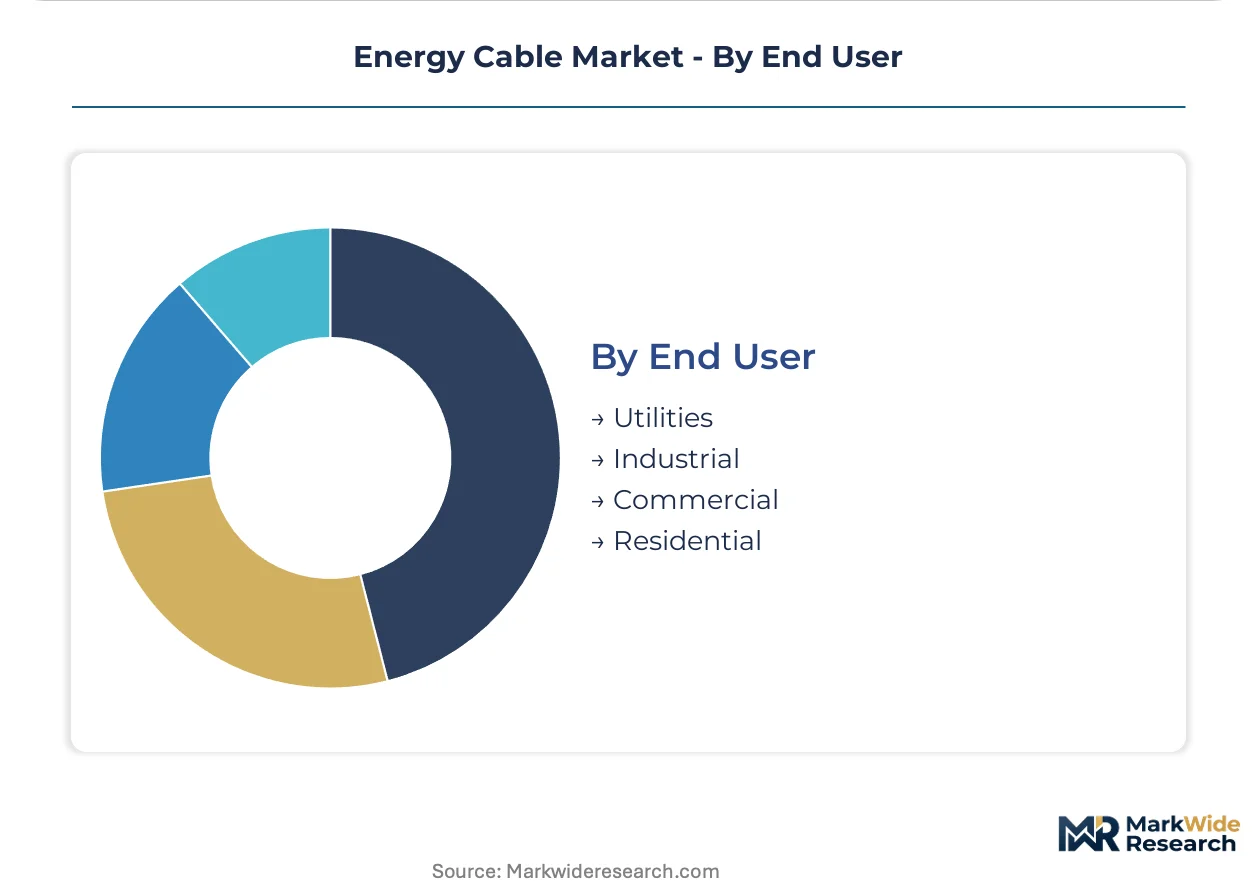
- Utilities:Transmission and distribution system operators procuring for grid reinforcement and renewable integration. China's State Grid and Southern Power Grid dominate capital deployment through ultra-high-voltage corridors.
- Industrial:Heavy manufacturing, mining, and petrochemical facilities requiring reliable medium-voltage supply. German automotive and chemical clusters specify high-availability cable systems with predictive monitoring.
- Commercial:Data centers, hospitals, and large retail complexes demanding redundant power infrastructure. Frankfurt and Amsterdam data center clusters are driving low-voltage and medium-voltage procurement.
- Residential:Single-family and multi-unit construction specifying building wire and service entrance cables. US housing starts and European building renovation rates set replacement demand.
Utilities dominate project value concentration. Commercial is where technology upgrade cycles are shortening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and the United States demonstrate low price elasticity for extra-high-voltage submarine systems, while European utilities and Indian distributors remain acutely sensitive to copper-driven cost swings in medium-voltage procurement.
China
State Grid Corporation and Southern Power Grid dominate ultra-high-voltage capital deployment across 800 kV and 1000 kV land corridors. MIIT directives enforce GB standards localization for transmission components, constraining non-domestic supplier participation. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing capacity for submarine cable exports.
United States
FERC Order 2023 restructuring of interconnection queues accelerates procurement timelines for renewable portfolio standard compliance. State-level mandates in California, Texas, and New York drive undergrounding programs and offshore wind grid connections. The PJM interconnection and ERCOT territory concentrate transmission reinforcement demand.
Germany
Transmission system operators TenneT and 50Hertz procure 525 kV HVDC submarine cables for North Sea offshore wind grid connections. The EU Green Deal and F-Gas Regulation mandate fluorinated gas phase-downs in cable insulation compounds. Hamburg and Munich enforce urban undergrounding mandates for aesthetic and reliability reasons.
United Kingdom
National Grid ESO and ScottishPower Renewables drive procurement for Celtic Sea and North Sea offshore wind export cables. Ofgem's RIIO price control framework shapes long-term service contract structures. Grimsby and Aberdeen harbor clusters concentrate installation vessel mobilization and cable storage facilities.
India
Power Grid Corporation and state electricity boards deploy medium-voltage aerial bundled cables for rural electrification under the Saubhagya scheme. Central Electricity Authority regulations enforce BIS certification for cross-linked polyethylene insulation. Gujarat and Maharashtra industrial corridors drive demand for high-availability cable systems in petrochemical and automotive clusters.
Energy Cable Market Vendor Landscape
Capability concentration sits with vertically integrated cable system providers controlling installation fleets and converter station integration; scale advantage sits with diversified industrial conglomerates leveraging compound manufacturing and regional procurement relationships. The market structures around three tiers: submarine specialists with marine assets, integrated power equipment providers with HVDC converter capabilities, and regional manufacturers serving utility replacement cycles. Dominant competitive moves include backward integration into compound manufacturing and long-term service contract bundling that internalizes installation and maintenance risk.
Within the submarine specialist tier, Prysmian Group and Nexans exemplify the vertically integrated archetype combining manufacturing with installation fleet control. Sumitomo Electric Industries occupies a position among Asia-Pacific industrial conglomerates with captive superconducting and high-temperature cable research pipelines. These three anchors represent the limited supplier base capable of delivering qualified 525 kV HVDC systems with factory-to-termination project accountability.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries |
| LS Cable & System |
| Furukawa Electric |
| NKT |
| Fujikura |
| ABB |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster concentrates XLPE compound production and copper conductor drawing capacity, translating upstream scale into pricing leverage for qualified submarine cable suppliers serving European offshore wind developers. Contract structures reward factory-to-termination project control with margin premiums unavailable to pure manufacturing competitors.
Pricing Analysis
Long-term service contracts spanning 20-25 years dominate extra-high-voltage procurement, displacing component-only purchasing as European transmission system operators internalize installation and maintenance risk. Price differentiation rests on IEC 62895 certification status and captive installation fleet availability, with qualified suppliers commanding substantial premiums over commodity manufacturers. Pricing pressure intensifies in low-voltage building wire as Chinese state-backed capacity expansion floods export markets. Industrial buyers in German automotive clusters demonstrate lowest price sensitivity, prioritizing predictive monitoring integration over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for XLPE insulation compound suppliers qualifying gas-free formulations under ECHA restrictions. Manufacturing gravity centers on China, Germany, and Italy for high-voltage systems, with South Korea and Japan anchoring superconducting cable R&D pipelines. Raw material dependencies draw from Chilean copper concentrate, Saudi petrochemical feedstock for polyethylene, and rare earth elements for high-temperature superconducting tapes. Distribution runs through vertically integrated EPC-service bundles that internalize marine installation risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Life-extension services for aging North Sea submarine infrastructure expand faster than hardware replacement cycles, creating recurring revenue pools that alter competitive economics. Service-attach penetration now determines supplier viability across European offshore wind auctions.
For Market Incumbents: Insulate margin pools by accelerating backward integration into compound manufacturing and securing 36-month installation vessel charters before competitor booking. Prysmian Group's fleet control model demonstrates how captive marine assets neutralize pure-manufacturer price aggression. ECHA fluorinated gas phase-downs threaten non-compliant inventory obsolescence; qualification investment for bio-based insulation alternatives is the essential defensive lever. For New Entrants and Emerging Players: Mid-market commercial data centers in Frankfurt and Amsterdam represent the most penetrable entry point for predictive monitoring-enabled cable systems, where technology upgrade cycles compress faster than utility procurement. US interconnection reform under FERC Order 2023 accelerates procurement timelines for renewable portfolio standard compliance, creating service-bundling opportunities without decade-long qualification barriers. Target predictive maintenance software partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant submarine cable capabilities and stranded installation vessel assets. Long-term viability hinges on 5-10 year offshore wind deployment trajectories in the North Sea and Baltic. Watch German and Danish auction pre-qualification lists as the inflection signal: developer consolidation around vertically integrated providers indicates acquisition premium compression for pure manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Installation Fleet Chartering | 24-36 month vessel booking backlogs under FERC Order 2023 acceleration reward early commitment. |
| Gas-Free Insulation Qualification | ECHA fluorinated gas restrictions invalidate legacy compound inventories without reformulation investment. |
| Predictive Monitoring Integration | German grid operators deploy distributed fiber-optic sensing to extract 15-30% additional ampacity. |
| Backward Integration into Compounds | Nexans' captive XLPE manufacturing demonstrates margin defense against copper volatility. |
| Long-Term Service Contract Bundling | European TSOs displace component purchasing with 20-25 year installation-maintenance agreements. |
Methodological Framework
A standing panel of submarine cable project managers, EPC contractor procurement leads, transmission system operator planning officers, and offshore wind developer grid connection specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from IEC 62895 certification databases, FERC interconnection queue filings, ECHA substance restriction updates, and customs trade data for copper conductor and XLPE compound flows. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure disclosures.
Scenario-bracketing anchored the analytical framework across the projection horizon, with demand trajectories tested against offshore wind auction award volumes and ultra-high-voltage corridor commissioning schedules. Segmentation dimensions modeled encompassed voltage tier, installation environment, conductor material, and regional regulatory cluster. CAGRs derived from unit economics analysis of representative project archetypes, incorporating copper price sensitivity bands and vessel day-rate assumptions without year-specific anchoring.
Practitioners should monitor ECHA substance restriction timelines, FERC interconnection queue restructuring implementation, and Chinese MIIT localization enforcement for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market