
 Saudi Arabia Drilling Services Market | 2026-2036
Saudi Arabia Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Drilling Services Market Analytics
Market Context
Procurement channels between national oil companies and international service contractors is fragmenting as localization mandates reshape vendor qualification. Arabian Drilling Company leverages its captive position with Saudi Aramco to sustain long-term rig supply contracts across onshore and offshore programs. Schlumberger PLC anchors deepwater technical capabilities while competing for high-specification automated drilling packages in the Red Sea. Halliburton Company differentiates through integrated well completion and directional drilling portfolios tailored to carbonate reservoir complexity.
Technical Definition and Segment Structure
Saudi Arabia drilling services encompass the engineered execution of borehole construction for hydrocarbon extraction, utilizing rotary table or top-drive systems capable of generating torque exceeding 50,000 ft-lbs and managing downhole pressures in formations exceeding 300°F. These services enable exploration access, production well delivery, and reservoir stimulation across carbonate and sandstone targets at depths ranging from 5,000 to 20,000 feet. Directional drilling and managed pressure drilling command premium margins as operators navigate high-pressure sour gas zones and extended-reach laterals in the Jafurah unconventional field. Digital rig technology and advanced LWD systems represent the fastest-expanding technology categories as real-time downhole data reduces non-productive time in complex geologies.
Regulatory Environment and Outlook
SFDA environmental standards and the Saudi Arabian Oil Company's in-kingdom total value add requirements shape equipment sourcing, emissions protocols, and local workforce ratios for drilling contractors. The Ministry of Energy's dual carbon goals and SAMR technical standards further constrain rig import specifications while accelerating domestic manufacturing partnerships. Stakeholders must monitor how localization thresholds and carbon intensity benchmarks reshape contractor eligibility and capital deployment priorities across the Kingdom's drilling programs.
Market Dynamics
SFDA environmental compliance protocols and Saudi Aramco's in-kingdom total value add program are restructuring vendor qualification criteria and redirecting capital deployment toward localized drilling capabilities across the Kingdom's unconventional frontiers.
Growth Catalysts
- Jafurah Unconventional Gas Development:Saudi Aramco's expansion of tight gas extraction in the Empty Quarter is generating demand for managed pressure drilling and extended-reach lateral capabilities.
- SFDA Emissions Protocols:The environmental regulator's tightening of flaring restrictions and waste management standards is accelerating rig fleet modernization toward automated, low-emission systems.
- Red Sea Deepwater Exploration:Offshore licensing rounds in previously untapped carbonate reservoirs are pulling high-specification jackup and semi-submersible rig deployments.
Market Restraints
- Specialized Steel Alloy Supply:Drill string and casing procurement depends on concentrated Japanese and German metallurgical suppliers, exposing contractors to input cost volatility and delivery delays.
- IKTV Localization Thresholds:Saudi Aramco's escalating local content requirements create structural barriers for international contractors lacking established Saudi manufacturing partnerships or joint ventures.
- High-Pressure Sour Gas Technical Limits:Hydrogen sulfide concentrations exceeding 10% in Khurais and Manifa fields constrain standard metallurgy and require premium corrosion-resistant alloys that extend procurement cycles.
Strategic Opportunities
- Empty Quarter Frontier Basins:Underexplored Paleozoic sandstone targets along the Rub al Khali margins offer first-mover positioning for integrated drilling and completion service packages.
- Digital Rig-Analytics Convergence:Real-time LWD data streams fused with predictive maintenance algorithms are creating new performance-based contract structures that tie contractor compensation to non-productive time reduction.
- Ministry of Energy Dual Carbon Mandate:The national net-zero 2060 commitment is channeling R&D investment toward electrified rig power systems and carbon capture-ready well construction methodologies.
Industry Challenges
- Directional Drilling Specialist Shortage:The Kingdom's technical institutes are producing insufficient geosteering engineers and MPD technicians to staff accelerated unconventional drilling programs.
- SFDA Certification Timelines:Environmental compliance verification for imported drilling fluids and cementing additives extends procurement cycles by four to six months, compressing project windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Drilling Services Market |
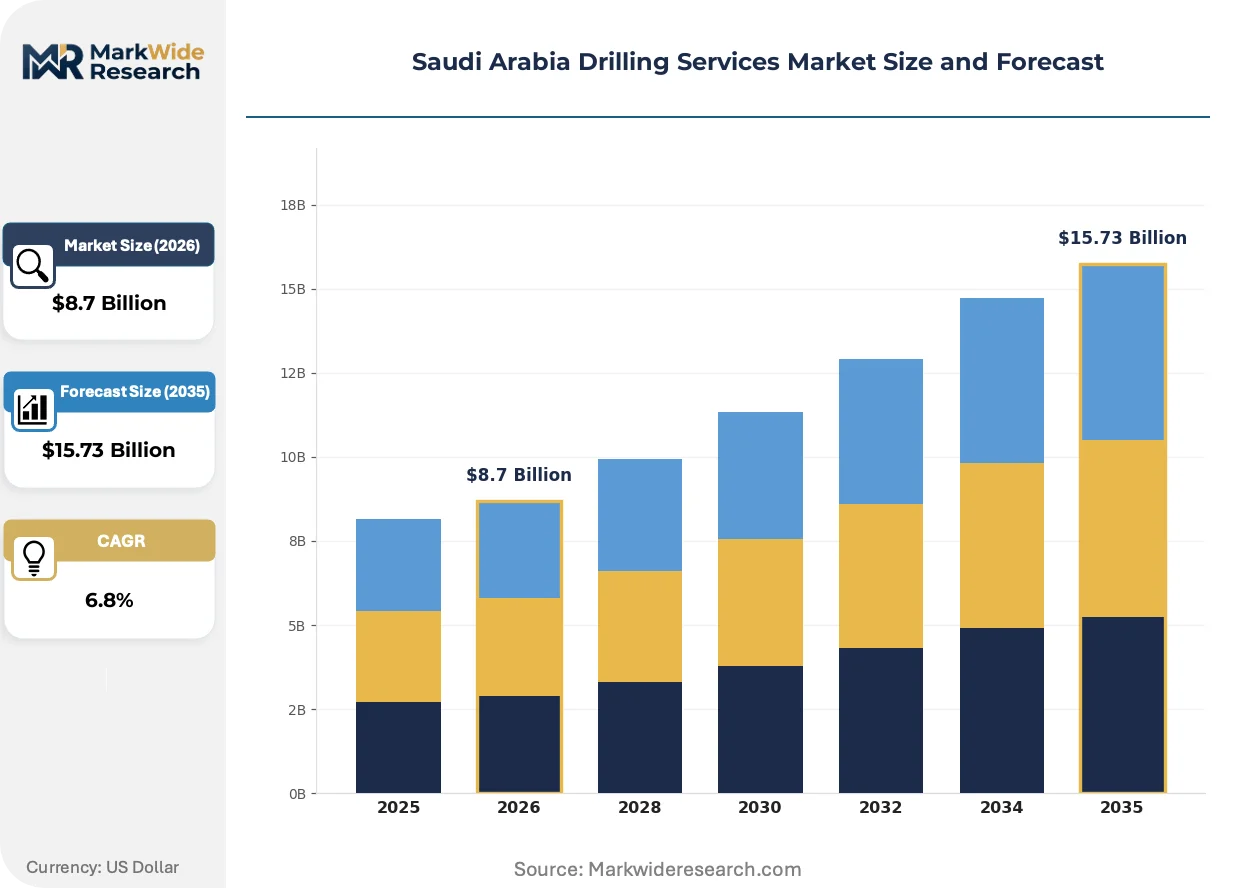
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rotary Drilling, Directional Drilling, Managed Pressure Drilling, Offshore Drilling End User: Oil and Gas Companies, Government Entities, Independent Operators, Service Providers Technology: Automated Drilling Systems, Conventional Drilling, Advanced LWD, Digital Rig Technology Application: Onshore Exploration, Offshore Exploration, Well Completion, Enhanced Oil Recovery |
| Companies Covered | Weatherford International PLC, Arabian Drilling Company, Schlumberger PLC, National Oilwell Varco Inc., ADES International Holding PLC, Halliburton Company, Nabors Industries Ltd, Saudi Arabian Oil Company, Baker Hughes Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Drilling Services Market Evolving Landscape
Automation and real-time subsurface analytics are displacing conventional rig operating models across Saudi Arabia's high-pressure, high-temperature drilling environments, compressing decision cycles and redefining contractor value propositions.
Managed pressure drilling systems are hybridizing conventional pressure control with automated choke manipulation and continuous annular pressure monitoring. Saudi Aramco's unconventional gas divisions are deploying these packages across Jafurah laterals at accelerating frequency. The technology is hybridizing well construction economics by enabling narrower pressure windows and reducing lost circulation events in fractured carbonate formations.
SFDA's updated environmental standards for drilling waste management and produced water handling are mandating closed-loop mud systems and zero-discharge protocols at onshore locations. These regulations are forcing rig fleet retrofits and specialized solids control equipment investments. Offshore operators in the Arabian Gulf are responding fastest, integrating cuttings reinjection and thermal desorption units to maintain operating permits.
Performance-based contracting is displacing traditional day-rate structures in Saudi Aramco tender evaluations. Integrated drilling contractors are accepting risk transfer for non-productive time and well delivery speed in exchange for upside participation. This shift is most visible in the Eastern Province shale gas pilot programs, where footage-based and flat-fee arrangements now dominate high-specification rig procurement.
Saudi Arabia Drilling Services Market Segmentation
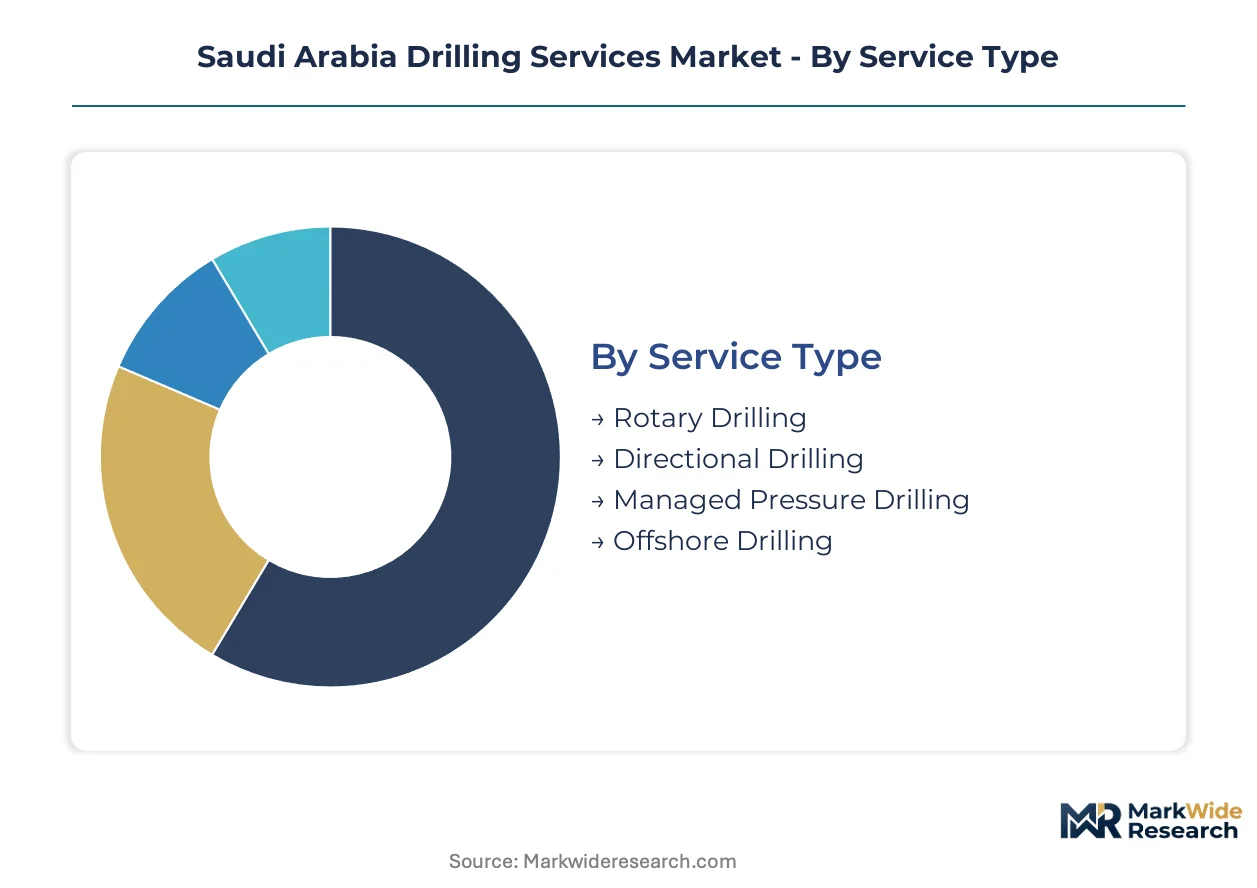
Segmentation in Saudi Arabia's drilling services market reveals how procurement criteria diverge across technical complexity, regulatory exposure, and localization mandates. Understanding these fault lines exposes where contractor margins concentrate and where qualification barriers reshape competitive access.
Service Type:
Cost tier differentiation across service categories separates commodity execution from premium technical capabilities requiring specialized equipment and certified personnel.
- Rotary Drilling:Conventional top-drive and rotary table systems dominate onshore development drilling across Ghawar and Khurais fields. SFDA emissions protocols are accelerating fleet replacement toward automated, low-emission configurations in the Eastern Province.
- Directional Drilling:Geosteering and horizontal lateral construction enable extended-reach wells in Jafurah unconventional targets. Technical institutes in the Kingdom produce insufficient specialist engineers, constraining deployment velocity for Saudi Aramco's tight gas programs.
- Managed Pressure Drilling:Closed-loop pressure control for narrow-margin formations.
- Offshore Drilling:Jackup and semi-submersible operations in Red Sea and Arabian Gulf licensing blocks.
Rotary drilling commands the established base. The steepest expansion runs through managed pressure drilling.
End User:
Customer type determines contract structure, risk allocation, and localization compliance intensity across the Kingdom's drilling procurement landscape.
- Oil and Gas Companies:Saudi Aramco dominates rig demand through long-term supply agreements and integrated drilling tenders. The operator's in-kingdom total value add program redirects awards toward contractors meeting escalating local content thresholds.
- Government Entities:Ministry of Energy and industrial development authorities fund frontier exploration in Rub al Khali margins. Procurement emphasizes technology transfer and domestic workforce development over pure cost minimization.
- Independent Operators:Niche players in marginal field redevelopment.
- Service Providers:Subcontractors to integrated drilling contractors.
Oil and gas companies anchor procurement volume. Government entities are expanding fastest as frontier basin exploration accelerates.
Technology:
Technology maturity curves separate legacy rig infrastructure from digitally integrated systems commanding performance-based contract premiums.
- Automated Drilling Systems:Robotic pipe handling and autonomous rig floor operations reduce crew exposure and non-productive time. Red Sea deepwater programs are pulling high-specification automated packages as operators navigate HPHT carbonate complexity.
- Digital Rig Technology:Real-time data acquisition, predictive maintenance algorithms, and remote operations centers redefine contractor value propositions. Saudi Aramco's unconventional divisions are piloting performance-based contracts tying compensation to drilling efficiency metrics.
- Advanced LWD:Logging-while-drilling sensors for formation evaluation.
- Conventional Drilling:Legacy mechanical systems in mature field redevelopment.
Conventional drilling retains the installed base. Digital rig technology is climbing the fastest as real-time analytics compress decision cycles.
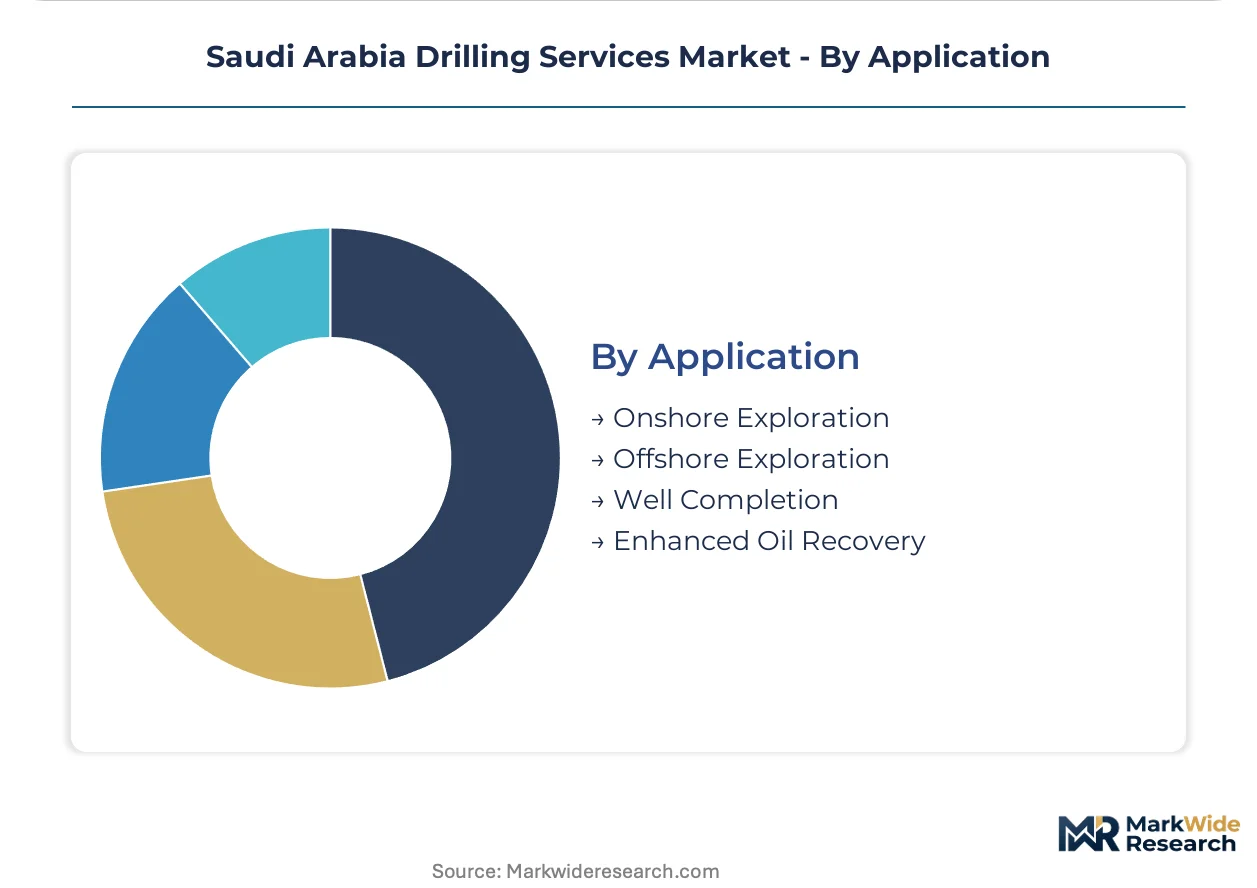
Application:
Application focus determines pressure regime exposure, environmental compliance intensity, and equipment specification requirements across Saudi Arabia's diverse basins.
- Onshore Exploration:Wildcat drilling in Paleozoic sandstone targets across Empty Quarter frontiers requires mobile desert-rated rigs and self-contained logistics. SFDA zero-discharge mandates are forcing closed-loop mud system investments at Rub al Khali locations.
- Well Completion:Casing installation, cementing, and perforation operations finalize well construction for production. Khurais and Manifa high-pressure sour gas fields demand premium corrosion-resistant alloys that extend procurement cycles and elevate material costs.
- Offshore Exploration:Frontier drilling in Red Sea carbonate plays.
- Enhanced Oil Recovery:Infill drilling and injector well conversion for mature reservoirs.
Onshore exploration holds the dominant position. Well completion is gaining share fastest as unconventional gas development intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Eastern Province's Dhahran cluster while frontier basins in the Empty Quarter absorb capital at compressed margins. The Kingdom's drilling demand geography splits between mature supergiant fields and unconventional gas frontiers.
Eastern Province
Ghawar and Khurais field redevelopment drives sustained rotary rig demand for infill drilling and water injection wells. SFDA emissions protocols are accelerating fleet replacement toward automated, low-emission configurations at Dhahran-based contractor yards. The Dammam-Khobar industrial corridor hosts the densest concentration of drilling service facilities and technical training centers.
Empty Quarter
Jafurah unconventional gas development is pulling managed pressure drilling and extended-reach lateral capabilities into the Rub al Khali margins. Saudi Aramco's in-kingdom total value add program redirects awards toward contractors with established Saudi manufacturing partnerships. Mobile desert-rated rigs with self-contained logistics operate under SFDA zero-discharge mandates at remote Paleozoic sandstone targets.
Western Region
Red Sea deepwater exploration is generating demand for high-specification jackup and semi-submersible rig deployments in previously untapped carbonate reservoirs. The Ministry of Energy's licensing rounds are pulling international contractors toward Jeddah-based supply chain nodes. HPHT well complexity is accelerating automated drilling package procurement for frontier drilling programs.
Riyadh
Administrative and procurement functions for national drilling programs concentrate in the capital's energy ministry and Saudi Aramco headquarters. Government-funded frontier exploration in Rub al Khali margins emphasizes technology transfer and domestic workforce development. Riyadh-based technical institutes are struggling to produce sufficient geosteering engineers for accelerated unconventional programs.
NEOM Northwest
The giga-project's industrial city development is creating parallel demand for construction drilling and geotechnical services alongside hydrocarbon exploration. Dual carbon mandate requirements are channeling R&D investment toward electrified rig power systems in the zone. NEOM's regulatory sandbox is piloting carbon capture-ready well construction methodologies for future deployment.
Saudi Arabia Drilling Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly, supplying drill string metallurgy and downhole telemetry. The vendor base organizes around three strategic archetypes: national champions with captive NOC relationships, international majors with deepwater technical capabilities, and regional specialists with desert operations expertise. Competitive moves concentrate on localization joint ventures and performance-based contract structures.
Within the national champion tier, Arabian Drilling Company occupies a position exemplifying captive rig supply relationships with Saudi Aramco. Among international majors, Schlumberger PLC and Halliburton Company represent the deepwater technical capability archetype, anchoring high-specification automated drilling packages for Red Sea and Arabian Gulf programs. These three entities exemplify how vendor qualification is fragmenting under SFDA environmental compliance and in-kingdom total value add thresholds.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Arabian Drilling Company |
| Schlumberger PLC |
| National Oilwell Varco Inc. |
| ADES International Holding PLC |
| Halliburton Company |
| Nabors Industries Ltd |
| Saudi Arabian Oil Company |
| Baker Hughes Co |
| Others |
Value Network & Pricing Analysis
Dhahran's contractor yard concentration in the Eastern Province concentrates automated rig fleet capacity, translating upstream equipment scarcity into sustained pricing leverage for high-specification drilling packages across Saudi Aramco's tender evaluations. SFDA emissions mandates and in-kingdom total value add thresholds compound this dynamic by restricting qualified supplier pools while elevating compliance premiums for localized service delivery.
Pricing Analysis
Configured-to-order pricing for managed pressure drilling and automated rig systems commands spreads exceeding standard rotary drilling rates by substantial margins, reflecting engineering customization for HPHT sour gas applications. Three-tier pricing structure across premium, standard, and economy levels separates automated digital rigs with predictive analytics from conventional mechanical fleets and bare-bones desert-rated units. Cost compression in standard rotary tiers is intensifying because Arabian Drilling Company's captive Saudi Aramco relationships limit competitive pricing latitude for international contractors. Independent operators in marginal field redevelopment exhibit highest price sensitivity, while unconventional gas divisions prioritize technical performance over rate minimization.
Supply Chain Analysis
Extended payment terms from national oil companies and supply-chain finance facilities strain working capital for drilling contractors navigating multi-month SFDA certification cycles. Specialized steel alloy supply draws from concentrated Japanese and German metallurgical sources, exposing drill string and casing procurement to input cost volatility and delivery delays. Premium corrosion-resistant alloys for Khurais and Manifa sour gas fields, automated rig control systems, and closed-loop mud handling equipment constitute critical component dependencies. Single-source vulnerability in high-grade metallurgy represents the dominant structural risk. Distribution runs through Dammam-Khobar industrial corridor hubs serving Eastern Province field operations, with Jeddah nodes emerging for Red Sea deepwater programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's drilling services market fragments across localization mandates, technical specialization tiers, and frontier basin geography, creating discrete entry niches for differentiated capabilities. SFDA environmental compliance and in-kingdom total value add thresholds displace incumbent advantages while elevating domestic partnership requirements.
For Market Incumbents: Entrench through backward integration into Saudi-based manufacturing joint ventures that satisfy escalating local content thresholds, while anchoring automated rig fleets with predictive maintenance capabilities to defend against technology substitution. Arabian Drilling Company's captive position demonstrates how Saudi Aramco relationship depth creates structural barriers for challengers lacking equivalent localization infrastructure. For New Entrants and Emerging Players: Pursue Empty Quarter frontier basin positioning through integrated drilling-completion packages targeting Paleozoic sandstone wildcat programs where established contractor density remains lowest. Mobile desert-rated rig capabilities with self-contained logistics offer the most penetrable wedge, with performance-based contract structures providing differentiated go-to-market access against day-rate incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a localization infrastructure play because in-kingdom total value add thresholds will continue escalating through the analysis window, rewarding capital deployed into Saudi manufacturing partnerships and technical training capabilities. Acquisition targets should emphasize contractors with established SFDA certification track records and Saudi workforce ratios exceeding current minima. The signal to watch is Saudi Aramco tender language evolution toward explicit local content weighting in technical evaluation matrices.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Joint Venture Formation | Satisfies in-kingdom total value add thresholds for Saudi Aramco tender eligibility. |
| Automated Rig Fleet Modernization | Addresses SFDA emissions protocols while reducing non-productive time in HPHT formations. |
| Performance-Based Contract Structuring | Aligns contractor compensation with drilling efficiency metrics in unconventional gas programs. |
| Technical Institute Partnership | Secures geosteering engineer pipeline for accelerated Jafurah development staffing. |
| Closed-Loop Mud System Deployment | Meets SFDA zero-discharge mandates at Rub al Khali frontier locations. |
Research Methodology
The analysis maps rotary drilling, directional drilling, managed pressure drilling, and offshore drilling service categories, each validated through drilling operations managers, procurement officers at national oil companies, rig fleet directors, and environmental compliance specialists. Primary interviews with these stakeholders combined with secondary validation against Saudi Aramco tender documentation, SFDA regulatory filings, Ministry of Energy licensing round disclosures, and industrial development authority investment announcements. Bottom-up rig count and day-rate modeling triangulated against top-down market sizing from capital expenditure disclosures across the analysis window.
Assumptions held fixed include SFDA environmental compliance protocol stringency and Saudi Aramco in-kingdom total value add threshold escalation trajectory, while oil price volatility and unconventional gas production target revisions were treated as sensitivity variables. Segmentation dimensions modeled encompass service type, end user archetype, technology maturity tier, and application focus across the projection horizon. CAGRs were derived from equipment deployment velocity and contract award pacing rather than simple extrapolation, with specific inputs including rig fleet automation adoption curves and frontier basin licensing round timing.
Sensitivities concentrate around Ministry of Energy dual carbon mandate implementation pace and SFDA certification timeline compression for imported drilling fluids. Forecasts reflect these documented assumptions with acknowledged revision potential from geopolitical supply disruptions in specialized steel alloy sourcing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Desalter Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Wireline Services Market