
 North America Digital Oilfield Market | 2026-2036
North America Digital Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Oilfield Market Analytics
Asset-light leasing models for downhole sensor networks is narrowing the competitive field for mid-tier operators seeking real-time visibility. Schlumberger leverages its integrated drilling and evaluation portfolio to dominate high-complexity digital deployments. Baker Hughes sustains technology leadership through proprietary artificial lift optimization algorithms. Honeywell International anchors its position with process automation systems that extend across refinery and upstream boundaries.
Digital oilfield denotes the integration of information technology, operational technology, and advanced analytics to automate and optimize hydrocarbon exploration and production workflows, typically incorporating edge computing nodes that process data within 50 milliseconds of generation to enable closed-loop reservoir control. The primary purpose centers on maximizing recovery rates while minimizing operational expenditure and unplanned downtime across mature and unconventional assets. Artificial Intelligence applications within production optimization command the deepest margin pools as operators prioritize predictive maintenance over reactive interventions. Cloud Computing deployments in reservoir management represent the fastest-expanding segment as majors consolidate subsurface data lakes across multi-basin portfolios. IoT sensor networks for drilling operations remain structurally mature, with growth now coming from replacement cycles rather than greenfield installations.
The EPA enforces methane monitoring mandates under the Clean Air Act that compel operators to deploy continuous emissions detection systems, directly expanding addressable demand for connected field infrastructure. The Pipeline and Hazardous Materials Safety Administration imposes integrity management rules that require real-time pressure and flow telemetry, reinforcing standards-based procurement criteria. State regulators in Texas and New Mexico layer additional flaring and venting restrictions that shape product specifications for digital control systems. Stakeholders must weigh capital allocation between proprietary platform development and vendor-agnostic interoperability architectures as the next competitive fault line.
Market Dynamics
The EPA's methane emissions rules are compressing deployment timelines for continuous monitoring infrastructure across Permian Basin well sites. Operators now face binding compliance deadlines that favor integrated sensor-to-cloud architectures over point solutions.
Growth Catalysts
- Subsurface digital twin adoption:Permian operators deploy reservoir simulation models that integrate real-time production data to optimize completion designs and EUR forecasts.
- Clean Air Act enforcement:EPA mandates for continuous emissions monitoring create durable procurement pull for connected field infrastructure across upstream assets.
- Edge computing latency thresholds:50-millisecond closed-loop control requirements are driving hardware refreshes at well pads and central processing facilities.
Market Restraints
- Specialized engineering talent scarcity:Reservoir analytics and edge systems integration skills concentrate among a limited pool of experienced practitioners.
- Legacy SCADA replacement costs:Brownfield installations require expensive retrofitting to achieve interoperability with modern IoT sensor networks.
- Cybersecurity insurance premiums:Ransomware exposure at remote well sites is elevating coverage costs for mid-tier operators.
Strategic Opportunities
- Asset-light sensor leasing:Mid-tier Permian operators bypass capital constraints through subscription-based downhole monitoring deployments.
- New Mexico venting restrictions:State-level flaring rules are accelerating demand for automated choke control and gas capture optimization systems.
- Cloud-native reservoir data lakes:Majors consolidate multi-basin subsurface databases, creating vendor opportunity in migration and analytics services.
Industry Challenges
- Interoperability standard gaps:Proprietary vendor protocols complicate multi-source data integration at the wellhead.
- OT-IT convergence friction:Operational technology teams resist cloud-connected architectures due to uptime reliability concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Oilfield Market |
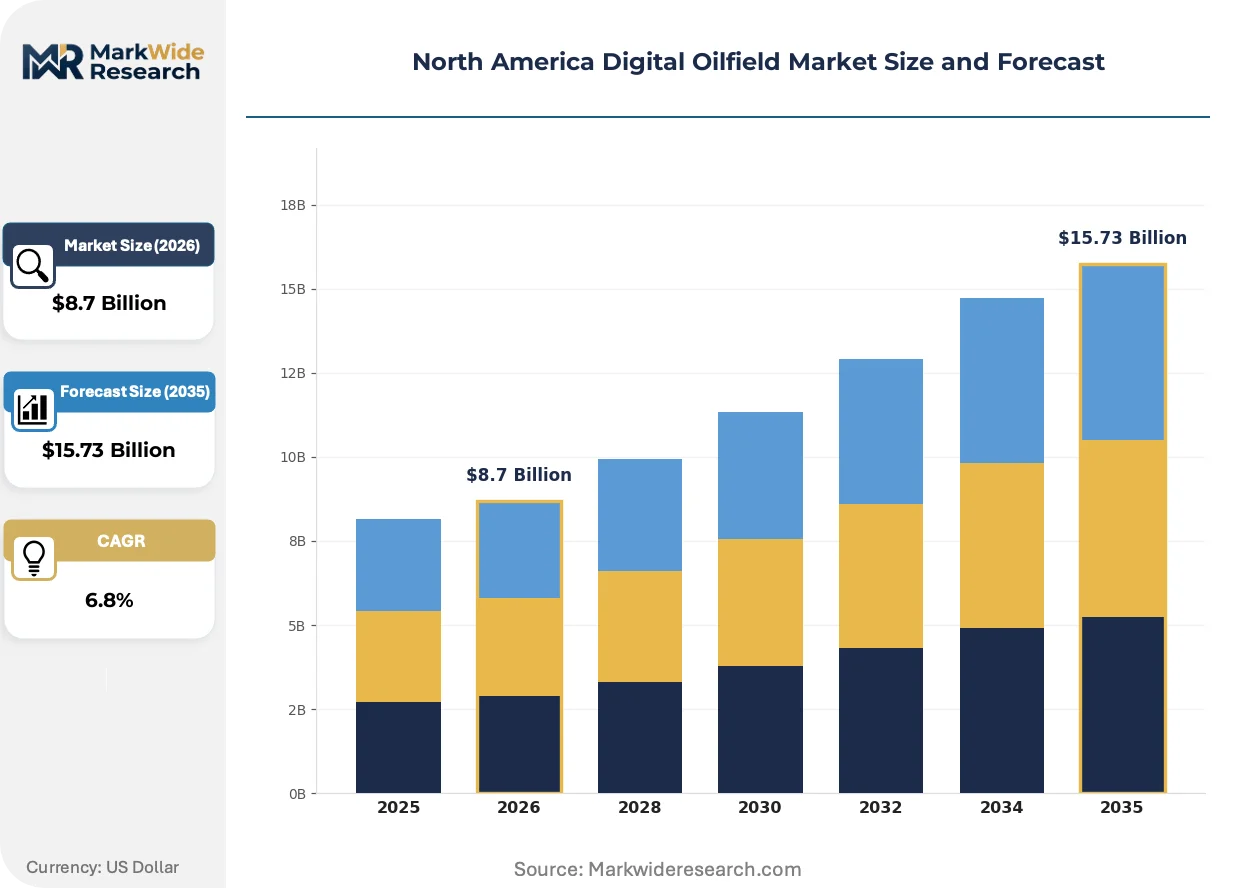
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Data Analytics, Cloud Computing, Artificial Intelligence Application: Reservoir Management, Production Optimization, Drilling Operations, Asset Management End User: Oil Producers, Service Providers, Equipment Manufacturers, Energy Consultants Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Remote Monitoring |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Emerson Electric, Weatherford, ABB, Honeywell International, NOV, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Oilfield Market Evolving Landscape
Real-time drilling analytics and automated reservoir control are compressing decision cycles from weeks to minutes across North American shale operations. Three distinct vectors are reshaping competitive positioning.
Edge-native processing architectures are collapsing the latency gap between sensor generation and actuation response. Permian drilling contractors now deploy sub-surface measurement-while-drilling systems that execute trajectory corrections without round-trip delays to surface facilities. This compression eliminates the historical trade-off between data richness and response speed.
EPA enforcement of methane monitoring mandates under the Clean Air Act is binding procurement specifications to continuous emissions detection standards. Operators must deploy optical gas imaging and sensor networks that transmit readings at 15-minute intervals or shorter. Texas and New Mexico regulators layer additional venting restrictions that shape control system requirements for digital vendors.
Leasing structures for downhole instrumentation are displacing capital purchase models among capital-constrained independents. Mid-tier Permian operators now contract sensor networks as operational expenditures with performance guarantees attached. This shift concentrates vendor risk on uptime delivery and compresses traditional hardware margins toward service annuity streams.
North America Digital Oilfield Market Segmentation
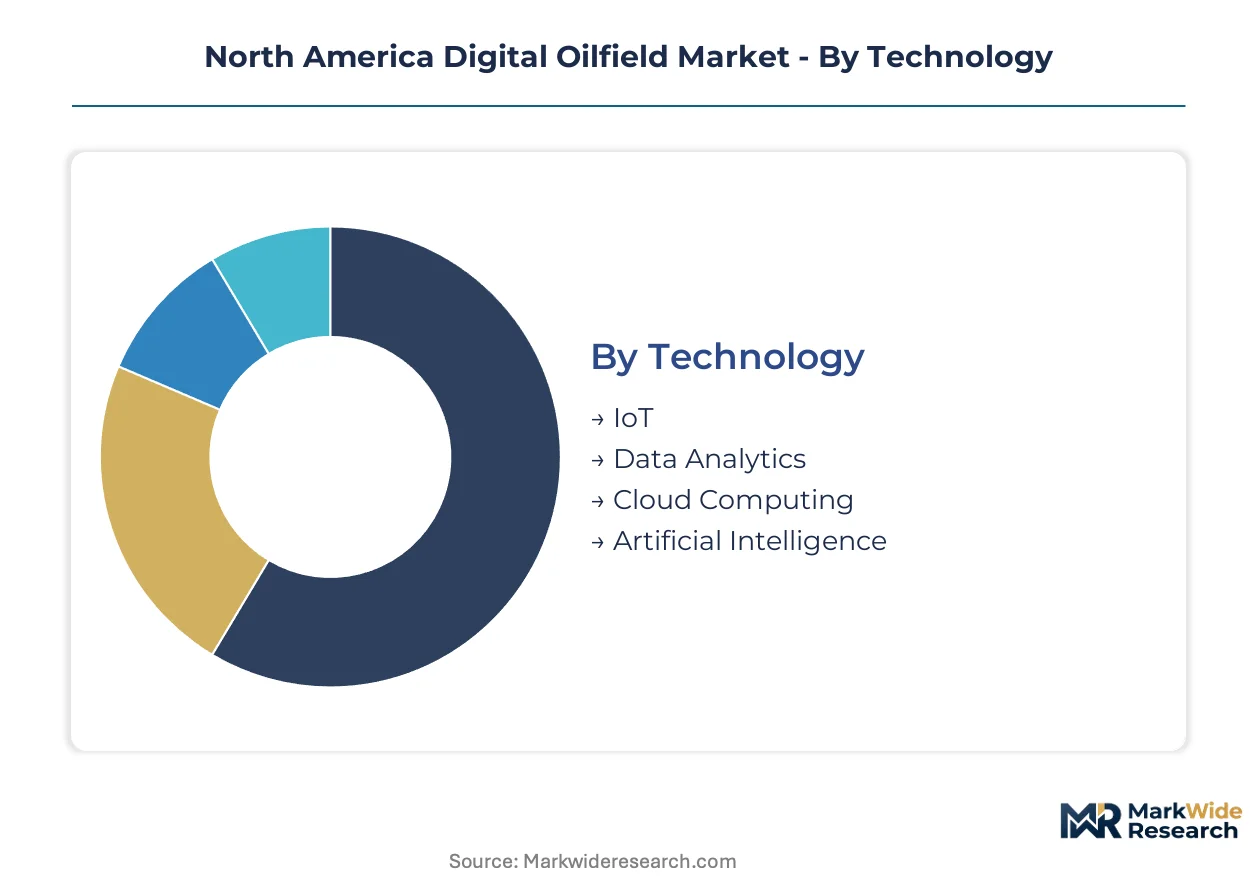
Segmentation reveals how capital cycles and compliance pressures distribute across the North America Digital Oilfield Market. Technology refresh rates vary dramatically between edge hardware and cloud platforms, while deployment models reflect operator maturity and risk tolerance.
Technology:
Replacement cycles compress fastest at the edge while enterprise software enjoys longer amortization periods.
- IoT:Sensor networks for wellhead pressure, temperature, and flow measurement operate on 5-7 year hardware lifecycles. Permian Basin operators are refreshing legacy SCADA endpoints to meet EPA methane monitoring mandates with 15-minute transmission intervals.
- Artificial Intelligence:Machine learning models for predictive maintenance and reservoir simulation require continuous retraining on production data. Majors deploy AI layers atop existing data infrastructure, avoiding wholesale platform replacement.
- Data Analytics:Real-time dashboards and historical trend analysis tools process streams from multiple sensor modalities.
- Cloud Computing:Reservoir data lakes and compute-intensive simulation workloads migrate to hosted environments.
IoT anchors the volume base while Artificial Intelligence gains share at the steepest rate.
Application:
Margin concentration follows operational criticality, with production-linked applications commanding premium pricing over planning tools.
- Production Optimization:Artificial lift control, choke automation, and gas capture systems deliver measurable barrel gains. Texas operators prioritize these deployments to minimize flaring penalties under state venting restrictions.
- Reservoir Management:Digital twin simulations integrate seismic, log, and production history to forecast EUR and guide infill drilling. Cloud-native platforms enable multi-basin portfolio analysis for majors with Permian and Bakken positions.
- Drilling Operations:Measurement-while-drilling and logging-while-drilling systems feed real-time trajectory corrections.
- Asset Management:Equipment health monitoring and spare parts logistics optimization reduce unplanned downtime.
Production Optimization commands the deepest margin pools while Reservoir Management expands most quickly as majors consolidate subsurface data lakes.
End User:
Procurement authority fragments across the value chain, with service providers acting as technology gatekeepers for capital-constrained independents.
- Oil Producers:Majors and independents with operated acreage in Texas and New Mexico specify integrated sensor-to-cloud architectures. These operators face direct EPA compliance liability and prioritize vendor consolidation.
- Service Providers:Drilling contractors and artificial lift specialists deploy owned digital infrastructure to differentiate performance-based contracts. Leasing models for downhole sensors concentrate vendor risk with this segment.
- Equipment Manufacturers:Pump, compressor, and valve OEMs embed connectivity as standard features.
- Energy Consultants:Reservoir engineering and data science boutiques deliver analytics as professional services.
Oil Producers anchor the volume base while Service Providers gain share at the steepest rate through performance-guaranteed leasing structures.
Deployment:
Operational technology teams resist full cloud migration due to uptime reliability concerns at remote well sites.
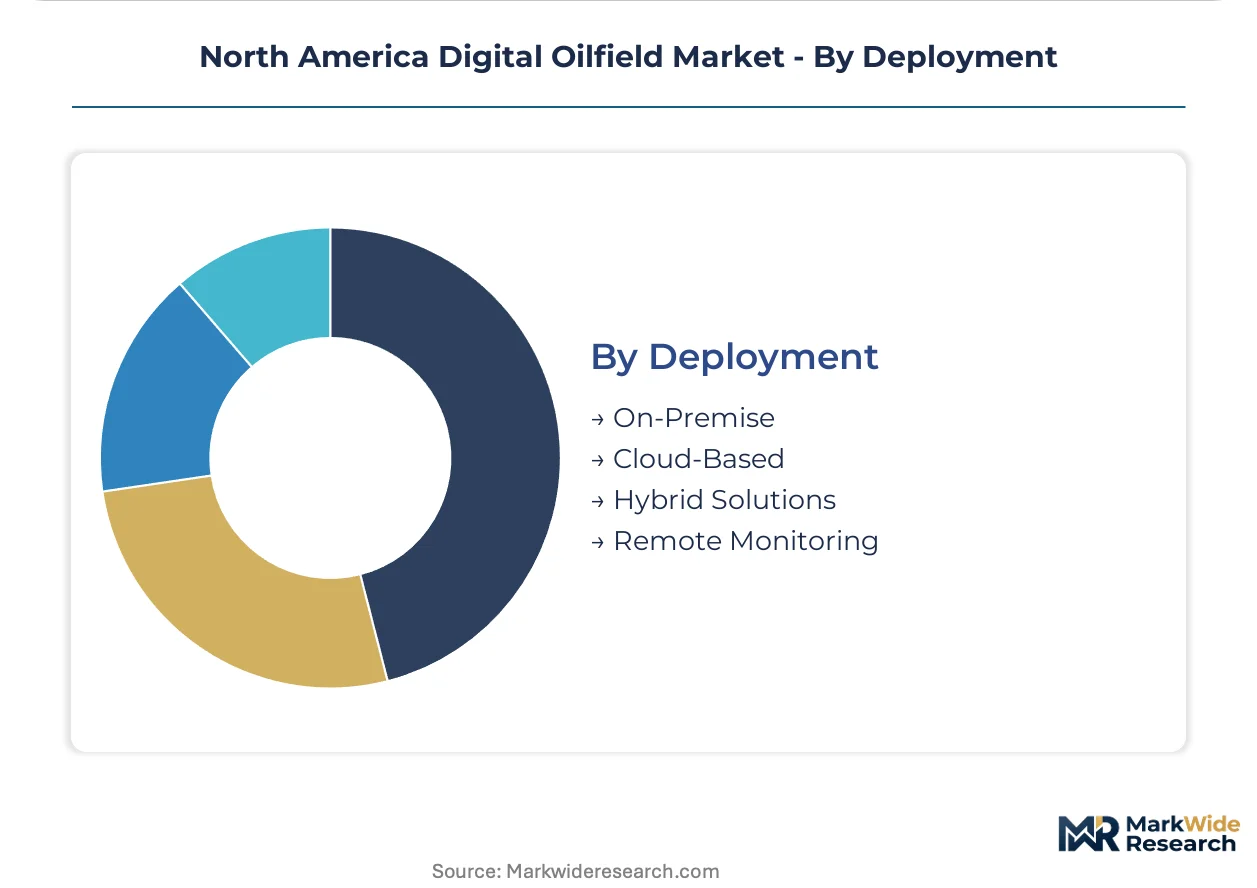
- Hybrid Solutions:Edge processing at well pads combined with cloud-based analytics and enterprise reporting satisfies latency and security requirements simultaneously. This architecture dominates Permian greenfield developments.
- On-Premise:Legacy SCADA and dedicated data historians remain entrenched at mature fields with sunk infrastructure investment. Brownfield retrofit costs slow replacement timelines.
- Cloud-Based:Reservoir simulation and corporate data lakes migrate to hosted environments for scalability.
- Remote Monitoring:Third-party operations centers handle alarm management and production optimization for independents lacking in-house capability.
Hybrid Solutions anchor the volume base while Cloud-Based deployments climb the fastest as majors rationalize multi-basin data infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methane enforcement under the Clean Air Act is compressing deployment timelines for continuous monitoring infrastructure across North American shale basins. Binding compliance deadlines favor integrated sensor-to-cloud architectures over fragmented point solutions. State-level venting restrictions in Texas and New Mexico layer additional procurement specifications for digital control systems.
United States
Permian Basin operators anchor regional demand through subsurface digital twin deployments that integrate real-time production data into EUR forecasting. The EPA mandates 15-minute transmission intervals for continuous emissions detection systems at well sites. Midland-Odessa drilling contractors now execute trajectory corrections through edge-native measurement-while-drilling systems without surface round-trip delays.
Canada
Alberta's oil sands producers prioritize artificial lift optimization and automated choke control to minimize venting under provincial methane reduction frameworks. Health Canada and Environment and Climate Change Canada enforce overlapping federal and provincial emissions monitoring standards that shape sensor procurement. Calgary-based operators consolidate multi-basin reservoir data lakes, driving cloud-native analytics demand across Western Canada sedimentary basins.
Mexico
Reform-era upstream liberalization is attracting international service providers to deploy digital infrastructure at onshore mature fields and deepwater developments. The country's national hydrocarbons regulator imposes production efficiency benchmarks that favor automated reservoir management systems. Ciudad del Carmen in Campeche Bay serves as the operational hub for offshore digital twin implementations at legacy Cantarell and Ku-Maloob-Zaap complexes.
North America Digital Oilfield Market Competitive Landscape
On the supply side, the industry is consolidating around integrated technology portfolios that span drilling, evaluation, and production optimization. Tiered competitive dynamics separate full-stack platform providers from specialized sensor and software vendors. Strategic archetypes include integrated oilfield services conglomerates, industrial automation conglomerates, and niche edge-computing hardware specialists. Dominant competitive moves center on performance-guaranteed leasing structures and proprietary algorithm development for artificial lift optimization.
Within the integrated services tier, Schlumberger, Halliburton, and Baker Hughes occupy positions that exemplify full-stack digital deployment capabilities. These companies anchor competitive positioning through combined hardware-software portfolios that address the entire well lifecycle. Industrial automation specialists including Emerson Electric and Honeywell International represent a distinct archetype focused on process control systems that bridge refinery and upstream boundaries. The competitive field narrows as asset-light leasing models concentrate vendor risk and compress traditional hardware margins toward recurring service revenue streams.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Emerson Electric |
| Weatherford |
| ABB |
| Honeywell International |
| NOV |
| Rockwell Automation |
| Others |
Value Network & Pricing Analysis
Houston's technology corridor concentrates digital oilfield system integration capacity, with vendor clustering near the Permian Basin's operational epicenter feeding pricing power to full-stack platform providers. This geographic concentration of engineering talent and field service infrastructure shapes procurement leverage across upstream operators.
Pricing Analysis
Certification level for hazardous area equipment creates the primary spread between premium and standard tiers. The market operates on hybrid pricing combining capital hardware sales with recurring SaaS subscriptions for analytics platforms. Price differentiation hinges on EPA compliance-grade sensor certification and bundled after-sales field service coverage. Cost compression in mid-tier sensor hardware is intensifying because contract manufacturers are absorbing commodity volatility. Capital-constrained independents exhibit highest price sensitivity while majors prioritize vendor consolidation over unit cost.
Supply Chain Analysis
Electronics manufacturing services in Mexico, Taiwan, and the United States hold capacity for edge computing hardware and ruggedized sensor assemblies. The supply chain draws from rare earth elements for magnetostrictive sensors, specialized semiconductors for high-temperature downhole applications, and precision-machined housings for pressure-rated environments. Single-source vulnerability concentrates in subsea-rated fiber optic telemetry components. Distribution runs through authorized integrator networks that bundle hardware with installation and calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American shale capital discipline is driving a cyclical recovery in digital oilfield spending, with EPA compliance mandates providing non-discretionary pull through the trough.
For Market Incumbents: Pre-empt margin erosion from asset-light leasing competitors by embedding proprietary algorithms into performance-guaranteed contracts. Secure backward integration into edge computing hardware to reduce exposure to semiconductor lead time volatility. Defend against emerging cloud-native challengers through OT-IT convergence certifications that address uptime reliability concerns at remote well sites. For New Entrants and Emerging Players: Mexico's reform-era upstream liberalization presents underpenetrated acreage for automated reservoir management deployments. Target independent Permian operators lacking in-house data science capabilities with remote monitoring subscriptions priced as operational expenditure. Enter through partnerships with drilling contractors seeking to differentiate performance-based day-rate contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with installed sensor bases capable of supporting recurring analytics revenue. Long-term viability hinges on EPA regulatory durability rather than commodity price recovery. Acquisition targets should demonstrate cloud-native architecture and multi-basin operator relationships. Watch for inflection signals in mid-tier operator bankruptcy filings that concentrate vendor consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Unifies fragmented SCADA and IoT endpoints under single vendor control across Permian well pads. |
| EPA Compliance Certification Program | Positions vendors for mandatory continuous emissions monitoring procurement under Clean Air Act enforcement. |
| Asset-Light Leasing Structure | Converts capital expenditure barriers into recurring revenue streams for capital-constrained independents. |
| Digital Twin Technology Licensing | Enables majors to consolidate multi-basin reservoir data lakes without proprietary platform development. |
| Edge Computing Hardware Partnership | Addresses 50-millisecond latency requirements for closed-loop reservoir control at well pads. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with drilling contractors, artificial lift specialists, reservoir engineers, and EPA compliance officers informed operational technology deployment patterns. Secondary sources include EPA enforcement actions, FERC pipeline integrity filings, state oil and gas commission venting restriction updates, and equipment manufacturer technical specifications. Bottom-up well count and sensor penetration estimates triangulate against top-down operator capital expenditure disclosures.
Calibration against historical technology refresh cycles and regulatory compliance deadlines shapes the analytical framework. Segmentation dimensions span technology type, application criticality, end-user procurement authority, and deployment architecture across the projection horizon. CAGRs derive from weighted scenario analysis incorporating EPA mandate enforcement timelines and shale basin drilling activity trajectories. Edge computing latency requirements and methane monitoring transmission intervals serve as industry-specific forecast inputs.
Practitioners should monitor EPA rulemaking revisions and state-level venting restriction expansions for early signals of procurement specification shifts. Forecasts reflect assumptions regarding regulatory durability and operator capital discipline continuity. Quarterly review of Permian drilling permit activity and mid-tier operator bankruptcy filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Floating Skimmer Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Frac Stack Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Libya Oil and Gas Midstream Market