
 North America Dry Eye Syndrome Market | 2026-2036
North America Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dry Eye Syndrome Market Intelligence
Buyer concentration among ophthalmology clinics is hardening as independent practices consolidate into multi-site specialty groups and hospital-affiliated networks. Alcon Inc. leverages its integrated surgical and pharmaceutical portfolio to secure preferred vendor status with these expanding clinic chains. AbbVie Inc. sustains its position through heavy R&D investment in disease-modifying therapies beyond conventional artificial tears. Bausch & Lomb Corp. competes on manufacturing scale, supplying high-volume commoditized drops to retail pharmacy channels that serve price-sensitive home care segments.
Dry eye syndrome encompasses a spectrum of ocular surface disorders characterized by tear film instability, hyperosmolarity, and ocular surface inflammation, typically diagnosed through tear break-up time testing, osmolarity measurement, and corneal staining assessment. Artificial tears remain the largest volume category, though margin pools are shifting toward lipid-based drops that address meibomian gland dysfunction, the dominant evaporative subtype. Anti-inflammatory drugs represent the fastest-expanding segment as prescribers move beyond symptomatic relief toward cyclosporine and corticosteroid protocols that modify disease progression. Disease-modifying treatment approaches command premium positioning as clinical evidence accumulates for long-term corneal surface preservation.
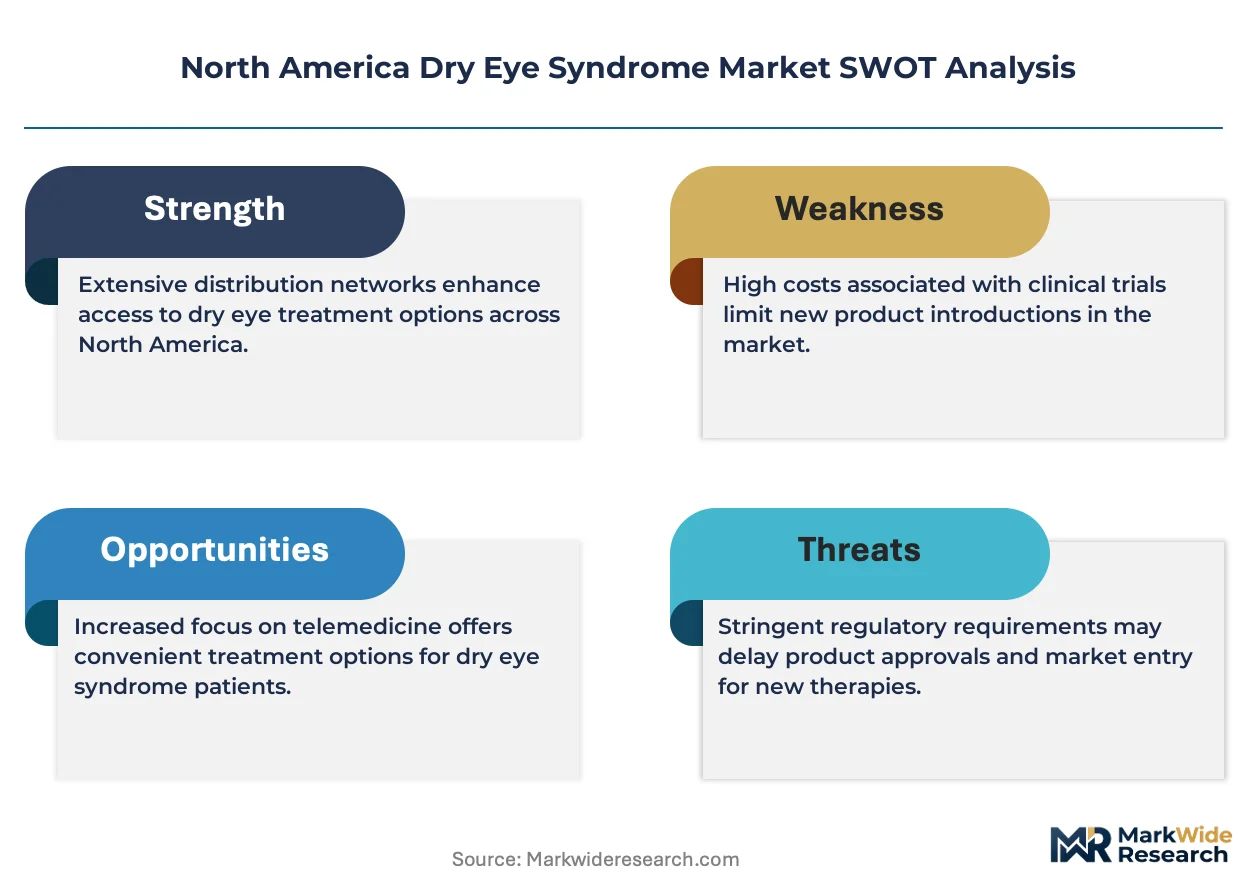
The FDA maintains stringent oversight of ophthalmic drug formulations through its Center for Drug Evaluation and Research, while Health Canada and PMRA enforce parallel standards that govern cross-border product registration and labeling requirements. These regulatory frameworks elevate barriers for new entrants, particularly for preservative-free multidose delivery systems and novel active pharmaceutical ingredients. Stakeholders must monitor evolving bioequivalence standards for complex generics and anticipate how FDA guidance on local action ophthalmic products will reshape competitive dynamics for established formulations.
Market Dynamics
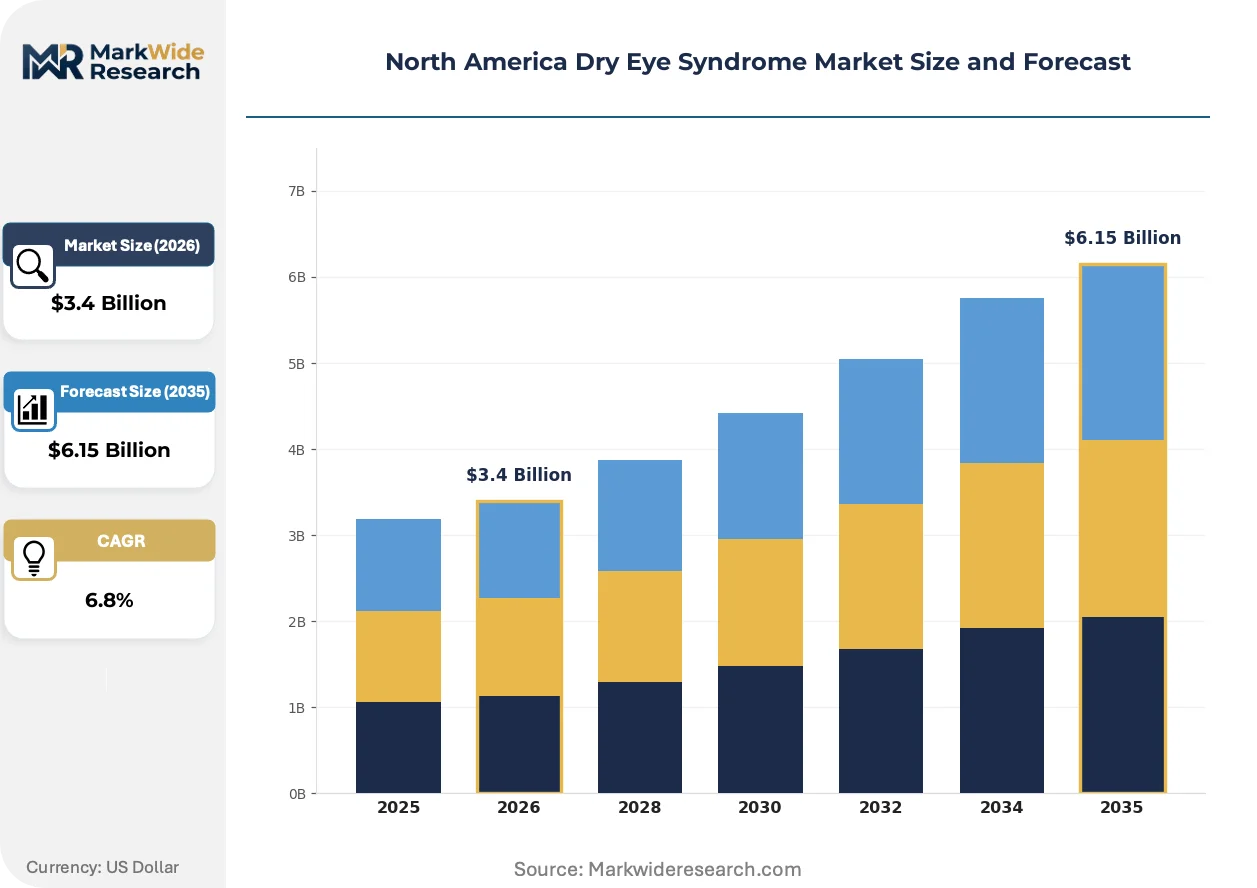
The North America Dry Eye Syndrome Market is being restructured by ophthalmology clinic consolidation into multi-site specialty groups, which hardens buyer concentration and compresses vendor margins through preferred vendor contracting.
Growth Catalysts
- Meibomian gland dysfunction protocols:Evaporative subtype recognition is expanding lipid-based drop prescriptions beyond artificial tears. Ophthalmology clinics now screen for this condition routinely.
- FDA guidance on local action ophthalmic products:Streamlined bioequivalence pathways for complex generics are accelerating generic cyclosporine entry. Generic manufacturers gain clearer development targets.
- Canada's aging population concentration:Demographic weight in Ontario and British Columbia is expanding the addressable patient base. Provincial health systems are adding dry eye to covered chronic condition monitoring.
Market Restraints
- Preservative-free multidose delivery systems:Technical barriers to stable, contamination-resistant formulations elevate manufacturing costs. Only specialized contract manufacturers possess validated production lines.
- Active pharmaceutical ingredient concentration:Cyclosporine and corticosteroid API supply concentrates among three global suppliers. North American formulators face input cost volatility and allocation risk.
- Health Canada and PMRA parallel registration requirements:Cross-border labeling harmonization delays create friction for unified North American launches. Product managers must maintain separate regulatory dossiers.
Strategic Opportunities
- Underpenetrated Mexican metropolitan markets:Mexico City and Monterrey ophthalmology infrastructure is expanding faster than specialist supply. First-mover clinic chains can establish dry eye service lines with limited competition.
- Teleophthalmology diagnostic convergence:Remote tear osmolarity testing combined with AI-powered corneal staining analysis extends specialist reach. Rural and suburban patient populations gain access previously limited to urban hubs.
- United States hospital-affiliated network procurement:Centralized purchasing by integrated delivery networks creates volume contracts for disease-modifying therapies. Manufacturers can secure multi-year supply agreements with predictable offtake.
Industry Challenges
- Ocular surface disease specialist training pipelines:Fellowship programs produce fewer cornea specialists than clinic expansion requires. Hiring competition elevates compensation costs for qualified diagnosticians.
- Legacy practice management system integration:Electronic health record fragmentation between independent clinics and hospital systems complicates patient tracking. Data interoperability gaps hinder outcome-based contracting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dry Eye Syndrome Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Punctal Plugs, Anti-Inflammatory Drugs, Lipid-Based Drops End User: Ophthalmology Clinics, Hospitals, Home Care, Retail Pharmacies Delivery Mode: Topical, Injectable, Oral, Surgical Treatment Type: Symptomatic, Preventive, Disease-Modifying, Combination Therapy |
| Companies Covered | AbbVie Inc., Alcon Inc., Novartis AG, Santen Pharmaceutical Co., Ltd., OASIS Medical, Johnson & Johnson Vision Care, Inc., Bausch & Lomb Corp., Oyster Point Pharmaceuticals, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dry Eye Syndrome Market Strategic Shifts & Innovations
Novel drug delivery mechanisms are compressing dosing frequency from four times daily to once-daily or sustained-release formats, reshaping patient adherence economics and competitive positioning around convenience premiums.
Nanostructured lipid carrier formulations are rewriting the efficacy-access tradeoff for anti-inflammatory dry eye therapies. These carriers improve corneal penetration of cyclosporine and corticosteroids while reducing systemic absorption. Large ophthalmology clinic chains in Texas and California are piloting these formulations for moderate-to-severe disease patients. The technology is compressing the gap between generic artificial tears and branded immunomodulators.
Health Canada and PMRA are tightening preservative safety thresholds for chronic-use ophthalmic products through updated guidance documents. This regulatory pressure is accelerating reformulation investments across the industry. Preservative-free multidose systems are becoming the default expectation for prescriptions exceeding ninety days, particularly in pediatric and contact lens wearer segments.
Patient acquisition patterns are rotating from optometry referral channels toward direct-to-clinic digital scheduling. Younger dry eye patients in metropolitan United States markets now self-refer based on online symptom assessments and insurance network searches. This channel shift is forcing clinic groups to invest in search visibility and automated intake workflows rather than relying on traditional optometric partnerships.
North America Dry Eye Syndrome Market Segmentation
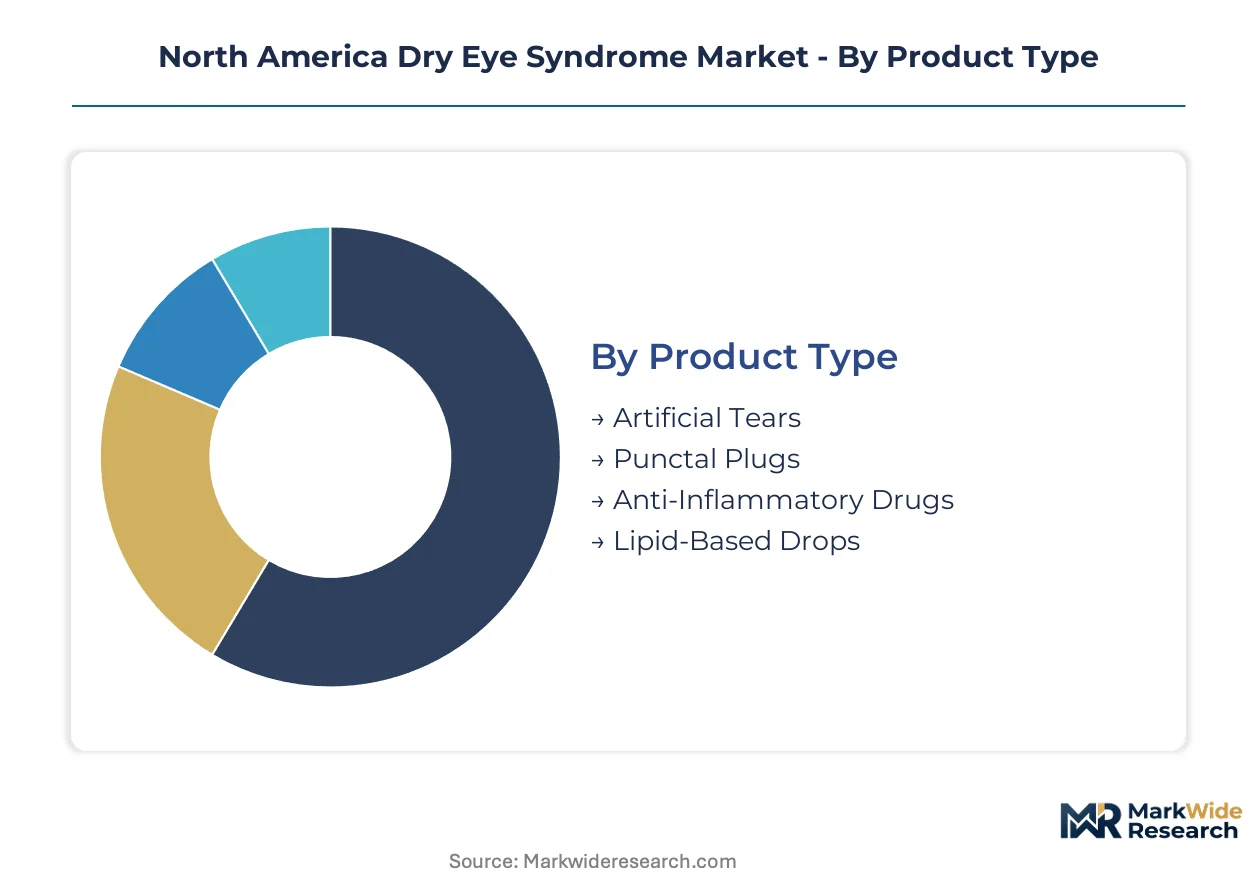
Segmentation in the North America Dry Eye Syndrome Market reveals distinct margin pools and contracting dynamics. Product type determines reimbursement tier and pharmacy channel placement. End user concentration shapes procurement leverage and vendor selection criteria.
Product Type:
Prescriber preference for mechanism-specific efficacy over generic lubrication is redrawing category boundaries.
- Artificial Tears:Polymeric lubricant solutions and gels provide immediate symptomatic relief through viscosity enhancement and tear film stabilization. Demand concentrates in retail pharmacy channels serving price-sensitive home care segments across the United States, where insurance coverage gaps push patients toward over-the-counter selection.
- Anti-Inflammatory Drugs:Cyclosporine emulsions and corticosteroid formulations target ocular surface inflammation through T-cell suppression and cytokine modulation. Ophthalmology clinics in metropolitan Texas and California are expanding prescriptions for these therapies as first-line disease-modifying protocols.
- Punctal Plugs:Silicone or collagen occlusive devices inserted into lacrimal puncta to reduce tear drainage and prolong ocular surface moisture retention.
- Lipid-Based Drops:Meibomian gland dysfunction-targeted formulations containing phospholipids and essential fatty acids to restore evaporative tear film integrity.
Leading the category by volume: Artificial Tears. Expanding most quickly: Anti-Inflammatory Drugs.
End User:
Site-of-care economics and reimbursement complexity fragment procurement authority across four distinct channels.
- Ophthalmology Clinics:Multi-site specialty groups and hospital-affiliated networks now control the majority of disease-modifying therapy prescriptions. These consolidated buyers leverage preferred vendor contracts to compress margins on high-volume artificial tears while paying premiums for novel anti-inflammatory formulations.
- Home Care:Self-administered regimens dominate the artificial tears segment, with patients purchasing through retail pharmacy and direct-to-consumer channels. Insurance coverage limitations for chronic dry eye maintenance drive out-of-pocket spending concentration in the United States.
- Hospitals:Integrated delivery networks in Ontario and British Columbia are adding dry eye screening to chronic condition protocols, creating institutional procurement opportunities for diagnostic devices and prescription therapies.
- Retail Pharmacies:High-volume commoditized drop distribution serves price-sensitive segments with limited specialist access, particularly in suburban and rural markets.
Dominating procurement volume: Ophthalmology Clinics. Gaining share fastest: Home Care.
Delivery Mode:
Patient adherence economics and formulation stability requirements determine competitive positioning across administration routes.
- Topical:Eye drops and ointments applied directly to the ocular surface constitute the overwhelming majority of prescriptions. FDA bioequivalence pathways for complex generic ophthalmic emulsions are accelerating competitor entry.
- Surgical:Punctal occlusion and meibomian gland expression procedures address refractory cases. Demand concentrates in cornea specialist practices within large metropolitan ophthalmology hubs.
- Injectable:Sustained-release corticosteroid implants and biologic agents delivered via periocular or intravitreal routes for severe inflammatory subtypes.
- Oral:Systemic omega-3 supplementation and tetracycline-class antibiotics targeting meibomian gland dysfunction through anti-inflammatory and lipid-modifying mechanisms.
Commanding prescription volume: Topical. Climbing the fastest: Surgical.
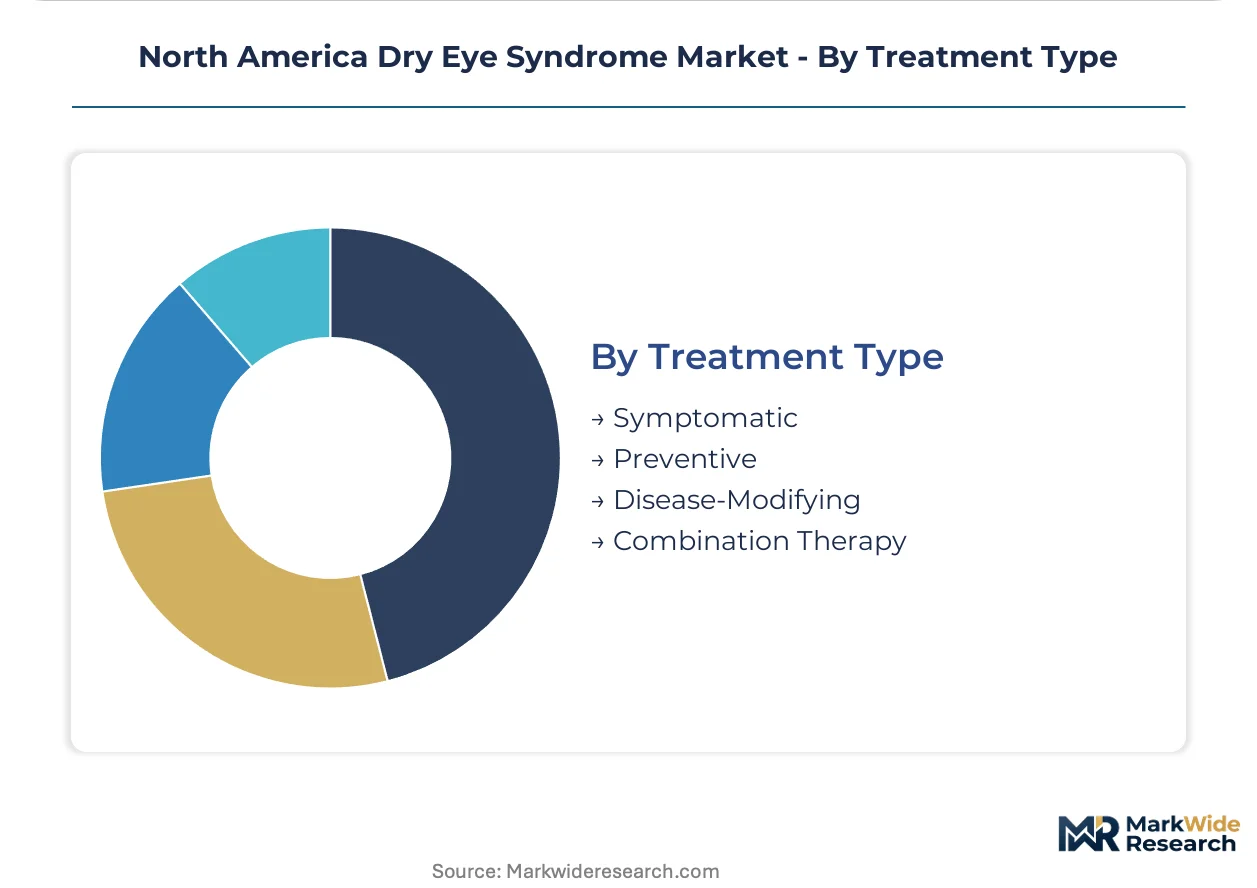
Treatment Type:
Clinical evidence accumulation for long-term corneal surface preservation is shifting reimbursement toward proactive protocols.
- Disease-Modifying:Immunomodulatory and anti-inflammatory therapies that alter underlying pathophysiology rather than masking symptoms. United States hospital-affiliated networks are centralizing purchasing for these premium-positioned treatments through multi-year supply agreements.
- Symptomatic:Lubricating and vasoconstrictive agents providing immediate but transient relief. Retail pharmacy channels and price-sensitive segments sustain volume despite margin compression.
- Preventive:Environmental modification, lid hygiene protocols, and nutritional supplementation targeting risk factor reduction in pre-symptomatic or mild disease.
- Combination Therapy:Sequential or concurrent use of lubricants, anti-inflammatories, and punctal occlusion tailored to mixed-mechanism disease phenotypes.
Generating highest revenue per patient: Disease-Modifying. Steepest expansion trajectory: Combination Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in metropolitan ophthalmology hubs across the continent, with the United States absorbing the majority of disease-modifying therapy volume. Canada and Mexico present divergent expansion trajectories shaped by regulatory sophistication and infrastructure investment cycles.
United States
Hospital-affiliated networks in Texas and California are consolidating procurement authority for premium anti-inflammatory therapies. FDA guidance on local action ophthalmic products accelerates generic cyclosporine entry, compressing margins for incumbent formulators. Greater Boston and Pacific Northwest cornea specialist practices pilot nanostructured lipid carrier formulations for moderate-to-severe disease.
Canada
Ontario and British Columbia health systems are adding dry eye screening to covered chronic condition monitoring protocols. Health Canada and PMRA maintain parallel registration requirements that delay unified North American product launches. Toronto and Vancouver ophthalmology clinic chains are expanding dedicated dry eye service lines as differentiated revenue streams.
Mexico
Mexico City and Monterrey ophthalmology infrastructure is expanding faster than specialist supply creates coverage gaps. The country's national pharmaceutical regulator enforces registration standards that favor established multinational formulators with compliance infrastructure. First-mover clinic groups in these metropolitan areas are capturing patient populations with limited competitor density.
North America Dry Eye Syndrome Market Key Industry Players
United States producers anchor the premium disease-modifying therapy tier; Swiss and Japanese specialists hold positions in novel delivery mechanism development. The vendor base stratifies across three tiers: integrated surgical-pharmaceutical conglomerates securing preferred vendor status with consolidating clinic chains, mid-scale generic manufacturers competing on FDA bioequivalence pathway execution, and niche device specialists supplying punctal plug and surgical instrumentation. Dominant competitive moves include horizontal consolidation into multi-site ophthalmology service networks and backward integration into preservative-free multidose delivery system manufacturing.
Within the integrated conglomerate tier, Alcon Inc. and AbbVie Inc. exemplify divergent strategic positioning—Alcon leveraging surgical-pharmaceutical portfolio breadth while AbbVie sustains presence through disease-modifying therapy development. Bausch & Lomb Corp. occupies the manufacturing scale-driven segment, supplying high-volume commoditized formulations to retail pharmacy channels serving price-sensitive home care segments across the continent.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Alcon Inc. |
| Novartis AG |
| Santen Pharmaceutical Co., Ltd. |
| OASIS Medical |
| Johnson & Johnson Vision Care, Inc. |
| Bausch & Lomb Corp. |
| Oyster Point Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up ophthalmology clinic chains in Texas and California are consolidating procurement authority, compressing margins on commoditized artificial tears while preserving premium positioning for disease-modifying therapies through preferred vendor contracting that locks in multi-year supply agreements.
Pricing Analysis
Volume concentrates in retail pharmacy artificial tears with razor-thin margins, while disease-modifying anti-inflammatory drugs capture premium positioning in ophthalmology clinics. Three-tier pricing structure across premium immunomodulators, standard lipid-based drops, and economy artificial tears reflects mechanism-specific efficacy differentiation. Cost compression in the artificial tears segment intensifies because FDA bioequivalence pathways accelerate generic cyclosporine entry. Home care patients purchasing through retail channels exhibit highest price sensitivity; hospital-affiliated networks purchasing disease-modifying therapies show lowest sensitivity due to centralized procurement and outcome-based contracting.
Supply Chain Analysis
FDA and Health Canada validation requirements for preservative-free multidose systems create qualification gating that limits contract manufacturing capacity to specialized facilities in the United States, Switzerland, and Japan. Active pharmaceutical ingredient supply for cyclosporine and corticosteroids draws from concentrated global suppliers, creating input cost volatility for North American formulators. Single-source vulnerability in API concentration elevates allocation risk during supply disruptions. Distribution runs through multi-site ophthalmology clinic networks for premium therapies and retail pharmacy channels for over-the-counter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in validated preservative-free multidose manufacturing prop pricing discipline for disease-modifying therapies, as capacity expansion timelines lag clinic consolidation-driven demand growth.
For Market Incumbents: Extend manufacturing scale advantages through backward integration into API sourcing and captive production of preservative-free multidose delivery systems. Alcon and AbbVie should deepen preferred vendor relationships with consolidating Texas and California clinic chains before generic cyclosporine entrants erode immunomodulator margins. Locking in multi-year supply agreements now secures offtake visibility against emerging competition. For New Entrants and Emerging Players: Direct-to-clinic digital scheduling platforms offer a low-friction entry path into underpenetrated Mexican metropolitan markets where ophthalmology infrastructure expansion outpaces specialist supply. First-mover clinic chains in Mexico City and Monterrey present partnership opportunities for novel lipid-based drop formulations targeting meibomian gland dysfunction. Teleophthalmology diagnostic convergence enables remote patient acquisition without capital-intensive physical presence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale generic manufacturers with FDA bioequivalence pathway execution capability in the United States and Canada. These assets offer manufacturing scale leverage as clinic consolidation intensifies price competition in commoditized segments. Watch for Health Canada and PMRA guidance tightening on preservative safety thresholds as the inflection signal accelerating reformulation investment requirements and consolidation pressure on sub-scale formulators lacking validated production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Multidose Manufacturing Scale-Up | FDA-validated production lines at Alcon and Bausch & Lomb address chronic-use safety requirements. |
| Preferred Vendor Contracting with Clinic Chains | Multi-site specialty groups in Texas and California centralize procurement for disease-modifying therapies. |
| Teleophthalmology Diagnostic Platform Launch | Remote tear osmolarity testing extends specialist reach into rural and suburban patient populations. |
| API Supply Agreement Diversification | Cyclosporine and corticosteroid sourcing from multiple global suppliers mitigates allocation risk. |
| Meibomian Gland Dementia Service Line Expansion | Dedicated revenue streams at Toronto and Vancouver clinic chains capture evaporative subtype recognition growth. |
Research Approach
Multi-period observation of ophthalmology clinic consolidation patterns, FDA guidance document evolution, and Health Canada registration timelines anchored the trend analysis, supplemented by interviews with cornea specialists, ophthalmology clinic procurement directors, pharmaceutical regulatory affairs leads, and retail pharmacy category managers. Secondary validation drew from FDA Center for Drug Evaluation and Research filings, Health Canada guidance documents, ClinicalTrials.gov ophthalmology trial registries, and provincial health system procurement databases. Bottom-up patient volume modeling triangulated against top-down therapy spending estimates.
Segment-weighting approaches applied differential growth assumptions across product type, end user channel, and treatment modality dimensions. The analytical framework incorporated patient population aging trajectories, meibomian gland dysfunction screening penetration rates, and generic cyclosporine entry timing assumptions across the projection horizon. CAGRs were derived from log-linear regression of segment-level spending trajectories, cross-referenced with formulary placement probability assessments for pipeline therapies.
The model holds under stable FDA bioequivalence standards and continued clinic consolidation momentum; deviation in Health Canada preservative safety threshold tightening or API supply disruption events would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and regulatory engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Gingivostomatitis Market