
 Global Epilepsy Market | 2026-2036
Global Epilepsy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epilepsy Market Analysis
The gulf between biologic antiepileptic therapies and generic small-molecule drugs is broadening, splitting treatment protocols into precision-medicine corridors versus cost-optimized maintenance lanes. UCB Inc. anchors its position through deep R&D investment in antibody and gene-therapy platforms for refractory cases. Eisai Co., Ltd. differentiates via its dominance in Asian regulatory filings and pediatric epilepsy indications. Pfizer Inc. competes through manufacturing scale that secures hospital formulary placement across multiple continents.
Epilepsy comprises a spectrum of chronic neurological disorders characterized by recurrent, unprovoked seizures resulting from excessive neuronal discharge, with diagnostic thresholds defined by EEG-confirmed seizure activity and treatment goals centered on seizure freedom without intolerable adverse effects. Antiepileptic drugs command the largest revenue pool within drug class segmentation, though vagus nerve stimulation devices capture disproportionate margins due to implantation procedure bundling and long-term maintenance contracts. Hospital pharmacies remain the dominant distribution channel for initiation-phase therapies, while retail and online channels expand for stable maintenance prescriptions.
The FDA, EMA, and WHO collectively shape market access through divergent efficacy-evidence requirements, with the FDA accelerating breakthrough therapy designations and the EMA enforcing stricter long-term safety surveillance through its pharmacovigilance framework. WHO inclusion of antiepileptic medicines on its Essential Medicines List drives procurement volumes in low-income health systems and influences national reimbursement decisions. Stakeholders must monitor how decentralized clinical trial designs and real-world evidence submissions are rewriting regulatory approval pathways for neuromodulation devices.
Market Dynamics
The epilepsy treatment landscape is fracturing along precision-medicine versus cost-optimization fault lines, as biologic and gene therapies for refractory cases diverge sharply from generic small-molecule maintenance protocols.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway compresses development timelines for rare epilepsy syndromes, drawing venture capital into previously uneconomical indications.
- Neurostimulation Implant Volumes:Tertiary epilepsy centers in the United States are expanding surgical capacity for responsive neurostimulation devices, creating procedural pull-through for device-drug combination protocols.
- WHO Essential Medicines List Inclusion:Antiepileptic medicines on this list drive procurement volumes in low-income health systems and influence national reimbursement decisions across sub-Saharan Africa and South Asia.
Market Restraints
- Biologic Manufacturing Concentration:Single-source suppliers for specialized viral vectors and cell lines create supply vulnerability for gene therapy candidates targeting Dravet syndrome and Lennox-Gastaut syndrome.
- EMA Pharmacovigilance Burden:The agency's long-term safety surveillance requirements extend post-market commitment timelines, elevating compliance costs for neuromodulation device manufacturers seeking European market access.
- Generic Small-Molecule Substitution:Narrow therapeutic index antiepileptic drugs face pharmacy-level substitution pressures that destabilize seizure control in stable patients, creating clinical resistance to formulary changes.
Strategic Opportunities
- Decentralized Clinical Trial Infrastructure:Remote seizure monitoring via wearable EEG is expanding patient recruitment geography beyond traditional academic medical center catchment areas.
- Real-World Evidence Submissions:FDA breakthrough therapy designation pathways now accept registry data and electronic health record-derived efficacy signals, compressing evidence generation for device indications.
- Pediatric Indication Expansion:EMA pediatric investigation plan requirements create regulatory exclusivity extensions for sponsors that develop age-appropriate formulations and dosing algorithms.
Industry Challenges
- Epileptologist Workforce Scarcity:Fellowship-trained specialists cluster in urban tertiary centers, leaving rural and semi-urban populations with general neurology management of complex, refractory cases.
- Neurostimulation Programming Complexity:Device parameter optimization requires specialized nursing and bioengineering support that hospital systems struggle to staff at scale, limiting implant utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epilepsy Market |
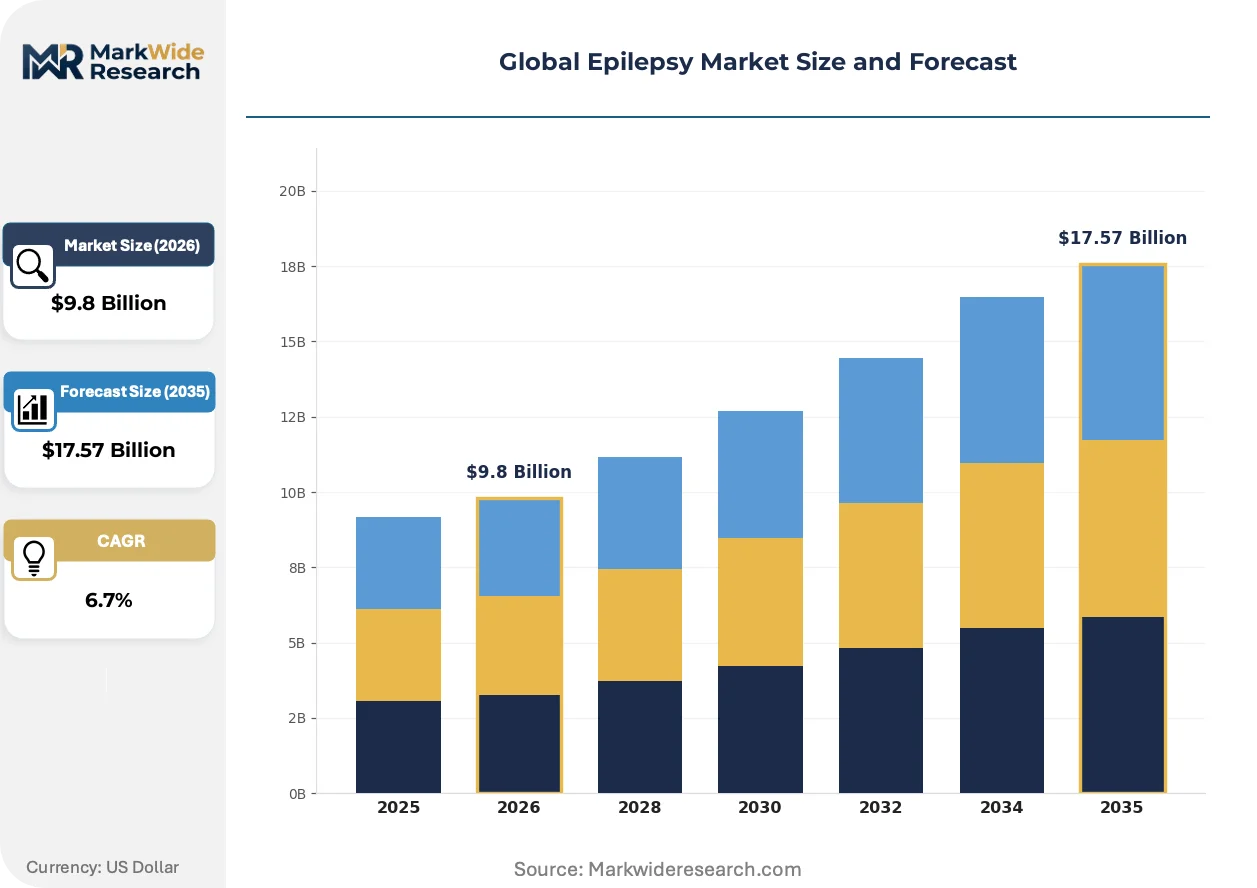
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Medication, Surgery, Vagus Nerve Stimulation, Responsive Neurostimulation Patient Age Group: Children, Adolescents, Adults, Elderly Drug Class: Antiepileptic Drugs, Benzodiazepines, Barbiturates, Others Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinics |
| Companies Covered | UCB Inc., Eisai Co., Ltd., Pfizer Inc., GSK plc, Novartis AG, H. Lundbeck A/S, Abbott Laboratories, Bausch Health Companies Inc., GW Pharmaceuticals Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epilepsy Market Emerging Trajectories
Digital biomarker capture and closed-loop therapeutic systems are converging to enable personalized seizure prediction and intervention, fundamentally altering the chronic disease management model for epilepsy.
Responsive neurostimulation hardware is modularizing around implantable pulse generators that separate sensing electrodes from therapeutic delivery channels. Pediatric epilepsy centers and adult tertiary referral networks are adopting these platforms faster than community neurology practices. This architecture is modularizing supplier ecosystems, allowing hospitals to mix electrode arrays from specialized manufacturers with generator platforms from device incumbents.
EMA's Medical Device Regulation (MDR) reclassification of active implantable neurological devices has tightened clinical evidence requirements for neurostimulator renewals. Manufacturers must now submit prospective post-market clinical follow-up data rather than retrospective registry analyses. High-density recording arrays and closed-loop stimulation systems face the steepest compliance burden, with several products delayed in European launch timelines pending MDR technical documentation review.
Hospital pharmacy consolidation is reshaping antiepileptic drug procurement, with integrated delivery networks centralizing specialty medication protocols under clinical pharmacist oversight. Retail and online channels are capturing stable maintenance prescriptions as 90-day dispensing becomes standard for non-narrow therapeutic index agents. This channel bifurcation is most pronounced in the United States, where pharmacy benefit manager formulary tiers increasingly steer patients toward mail-order fulfillment for chronic maintenance therapy.
Global Epilepsy Market Segmentation
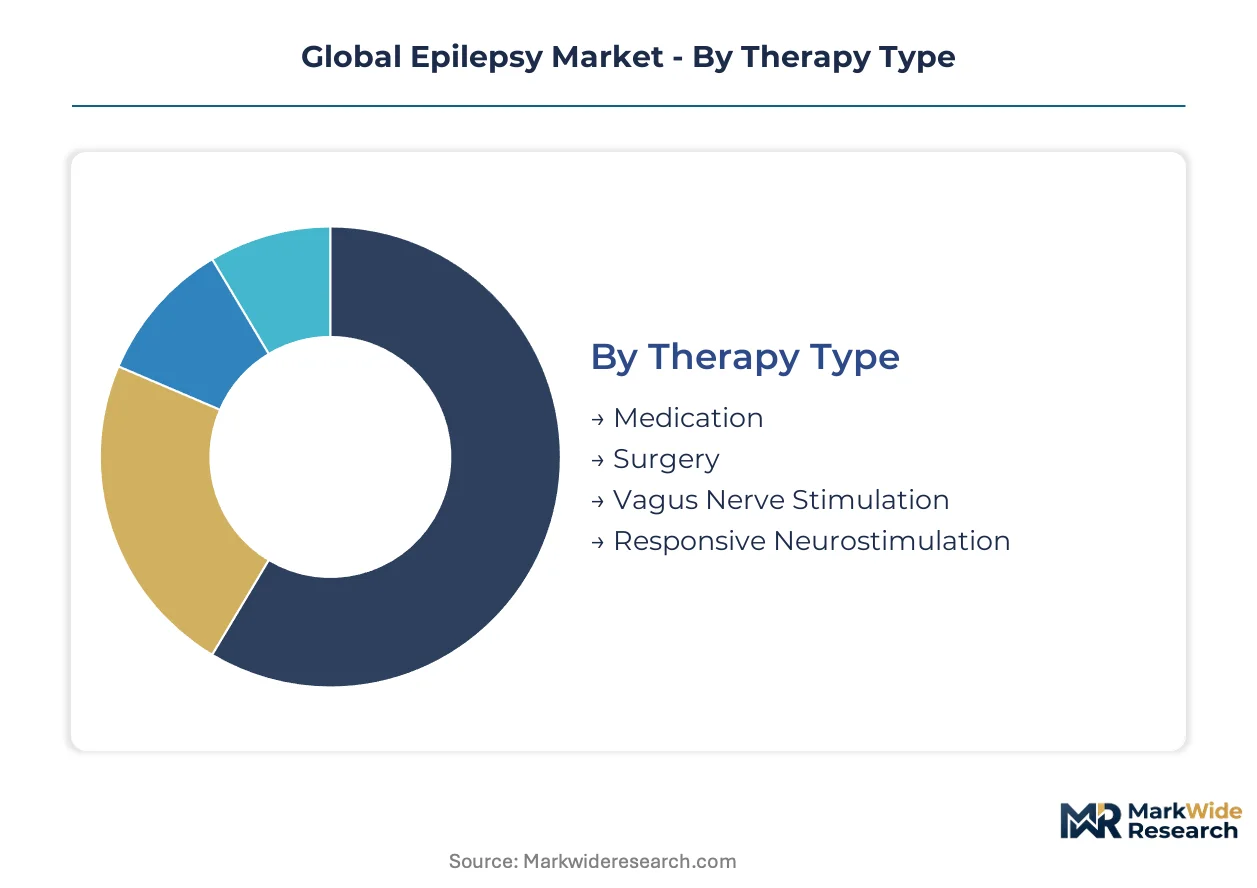
Epilepsy treatment protocols fragment across patient lifecycle stages, therapeutic intensity levels, and care delivery settings. Understanding these divides reveals where precision medicine investments concentrate versus where cost optimization dominates procurement decisions.
Therapy Type:
Upgrade cycles vary sharply across this dimension, with implantable neurostimulation devices requiring surgical replacement every 5-7 years while medication regimens shift through titration phases.
- Medication:Small-molecule antiepileptic drugs remain the first-line intervention for newly diagnosed patients, with generic substitution protocols driving formulary decisions in United States integrated delivery networks and India's public procurement systems. Hospital pharmacies in tertiary centers retain dispensing control for narrow therapeutic index agents.
- Surgery:Resective procedures for drug-resistant focal epilepsy require specialized epileptologist-surgical teams concentrated at Cleveland Clinic, Mayo Clinic, and similar United States academic centers. Patient selection criteria have tightened as neurostimulation alternatives expand.
- Vagus Nerve Stimulation:Implantable pulse generators with transcutaneous programming capabilities serve patients with multifocal or bilateral seizure foci unsuitable for resection.
- Responsive Neurostimulation:Closed-loop systems with intracranial sensing electrodes target bilateral temporal lobe epilepsy, with programming complexity limiting deployment to fellowship-trained centers.
Medication sits at the top of the volume ranking, with responsive neurostimulation climbing the fastest.
Patient Age Group:
Developmental neurobiology creates distinct pharmacokinetic profiles and seizure semiology patterns across life stages, forcing formulation and dosing specialization.
- Children:Dravet syndrome and Lennox-Gastaut syndrome drive orphan drug development, with FDA pediatric exclusivity incentives shaping sponsor investment. Liquid formulations and weight-based dosing algorithms dominate prescribing in pediatric epilepsy centers.
- Adolescents:Transition protocols from pediatric to adult care create adherence discontinuities, with driving restrictions and academic performance pressures influencing treatment goals.
- Adults:Employment concerns and pregnancy planning drive demand for seizure freedom over adverse effect minimization in this largest-volume segment.
- Elderly:Comorbid cardiovascular and cognitive conditions complicate antiepileptic selection, with drug-drug interaction profiles dominating formulary decisions in geriatric neurology practices.
Adults command the largest patient pool, while children show the steepest expansion trajectory for novel biologic therapies.
Drug Class:
Margin structures diverge between long-genericized small molecules and patent-protected antiepileptic drugs with extended-release formulations.
- Antiepileptic Drugs:Sodium channel blockers, GABA enhancers, and glutamate antagonists comprise the therapeutic backbone, with levetiracetam and lamotrigine dominating maintenance protocols in United States and European prescribing.
- Benzodiazepines:Rescue medications for acute seizure clusters face regulatory scrutiny for dependence potential, limiting chronic use to specific epilepsy syndromes.
- Barbiturates:Phenobarbital persists in low-resource settings through WHO Essential Medicines List inclusion, though developed markets have largely displaced this class.
- Others:Cannabidiol extracts and fenfluramine represent recent additions for specific genetic epilepsies.
Antiepileptic drugs anchor volume, with cannabidiol and other novel agents gaining share fastest.
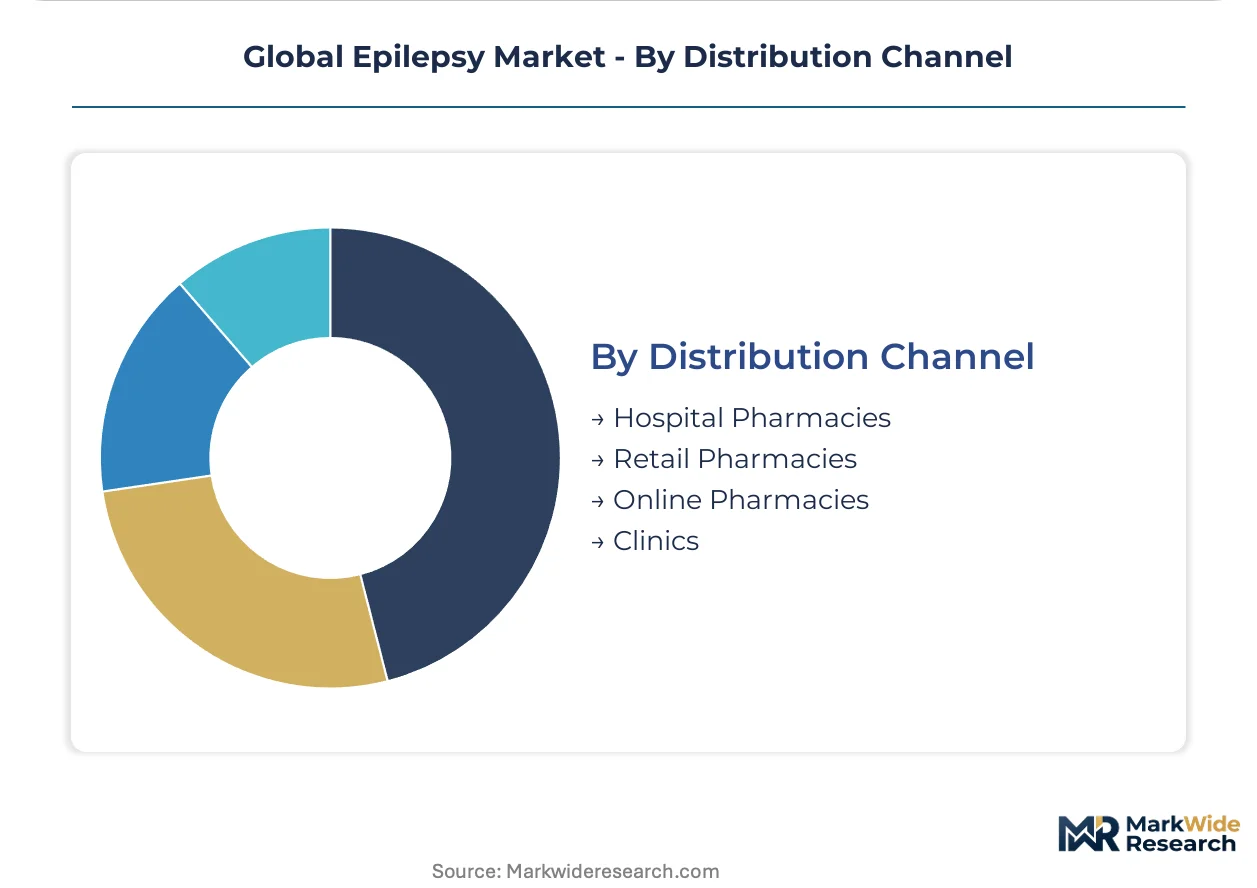
Distribution Channel:
Channel selection tracks treatment phase, with initiation-phase therapies requiring clinical oversight that retail and online fulfillment cannot replicate.
- Hospital Pharmacies:Integrated delivery networks centralize specialty antiepileptic procurement under clinical pharmacist oversight, with therapeutic drug monitoring protocols requiring inpatient infrastructure.
- Retail Pharmacies:90-day maintenance dispensing for stable patients has shifted volume toward CVS, Walgreens, and similar United States chains, with pharmacy benefit manager formulary tiers steering fulfillment decisions.
- Online Pharmacies:Mail-order fulfillment captures chronic maintenance prescriptions for non-narrow therapeutic index agents, with auto-refill programs improving adherence metrics.
- Clinics:Infusion centers administer parenteral formulations for patients with swallowing difficulties or status epilepticus protocols.
Hospital pharmacies lead in value concentration, though online channels are expanding most quickly for stable maintenance populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained epileptologists cluster in urban academic medical centers across five countries, creating concentrated demand nodes for advanced neurostimulation and biologic therapies.
United States
Tertiary epilepsy centers in Cleveland, Rochester, and Houston drive implant volumes for responsive neurostimulation devices that exceed any single European country's surgical capacity. FDA breakthrough therapy designations compress approval timelines for rare syndrome therapies, accelerating venture capital deployment. The Mayo Clinic's Rochester campus anchors a Midwestern referral network that captures complex resective surgery cases from twelve surrounding states.
Germany
EMA pharmacovigilance requirements extend post-market surveillance timelines for neuromodulation devices, elevating compliance costs for manufacturers seeking European market access. The country's statutory health insurance system maintains tight formulary control over narrow therapeutic index antiepileptic drugs, preserving hospital pharmacy dispensing dominance. Baden-Württemberg's university hospitals in Heidelberg and Freiburg concentrate pediatric epilepsy surgical expertise for Central European referrals.
Japan
PMDA regulatory pathways for pediatric indications create exclusivity incentives that shape sponsor investment in age-appropriate formulations. METI industrial policy supports domestic manufacturing of implantable pulse generators through targeted R&D subsidies. Tokyo's National Center of Neurology and Psychiatry anchors a Kanto-region network that manages the country's highest volume of vagus nerve stimulation programming.
India
WHO Essential Medicines List inclusion drives phenobarbital and phenytoin procurement volumes through the country's public health distribution system. CDSCO accelerated approval pathways for orphan drugs remain underdeveloped, limiting biologic therapy access to private tertiary centers. Maharashtra's Mumbai-Pune corridor concentrates the nation's fellowship-trained epileptologists, creating a two-tier treatment landscape between urban academic centers and general neurology practices.
United Kingdom
NICE technology appraisals create explicit cost-effectiveness thresholds that restrict NHS reimbursement for high-cost neurostimulation devices outside specialized commissioning frameworks. The country's Medicines and Healthcare products Regulatory Agency aligns post-Brexit with FDA breakthrough designations for rare epilepsy syndromes. London's National Hospital for Neurology and Neurosurgery maintains Europe's highest surgical volume for responsive neurostimulation implants.
Global Epilepsy Market Vendor Landscape
Top-tier vendors anchor the biologic and device segments, while mid-scale pharmaceutical manufacturers compete on generic small-molecule volume and hospital formulary placement. Market structure concentrates around three strategic archetypes: integrated neurology-device conglomerates with surgical service bundling, biotech specialists pursuing antibody and gene therapy platforms, and diversified pharmaceutical incumbents leveraging manufacturing scale. Dominant competitive moves include vertical integration into specialized viral vector manufacturing and strategic partnerships with tertiary epilepsy centers for real-world evidence generation.
Within the biologic therapy tier, UCB Inc. and Eisai Co., Ltd. exemplify divergent geographic specialization strategies that shape regulatory filing patterns. Pfizer Inc. occupies a position representing manufacturing-scale incumbents that secure multi-continent hospital procurement contracts through volume commitments. These three entities collectively illustrate how competitive positioning in epilepsy therapeutics fragments across precision-medicine innovation vectors and cost-optimized maintenance protocols.
| Leading Market Players |
|---|
| UCB Inc. |
| Eisai Co., Ltd. |
| Pfizer Inc. |
| GSK plc |
| Novartis AG |
| H. Lundbeck A/S |
| Abbott Laboratories |
| Bausch Health Companies Inc. |
| GW Pharmaceuticals Plc. |
| Others |
Supply Flow & Price Mechanics
Viral vector manufacturing costs cascade through gene therapy pricing tiers, with single-source bioreactor capacity in the United States and Europe commanding premium placement against Asian contract manufacturing alternatives for maintenance antiepileptic drugs.
Pricing Analysis
Bundled implantation-procedure pricing for responsive neurostimulation devices captures surgical facility fees and long-term programming contracts, while unbundled generic antiepileptic drug procurement splits across pharmacy benefit manager tiers. Price differentiation rests on FDA breakthrough therapy designation status and narrow therapeutic index classification. Cost compression in the small-molecule tier intensifies as Indian and Chinese API suppliers expand volume contracts. Hospital systems show highest price sensitivity for maintenance-phase medications, while tertiary epilepsy centers absorb premium device pricing for refractory case protocols.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hub-and-spoke patterns for implantable pulse generators, with temperature-controlled logistics for biologic therapies. Active pharmaceutical ingredients draw from Indian and Chinese manufacturing clusters, while specialized electrode arrays source from Swiss and Japanese precision component suppliers. Single-source viral vector production creates vulnerability for gene therapy candidates targeting Dravet syndrome. Distribution runs through integrated delivery network central pharmacies for initiation-phase therapies, with retail and mail-order channels capturing stable maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA breakthrough therapy pathways and EMA pharmacovigilance burdens creates cost-differential opportunities for sponsors prioritizing United States market entry over European expansion.
For Market Incumbents: Acquire specialized viral vector manufacturing capacity to secure supply chain control for gene therapy pipelines targeting Lennox-Gastaut syndrome. Incumbent pharmaceutical manufacturers face substitution pressure from Indian API suppliers in the generic maintenance tier; backward integration into active pharmaceutical ingredient production preserves margin structure. Hospital formulary placement contracts require renewal investment as integrated delivery networks consolidate procurement authority.
For New Entrants and Emerging Players: Launch via decentralized clinical trial infrastructure leveraging wearable EEG remote monitoring to bypass tertiary center recruitment bottlenecks. Pediatric epilepsy indications in Japan and the United States offer the most penetrable regulatory pathways through PMDA and FDA pediatric exclusivity incentives. Target real-world evidence generation partnerships with academic medical centers to compress evidence timelines for neurostimulation device submissions.
For Investors and Strategic Acquirers: Consolidation pressure builds where biologic manufacturing concentration intersects with orphan drug pricing power and limited supplier alternatives. Long-term viability over the next decade favors platforms combining antibody therapies with neuromodulation device service bundling. Monitor FDA gene therapy approval velocity as the inflection signal for capital deployment timing into viral vector manufacturing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated pathways compress development timelines for Dravet syndrome therapies. |
| Neurostimulation Service Bundling | Surgical-procedure contracts with Cleveland Clinic and Mayo Clinic anchor implant volumes. |
| Pediatric Investigation Plan Filing | EMA requirements create regulatory exclusivity extensions for age-appropriate formulations. |
| Real-World Evidence Registry Development | Electronic health record data satisfies FDA breakthrough therapy evidentiary standards. |
| Viral Vector Manufacturing Scale-Up | In-house bioreactor capacity mitigates single-source supply risk for gene therapy candidates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Comparable historical periods anchored the projection framework across the analysis window, with segmentation dimensions spanning therapy type, patient age group, drug class, and distribution channel. CAGRs derived from fitted growth curves applied to patient prevalence data and treatment penetration rates. Modeled inputs incorporated neurostimulation implant volumes from tertiary epilepsy centers and antiepileptic drug procurement patterns through integrated delivery networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory pathway delays or viral vector supply disruptions. Forecasts reflect documented assumptions regarding patient diagnosis rates and therapy switching patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market