
 Global Urea Cycle Disorder Market | 2026-2036
Global Urea Cycle Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urea Cycle Disorder Market Foresight
Patient support programs and long-term therapy management services is expanding the addressable value pool beyond drug shipments alone. Recordati Rare Diseases leverages its rare disease commercial infrastructure across European metabolic centers. Ultragenyx Pharmaceutical anchors its position through sustained investment in gene therapy manufacturing scale. BioMarin Pharmaceutical dominates the enzyme replacement segment with deep clinical data packages that reinforce prescriber loyalty.
Urea cycle disorders comprise a group of six inherited enzymatic deficiencies that disrupt nitrogen excretion, causing toxic ammonia accumulation that demands immediate pharmacological intervention and lifelong dietary protein restriction. Ammonia scavengers such as sodium phenylbutyrate and glycerol phenylbutyrate function as alternative nitrogen disposal pathways, while emerging gene therapies target the underlying hepatic enzyme deficit. Enzyme replacement therapy commands the largest revenue share due to chronic administration requirements and premium pricing for orphan biologics. Gene therapy represents the fastest-expanding segment as clinical programs advance toward regulatory submission, though manufacturing complexity constrains near-term volume.
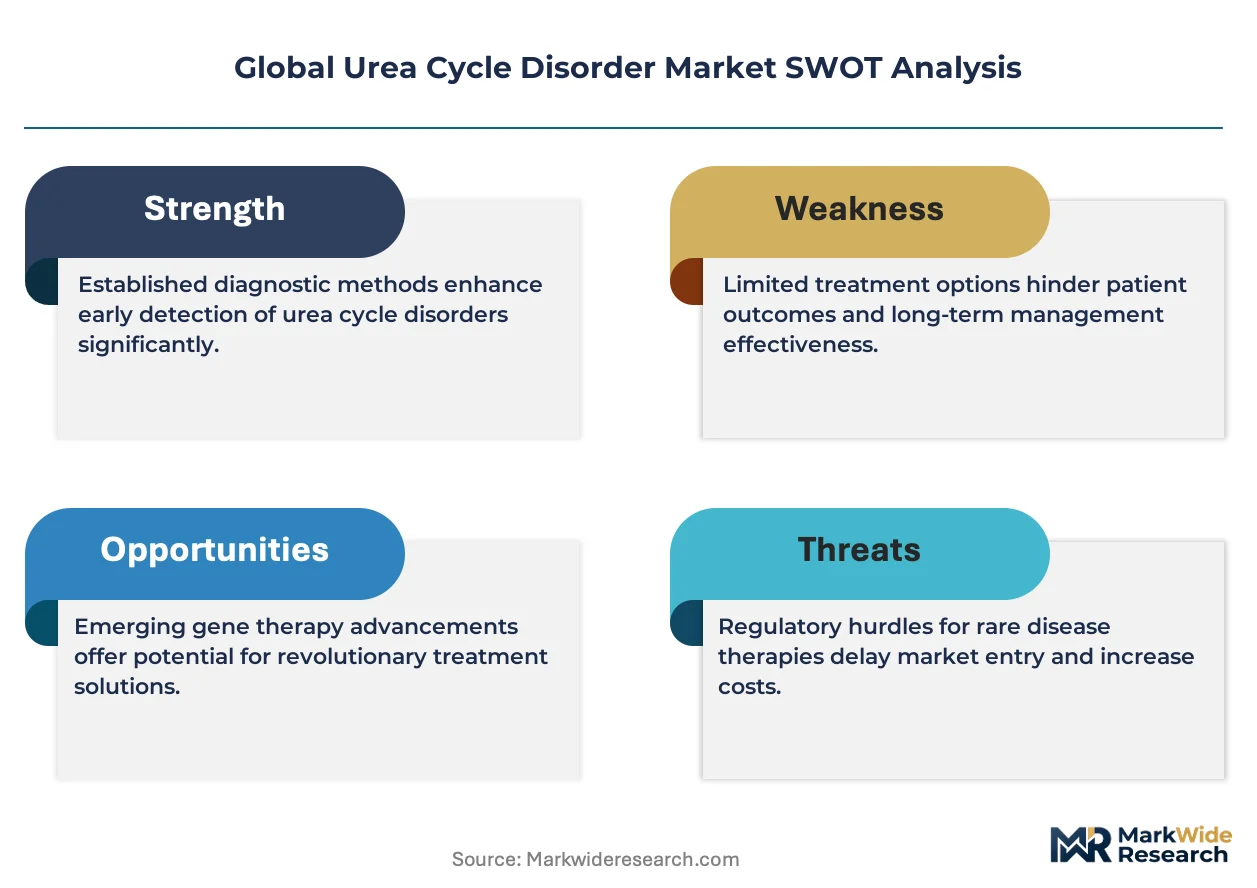
FDA orphan drug exclusivity provisions and EMA pediatric investigation plan mandates shape clinical trial investment and market access timelines for developers. The EU AI Act and GDPR impose emerging compliance burdens on digital biomarker tools and remote patient monitoring platforms used in metabolic disease management. Stakeholders must weigh manufacturing partnerships against captive gene therapy capacity decisions before pivotal trial readouts reshape competitive rankings.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines and forcing incumbents to choose between captive capacity investments and strategic outsourcing partnerships before pivotal trial data reshapes competitive rankings.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market exclusivity provisions accelerate clinical trial investment timelines for ultra-rare enzymatic deficiencies. Developers prioritize urea cycle disorder programs within rare disease portfolios.
- Pediatric metabolic clinic networks:Specialized treatment centers in the United States, Germany, and Japan drive ammonia scavenger therapy adoption through coordinated multidisciplinary care protocols.
- AAV vector manufacturing advances:Improved upstream bioprocessing yields and downstream purification efficiencies are reducing per-patient production costs for hepatic-directed gene therapies.
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers of GMP-grade plasmid DNA for AAV production create bottlenecks and price volatility for gene therapy developers.
- EU AI Act compliance burden:Algorithmic decision-making restrictions impose validation requirements on digital biomarker tools used for remote ammonia monitoring in metabolic disease management.
- Gene therapy durability uncertainty:Long-term expression persistence for hepatic enzyme replacement remains unproven, creating prescriber hesitation and payer skepticism about lifetime value propositions.
Strategic Opportunities
- Brazil rare disease regulatory pathway:ANVISA's accelerated approval framework for orphan indications offers first-mover positioning in Latin America's largest healthcare market.
- Continuous glucose monitoring convergence:Integration of real-time ammonia sensing with wearable metabolic monitoring platforms creates differentiated chronic disease management offerings.
- Patient registry data monetization:Longitudinal natural history databases built through academic metabolic center collaborations enable evidence generation for label expansion and payer negotiations.
Industry Challenges
- Gene therapy talent scarcity:Shortages of process development scientists and regulatory strategists with AAV manufacturing experience constrain program advancement timelines.
- Cross-border trial coordination complexity:Divergent pediatric investigation plan requirements between FDA and EMA create protocol amendment burdens and site activation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urea Cycle Disorder Market |
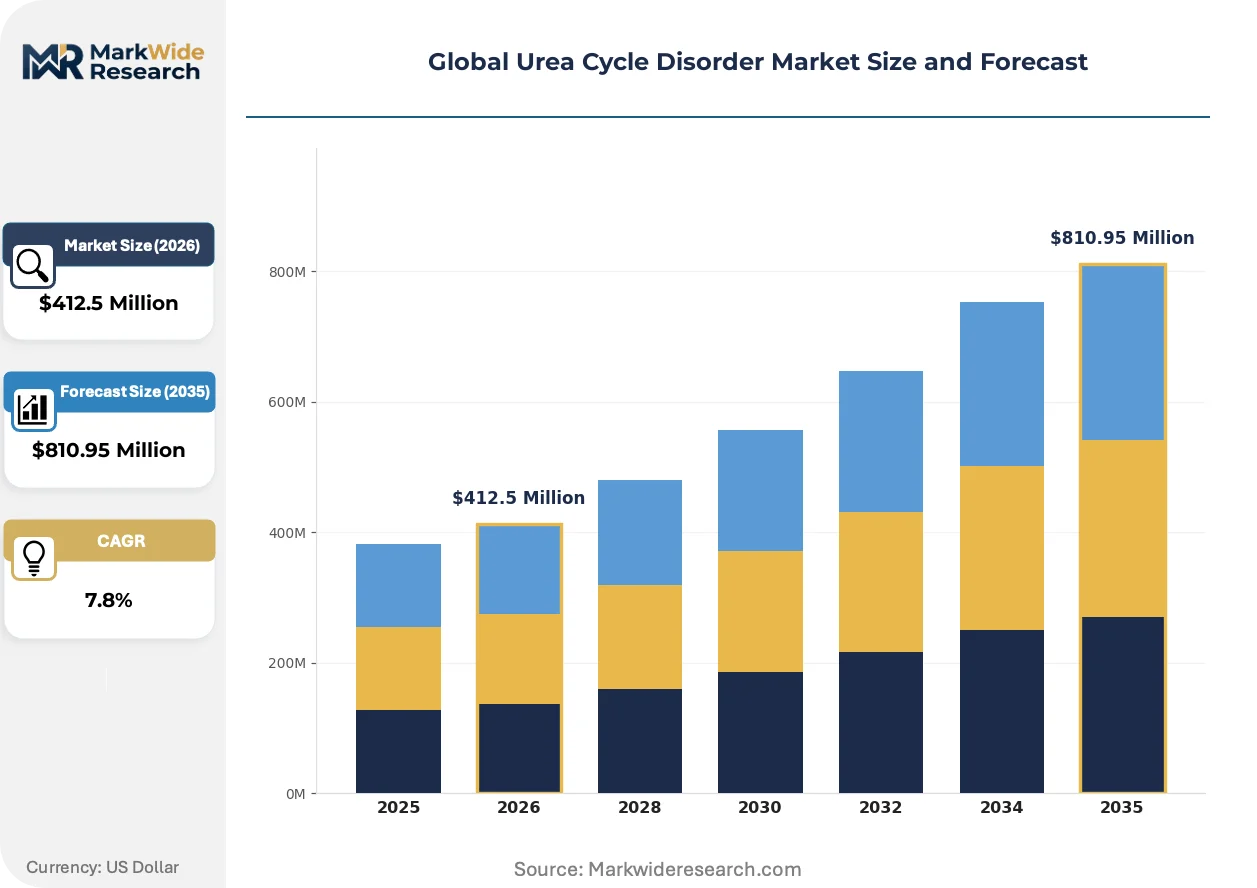
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Supplements, Enzyme Replacement Therapy, Gene Therapy, Ammonia Scavengers, Medical Foods Therapy Area: Hyperammonemia Management, Neonatal UCD, Late-Onset UCD, Liver Support, Metabolic Correction End User: Specialty Clinics, Genetic Counseling Centers, Pediatric Care Units, Metabolic Disorder Clinics, Diagnostic Laboratories Delivery Mode: Oral Administration, Intravenous Infusion, Subcutaneous Injection, Dietary Intake, Transdermal Application |
| Companies Covered | Bausch Health Companies Inc., Recordati Rare Diseases, Ultragenyx Pharmaceutical, Acer Therapeutics, Eurocept Pharmaceuticals Holding, BioMarin Pharmaceutical, Horizon Therapeutics Plc, Abbott Laboratories, Aeglea BioTherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urea Cycle Disorder Market Shifts & Advancements
Platform technologies are collapsing traditional boundaries between chronic pharmaceutical management and curative intervention models, forcing metabolic disease stakeholders to reconfigure service architectures and partnership strategies.
AAV5 and AAV8 capsid engineering is modularizing gene delivery specificity for hepatocyte-targeted enzyme expression. Academic centers and contract manufacturers are adopting standardized vector backbone designs to accelerate IND-enabling studies. This standardization is modularizing regulatory filing preparation and reducing chemistry-manufacturing-controls documentation burdens for second-generation programs.
EMA's pediatric investigation plan mandates now require longitudinal neurodevelopmental outcome tracking for metabolic disease therapies, extending trial durations and expanding endpoint portfolios. Sponsors must integrate cognitive assessment batteries and quality-of-life instruments into protocols previously focused on biochemical surrogates. European metabolic centers are responding by building dedicated neuropsychology cores within existing clinical research infrastructure.
Hospital procurement committees are consolidating ammonia scavenger purchasing through metabolic disease formulary carve-outs, displacing individual prescriber autonomy with centralized pharmacy and therapeutics review. Academic medical centers in the United States are piloting outcomes-based contracts linking sodium phenylbutyrate reimbursement to emergency department utilization reduction. This shift is most visible in integrated delivery networks with captive pediatric specialty pharmacy operations.
Global Urea Cycle Disorder Market Segmentation
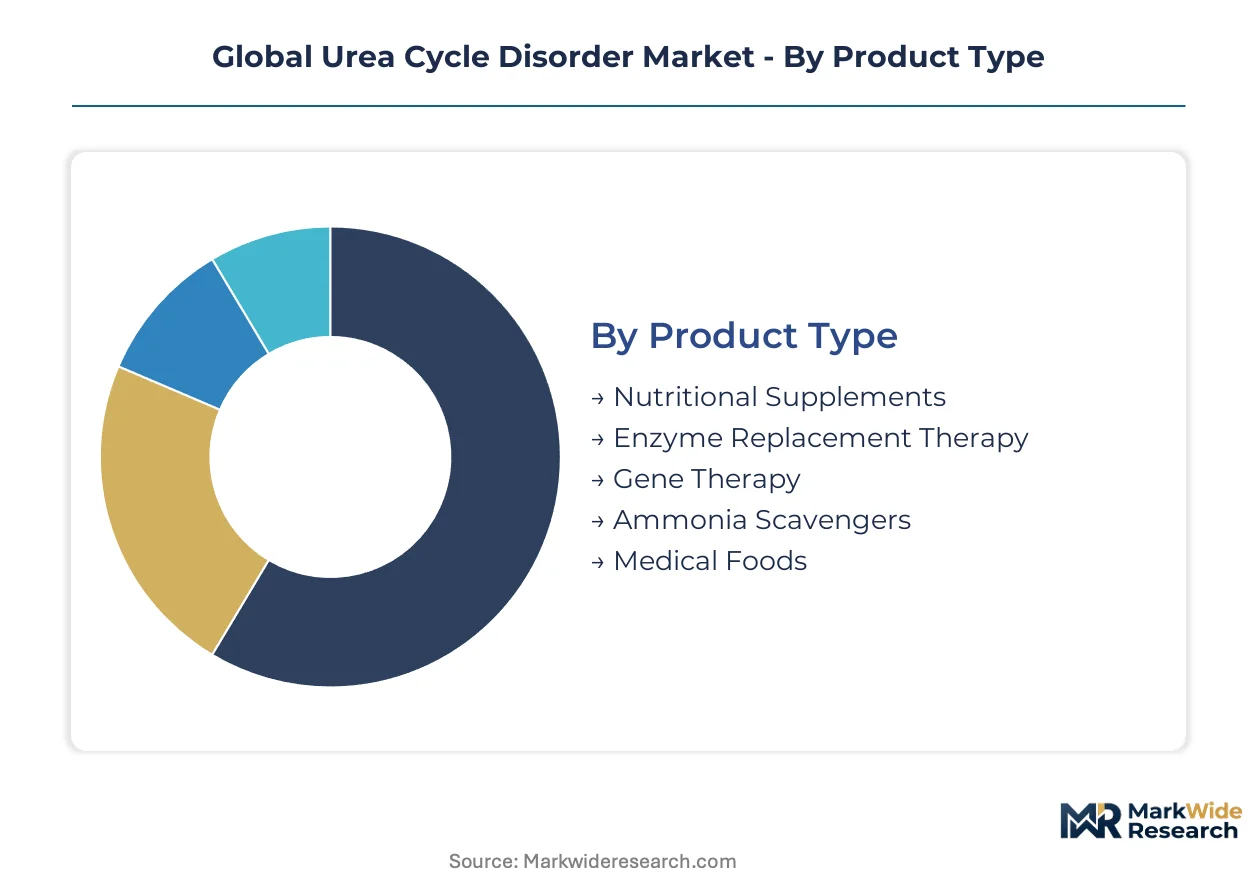
Urea cycle disorder therapeutics fragment across multiple technical and clinical axes that determine prescriber preference, reimbursement pathways, and manufacturing investment priorities. Each segmentation layer reveals distinct competitive dynamics between chronic management modalities and emerging curative interventions.
Product Type:
Technology maturity and regulatory pathway complexity define competitive positioning across the therapeutic portfolio.
- Enzyme Replacement Therapy:Recombinant phenylalanine ammonia-lyase and similar biologics require chronic intravenous or subcutaneous administration. Pediatric metabolic centers in the United States and Germany anchor demand due to established infusion infrastructure and favorable orphan drug reimbursement.
- Gene Therapy:AAV-delivered hepatic enzyme expression targets underlying genetic deficits with single-dose curative intent. Manufacturing scale constraints and durability questions temper near-term adoption despite transformative clinical potential.
- Ammonia Scavengers:Sodium phenylbutyrate and glycerol phenylbutyrate remain the pharmacological backbone for acute hyperammonemia episodes and chronic nitrogen disposal.
- Nutritional Supplements:Essential amino acid formulations and specialized protein-restricted diets support baseline metabolic management.
- Medical Foods:FDA-regulated products provide disease-specific nutritional support distinct from standard dietary supplements.
Enzyme replacement therapy leads on scale; gene therapy leads on momentum.
Therapy Area:
Clinical presentation timing and severity stratify intervention urgency and therapeutic modality selection.
- Hyperammonemia Management:Acute ammonia reduction protocols using scavenger drugs and dialysis represent the immediate intervention tier. Emergency departments and intensive care units in Japan and the United States drive protocol standardization.
- Neonatal UCD:Crisis presentation within 24-72 hours of birth demands rapid molecular diagnosis and aggressive metabolic stabilization. Specialized neonatal intensive care networks concentrate case volume.
- Late-Onset UCD:Adult presentations triggered by metabolic stress or pregnancy require differentiated diagnostic workups and chronic management protocols.
- Liver Support:Orthotopic transplantation and hepatocyte replacement address the most severe enzymatic deficiencies.
- Metabolic Correction:Curative approaches including gene therapy and liver-directed interventions target definitive disease modification.
Hyperammonemia management captures the highest acute intervention volume; neonatal UCD programs are climbing the fastest as newborn screening expands.
End User:
Care delivery setting determines patient access patterns and product distribution requirements.
- Metabolic Disorder Clinics:Dedicated centers coordinate multidisciplinary care including genetics, nutrition, and neurology. Academic medical centers in Germany and Japan maintain the deepest specialized infrastructure.
- Pediatric Care Units:Neonatal and pediatric wards manage acute decompensations and initiate long-term therapy.
- Specialty Clinics:General rare disease and genetics practices provide regional access points.
- Genetic Counseling Centers:Preconception and prenatal screening sites identify at-risk families.
- Diagnostic Laboratories:Molecular and biochemical testing facilities enable definitive diagnosis.
Metabolic disorder clinics lead on scale; pediatric care units lead on momentum.
Delivery Mode:
Route of administration shapes patient compliance, caregiver burden, and health economics.
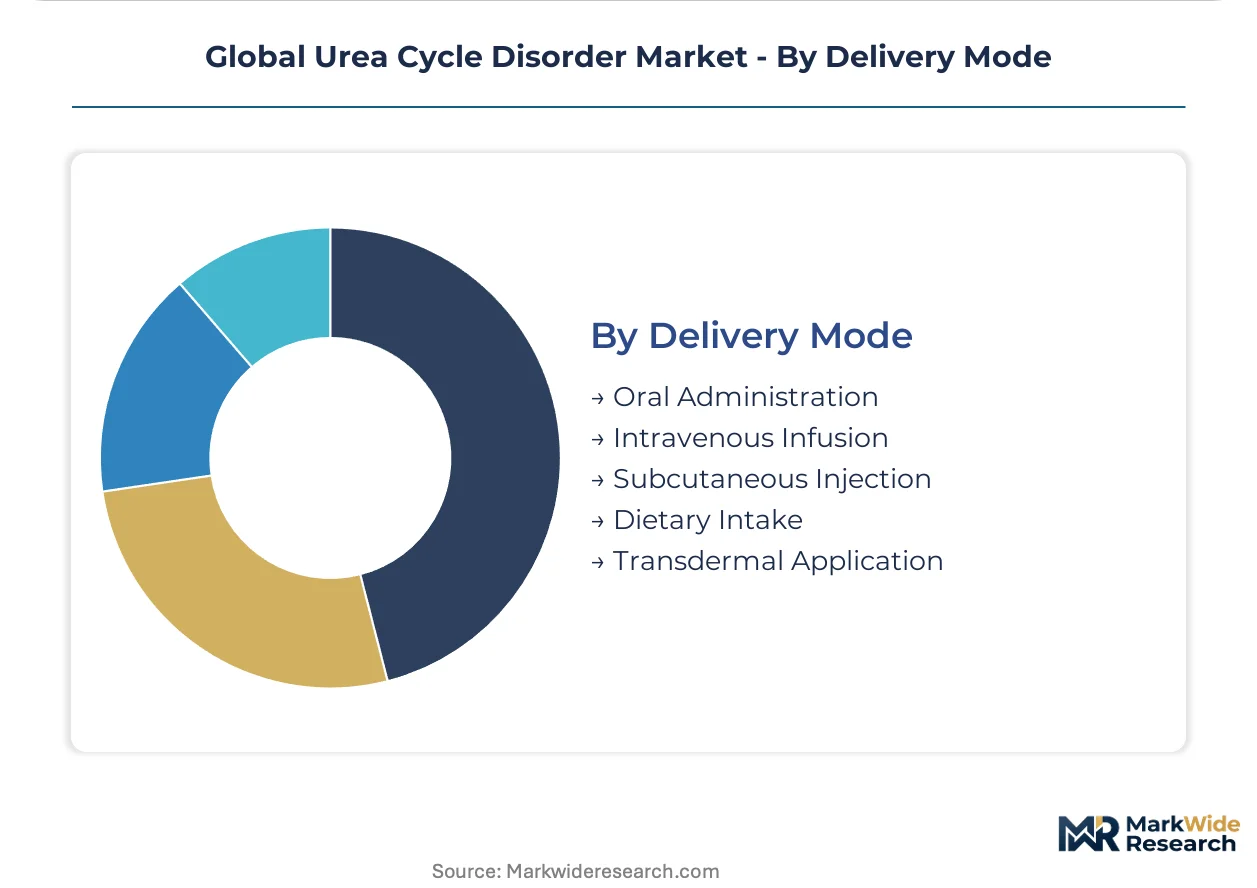
- Oral Administration:Sodium phenylbutyrate tablets and powders enable home-based chronic management. Palatability and pill burden limit adherence in pediatric populations.
- Intravenous Infusion:Acute hyperammonemia requires hospital-based sodium benzoate and sodium phenylacetate administration.
- Subcutaneous Injection:Emerging enzyme replacement and gene therapy delivery platforms target depot formulations.
- Dietary Intake:Medical foods and specialized nutrition integrate into daily metabolic control.
- Transdermal Application:Investigational patches for ammonia scavenger delivery address compliance barriers.
Oral administration leads on scale; subcutaneous injection leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan maintain deeper specialized metabolic center networks than Brazil, though each market deploys ammonia scavenger therapies through distinctly regulated procurement channels.
United States
Pediatric metabolic clinics at Boston Children's Hospital and Children's Hospital of Philadelphia anchor ammonia scavenger adoption through coordinated multidisciplinary protocols. FDA orphan drug exclusivity provisions accelerate clinical trial investment timelines for ultra-rare enzymatic deficiencies. The FDA's pediatric investigation plan mandates shape protocol designs that extend across academic medical centers in the Northeast and California.
Germany
Academic metabolic centers in Munich and Heidelberg drive coordinated care standardization for enzyme replacement therapies. EMA pediatric investigation plans require longitudinal neurodevelopmental outcome tracking that extends trial durations and expands endpoint portfolios. The EU AI Act imposes validation requirements on digital biomarker tools used for remote ammonia monitoring in metabolic disease management.
Japan
Specialized neonatal intensive care networks in Tokyo and Osaka concentrate case volume for crisis presentations within 24-72 hours of birth. METI and PMDA frameworks support accelerated pathways for hepatic-directed gene therapies targeting enzymatic deficiencies. Manufacturing partnerships with domestic contract development organizations are compressing gene therapy development timelines before pivotal trial readouts.
Brazil
ANVISA's accelerated approval framework for orphan indications offers first-mover positioning in Latin America's largest healthcare market. The country's national pharmaceutical regulator has streamlined import pathways for ammonia scavenger therapies previously unavailable through domestic distribution. São Paulo's academic medical centers are building dedicated metabolic disease units to capture regional patient volume from across the Southern Cone.
Global Urea Cycle Disorder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enzyme replacement and gene therapy developers commanding premium positioning through orphan biologic pricing while ammonia scavenger manufacturers face procurement committee consolidation. The vendor base organizes around three strategic archetypes: rare disease commercial infrastructure operators, gene therapy manufacturing scale investors, and chronic metabolic management incumbents. Dominant competitive moves include strategic outsourcing partnerships for AAV vector production and captive capacity investments ahead of pivotal trial data.
Among rare disease commercial infrastructure operators, Recordati Rare Diseases and Ultragenyx Pharmaceutical exemplify the European and North American anchoring positions. BioMarin Pharmaceutical occupies a position within the enzyme replacement tier that reinforces prescriber loyalty through deep clinical data packages. These three entities represent distinct geographic and therapeutic modality concentrations without overlapping operational footprints.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Recordati Rare Diseases |
| Ultragenyx Pharmaceutical |
| Acer Therapeutics |
| Eurocept Pharmaceuticals Holding |
| BioMarin Pharmaceutical |
| Horizon Therapeutics Plc |
| Abbott Laboratories |
| Aeglea BioTherapeutics |
| Others |
Supply & Pricing Matrix
Plasmid DNA costs cascade from limited GMP-grade suppliers through AAV vector production into gene therapy price premiums, while ammonia scavenger commoditization compresses margins for chronic management tiers.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for enzyme replacement therapies as BioMarin Pharmaceutical and Ultragenyx Pharmaceutical expand captive biologics manufacturing. Three-tier pricing structure across premium orphan biologics, standard ammonia scavengers, and economy nutritional supplements stratifies patient access by disease severity and reimbursement tier. Pricing pressure stems from hospital procurement committee consolidation of sodium phenylbutyrate purchasing through metabolic disease formulary carve-outs. Pediatric metabolic clinics demonstrate lowest price sensitivity due to orphan drug reimbursement guarantees, while adult late-onset segments face higher out-of-pocket exposure.
Supply Chain Analysis
Cold-chain logistics costs for AAV vectors and enzyme biologics concentrate distribution investment around specialized metabolic centers in Boston, Munich, and Tokyo. Manufacturing draws from plasmid DNA suppliers in the United States, viral vector production facilities in Germany, and fill-finish operations in Switzerland. Single-source vulnerability for GMP-grade plasmid DNA creates bottlenecks that propagate through gene therapy development timelines. Distribution runs through hospital specialty pharmacy networks and regional metabolic clinic hubs rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on AAV manufacturing yield improvements and premium-tier gene therapy pricing power displacing chronic scavenger dependence.
For Market Incumbents: Hedge gene therapy durability uncertainty by maintaining ammonia scavenger portfolios as bridge therapies while building outcomes-based contracts with integrated delivery networks. Secure captive plasmid DNA supply through strategic manufacturing partnerships before pivotal trial readouts reshape competitive rankings. Prioritize vertical integration into AAV upstream bioprocessing to defend against contract manufacturer capacity constraints. For New Entrants and Emerging Players: Enter via Brazil's ANVISA accelerated orphan pathway to establish Latin American metabolic disease infrastructure before established players consolidate regional access. Target neonatal UCD segments where newborn screening expansion creates addressable patient pools with limited incumbent presence. Pursue academic center co-development partnerships for neurodevelopmental outcome data that satisfies EMA pediatric investigation mandates. For Investors and Strategic Acquirers: Roll-up economics work for gene therapy platform specialists because manufacturing scale constraints and regulatory complexity deter fragmented competition. Five-to-ten year viability hinges on durability data from hepatic-directed AAV programs. Watch for liver enzyme expression persistence signals as the inflection indicator for lifetime value proposition validation.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Manufacturing Scale-Up | Captive vector production in Germany reduces per-patient costs and compresses development timelines for hepatic-directed programs. |
| Pediatric Investigation Plan Alignment | Coordinated FDA and EMA neurodevelopmental endpoint strategies accelerate regulatory submission pathways for metabolic disease therapies. |
| Hospital System Partnership | Academic medical center alliances in the United States enable outcomes-based sodium phenylbutyrate contracts tied to emergency department utilization. |
| Patient Registry Development | Longitudinal natural history databases through Munich and Heidelberg metabolic centers generate evidence for label expansion negotiations. |
| Brazil Market Entry | ANVISA orphan acceleration frameworks position first-movers to capture Southern Cone patient volume through São Paulo metabolic units. |
Research Methodology
Bottom-up metabolic clinic demand modeling reconciled against top-down AAV manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives at gene therapy sponsors, regulatory affairs leads managing pediatric investigation plans, formulary directors at academic medical centers, and hospital procurement managers overseeing metabolic disease carve-outs were validated against secondary sources including FDA orphan drug filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol registries, and hospital specialty pharmacy procurement databases.
Input-output matrices across therapy modality, patient presentation timing, and regional regulatory cluster dimensions drive volume and value projections over the analysis window. Segmentation modeling incorporates enzyme replacement administration frequency, gene therapy durability assumptions, and ammonia scavenger chronic utilization patterns. CAGRs derive from patient prevalence epidemiology, newborn screening expansion trajectories, and manufacturing capacity buildout schedules.
Inputs from regulatory filing databases and academic metabolic center collaborations were available through the study window; gaps in long-term gene therapy expression persistence data introduce uncertainty bands around curative intervention adoption curves. Forecasts reflect documented assumptions about AAV manufacturing yield improvements and reimbursement pathway evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market