
 Nonalcoholic Steatohepatitis Market | 2026-2036
Nonalcoholic Steatohepatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Nonalcoholic Steatohepatitis Market Intelligence
Small-molecule therapeutics is restructuring product economics in nonalcoholic steatohepatitis treatment, displacing earlier biologic-centric development models that carried heavier manufacturing burdens. Madrigal Pharmaceuticals leverages thyroid hormone receptor-beta selectivity to anchor its clinical positioning. Pfizer competes through broad metabolic disease infrastructure and established hepatology partnerships. Eli Lilly and Company differentiates via integrated diabetes-to-NASH patient pathway strategies.
Nonalcoholic steatohepatitis represents progressive liver inflammation and fibrosis occurring in non-alcoholic individuals, characterized by steatosis exceeding five percent hepatocyte involvement with ballooning degeneration and lobular inflammation. The condition serves as a precursor to cirrhosis and hepatocellular carcinoma, driving demand for interceptive pharmaceutical intervention. Pharmaceuticals dominates current revenue pools as multiple Phase III candidates approach regulatory submission, while Diagnostics captures accelerated investment following validation of non-invasive biomarker panels. Drug Therapy leads therapeutic modality selection, though Patient Monitoring segments are expanding fastest as payors demand real-world evidence of treatment response.
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for NASH-specific therapies, while WHO inclusion of fatty liver disease in global non-communicable disease targets is expanding addressable populations in lower-income settings. Rezdiffra's conditional approval under FDA accelerated pathways has established precedent for surrogate endpoint acceptance that subsequent sponsors must navigate. Stakeholders should monitor evolving fibrosis staging consensus between FDA and EMA, as harmonization would streamline multinational trial design and reshape capital allocation across development portfolios.
Market Dynamics
FDA accelerated approval pathways for breakthrough NASH therapies are compressing competitive timelines and forcing sponsors to build commercial infrastructure ahead of confirmatory data readouts.
Growth Catalysts
- EMA PRIME eligibility:European priority medicines designation grants enhanced regulatory support and accelerated assessment, reducing time-to-market for fibrosis-targeting therapies.
- Specialty hepatology clinics:These centers are expanding adoption of non-invasive diagnostic protocols including vibration-controlled transient elastography and MRI-PDFF quantification.
- WHO inclusion of fatty liver disease:Global non-communicable disease targets now incorporate metabolic liver conditions, expanding screening programs in lower-income health systems.
Market Restraints
- Surrogate endpoint validation:FDA requires histologic confirmation for full approval, creating uncertainty for sponsors relying on non-invasive biomarker strategies.
- Reimbursement complexity:Payers demand real-world evidence of cirrhosis prevention, delaying formulary placement for therapies approved on accelerated pathways.
- Diagnostic infrastructure gaps:Liver biopsy capacity constraints in community settings limit patient identification for specialty therapy enrollment.
Strategic Opportunities
- Integrated diabetes-to-NASH pathways:Endocrinology practices present underpenetrated referral channels for early-stage fibrosis intervention.
- Non-invasive biomarker panels:Blood-based fibrosis scores and proteomic signatures enable point-of-care screening expansion beyond hepatology centers.
- Patient monitoring platforms:Digital therapeutics and remote fibrosis tracking create recurring revenue models alongside pharmaceutical treatment.
Industry Challenges
- Histopathology reader variability:Centralized NASH Clinical Research Network scoring requirements create bottlenecks in Phase III trial execution.
- Cross-functional talent scarcity:Competition for hepatology clinical development expertise intensifies as multiple sponsors advance registrational programs simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonalcoholic Steatohepatitis Market |
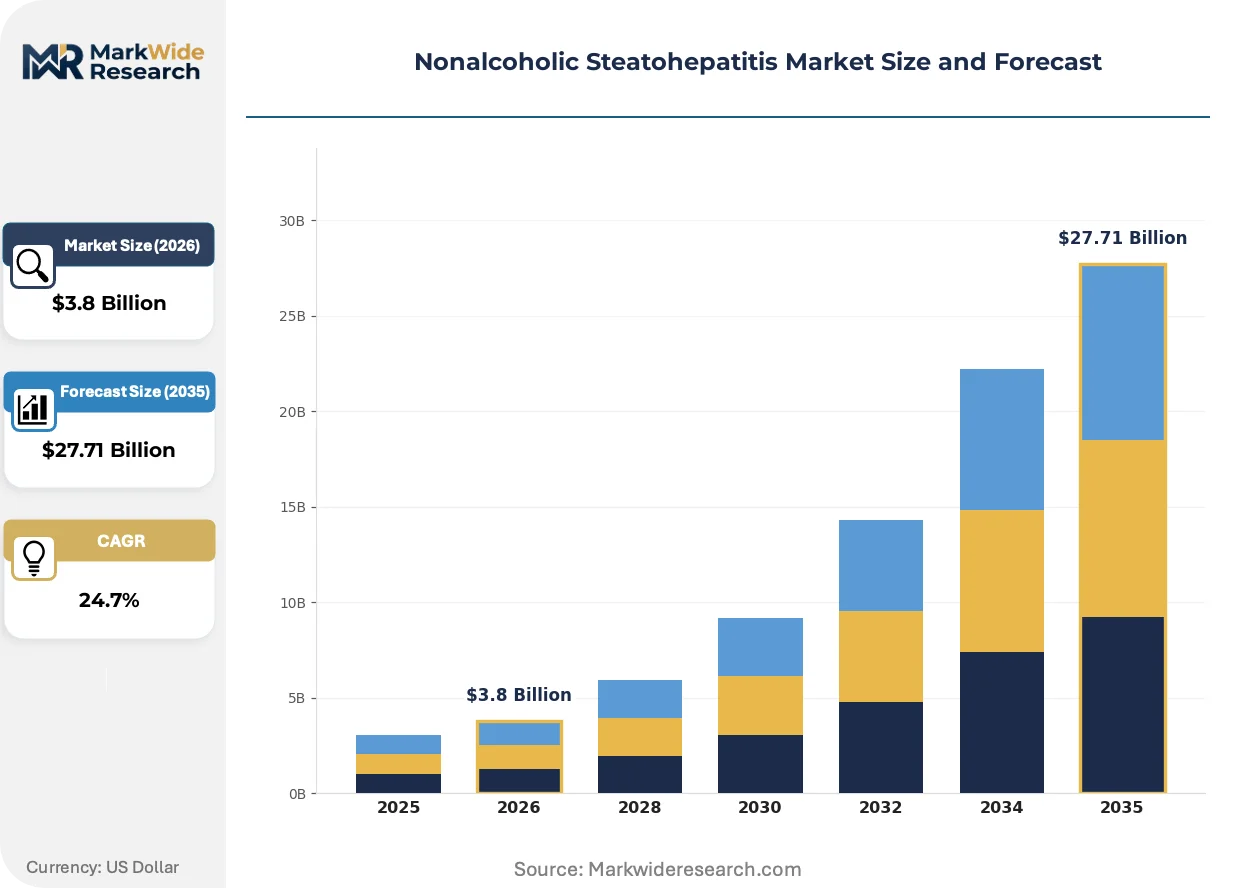
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutraceuticals, Diagnostics, Medical Devices Therapy Area: Drug Therapy, Lifestyle Modification, Surgical Intervention, Patient Monitoring End User: Hospitals, Clinics, Homecare Settings, Research Institutions Form: Tablet, Injection, Solution, Dietary Supplement |
| Companies Covered | Pfizer, AstraZeneca, Madrigal Pharmaceuticals, 89bio, Enyo Pharma, Eli Lilly and Company, Regeneron Pharmaceuticals, Galmed Pharmaceuticals, Novo Nordisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonalcoholic Steatohepatitis Market Strategic Shifts & Innovations
Artificial intelligence applications in liver imaging are restructuring how fibrosis staging occurs, compressing diagnostic timelines while reducing reliance on invasive procedures.
Magnetic resonance elastography combined with proton density fat fraction quantification is automating non-invasive liver assessment. Academic medical centers and large hepatology networks are deploying these platforms at scale for patient stratification. The technology is automating fibrosis monitoring workflows that previously required serial biopsy, enabling more frequent treatment response evaluation.
FDA breakthrough therapy designation criteria for NASH now explicitly incorporate histologic surrogate endpoints. This regulatory evolution permits conditional approval based on fibrosis improvement without cirrhosis outcomes data. Sponsors with late-stage assets are restructuring Phase III protocols to capture these accelerated pathways while building confirmatory outcome studies.
Integrated care contracts between payors and health systems are reshaping how NASH therapies are procured and reimbursed. Bundled payment models for metabolic liver disease management are displacing fee-for-service pharmaceutical purchasing in United States Medicare Advantage networks. California and Florida health systems are piloting outcomes-based agreements that tie therapy access to demonstrated fibrosis regression metrics.
Nonalcoholic Steatohepatitis Market Segmentation
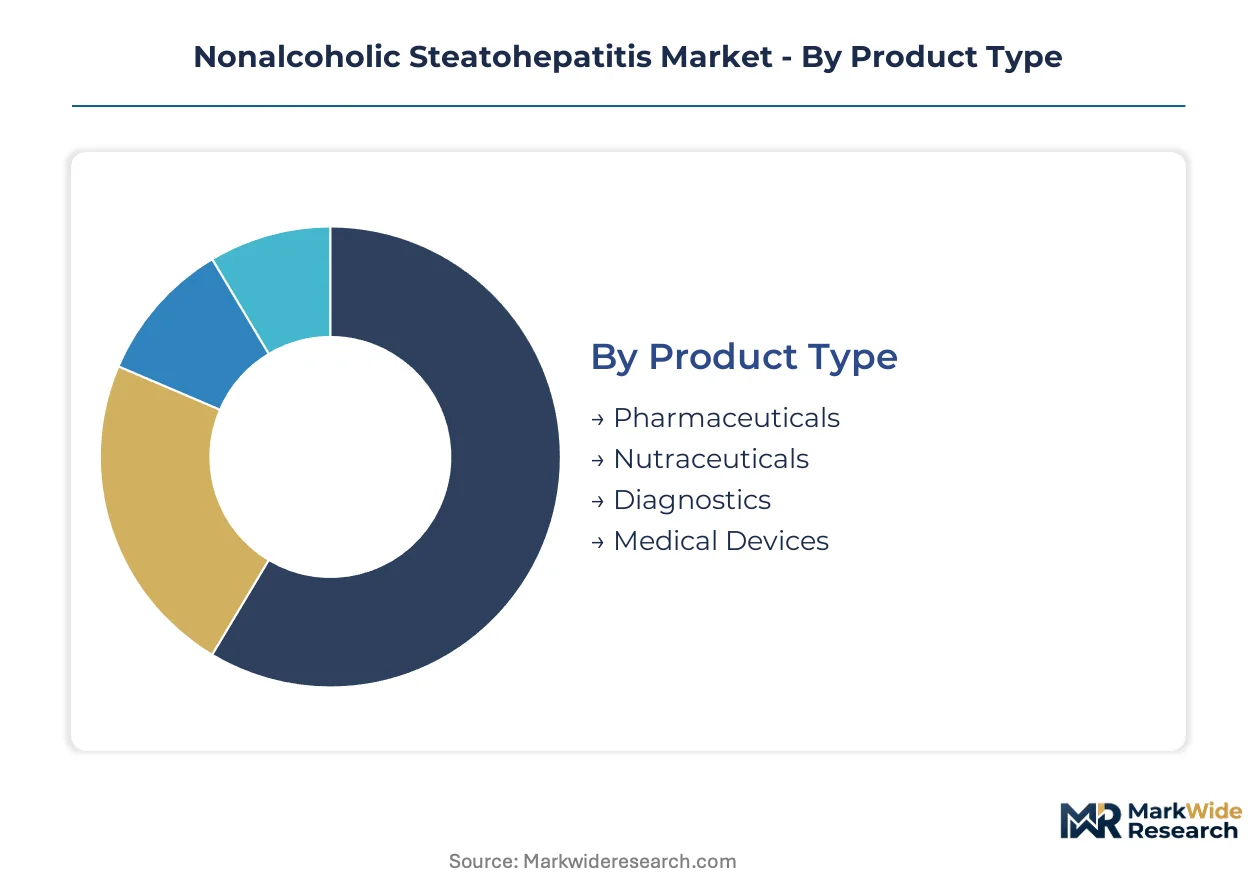
NASH market segmentation reflects divergent regulatory pathways across therapeutic and diagnostic categories. Product-level FDA approvals carry distinct evidentiary burdens compared to diagnostic platform clearances, reshaping how sponsors allocate development capital.
Product Type:
FDA breakthrough therapy designation applies selectively across this category, with small-molecule therapeutics facing accelerated review while diagnostic platforms navigate 510(k) or De Novo pathways depending on predicate availability.
- Pharmaceuticals:Small-molecule and biologic drug candidates dominate late-stage pipelines, with thyroid hormone receptor-beta agonists and GLP-1 receptor modulators advancing through Phase III. Demand concentrates in United States specialty hepatology clinics where Medicare Advantage reimbursement for fibrosis-targeting therapies has expanded.
- Diagnostics:Non-invasive biomarker panels and imaging platforms capture accelerated investment following validation of blood-based fibrosis scores and MRI-PDFF quantification methods. European EMA PRIME eligibility for companion diagnostic development is compressing timelines for integrated therapeutic-diagnostic submissions.
- Nutraceuticals:Vitamin E and omega-3 formulations occupy an ambiguous regulatory position between dietary supplements and investigational drugs.
- Medical Devices:Vibration-controlled transient elastography systems and portable ultrasound platforms enable point-of-care liver assessment outside tertiary centers.
Leading the category by volume: Pharmaceuticals. Growing fastest: Diagnostics.
Therapy Area:
Cost tier stratification separates acute intervention from chronic management, with surgical procedures commanding premium reimbursement while monitoring platforms compete on per-patient-per-month subscription economics.
- Drug Therapy:Systemic pharmacologic intervention targets metabolic drivers and fibrogenic pathways simultaneously. Rezdiffra's conditional FDA approval established precedent for surrogate endpoint acceptance, though confirmatory outcome studies remain mandatory for full approval.
- Patient Monitoring:Digital therapeutics and remote fibrosis tracking platforms create recurring revenue models alongside pharmaceutical treatment. California and Florida health systems pilot outcomes-based agreements tying therapy access to demonstrated regression metrics.
- Lifestyle Modification:Structured weight management and exercise protocols serve as first-line intervention in European clinical guidelines.
- Surgical Intervention:Bariatric surgery and liver transplantation represent terminal options for decompensated cirrhosis patients.
Highest reimbursement tier: Surgical Intervention. Steepest expansion trajectory: Patient Monitoring.
End User:
Patient volume distributes unevenly across care settings, with community-based identification bottlenecks limiting enrollment into specialty therapy protocols despite disease prevalence.
- Clinics:Specialty hepatology and endocrinology practices serve as gatekeepers for advanced therapy access. United States Medicare Advantage networks in California and Florida are piloting integrated care contracts that bundle metabolic liver disease management.
- Hospitals:Academic medical centers deploy MRI-PDFF and magnetic resonance elastography at scale for patient stratification and trial enrollment.
- Homecare Settings:Remote monitoring and digital therapeutic delivery expand access beyond tertiary centers.
- Research Institutions:Centralized NASH Clinical Research Network scoring requirements create execution bottlenecks for Phase III trials.
Primary volume concentration: Clinics. Gaining share fastest: Homecare Settings.
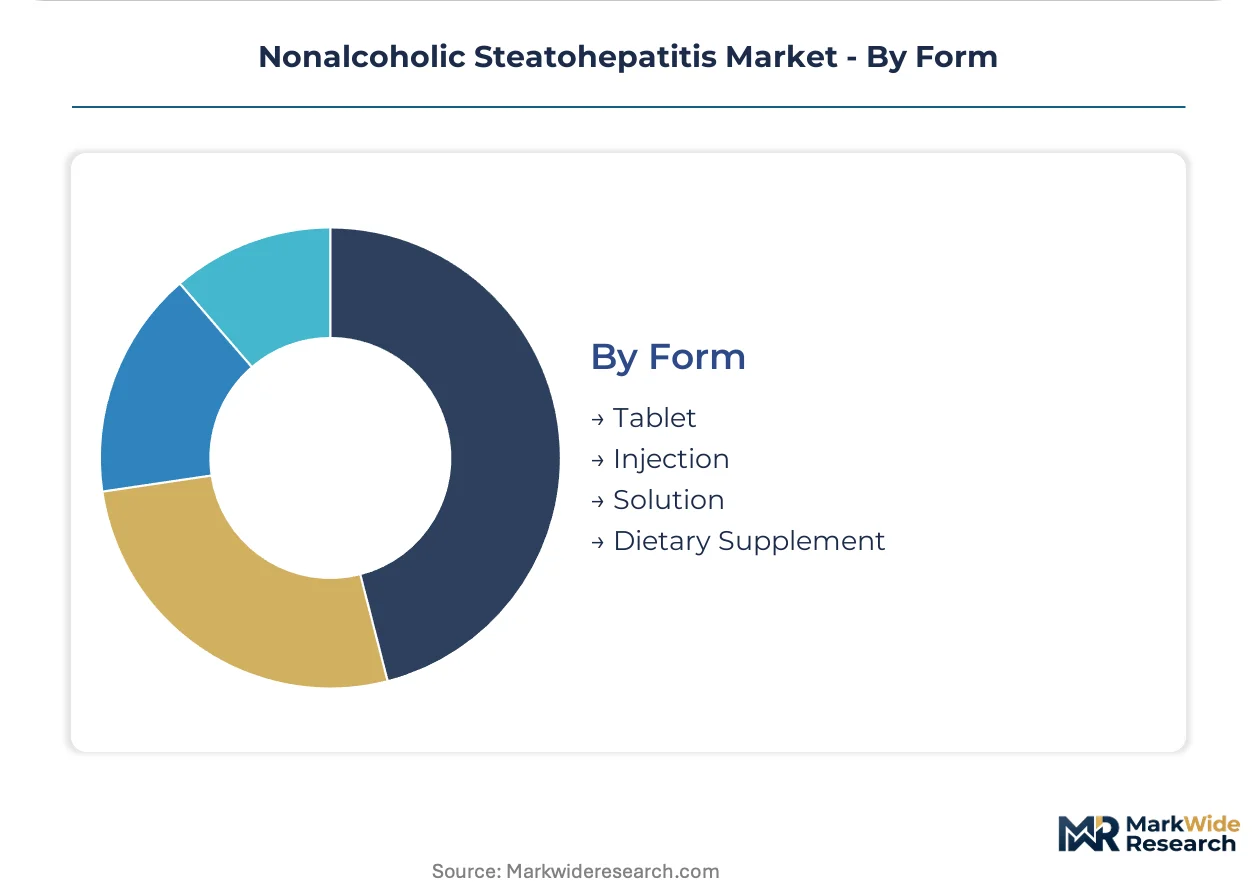
Form:
Manufacturing complexity and cold-chain requirements differentiate delivery mechanisms, with oral formulations enabling broad distribution while injectable biologics concentrate in specialty pharmacy channels.
- Tablet:Oral small-molecule therapeutics enable decentralized prescribing and retail pharmacy distribution. Madrigal Pharmaceuticals' resmetirom leverages once-daily oral dosing to differentiate from injectable metabolic therapies.
- Injection:GLP-1 receptor agonists and biologic candidates require cold-chain logistics and specialty administration. Eli Lilly's integrated diabetes-to-NASH pathway strategies position injectable assets for endocrinology practice adoption.
- Solution:Liquid formulations accommodate pediatric populations and patients with swallowing difficulties.
- Dietary Supplement:Over-the-counter positioning circumvents prescription regulatory requirements but limits reimbursement access.
Dominant by prescription volume: Tablet. Climbing the fastest: Injection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty hepatology clinics concentrate the highest patient volumes for advanced NASH therapy enrollment. Medicare Advantage reimbursement structures in California and Florida health systems are piloting bundled payment models for metabolic liver disease management.
United States
FDA accelerated approval pathways for breakthrough NASH therapies are compressing development timelines for sponsors. The agency's conditional approval of Rezdiffra established precedent for surrogate endpoint acceptance in fibrosis-targeting drugs. Massachusetts and California academic medical centers deploy MRI-PDFF and magnetic resonance elastography at scale for patient stratification and clinical trial enrollment.
Germany
EMA PRIME eligibility grants enhanced regulatory support for fibrosis-targeting therapies seeking European market access. The country's national pharmaceutical regulator prioritizes accelerated assessment for drugs addressing unmet needs in metabolic liver disease. Bavaria and North Rhine-Westphalia host specialized hepatology networks that integrate non-invasive diagnostic protocols into routine diabetes care pathways.
Japan
PMDA breakthrough designation criteria for NASH now explicitly incorporate histologic surrogate endpoints similar to FDA precedent. METI funding programs support domestic development of non-invasive biomarker panels for point-of-care liver assessment. Tokyo and Osaka metropolitan areas concentrate the nation's hepatology clinical trial infrastructure and specialized diagnostic imaging capacity.
United Kingdom
NICE technology appraisal processes are evolving to accommodate therapies approved on accelerated pathways with pending confirmatory data. The country's national health service pilots integrated care contracts that bundle metabolic liver disease management across primary and specialty settings. London and the Southeast region anchor the highest concentration of hepatology research institutions and centralized NASH Clinical Research Network scoring facilities.
China
NMPA priority review pathways for innovative drugs are expanding to include NASH-specific therapies with China-specific clinical data packages. The regulator's evolving standards for surrogate endpoint acceptance are reshaping how multinational sponsors design regional Phase III protocols. Yangtze River Delta medical centers are deploying vibration-controlled transient elastography systems at scale for community-based patient identification.
Nonalcoholic Steatohepatitis Market Key Industry Players
Strategic partnerships dominate the current landscape as sponsors seek to combine metabolic disease infrastructure with hepatology development expertise. The competitive structure fragments across three distinct tiers: large pharmaceutical conglomerates with broad metabolic portfolios, mid-cap biotech specialists focused on liver-targeted mechanisms, and emerging platforms pursuing novel fibrogenic pathway modulation. Two strategic archetypes define positioning: integrated diabetes-to-NASH pathway builders and selective thyroid hormone receptor-beta agonist developers. Capacity expansion in diagnostic infrastructure and technology licensing for non-invasive biomarker platforms represent the dominant competitive moves reshaping alliance patterns.
Within the large-cap metabolic infrastructure tier, Pfizer and Eli Lilly and Company exemplify divergent strategic positioning. Pfizer occupies a position anchored in established hepatology partnerships and broad clinical development networks. Eli Lilly and Company represents the integrated pathway archetype, leveraging diabetes care infrastructure to capture early-stage fibrosis patients through endocrinology referral channels. Madrigal Pharmaceuticals sits within the selective mechanism specialist tier, with its development focus centered on thyroid hormone receptor-beta selectivity as a clinical differentiation anchor.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Madrigal Pharmaceuticals |
| 89bio |
| Enyo Pharma |
| Eli Lilly and Company |
| Regeneron Pharmaceuticals |
| Galmed Pharmaceuticals |
| Novo Nordisk |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient costs for thyroid hormone receptor-beta agonists and GLP-1 receptor modulators cascade through formulation, cold-chain logistics, and specialty pharmacy markups before reaching Medicare Advantage formularies and European national health systems. This input-cost progression creates divergent pricing tiers between oral small-molecule tablets and injectable biologics, with manufacturing complexity and distribution infrastructure requirements determining final reimbursement negotiations.
Pricing Analysis
Volume concentration in oral tablet formulations competes against margin capture in injectable metabolic therapies requiring specialty administration. Pricing stratifies across premium biologic tiers anchored by cold-chain logistics and standard oral tiers enabled by retail pharmacy distribution. Cost compression in the tablet segment intensifies as multiple sponsors advance Phase III candidates simultaneously. Community hepatology clinics exhibit highest price sensitivity due to formulary budget constraints, while academic medical centers demonstrate lowest sensitivity given bundled payment pilot structures.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics involve returns processing, cold-chain refurbishment, and remanufacturing protocols that add 15-20% overhead to specialty pharmacy operations. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for small-molecule candidates, while biologic cell culture and fill-finish capacity clusters in Ireland, Singapore, and the United States. Supply chain vulnerability rests on single-source dependencies for recombinant protein production. Distribution runs through specialty pharmacy channels for injectables and retail networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive diagnostic protocols are displacing liver biopsy as the standard for fibrosis staging, creating technology-transition investment windows across imaging platforms, blood-based biomarker panels, and integrated care delivery systems.
For Market Incumbents: Cement control over endocrinology referral channels before GLP-1 receptor agonist sponsors complete diabetes-to-NASH pathway integration. Lock in exclusive MRI-PDFF and magnetic resonance elastography placement contracts with California and Florida Medicare Advantage networks. Counter the threat of non-invasive biomarker point-of-care expansion by acquiring vibration-controlled transient elastography platform operators in community clinic settings.
For New Entrants and Emerging Players: Launch via direct-to-specialist digital therapeutics models targeting homecare monitoring segments where incumbent pharmaceutical sponsors lack bundled service infrastructure. Exploit underpenetrated European primary care pathways in Germany and the United Kingdom where diabetes screening protocols can incorporate fibrosis risk stratification. Prioritize blood-based proteomic signature development for EMA PRIME-eligible companion diagnostic submissions.
For Investors and Strategic Acquirers: FDA confirmatory outcome study readouts for Rezdiffra and subsequent accelerated approval conversions are the leading indicator that full approval revenue multiples will expand across the NASH therapeutic category. Position portfolios for 5-10 year holding periods spanning surrogate endpoint acceptance maturation through cirrhosis prevention outcomes validation. Target acquisition profiles centered on integrated diagnostic-therapeutic platform developers with proprietary non-invasive biomarker IP. Monitor EMA-FDA fibrosis staging harmonization negotiations as the critical regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval for surrogate endpoints compresses competitive timelines for fibrosis-targeting therapies. |
| Clinical Trial Advancement | Phase III protocol designs incorporating non-invasive biomarker endpoints reduce patient identification bottlenecks. |
| Licensing Agreement | Diagnostic platform licensing to pharmaceutical sponsors enables integrated therapeutic-diagnostic submissions. |
| Manufacturing Scale-Up | Cold-chain capacity expansion supports GLP-1 receptor agonist supply for endocrinology practice penetration. |
| Pipeline Diversification | Thyroid hormone receptor-beta selectivity programs hedge against metabolic pathway competition from diabetes franchises. |
Research Approach
Multi-period observation of FDA accelerated approval decisions, EMA PRIME eligibility grants, and Medicare Advantage formulary placements anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States payors, and hepatology clinical investigators. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Input-output matrices structured the forecast framework across therapy area, product type, end user setting, and geographic regulatory cluster dimensions. CAGRs were derived from segmented growth rate differentials applied to base-year revenue pools. Forecast inputs incorporated Phase III trial enrollment velocity, surrogate endpoint validation timelines, and non-invasive diagnostic adoption curves.
Regulatory pathway reversals, confirmatory study failure rates, and reimbursement negotiation delays are the dominant revision risks to projection assumptions. Practitioners should monitor FDA-EMA fibrosis staging harmonization progress and Medicare Advantage bundled payment expansion metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market