
 Diffuse Large B-Cell Lymphoma Therapeutics Market | 2026-2036
Diffuse Large B-Cell Lymphoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Diffuse Large B-Cell Lymphoma Therapeutics Market Analysis
Antibody-drug conjugates are rebalancing first-line treatment economics away from conventional chemotherapy backbones. Roche leverages its diagnostic-therapeutic pairing to sustain premium positioning across the DLBCL care pathway. Bristol Myers Squibb anchors the CAR T-cell segment through manufacturing scale and approved indications. AbbVie differentiates via its bispecific antibody platform, competing in relapsed and refractory settings without autologous cell collection requirements.
Diffuse large B-cell lymphoma therapeutics comprise systemic agents designed to eradicate malignant B-lymphocytes through targeted cytotoxicity, immune modulation, or genetic reprogramming, with CAR T-cell products requiring leukapheresis, cryopreservation, and lymphodepletion preconditioning before infusion. These therapies serve the primary purpose of inducing durable remission in aggressive non-Hodgkin lymphoma where anthracycline-based regimens fail. Monoclonal antibodies occupy the largest revenue pool due to rituximab biosimilar erosion and obinutuzumab uptake in combination protocols. CAR T-cell therapy represents the fastest-growing drug type as manufacturing capacity expands and outpatient administration models mature. Intravenous administration dominates volume, though subcutaneous formulations are gaining traction in maintenance settings for patient convenience.
The FDA's accelerated approval and breakthrough therapy designation programs compress development timelines for novel DLBCL agents, while EMA's PRIME scheme shapes European market sequencing and reimbursement negotiations. Health Canada and the UK's MHRA align on post-market safety monitoring for cytokine release syndrome, constraining label expansion for high-potency immunotherapies. Stakeholders must monitor how real-world evidence requirements for confirmatory trials reshape investment thresholds in the relapsed-refractory pipeline.
Market Dynamics
FDA accelerated approval pathways compress development timelines for novel DLBCL agents, while manufacturing scale constraints for autologous cell therapies create supply-demand asymmetries that reshape competitive positioning across the care pathway.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework reduces clinical-to-commercial lag for CAR T-cell products, compressing investor payback periods.
- Leukapheresis network densification:Academic medical centers in the United States are adding dedicated apheresis units, expanding patient access to cell-based interventions.
- Real-world evidence mandates:Post-market confirmatory trial requirements under FDA guidance are institutionalizing observational study infrastructure.
Market Restraints
- Viral vector supply concentration:Lentiviral and retroviral vector production concentrates among three contract manufacturers, creating single-source vulnerabilities for CAR T-cell developers.
- Cytokine release syndrome monitoring:FDA-mandated Risk Evaluation and Mitigation Strategies impose 24-hour post-infusion hospitalization requirements that limit outpatient adoption.
- Rituximab biosimilar erosion:Reference product revenue compression in first-line settings redirects R&D investment toward relapsed-refractory indications.
Strategic Opportunities
- Allogeneic platform development:Off-the-shelf CAR T-cell products eliminate leukapheresis logistics, opening community oncology clinic channels.
- Subcutaneous administration formats:Bispecific antibodies delivered via subcutaneous injection reduce infusion chair time and shift site-of-care economics.
- Japan's Sakigake designation:PMDA priority review incentives attract early-phase trials, creating geographic diversification for pipeline assets.
Industry Challenges
- Vector manufacturing scale-up:Suspension bioreactor technology transfer from stainless-steel platforms requires 18-24 month validation timelines.
- Cross-border cryopreservation logistics:Temperature excursion risks during international cell product transport complicate multi-site manufacturing networks.
- Confirmatory trial enrollment:Accelerated approval conversions face patient recruitment competition from newer pipeline entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diffuse Large B-Cell Lymphoma Therapeutics Market |
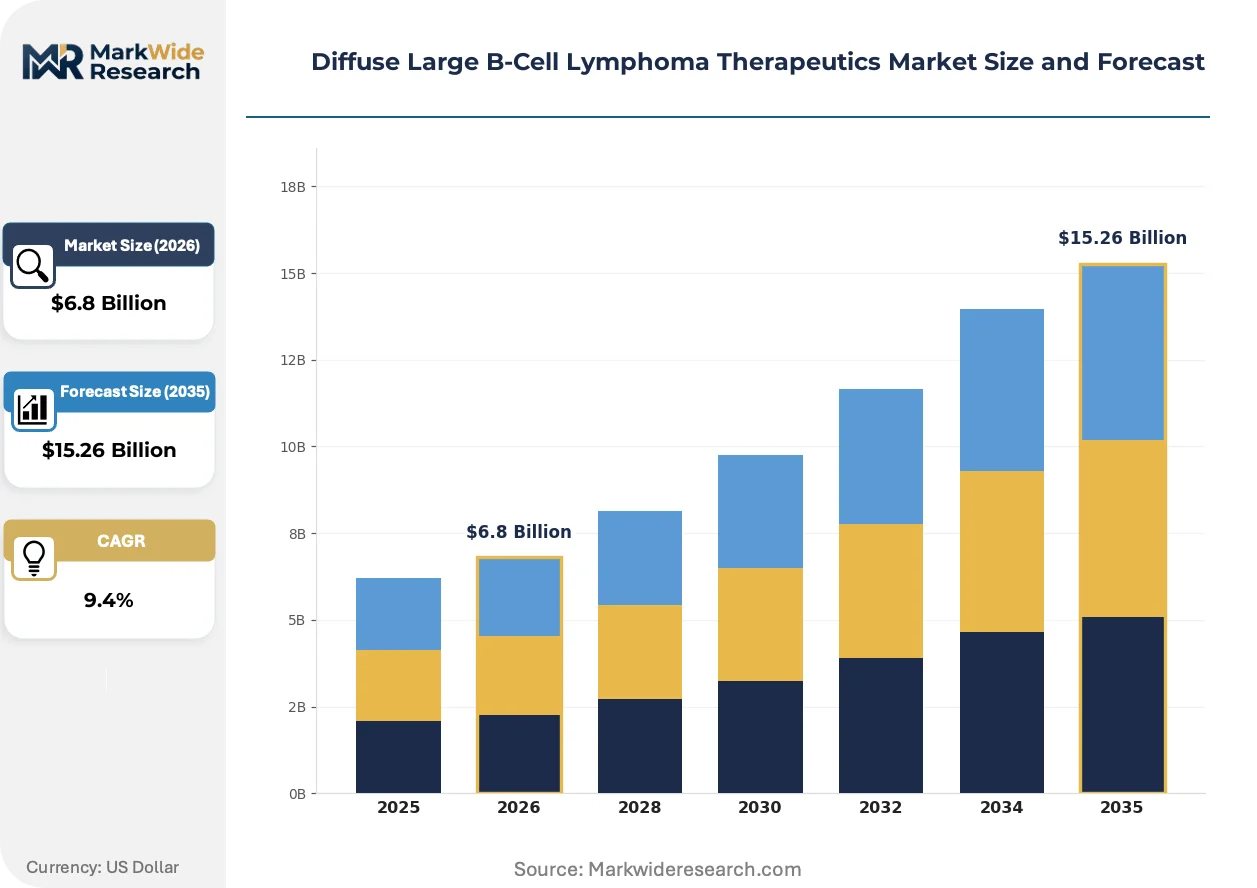
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Monoclonal Antibodies, Chemotherapy, CAR T-Cell Therapy, Immune Checkpoint Inhibitors Administration Route: Intravenous, Subcutaneous, Oral, Intrathecal End User: Hospitals, Specialty Clinics, Research Laboratories, Homecare Stage of Treatment: First-line Therapy, Second-line Therapy, Maintenance Therapy, Palliative Care |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Gilead Sciences, Inc., Pfizer Inc., Merck & Co., Inc., Bristol Myers Squibb Company, AbbVie Inc., ADC Therapeutics SA, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diffuse Large B-Cell Lymphoma Therapeutics Market Emerging Trajectories
Modular manufacturing architectures are reconfiguring how cell therapies move from bench to bedside, while regulatory convergence around real-world evidence standards is compressing traditional validation cycles across major markets.
Chimeric antigen receptor constructs incorporating synthetic biology elements are modularizing vector design workflows, enabling rapid retargeting against novel tumor antigens. Contract development organizations are adopting plug-and-play plasmid systems to shorten GMP timeline commitments. This modularity is fragmenting the historically integrated CAR T-cell value chain into separable component supply tiers.
The European Medicines Agency's PRIME scheme is conditioning European launch sequencing on early health technology assessment engagement, forcing developers to embed payer evidence generation into Phase II protocols. Manufacturers now face parallel regulatory and reimbursement dossier preparation. France's ANSM and Germany's BfArM are implementing divergent post-authorization study requirements that complicate pan-European labeling strategies.
Site-of-care economics are compressing as hospital outpatient departments consolidate infusion services into specialized immuno-oncology units. United States-based health systems are unbundling CAR T-cell administration from academic referral centers, shifting eligible patients toward community hospital settings. This geographic decentralization is most visible in Texas and Florida, where certificate-of-need restrictions on specialized beds are weakest.
Diffuse Large B-Cell Lymphoma Therapeutics Market Segmentation
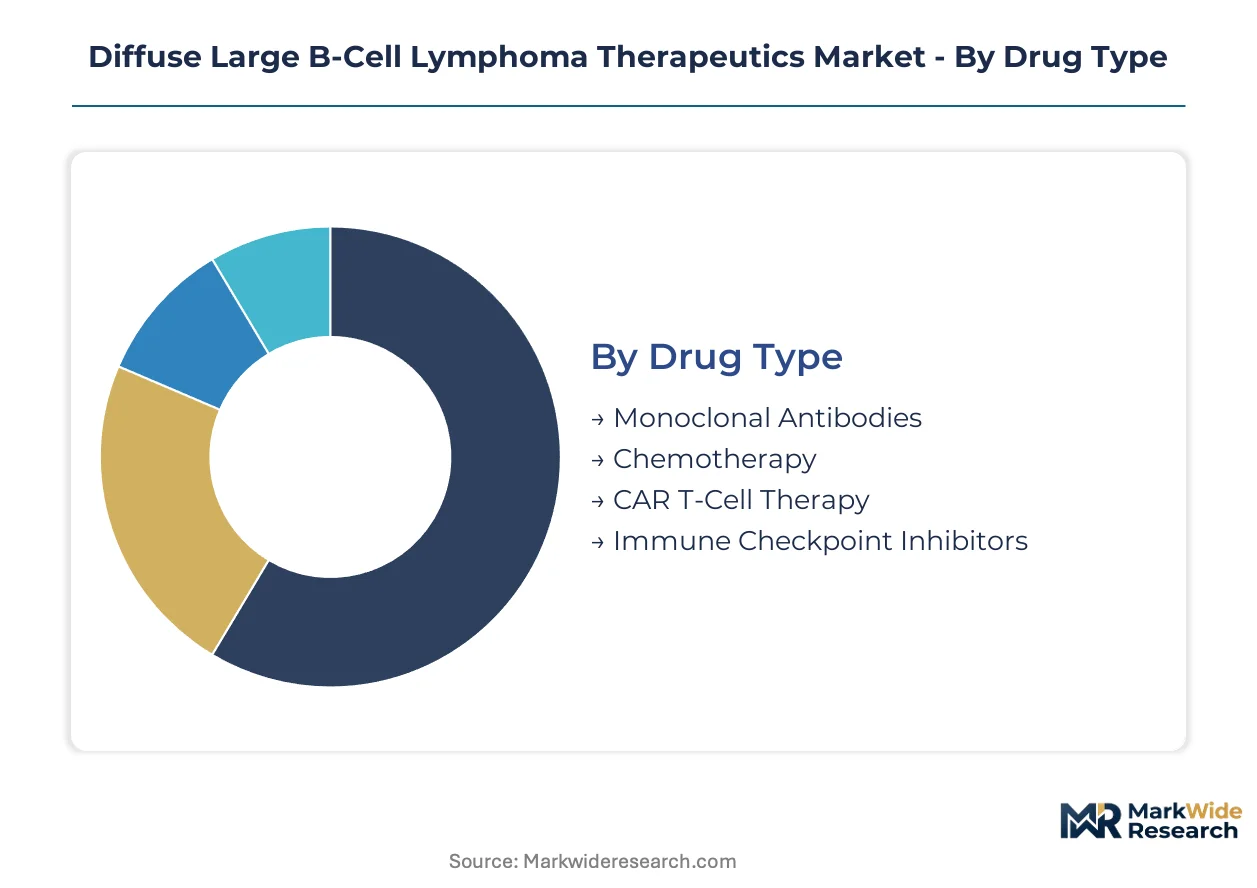
Segmentation in DLBCL therapeutics reveals how treatment modalities split between established infrastructure and emerging delivery platforms. Drug type classifications track the shift from cytotoxic backbones toward immune-modulating biologics. Route and setting dimensions expose where site-of-care economics favor hospital consolidation versus decentralized administration.
Drug Type:
Integration depth separates standalone agents requiring minimal biomarker support from complex modalities embedded within diagnostic-guided care pathways.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD20 surface antigens on malignant B-cells, administered in combination with chemotherapy backbones. Demand concentrates in United States hospital outpatient departments where rituximab biosimilar substitution has compressed margins and shifted volume toward obinutuzumab-containing protocols in academic medical centers.
- CAR T-Cell Therapy:Autologous cellular products requiring leukapheresis, ex vivo genetic modification, and lymphodepletion preconditioning. Manufacturing scale constraints in lentiviral vector production limit patient access to specialized academic centers in Texas, Florida, and California where apheresis infrastructure is densest.
- Chemotherapy:Anthracycline-based cytotoxic regimens (R-CHOP backbone) delivered in cyclic infusion schedules.
- Immune Checkpoint Inhibitors:PD-1/PD-L1 antagonists modulating tumor microenvironment immune evasion.
Volume placements concentrate in Monoclonal Antibodies; the faster expansion belongs to CAR T-Cell Therapy.
Administration Route:
Cost tier stratification distinguishes capital-intensive infusion infrastructure from lower-touch delivery formats suitable for community penetration.
- Intravenous:Direct vascular delivery requiring specialized infusion chairs, nursing oversight, and emergency resuscitation capacity. Hospitals in Germany and France maintain highest per-capita IV infusion capacity for oncology, though United States sites are consolidating into dedicated immuno-oncology units to capture CAR T-cell administration revenue.
- Subcutaneous:Depot-formulation biologics enabling reduced chair time and ambulatory administration. Bispecific antibody uptake in United Kingdom day-case oncology units is accelerating as NHS England reimbursement separates administration fees from drug acquisition costs.
- Oral:Small-molecule agents with bioavailability constraints requiring hepatic metabolism monitoring.
- Intrathecal:CNS prophylaxis delivery for high-risk DLBCL with leptomeningeal involvement.
Revenue concentration remains in Intravenous formats; Subcutaneous modalities are gaining share fastest in maintenance and relapsed-refractory settings.
End User:
Customer type fragmentation reflects how therapy complexity dictates site credentialing requirements and reimbursement tiering.
- Hospitals:Comprehensive centers with apheresis capability, stem cell processing labs, and ICU backup for cytokine release syndrome management. United States-based health systems in Texas and Florida are unbundling CAR T-cell services from flagship academic campuses into community hospital satellites where certificate-of-need restrictions are weakest.
- Specialty Clinics:Hematology-oncology focused ambulatory sites handling bispecific antibody and maintenance monoclonal antibody administration. Germany's office-based oncologist practices (niedergelassene Ärzte) are capturing maintenance rituximab volume through subcutaneous formulation adoption.
- Research Laboratories:Academic centers conducting Phase I/II trials with embedded GMP manufacturing.
- Homecare:Limited to oral agent monitoring and post-infusion nursing visits in select European markets.
Patient volumes aggregate in Hospitals; Specialty Clinics are expanding their serviceable share most rapidly through subcutaneous administration adoption.
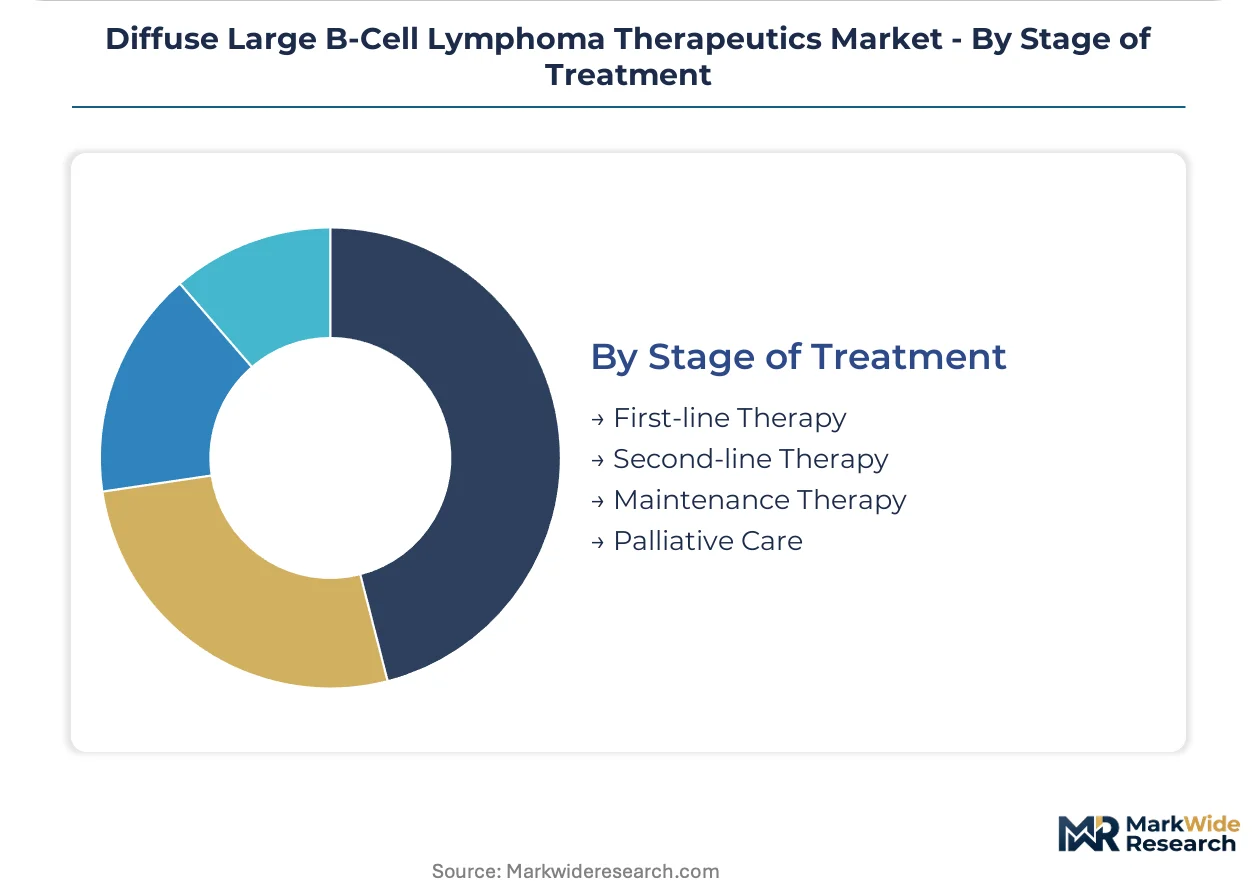
Stage of Treatment:
Maturity gradients separate commoditized first-line protocols from high-margin relapsed-refractory interventions where clinical unmet need justifies premium pricing.
- First-line Therapy:Curative-intent R-CHOP or R-EPOCH regimens with rituximab biosimilar erosion compressing branded revenue. France's ANSM and Germany's BfArM impose divergent post-authorization study requirements that complicate pan-European labeling for novel first-line combinations.
- Second-line Therapy:Salvage chemotherapy bridging to transplant or CAR T-cell eligibility. United States referral networks concentrate second-line CAR T-cell evaluation at NCI-designated cancer centers with established manufacturing partnerships.
- Maintenance Therapy:Extended rituximab or lenalidomide for high-risk complete responders.
- Palliative Care:Symptom-directed therapy in multiply relapsed disease.
Treatment initiations concentrate in First-line Therapy; the steepest expansion trajectory belongs to Second-line Therapy as CAR T-cell manufacturing capacity scales and outpatient administration models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for DLBCL therapeutics concentrates in the United States, where CAR T-cell referral networks and apheresis infrastructure exceed all other markets combined. Europe and Japan follow with distinct reimbursement and regulatory pathways shaping commercial sequencing. Manufacturing partnerships and site credentialing requirements determine geographic penetration for cell-based modalities.
United States
Academic medical centers in Texas, Florida, and California maintain the densest leukapheresis networks, enabling CAR T-cell patient access beyond flagship campuses. FDA breakthrough therapy designation compresses clinical-to-commercial timelines for novel agents. Hospital systems in Houston and Miami are unbundling cell therapy services into community satellites where certificate-of-need restrictions are weakest.
Germany
Office-based oncologist practices capture maintenance monoclonal antibody volume through subcutaneous rituximab adoption, shifting site-of-care economics. BfArM imposes post-authorization study requirements that diverge from French ANSM standards, complicating pan-European labeling. The Rhine-Ruhr corridor concentrates infusion capacity across university hospitals in Cologne and Düsseldorf.
France
ANSM early access programs channel relapsed-refractory patients toward academic centers in Paris and Lyon prior to formal reimbursement listing. Health technology assessment engagement under HAS guidelines conditions launch sequencing and pricing negotiations. The Île-de-France region anchors clinical trial recruitment for Phase I/II pipeline assets.
Japan
PMDA Sakigake designation attracts early-phase trials, creating geographic diversification for bispecific antibody and allogeneic CAR T-cell developers. METI incentives support domestic manufacturing scale-up for viral vector production. Tokyo and Osaka medical districts concentrate hematology-oncology specialists with cell therapy administration credentials.
United Kingdom
NHS England reimbursement separates administration fees from drug acquisition costs, accelerating bispecific antibody uptake in day-case oncology units. MHRA alignment with FDA post-market safety monitoring for cytokine release syndrome constrains label expansion timelines. The Greater Manchester and London cancer alliances consolidate immuno-oncology infusion services.
Diffuse Large B-Cell Lymphoma Therapeutics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates dominating monoclonal antibodies and CAR T-cell products while biotechnology specialists concentrate in bispecific platforms and antibody-drug conjugates. The structure tiers across three archetypes: diagnostic-therapeutic pairing strategists, manufacturing-scale cell therapy anchors, and bispecific antibody platform builders. Competitive moves center on manufacturing capacity expansion for lentiviral vector production and strategic partnerships to secure cryopreservation logistics networks.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify archetypes pairing diagnostic assets with therapeutic portfolios across the DLBCL care pathway. Bristol Myers Squibb Company occupies a position anchoring CAR T-cell segment representation through manufacturing scale and approved indication breadth. Among biotechnology specialists, ADC Therapeutics SA sits within the antibody-drug conjugate platform tier, competing in relapsed-refractory settings without autologous cell collection requirements.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Gilead Sciences, Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Bristol Myers Squibb Company |
| AbbVie Inc. |
| ADC Therapeutics SA |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
Academic medical centers and hospital outpatient departments concentrate procurement decisions for DLBCL therapeutics, anchoring a value-based pricing model where clinical outcomes determine reimbursement tiers and site-of-care economics dictate net realized prices.
Pricing Analysis
Volume placements concentrate in commoditized rituximab biosimilars where price erosion compresses margins, while CAR T-cell and bispecific antibody segments command premium positioning through outcome-based contracts. Price differentiation hinges on manufacturing complexity and FDA breakthrough therapy status versus standard-of-care equivalence. Pricing pressure intensifies in first-line settings as biosimilar substitution accelerates, with Germany's office-based oncologists and United States hospital systems exhibiting divergent sensitivity—community clinics prioritize acquisition cost minimization while academic centers prioritize clinical protocol adherence.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EMA for lentiviral vectors compel CAR T-cell developers to qualify multiple contract manufacturers, fragmenting production across United States, Germany, and Switzerland. Viral vector production draws from suspension bioreactor platforms and plasmid DNA feedstocks, with single-source vulnerabilities in cryopreservation logistics creating temperature excursion risks during cross-border transport. Tariff exposure on Chinese-sourced raw materials and regulatory divergence between ANSM and BfArM compound supply complexity. Distribution runs through specialized hospital pharmacy channels and academic center stem cell processing labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing scale requirements and regulatory compliance burdens are forcing consolidation among subscale CAR T-cell developers, leaving only integrated platforms with vector production capabilities and established apheresis networks.
For Market Incumbents: Acquire lentiviral vector manufacturing assets to secure supply chain control against contract manufacturer concentration risks. Expand apheresis network density in Texas and Florida where certificate-of-need restrictions weakest. Invest in subcutaneous formulation capabilities to capture site-of-care shift toward community oncology clinics.
For New Entrants and Emerging Players: Enter via allogeneic off-the-shelf platforms that eliminate leukapheresis logistics and open community clinic channels. Target Japan's Sakigake-designated early access pathway for bispecific antibody assets. Pursue strategic partnerships with established CDMOs to bypass 18-24 month GMP validation timelines.
For Investors and Strategic Acquirers: The window for entry favors platform-stage biotechnology assets with modular CAR constructs and embedded health technology assessment capabilities. Long-term viability rests on pipeline diversification across treatment lines and administration formats. Watch FDA confirmatory trial enrollment rates as inflection indicator for accelerated approval conversion risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | Eliminates patient-specific leukapheresis, enabling community clinic administration and geographic expansion. |
| Subcutaneous Formulation Investment | Reduces infusion chair time and shifts site-of-care economics toward ambulatory settings in NHS England. |
| Vector Manufacturing Scale-Up | Suspension bioreactor technology transfer addresses supply constraints for CAR T-cell expansion. |
| Health Technology Assessment Integration | Early HAS engagement in France conditions reimbursement negotiations and launch sequencing. |
| Real-World Evidence Infrastructure | Post-market confirmatory trial capabilities satisfy FDA mandates and support label expansion. |
Methodological Framework
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down revenue reconciliation triangulate market sizing across treatment lines and administration routes.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon, with segmentation modeling covering drug type, stage of treatment, administration route, and regional regulatory cluster. CAGRs derive from patient incidence projections, therapy penetration assumptions, and pricing elasticity parameters, incorporating manufacturing capacity buildout timelines and site credentialing expansion rates as industry-specific inputs.
Revisions become necessary when FDA confirmatory trial failures, viral vector supply disruptions, or reimbursement policy shifts materialize. Deviation in accelerated approval conversion rates or allogeneic platform clinical outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Leukocytoclastic Vasculitis Market